
 Circulating Fluidized Bed Boilers Market | 2026-2036
Circulating Fluidized Bed Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Circulating Fluidized Bed Boilers Market Analysis
Chinese boiler fabricators is pivoting toward higher-capacity supercritical CFB designs for export markets. Babcock & Wilcox Enterprises leverages its North American installed base to sustain aftermarket service contracts across aging coal fleets. Bharat Heavy Electricals Limited anchors domestic supply chains for Indian power sector tenders, while Doosan Heavy Industries & Construction competes on seaworthy modular designs for island nations.
Circulating fluidized bed boilers suspend fuel particles in upward-flowing combustion air at velocities of 3-8 m/s, achieving uniform temperature distribution across the reaction chamber while enabling in-situ sulfur capture through limestone injection. Power Generation applications dominate current order books due to baseload reliability requirements, though Waste Incineration segments are attracting capital as municipalities tighten landfill diversion mandates. Biomass fuel configurations command margin premiums where carbon accounting rules reward renewable thermal output, while Coal-based units retain volume leadership in markets with abundant low-rank reserves.
EPA Clean Air Act enforcement shapes US retrofit demand, while India's CEA mandates minimum efficiency thresholds that favor CFB adoption over conventional pulverized coal. The EU Industrial Emissions Directive and associated BAT conclusions constrain new combustion plant permits, filtering market access toward vendors with proven emission control integration. Stakeholders must weigh fuel switching flexibility against carbon border adjustment exposure when committing to long-delivery boiler contracts.
Market Dynamics
Coal-to-biomass fuel flexibility is compressing equipment replacement cycles across baseload power fleets. CFB operators now prioritize combustion systems capable of handling 40-60% biomass blends without derating, driven by carbon accounting penalties and fuel price arbitrage opportunities.
Growth Catalysts
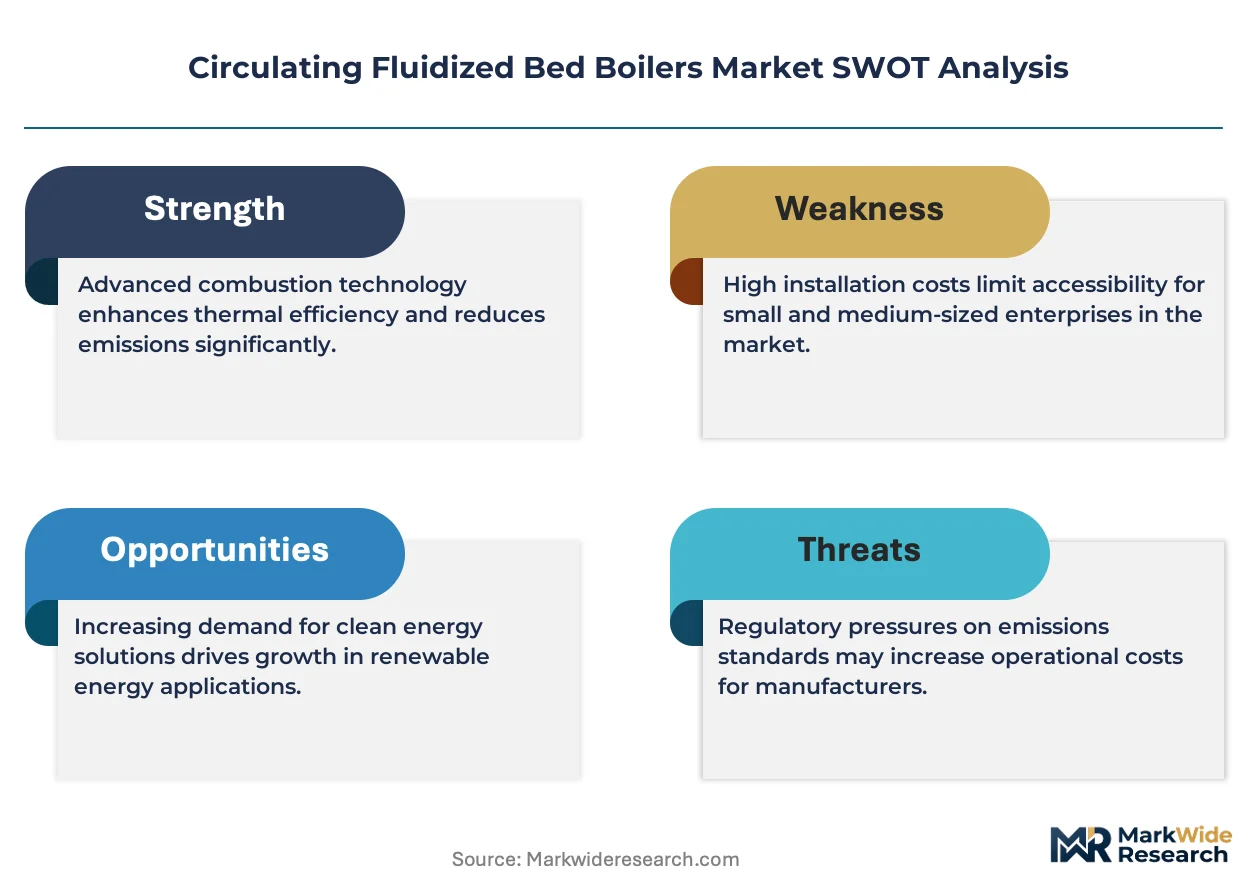
- India's CEA Efficiency Mandates:Minimum thermal efficiency thresholds for new thermal units favor CFB designs over subcritical pulverized coal, accelerating fleet replacement tenders by state-run generators.
- Biomass Co-firing Incentives:Renewable thermal certificates and carbon border adjustment mechanisms reward plants demonstrating fuel-switching flexibility, with biomass configurations commanding procurement preference.
- Southeast Asian Coal Quality Decline:Indonesian and Vietnamese mines are extracting lower-rank reserves with higher moisture and ash content, necessitating CFB's superior fuel tolerance versus conventional boilers.
Market Restraints
- Refractory Material Cost Volatility:Chrome-magnesite and alumina-silicate lining prices fluctuate with South African and Chinese export restrictions, compressing fabrication margins on fixed-price contracts.
- Specialized Welding Labor Scarcity:ASME Section IX-certified pressure vessel welders concentrate in Poland, South Korea, and India, creating 14-18 month backlog risks for supercritical CFB projects.
- Long-delivery Equipment Cycles:36-48 month lead times from order to commissioning expose vendors to currency and commodity price swings that fixed contracts cannot absorb.
Strategic Opportunities
- Waste-to-Energy Municipal Mandates:EU landfill diversion targets and similar policies in Japan are opening CFB incineration segments for refuse-derived fuel and sewage sludge applications.
- Supercritical CFB Technology Export:Chinese fabricators with domestic 600 MW+ operational experience are bidding into Turkey, Pakistan, and Botswana markets seeking higher-efficiency baseload options.
- Carbon Capture Retrofit Compatibility:CFB's lower flame temperatures and in-situ sulfur capture simplify post-combustion amine scrubber integration, positioning installed units for 45Q credit eligibility.
Industry Challenges
- Control System Integration Complexity:Distributed control system upgrades for legacy CFB units require reconciling 1990s-era DCS architectures with modern digital twin and predictive maintenance platforms.
- Fuel Handling Infrastructure Reconfiguration:Biomass pellet and agricultural residue supply chains demand new receiving, storage, and preprocessing equipment that existing coal yards cannot accommodate without substantial civil works.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circulating Fluidized Bed Boilers Market |
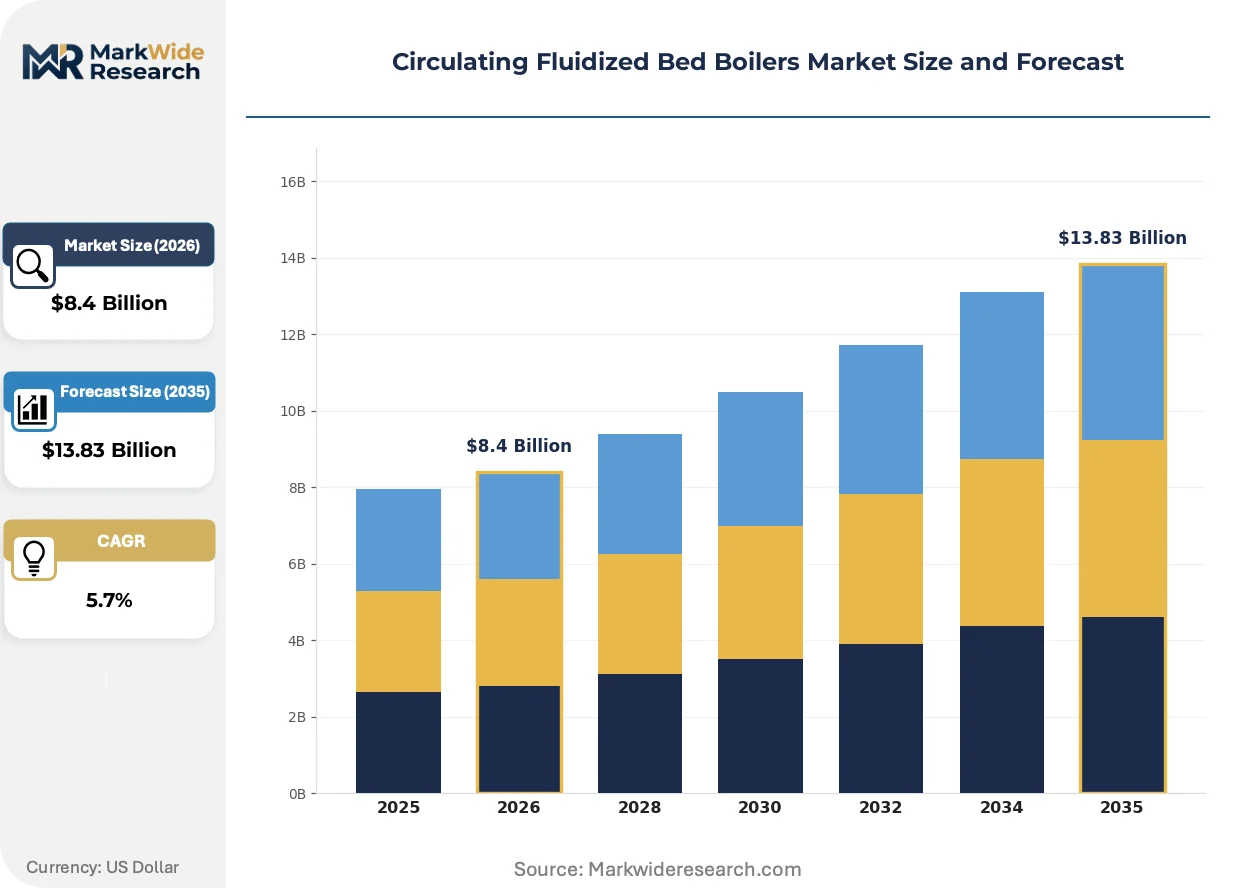
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Combustion, Gasification, Co-Firing, Dual-Fluid Application: Power Generation, Industrial Heating, Waste Incineration, Chemical Processing End User: Utilities, Manufacturing, Oil & Gas, Pulp & Paper Fuel Type: Biomass, Coal, Natural Gas, Petcoke |
| Companies Covered | Babcock & Wilcox Enterprises, Bharat Heavy Electricals Limited, Thermax Limited, Doosan Heavy Industries & Construction, Mitsubishi Power, ANDRITZ, Valmet, IHI Corporation, Sumitomo SHI Foster Wheeler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circulating Fluidized Bed Boilers Market Emerging Trajectories
Digital combustion optimization and modular fabrication methods are compressing project timelines while expanding fuel tolerance envelopes. Equipment vendors are repositioning around lifecycle service contracts rather than standalone hardware sales.
Advanced neural network-based burner management systems are decentralizing combustion control from centralized DCS architectures to edge-computing nodes at individual wind boxes. Independent power producers in Thailand and the Philippines are piloting these systems to manage 30+ fuel blend variations. This architecture is decentralizing operational decision-making from plant control rooms to automated real-time adjustment loops.
The EPA's revised Mercury and Air Toxics Standards enforcement timeline is tightening particulate and acid gas limits for existing coal-fired capacity. Operators face retrofit investment decisions between post-combustion scrubbers and CFB repowering with integrated limestone injection. US merchant generators in Texas and PJM interconnection zones are favoring CFB conversions for units below 300 MW given site footprint constraints.
Power purchase agreement structures are migrating from capacity-based to availability-based remuneration, altering buyer evaluation criteria. Industrial offtakers in cement and chemicals sectors are now prioritizing boiler reliability guarantees over capital cost minimization. This preference shift is most pronounced in India's captive power sector, where grid instability makes continuous steam supply critical to process economics.
Circulating Fluidized Bed Boilers Market Segmentation
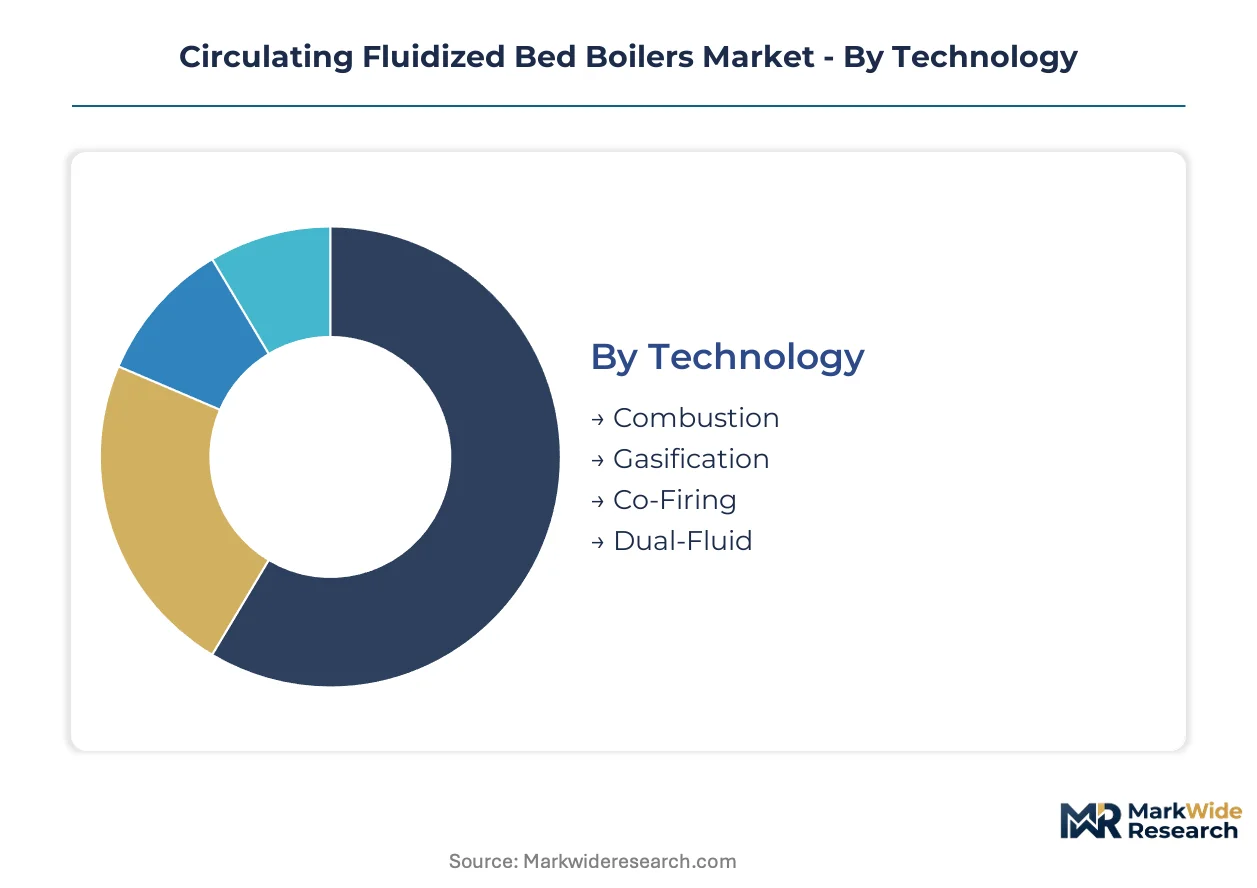
Circulating fluidized bed boilers serve heterogeneous operational requirements across fuel chemistries and thermal duty cycles. Segmentation reveals where engineering trade-offs between combustion efficiency and fuel flexibility concentrate procurement decisions.
Technology:
Upgrade cycles favor combustion architectures that accommodate fuel switching without hardware replacement, while greenfield installations prioritize efficiency-maximizing configurations.
- Combustion:Suspends fuel particles in high-velocity air streams at 800-950°C, achieving uniform temperature distribution through turbulent mixing. Demand concentrates in Indian state-run generation tenders where CEA efficiency mandates favor CFB repowering of aging subcritical units.
- Gasification:Partial oxidation produces syngas for integrated gasification combined cycle plants or chemical synthesis feedstock. Southeast Asian coal quality decline—higher moisture Indonesian and Vietnamese reserves—drives adoption where fuel flexibility outweighs pure thermal efficiency.
- Co-Firing:Enables simultaneous combustion of coal with 40-60% biomass blends.
- Dual-Fluid:Separates combustion and heat transfer loops for enhanced temperature control.
Volume placements concentrate in Combustion; the faster expansion belongs to Gasification.
Application:
Cost tier differentiation separates baseload reliability premiums from waste-handling operational complexity.
- Power Generation:Dominates current order books through baseload reliability requirements and grid stability mandates. Indian utilities and Southeast Asian IPPs prioritize supercritical CFB designs for 300-600 MW units where coal quality variability would derate conventional pulverized coal boilers.
- Waste Incineration:Municipal landfill diversion mandates in EU member states and Japan create dedicated revenue streams for refuse-derived fuel and sewage sludge processing. CFB's lower combustion temperatures reduce slagging risks from heterogeneous waste streams compared to grate-fired alternatives.
- Industrial Heating:Process steam for cement, chemicals, and textiles.
- Chemical Processing:Petrochemical crackers and syngas production.
Power Generation commands procurement volume; Waste Incineration climbs fastest on regulatory tailwinds.
End User:
Customer type segmentation tracks divergent procurement authority structures—centralized utility tenders versus decentralized industrial captive power decisions.
- Utilities:State-run generators in India and merchant operators in Texas PJM zones drive fleet replacement cycles. EPA MATS enforcement and availability-based PPA structures prioritize reliability guarantees over capital cost minimization for sub-300 MW unit conversions.
- Manufacturing:Cement and chemicals sector offtakers in India's captive power sector prioritize continuous steam supply where grid instability threatens process economics. Procurement evaluates lifecycle service contracts over standalone hardware acquisition.
- Oil & Gas:Refinery steam and power integration.
- Pulp & Paper:Black liquor and bark combustion in integrated mills.
Utilities anchor installed base; Manufacturing gains share fastest on process reliability premiums.
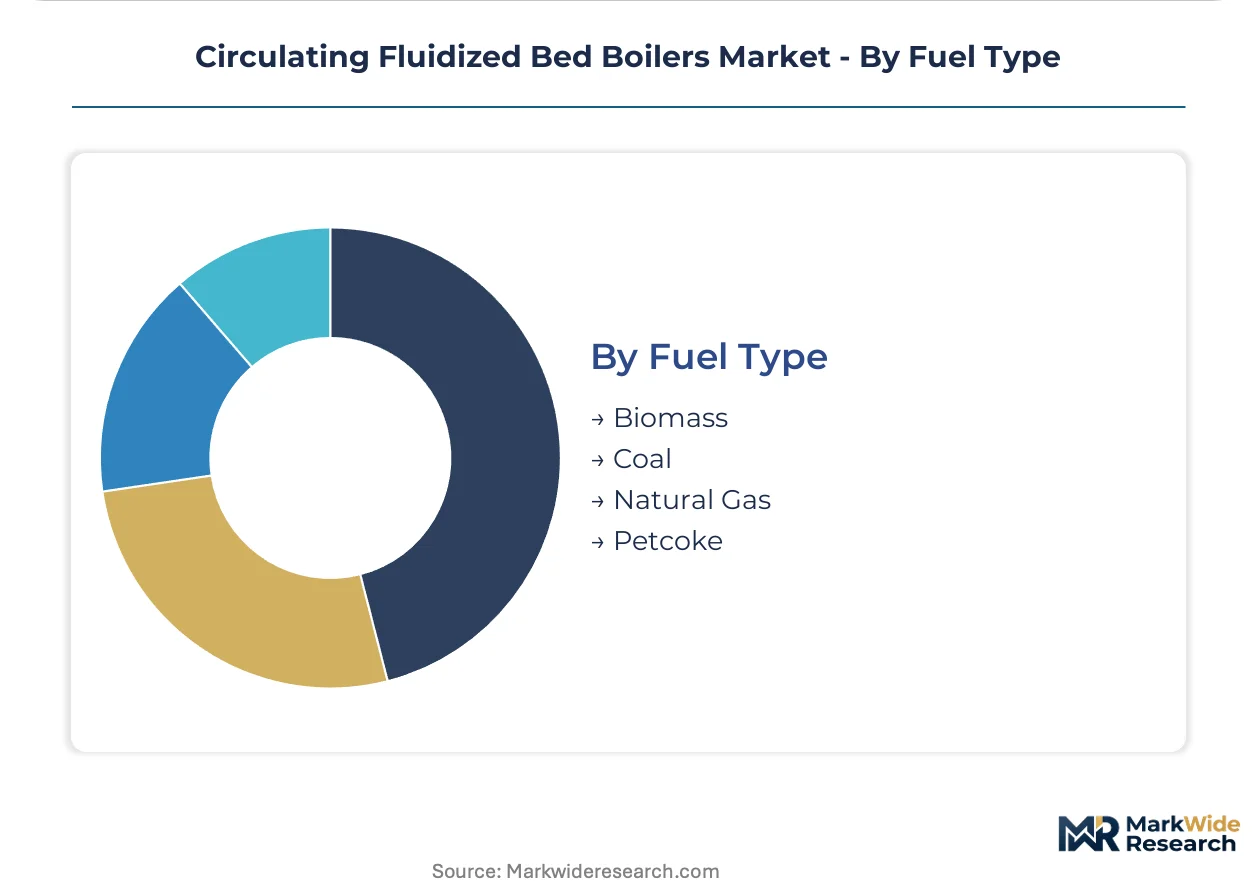
Fuel Type:
Margin structure stratifies around carbon accounting treatment and feedstock security.
- Biomass:Agricultural residues and energy crops command procurement premiums where renewable thermal certificates and carbon border adjustment mechanisms reward demonstrated fuel-switching flexibility. EU and Japanese installations lead adoption.
- Coal:Retains volume leadership in markets with abundant low-rank reserves—India, Indonesia, Botswana—where CFB's tolerance for high-ash, high-moisture feedstock offsets efficiency penalties against imported fuel dependency.
- Natural Gas:Bridge fuel configurations in dual-fuel capable units.
- Petcoke:Refinery byproduct utilization in integrated petrochemical complexes.
Coal dominates unit placements; Biomass expands most quickly on incentive structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian coal basins with deteriorating calorific values anchor Southeast Asian procurement patterns. Indian thermal coal fields with high-ash content drive domestic CFB specifications. Chinese manufacturing clusters export supercritical designs to emerging markets.
India
State-run NTPC and state electricity boards tender 300-600 MW supercritical CFB replacements for aging subcritical units. The Central Electricity Authority mandates minimum thermal efficiency thresholds that favor CFB over pulverized coal. Gujarat and Maharashtra host fabrication clusters where Bharat Heavy Electricals Limited anchors domestic supply chains.
United States
Merchant generators in Texas and PJM interconnection zones retrofit sub-300 MW units for MATS compliance. EPA enforcement of Mercury and Air Toxics Standards tightens particulate and acid gas limits for existing coal capacity. Ohio and Pennsylvania host engineering service hubs where operators evaluate CFB repowering against post-combustion scrubber retrofits.
China
Domestic utilities commission 600 MW+ supercritical CFB units for high-ash domestic coal. The Ministry of Ecology and Environment enforces emission intensity targets that accelerate fleet technology upgrades. Shandong and Shanxi provinces concentrate operational experience that fabricators leverage for export bids into Turkey and Pakistan.
Indonesia
Independent power producers specify CFB designs to handle lower-rank reserves with 35-45% moisture content. The national energy ministry prioritizes domestic coal utilization over imported fuel dependency. Java and Sumatra host project development clusters where Chinese and Korean fabricators compete on fuel-flexibility guarantees.
Germany
Municipal utilities commission CFB waste-to-energy plants under EU landfill diversion mandates. The Industrial Emissions Directive and associated BAT conclusions constrain new combustion permits to vendors with integrated emission control. Bavaria and North Rhine-Westphalia concentrate operational expertise in refuse-derived fuel processing.
Circulating Fluidized Bed Boilers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular fabrication and digital service contracts. The vendor base stratifies around three archetypes: full-system integrators with lifecycle service capabilities, regional fabricators competing on delivery timelines, and technology licensors monetizing combustion know-how. Competitive positioning hinges on ASME certification maintenance and supercritical welding capacity rather than pure manufacturing scale. Consolidation pressure concentrates in aftermarket services, where installed base density determines contract renewal rates.
Among Asia-Pacific fabricators, Bharat Heavy Electricals Limited and Doosan Heavy Industries & Construction exemplify divergent geographic strategies. Babcock & Wilcox Enterprises occupies a position in the North American service-contract tier, leveraging legacy installed base density. Mitsubishi Power and IHI Corporation represent Japanese entrants with advanced supercritical experience. These anchors illustrate how competitive positioning fragments across regional procurement authority structures rather than converging on global scale.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises |
| Bharat Heavy Electricals Limited |
| Thermax Limited |
| Doosan Heavy Industries & Construction |
| Mitsubishi Power |
| ANDRITZ |
| Valmet |
| IHI Corporation |
| Sumitomo SHI Foster Wheeler |
| Others |
Supply Flow & Price Mechanics
EPA Clean Air Act enforcement gates qualified supply for premium-tier CFB systems, restricting vendor access to operators demonstrating integrated sulfur capture and mercury control capabilities. This environmental mandate compresses fabrication margins for uncertified competitors while elevating lifecycle service contracts as the primary pricing differentiator for approved suppliers.
Pricing Analysis
Warranty and aftermarket service bundling separates premium CFB vendors from unbundled equipment-only competitors, with supercritical welding certification and ASME Section IX compliance commanding substantial premiums. Price differentiation hinges on fabrication grade and geographic delivery logistics, with modular designs for island nations carrying freight premiums against land-based installations. Pricing pressure stems from fixed-price contract exposure to refractory material cost swings, with chrome-magnesite and alumina-silicate volatility compressing margins on long-delivery projects. State-run utilities in India exhibit highest price sensitivity through competitive tender structures, while merchant generators in Texas prioritize reliability guarantees over capital cost minimization.
Supply Chain Analysis
Regional distribution centers in Poland, South Korea, and India anchor hub-and-spoke patterns for pressure vessel components and specialized welding services. Manufacturing concentration centers on China, India, and South Korea for boiler fabrication, with critical inputs drawing from South African chrome ore, Chinese refractory exports, and Indian structural steel. Single-source vulnerability in ASME-certified welding labor creates 14-18 month backlog risks for supercritical projects. Distribution runs through EPC contractor networks and direct utility procurement channels, with lifecycle service contracts increasingly displacing standalone hardware transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with supercritical fabrication credentials and dense installed bases for aftermarket capture. Refractory cost volatility and welding labor scarcity are forcing weaker regional fabricators toward exit or acquisition.
For Market Incumbents: Deploy lifecycle service contract expansion to lock in utility renewal revenue and counter Chinese supercritical export competition. Secure backward integration into refractory material supply chains to hedge South African and Chinese export restriction exposure. Deepen ASME certification maintenance investments to sustain competitive moats against emerging modular fabricators. For New Entrants and Emerging Players: Begin with waste-to-energy municipal mandates in EU member states and Japan where landfill diversion targets create dedicated procurement streams for refuse-derived fuel CFB configurations. Target smaller industrial captive power segments in India's cement and chemicals sectors where grid instability prioritizes continuous steam supply over lowest capital cost. Pursue digital combustion optimization partnerships with independent power producers in Thailand and the Philippines as a differentiated entry vector. For Investors and Strategic Acquirers: Indian CEA efficiency mandate acceleration is the leading indicator that state-run tender volume will concentrate among vendors with proven 300-600 MW supercritical delivery records. Acquisition candidates with dense regional installed bases and ASME-certified welding capacity offer strongest long-term viability through service contract renewal economics. Watch for carbon border adjustment mechanism implementation signals in EU trading partners as the inflection point for biomass co-firing premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CFB Technology Licensing | Chinese fabricators leverage domestic 600 MW+ operational experience for export bids into Turkey and Pakistan. |
| Backward Integration into Refractory Supply | Vendors with captive chrome-magnesite sourcing hedge South African export restriction exposure on fixed-price contracts. |
| Digital Twin Platform Deployment | Neural network-based burner management decentralizes control from centralized DCS architectures to edge-computing nodes. |
| Waste-to-Energy Capacity Buildout | EU landfill diversion targets and Japanese municipal mandates open dedicated revenue streams for refuse-derived fuel processing. |
| Carbon Capture Retrofit Compatibility | CFB's lower flame temperatures simplify post-combustion amine scrubber integration for 45Q credit eligibility. |
Methodological Framework
Trade publications, customs databases, and regulatory filing repositories formed the secondary backbone for this analysis, cross-referenced with primary interviews involving utility planning officers, EPC contractor project managers, boiler fabrication procurement leads, and aftermarket service directors. Bottom-up segmentation modeling across fuel type, capacity tier, and application vertical was triangulated against top-down macroeconomic indicators and energy policy trajectories.
Historical trendline analysis tracked technology adoption patterns and fleet replacement cycles across the projection horizon, with CAGR derivation anchored in regulatory mandate enforcement timelines and fuel quality deterioration trajectories. Segmentation dimensions modeled include combustion architecture, fuel chemistry configuration, end-user procurement authority structure, and regional grid stability requirements. Forecast inputs incorporated CEA efficiency threshold compliance schedules, EPA MATS enforcement intensity, and Southeast Asian coal basin calorific value decline rates.
Underlying measurement precision varies by segment; supercritical CFB installations and waste-to-energy deployments carry tighter precision than emerging gasification configurations. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, commodity price stability, and welding labor availability. Periodic stress-testing of base assumptions is recommended given exposure to South African mineral export policies and Chinese refractory market interventions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Fuel Operated Heaters Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Advanced Utility Boilers Market
Boilers
Oil-Fired Boiler Market
Boilers
Boiler System Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Industrial Biomass Boiler Market
Boilers
Boiler Control Market
Boilers
Europe Combined Heat and Power Market
Boilers
Reformer Unit Market
Boilers
Boiler Combustion Chamber Market
Boilers
Commercial Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Utility Boiler Market
Boilers
Field Erected Boiler Market
Boilers
Watertube Boilers Market