

Wheat Straw Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Straw Packaging Market Insights
Foodservice distribution channels are rewriting procurement standards for disposable packaging across Europe and North America. Huhtamaki leverages its molded pulp manufacturing scale to supply wheat straw composite trays to quick-service chains. Eco-Products anchors the North American institutional channel through direct contracts with university and corporate cafeteria operators. Vegware differentiates by controlling composting infrastructure partnerships that close the loop for foodservice clients.
Wheat straw packaging utilizes agricultural residue fibers combined with kraft paper or biodegradable binders to form rigid containers, typically achieving oil resistance up to 100°C through PLA film lamination or chitosan coatings. The primary commercial purpose centers on replacing petroleum-based foodservice disposables in closed-loop catering and retail environments. Trays and boxes lead product type demand due to their structural suitability for hot meals and takeaway formats. Molded pulp and wheat straw composite materials capture margin pools where manufacturers integrate fiber processing with thermoforming operations. Food packaging applications dominate volume, though cosmetics containers show faster growth as personal care brands seek agricultural-waste narratives for premium positioning.
REACH and the EU Packaging and Packaging Waste Regulation establish chemical safety and recyclability mandates that wheat straw formulations must satisfy for European market access. The FDA maintains food contact substance notification requirements for agricultural fiber packaging entering US interstate commerce. Stakeholders must monitor compostability certification harmonization between BPI standards and emerging national frameworks to avoid market fragmentation that complicates multi-territory product launches.
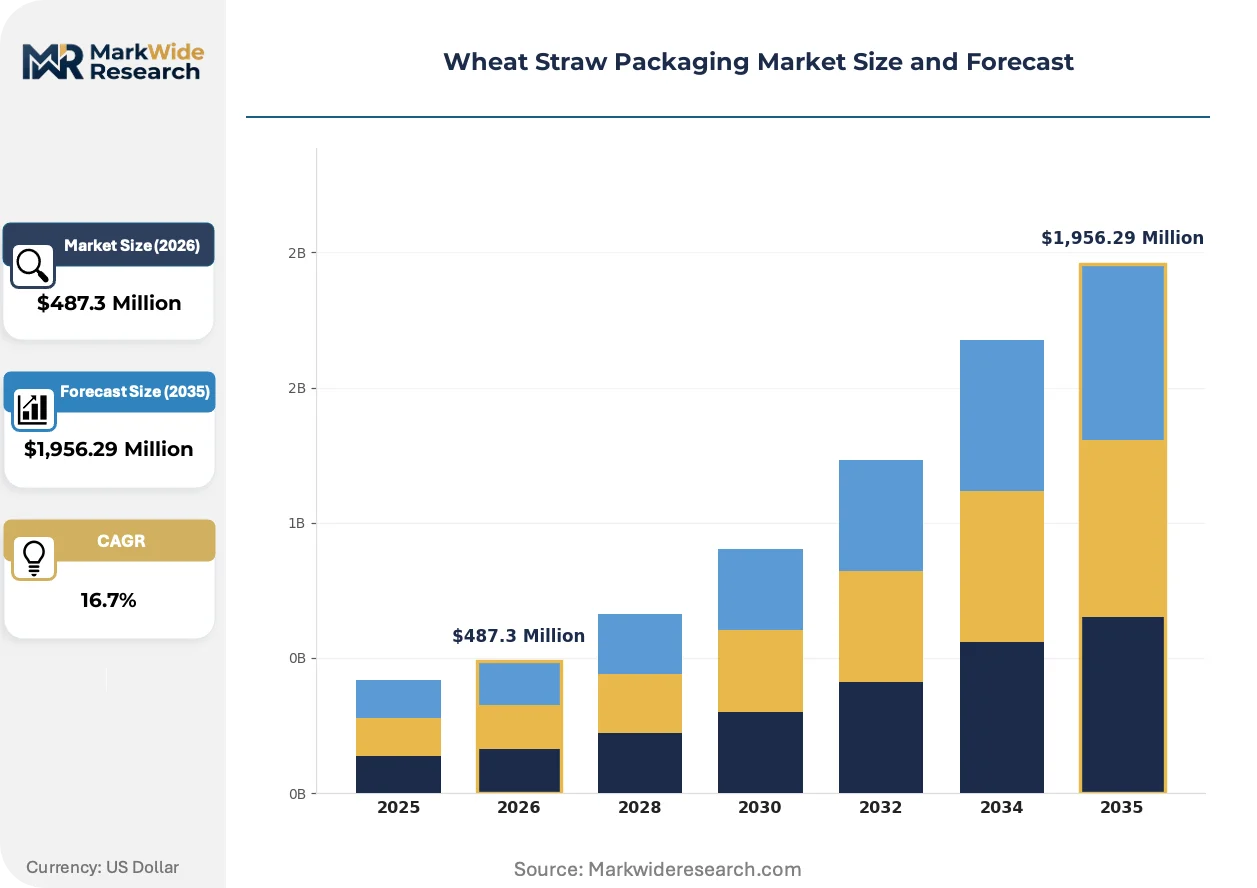
Market Dynamics
Foodservice procurement mandates are compressing the transition timeline from petroleum-based disposables to agricultural fiber alternatives. Quick-service chains now require compostable packaging specifications in supplier contracts, forcing material substitution decisions upstream in the supply chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds and extended producer responsibility schemes push food manufacturers toward certified compostable materials. German retail chains enforce private-label compliance ahead of statutory deadlines.
- Quick-service restaurant procurement:Chain-level sustainability commitments require molded pulp trays and boxes for hot-meal formats. Centralized purchasing concentrates volume behind agricultural fiber specifications.
- Chitosan coating technology:Oil resistance up to 100°C without petroleum-derived films enables direct replacement of plastic-lined containers. Coating suppliers integrate with thermoforming operations to guarantee performance.
Market Restraints
- PLA film price volatility:Polylactic acid lamination costs fluctuate with corn starch feedstock markets. Wheat straw composite margins compress when biopolymer prices spike.
- Composting infrastructure gaps:Industrial composting facility concentration in Western Europe leaves Eastern European and North American markets with disposal route uncertainty. Certification without disposal access undermines value proposition.
- REACH chemical compliance:Agricultural fiber processing aids and coatings face substance authorization requirements. Registration costs and testing timelines delay product launches for small manufacturers.
Strategic Opportunities
- Cosmetics premium positioning:Personal care brands adopt agricultural-waste narratives for skincare and haircare containers. Wheat straw rigid packaging commands price premiums in clean beauty segments.
- Closed-loop catering contracts:Corporate cafeteria operators seek single-source compostable packaging with guaranteed disposal. Direct service agreements bypass distributor markups and secure volume commitments.
- BPI certification harmonization:Emerging national compostability frameworks create first-mover advantage for brands with established biodegradation testing. Multi-territory product registrations consolidate behind unified standards.
Industry Challenges
- Thermoforming equipment retrofitting:Legacy pulp molding machinery requires modification for wheat straw fiber processing. Capital expenditure demands strain mid-scale manufacturers.
- Compostability certification timelines:BPI and TÜV Austria testing protocols extend six to twelve months. Product launches stall awaiting biodegradation validation in target soil conditions.
- Fiber supply seasonality:Wheat straw harvest concentration creates raw material procurement windows. Storage and preprocessing capacity must buffer annual supply pulses.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Straw Packaging Market Trends and Innovations
Material science advances and regulatory pressure are converging to accelerate substitution of petroleum-based foodservice disposables. Processing innovations and certification harmonization reshape competitive positioning across packaging tiers.
Chitosan bio-coating formulations are collapsing the performance gap between agricultural fiber containers and plastic-lined alternatives. Quick-service chains in Germany and France specify chitosan-coated trays for hot-oil applications. The technology compresses material substitution timelines by eliminating compostability trade-offs previously accepted by buyers.
REACH substance authorization requirements are tightening chemical safety verification for agricultural fiber processing aids. ECHA scrutiny of binders and coatings forces reformulation investments across European suppliers. Molded pulp manufacturers with in-house polymer chemistry capabilities capture margin from compliance-driven supplier switching.
University and corporate cafeteria operators now bundle packaging procurement with composting service contracts. Direct vendor relationships replace distributor intermediaries in the North American institutional channel. Campus sustainability offices in California and New York mandate closed-loop verification, consolidating purchasing behind integrated packaging-disposal providers.
Wheat Straw Packaging Market Segmentation
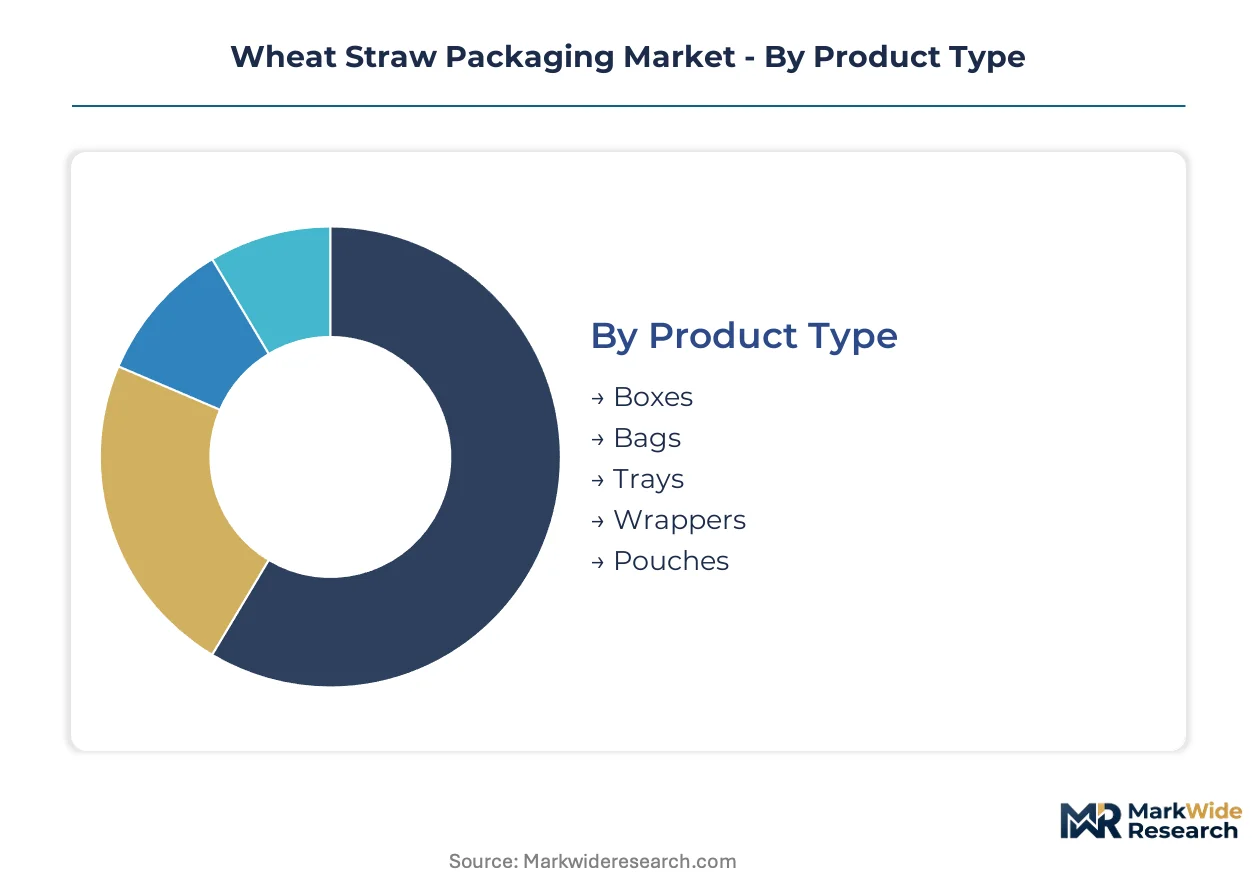
Wheat straw packaging serves divergent performance requirements across temperature-resistant foodservice formats and premium cosmetic presentations. Segmentation reveals how fiber processing capabilities and coating technologies align with specific end-use durability demands and regulatory compliance thresholds.
Product Type:
Use-case spectrum spans hot-meal containment, dry goods protection, and flexible wrapping for grab-and-go retail formats.
- Trays:Molded pulp structures with chitosan or PLA lamination withstand temperatures to 100°C for quick-service hot meal service. German and French chain procurement mandates concentrate volume behind oil-resistant specifications.
- Boxes:Rigid containers formed from wheat straw-kraft paper composites provide structural integrity for retail food and gift applications. E-commerce fulfillment requirements in California and New York drive demand for crush-resistant geometries.
- Bags:Flexible pouches with wheat straw fiber content serve dry goods and bakery segments where barrier properties are less critical.
- Wrappers:Thin-format sheets for sandwich and confectionery wrapping prioritize printability and grease resistance over thermal performance.
- Pouches:Stand-up and flat formats for snacks and small-format cosmetics leverage fiber-based sustainability narratives in clean beauty marketing.
The dominant share belongs to Trays, while Boxes are closing the gap fastest.
Packaging Material:
Material cost tiers separate commodity fiber blends from performance-engineered composites with certified compostability.
- Wheat Straw Composite:Agricultural residue fibers combined with kraft paper and biodegradable binders form the base specification for rigid containers. REACH substance authorization requirements for processing aids force reformulation investments among European suppliers.
- Molded Pulp:Thermoformed fiber matrices achieve structural rigidity without petroleum-derived components. Huhtamaki's manufacturing scale supplies quick-service chains with integrated fiber processing and forming operations.
- Kraft Paper:Unbleached wood pulp layers provide moisture management and print substrates for outer packaging surfaces.
- Biodegradable Plastics:Starch-based and other compostable polymers serve as window films and structural reinforcements where fiber alone underperforms.
- PLA Films:Polylactic acid lamination delivers oil and moisture barriers, though corn starch feedstock price volatility compresses composite margins during commodity spikes.
Molded Pulp commands the largest production volume, with Wheat Straw Composite expanding most quickly as fiber preprocessing capacity scales.
Application:
Application maturity separates established foodservice demand from emerging premium positioning in personal care.
- Food Packaging:Hot-meal containers, produce trays, and takeaway boxes dominate commercial volume through quick-service restaurant and institutional cafeteria procurement. FDA food contact substance notifications govern agricultural fiber packaging entering US interstate commerce.
- Cosmetics Containers:Rigid jars and compact cases for skincare and haircare products command price premiums through agricultural-waste sustainability narratives. Personal care brands in Germany and France adopt these formats for clean beauty line extensions.
- Pharmaceuticals Packaging:Secondary cartons and blister pack backing cards utilize fiber composites where moisture sensitivity permits.
- Gift Packaging:Decorative boxes and rigid set packaging for seasonal retail leverage print quality and structural aesthetics.
- Stationery Boxes:Document storage and organizational products serve corporate sustainability procurement programs.
Food Packaging retains the dominant share, while Cosmetics Containers gain share fastest on premium positioning momentum.
End User:
Customer procurement scale separates centralized chain mandates from fragmented direct purchasing.
- Food Manufacturers:Quick-service chains and ready-meal producers specify compostable packaging in supplier contracts, concentrating volume behind agricultural fiber formats. EU Packaging and Packaging Waste Regulation compliance deadlines accelerate substitution timelines.
- E-commerce Platforms:Fulfillment operations for food and personal care subscription services prioritize protective yet compostable unboxing experiences.
- Personal Care Brands:Clean beauty and natural product lines adopt wheat straw containers to differentiate shelf presence and sustainability credentials.
- Retail Outlets:Private-label food and gift packaging decisions follow chain-level sustainability commitments, particularly in German retail mandates.
- Pharmaceutical Companies:Secondary packaging applications remain limited by moisture barrier requirements and validation protocols.
Food Manufacturers hold the dominant procurement volume, with E-commerce Platforms climbing the fastest on fulfillment packaging redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail chains command 15-20% price premiums over North American institutional buyers for certified compostable wheat straw packaging, reflecting tighter regulatory deadlines and concentrated procurement power. This asymmetry concentrates manufacturing investment in Western European fiber processing capacity. Eastern European and Asian markets absorb residual supply at compressed margins due to infrastructure gaps.
Germany
Quick-service restaurant chains and private-label retailers drive concentrated demand for oil-resistant trays and boxes. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes with 2025 compliance deadlines. The Rhine-Ruhr industrial corridor hosts thermoforming operations that integrate chitosan coating lines with molded pulp production.
France
Institutional cafeteria operators in Paris and Lyon mandate closed-loop compostable packaging for public sector foodservice contracts. ANSM and ECHA coordinate substance authorization reviews for agricultural fiber processing aids. The Auvergne-Rhône-Alpes region clusters university procurement offices that bundle packaging with guaranteed disposal services.
United States
Corporate cafeteria operators and university sustainability offices in California and New York rewrite procurement specifications for agricultural fiber disposables. FDA food contact substance notifications govern interstate commerce of wheat straw composites. The Pacific Northwest concentrates molded pulp manufacturing capacity serving West Coast quick-service chains.
India
Food manufacturers and export-oriented processors adopt wheat straw packaging for European private-label compliance. FSSAI establishes food contact safety standards for agricultural fiber materials entering domestic and export channels. Gujarat and Maharashtra host fiber preprocessing facilities that supply thermoforming operations in Pune and Ahmedabad industrial zones.
China
E-commerce fulfillment platforms and quick-service chains drive demand for crush-resistant wheat straw boxes. SAMR and GB standards govern compostability claims and food contact safety for domestic market access. The Yangtze River Delta concentrates molded pulp manufacturing serving both domestic foodservice and export cosmetics container markets.
Wheat Straw Packaging Market Competitive Landscape
Integrated fiber processors and specialized compostable packaging suppliers split the market between scale-driven foodservice contracts and premium-positioned sustainability narratives. The vendor base concentrates around three strategic archetypes: multinational molded pulp manufacturers with captive fiber supply, regional specialists controlling composting infrastructure partnerships, and agricultural-waste material innovators serving cosmetics and gift packaging segments. Competitive dynamics center on thermoforming capacity expansion and BPI certification harmonization to secure multi-territory product registrations.
Among multinational molded pulp manufacturers, Huhtamaki anchors the scale-driven tier with integrated fiber processing and thermoforming operations. Eco-Products and Vegware occupy positions within the North American and European institutional channels respectively, exemplifying specialists that bundle packaging procurement with composting service contracts. These three companies represent the dominant competitive archetypes: manufacturing scale, infrastructure-integrated service models, and closed-loop verification capabilities.
| Leading Market Players |
|---|
| Huhtamaki |
| Eco-Products |
| Vegware |
| Biofutura |
| Pappco Greenware |
| GreenGood USA |
| Green Home |
| Biopac India Corporation |
| Yash Pakka |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor connects German thermoforming clusters to Mediterranean fiber preprocessing facilities, with transport cost swings amplifying margin compression for standard-grade wheat straw trays while configured-to-order chitosan-coated specifications capture procurement premiums from quick-service chains.
Pricing Analysis
The customization-premium spread separates standard wheat straw composite trays from chitosan-coated configured orders by fifteen to twenty percent. Three-tier pricing structure across premium, standard, and economy levels reflects BPI certification grade and volume scale. Pricing pressure stems from PLA film feedstock volatility linked to corn starch commodity markets. Food manufacturers exhibit highest price sensitivity, while cosmetics brands absorb premiums for agricultural-waste sustainability narratives.
Supply Chain Analysis
Export-control regime scrutiny of chitosan bio-coating technology limits technology transfer to unapproved thermoforming operations. Manufacturing concentrates in Germany, China, and India. Raw material procurement draws from wheat straw harvests, kraft paper pulp, and corn starch derivatives. Single-source vulnerability in industrial composting facility access creates disposal route uncertainty. Distribution runs through foodservice distributors and direct institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wheat straw packaging market approaches a platform-economics inflection as composting infrastructure partnerships become the interoperability layer that determines vendor viability. Closed-loop service bundling now separates sustainable procurement winners from commodity fiber suppliers.
For Market Incumbents: Insulate thermoforming capacity in the Rhine-Ruhr corridor against PLA price volatility through backward integration into fiber preprocessing. Secure multi-territory BPI certification ahead of harmonization deadlines to lock in quick-service chain procurement contracts before regulatory thresholds tighten.
For New Entrants and Emerging Players: Build out cosmetics container manufacturing capabilities targeting German and French clean beauty brands where agricultural-waste narratives command shelf price premiums. White-space opportunity concentrates in Eastern European markets where composting infrastructure gaps have delayed incumbent entry.
For Investors and Strategic Acquirers: Chitosan coating technology specialists with in-house polymer chemistry capabilities represent the highest-conviction acquisition archetype for medium-term consolidation. Watch for REACH substance authorization rulings on agricultural fiber processing aids as the signal indicating which formulation platforms will survive regulatory tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Chitosan Coating Scale-Up | Eliminates PLA lamination dependency for German quick-service hot-meal specifications. |
| Composting Infrastructure Partnership | Secures closed-loop verification for California and New York institutional cafeteria contracts. |
| REACH Compliance Investment | Accelerates product registration timelines for European agricultural fiber packaging launches. |
| Cosmetics Container Line Extension | Captures premium positioning in French clean beauty shelf differentiation strategies. |
| Fiber Preprocessing Capacity Addition | Buffers wheat straw harvest seasonality for continuous thermoforming operations. |
Research Methodology
A spread of perspectives from molded pulp plant managers, quick-service chain procurement directors, composting facility operators, and ECHA regulatory affairs specialists converged on the working assumptions shaping demand and supply trajectories. Primary fieldwork combined structured interviews with secondary validation against EU Packaging and Packaging Waste Regulation filings, BPI certification databases, and customs trade records for agricultural fiber packaging. Bottom-up volume estimates from thermoforming capacity utilization triangulated against top-down demand aggregation from foodservice procurement contracts.
Demand-supply-balance modeling across the analysis window segmented volume by product type, packaging material grade, application durability requirements, and end-user procurement scale. CAGRs derived from regression analysis of historical substitution rates for petroleum-based disposables. Forecast inputs incorporated chitosan coating technology adoption curves and composting infrastructure buildout timelines by metropolitan region.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated fiber-to-forming specialists would shift outcomes beyond modeled ranges. Material shifts in EU substance authorization rulings for agricultural fiber processing aids would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.