
 USA and Canada Molded Fiber Pulp Packaging Market | 2026-2036
USA and Canada Molded Fiber Pulp Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Molded Fiber Pulp Packaging Market Analytics
Food-grade specification upgrades across grease-resistant and oven-safe tiers is redrawing competitive boundaries in molded fiber pulp packaging. Huhtamaki Oyj leverages its North American thermoforming footprint to supply quick-service chains with certified compostable trays. Pactiv LLC anchors the institutional foodservice channel through direct distribution partnerships with broadline distributors. EnviroPAK Corporation specializes in custom-engineered protective formats for precision electronics, differentiating on dimensional stability rather than commodity volume.
USA and Canada molded fiber pulp packaging consists of formed cellulose structures manufactured through vacuum-filtration or press-molding processes using slurries of recycled paper, virgin fiber, or agricultural residues such as sugarcane bagasse, typically achieving wall thicknesses of 1.5–4.0 mm for structural protection or 0.8–1.5 mm for food-contact trays. These products serve primarily as protective cushioning, containment vessels, and retail display platforms across sectors requiring biodegradability or plastic displacement. Trays dominate foodservice procurement due to standardized sizing for protein and produce presentation, while clamshells capture expanding demand in grab-and-go retail formats where hinged-lid security matters. Recycled paper feeds most volume production, though sugarcane fiber commands margin premiums in premium cosmetic and pharmaceutical applications where whiteness and fiber uniformity carry brand weight.
The US FDA maintains food-contact substance notification requirements for molded fiber additives and coatings, while EPA guidelines on recycled content labeling shape procurement specifications for federal vendors; Environment Canada administers the Single-use Plastics Prohibition Regulations that directly ban polystyrene foodware alternatives in provinces aligning with federal schedules. State-level extended producer responsibility frameworks in California, Oregon, and Washington further tighten material traceability obligations. Stakeholders must monitor composting facility certification standards across jurisdictions, as ASTM D6400 and D6868 compliance gaps between products and local processing capacity threaten value-chain credibility.
Market Dynamics
US EPA and Environment Canada restrictions on single-use plastics are compressing demand timelines for polystyrene alternatives, forcing foodservice operators to accelerate molded fiber qualification cycles and lock in multi-year supply contracts ahead of regulatory deadlines.
Growth Catalysts
- Single-use plastics prohibitions:Environment Canada's federal ban schedule and US state-level mandates in California, Oregon, and Washington are eliminating polystyrene foodware from institutional procurement.
- Municipal composting infrastructure:Curbside organics collection in Seattle, San Francisco, and Toronto creates end-of-life pathways that validate molded fiber's biodegradability claims.
- Quick-service restaurant chain commitments:Corporate sustainability targets at major burger and coffee chains are converting tray and cup carrier specifications to certified compostable formats.
Market Restraints
- Recycled fiber cost volatility:OCC (old corrugated containers) pricing swings track pulp futures, compressing converter margins when post-consumer feedstock spikes.
- Regional supply concentration:Thermoforming capacity clusters in the Midwest and Southeast create freight disadvantages for West Coast foodservice distributors.
- Performance gaps in high-moisture applications:Uncoated molded fiber loses structural integrity beyond 30 minutes in sauced protein presentations, limiting full-menu replacement.
Strategic Opportunities
- Canadian provincial alignment gaps:Alberta and Saskatchewan lag federal single-use plastics schedules, creating windows for early supplier positioning ahead of harmonized enforcement.
- Pharmaceutical secondary packaging:Moisture-buffered molded fiber inserts for temperature-sensitive biologics represent an untapped specification tier above commodity foodservice.
- Extended producer responsibility frameworks:California's SB 54 implementation is forcing brand owners to fund collection infrastructure, indirectly subsidizing molded fiber's composting access.
Industry Challenges
- ASTM D6400 certification bottlenecks:Third-party lab testing queues stretch 14-18 weeks, delaying product launches for seasonal foodservice contracts.
- Thermoforming tool capex intensity:Custom aluminum molds for proprietary tray dimensions require $150,000-$400,000 upfront investment, constraining SKU proliferation.
- Coating chemistry compliance:PFAS-free grease barrier formulations must navigate FDA food-contact notification reviews that add 6-12 months to development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Molded Fiber Pulp Packaging Market |
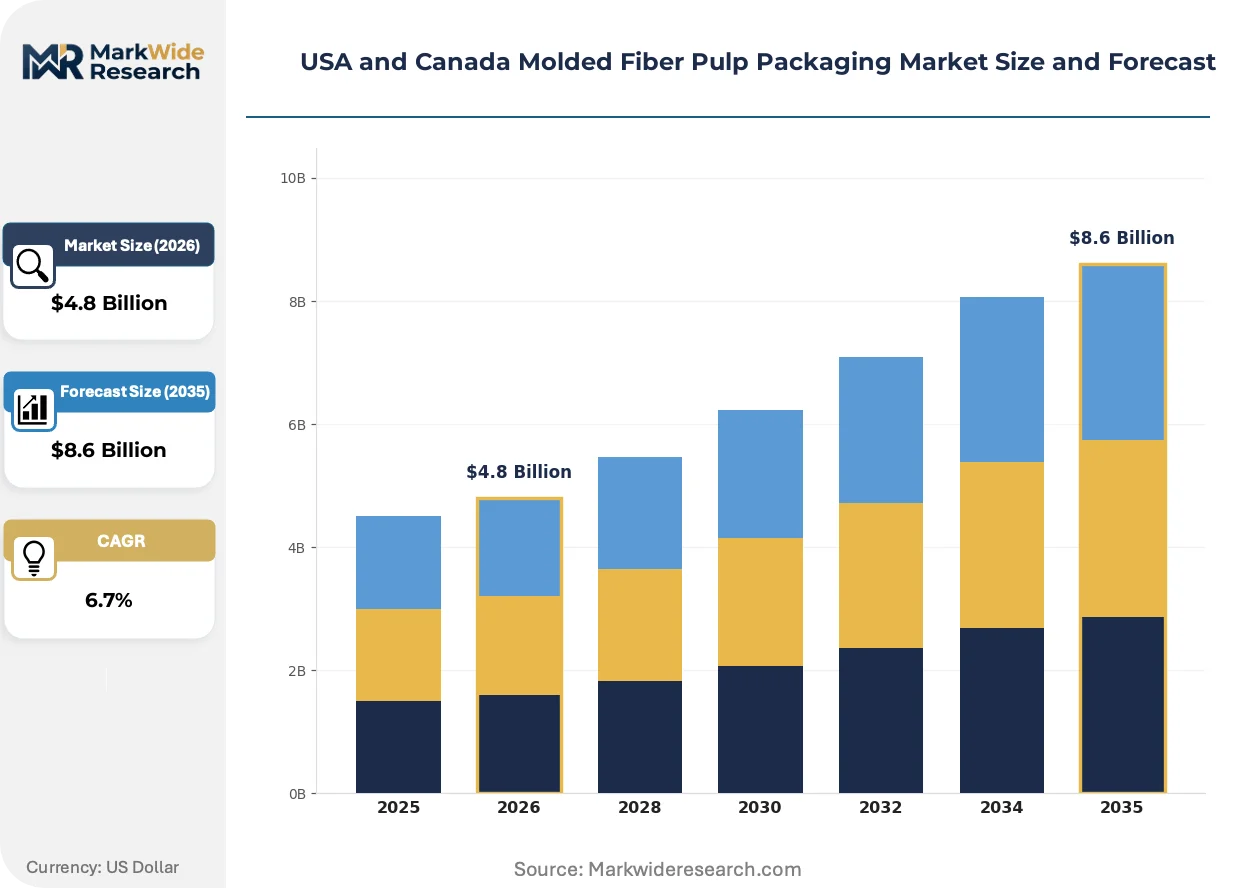
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Clamshells, Containers, Pads End User: Food & Beverage, Electronics, Healthcare, Consumer Goods Application: Packaging, Protection, Display, Shipping Material: Recycled Paper, Virgin Fiber, Bamboo, Sugarcane |
| Companies Covered | Pactiv LLC, Western Pulp Products Company, ProtoPak Engineering Corporation, Pacific Pulp Molding, Inc., FiberCel Packaging LLC, Henry Molded Products Inc., EnviroPAK Corporation, Michelsen Packaging Company, Huhtamaki Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Molded Fiber Pulp Packaging Market Evolving Landscape
Equipment automation and coating chemistry advances are compressing cycle times and expanding performance envelopes, enabling molded fiber to penetrate applications previously reserved for plastic or foam.
Thermoforming press technology is bifurcating the competitive landscape. High-speed rotary machines from European suppliers now achieve 45-second cycle times for deep-draw clamshells, while North American fabricators still rely on slower platen presses. Quick-service chains with national rollout schedules are specifying rotary-formed trays exclusively. This equipment gap is concentrating volume with converters who have invested in next-generation thermoforming lines, marginalizing smaller regional players on speed and unit economics.
Environment Canada's Single-use Plastics Prohibition Regulations are tightening enforcement timelines for polystyrene foodware. The federal framework allows provinces to accelerate implementation, and British Columbia has already advanced its ban date ahead of the national schedule. Foodservice distributors serving cross-border chains must now maintain dual SKU portfolios: compliant formats for Canadian locations and legacy stock for US jurisdictions with slower phase-outs. This regulatory asynchrony is forcing inventory complexity into already thin-margin distribution channels.
Chain-level sustainability scorecards are reshaping supplier selection criteria. Major quick-service operators now weight compostability certification at 15-20% of total vendor evaluation, up from nominal consideration five years ago. Broadline distributors like Sysco and US Foods are responding by pre-qualifying molded fiber SKUs in their private-label portfolios. This preference shift is most visible in California and Washington, where municipal procurement mandates amplify corporate sustainability targets.
USA and Canada Molded Fiber Pulp Packaging Market Segmentation
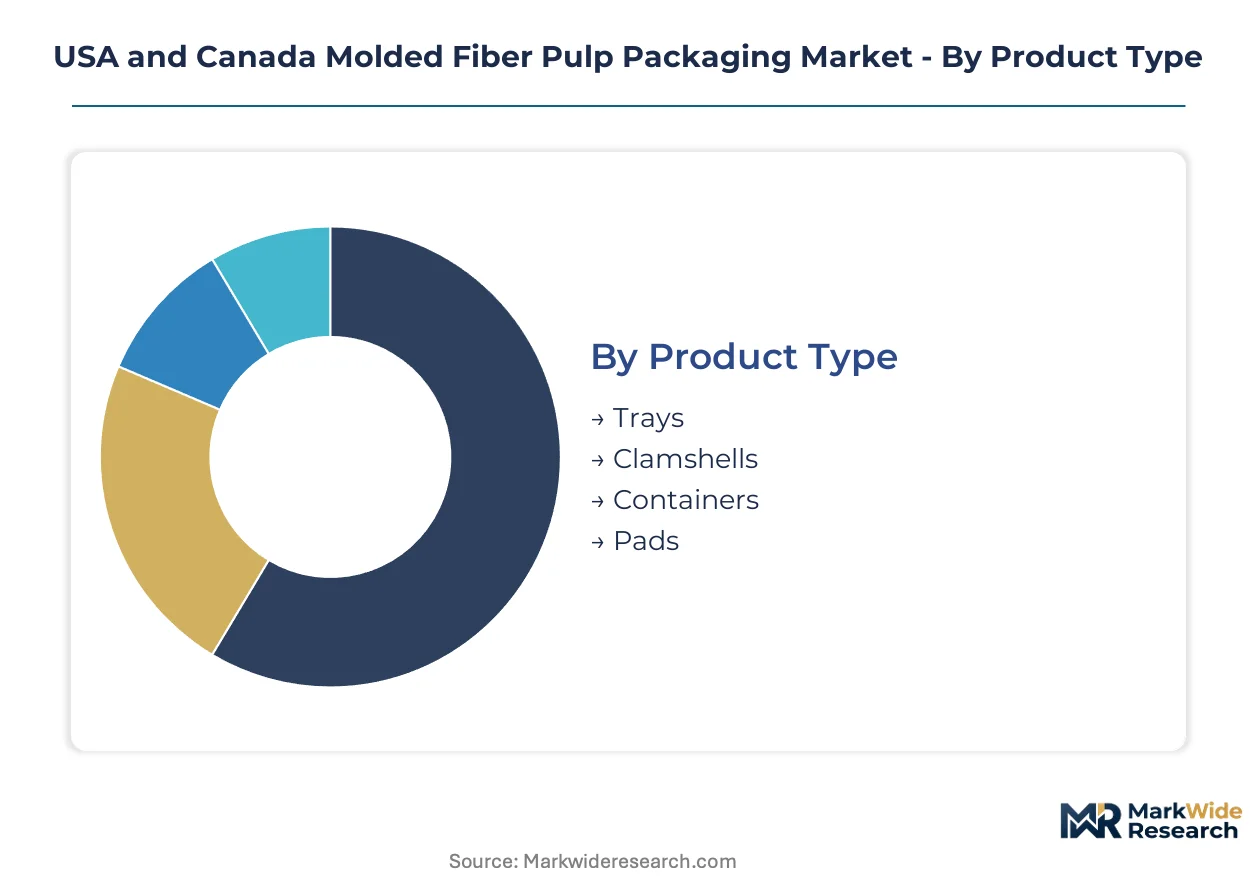
Molded fiber pulp packaging exhibits sharp specification divergence across end-use requirements, with FDA food-contact notifications governing foodservice formats and dimensional stability standards driving electronics-grade production. Segmentation clarity enables converters to align thermoforming investments with regulatory compliance burdens and margin structures.
Product Type:
US EPA and Environment Canada single-use plastics prohibitions create tiered compliance urgency, with food-contact formats facing accelerated qualification timelines ahead of state and provincial enforcement deadlines.
- Trays:Standardized rectangular formats with 0.8–1.5 mm wall thickness dominate quick-service protein and produce presentation. California and Washington institutional procurement mandates concentrate demand for certified compostable specifications.
- Clamshells:Hinged-lid designs with integrated locking tabs serve grab-and-go retail formats requiring tamper evidence. British Columbia's advanced polystyrene ban timeline is forcing cross-border chains to dual-source compliant SKUs ahead of US state phase-outs.
- Containers:Deep-draw cylindrical formats for soup and grain bowls.
- Pads:Flat cushioning sheets for secondary protective layers in electronics shipping.
Established volume favors Trays; emerging adoption favors Clamshells.
End User:
Cost tier differentiation separates commodity foodservice procurement from premium pharmaceutical specifications, with coating chemistry investments determining margin capture.
- Food & Beverage:Quick-service chains and institutional cafeterias drive standardized tray and carrier formats. California SB 54 extended producer responsibility frameworks are shifting collection infrastructure costs onto brand owners, indirectly subsidizing composting access for molded fiber alternatives.
- Electronics:Precision-molded protective formats demand dimensional stability within ±0.5 mm tolerance for component shipping. Toronto and Vancouver tech manufacturing clusters concentrate demand for custom-engineered protective solutions.
- Healthcare:Sterile barrier formats for medical device secondary packaging.
- Consumer Goods:Cosmetic and personal care display platforms emphasizing fiber whiteness.
Procurement scale concentrates in Food & Beverage; margin expansion concentrates in Electronics.
Application:
Volume distribution tracks functional performance requirements, with moisture resistance specifications creating specification boundaries between containment and protective uses.
- Packaging:Primary containment vessels for food and consumer products. Oregon and Washington municipal composting infrastructure validates end-of-life claims for curbside collection eligibility.
- Protection:Cushioning and bracing formats for shock-sensitive shipments. Midwest electronics distribution hubs generate concentrated demand for engineered protective geometries.
- Display:Retail-ready presentation platforms with printed fiber surfaces.
- Shipping:Dunnage and void-fill formats for freight consolidation.
Unit volume leadership sits with Packaging; technical differentiation concentrates in Protection.
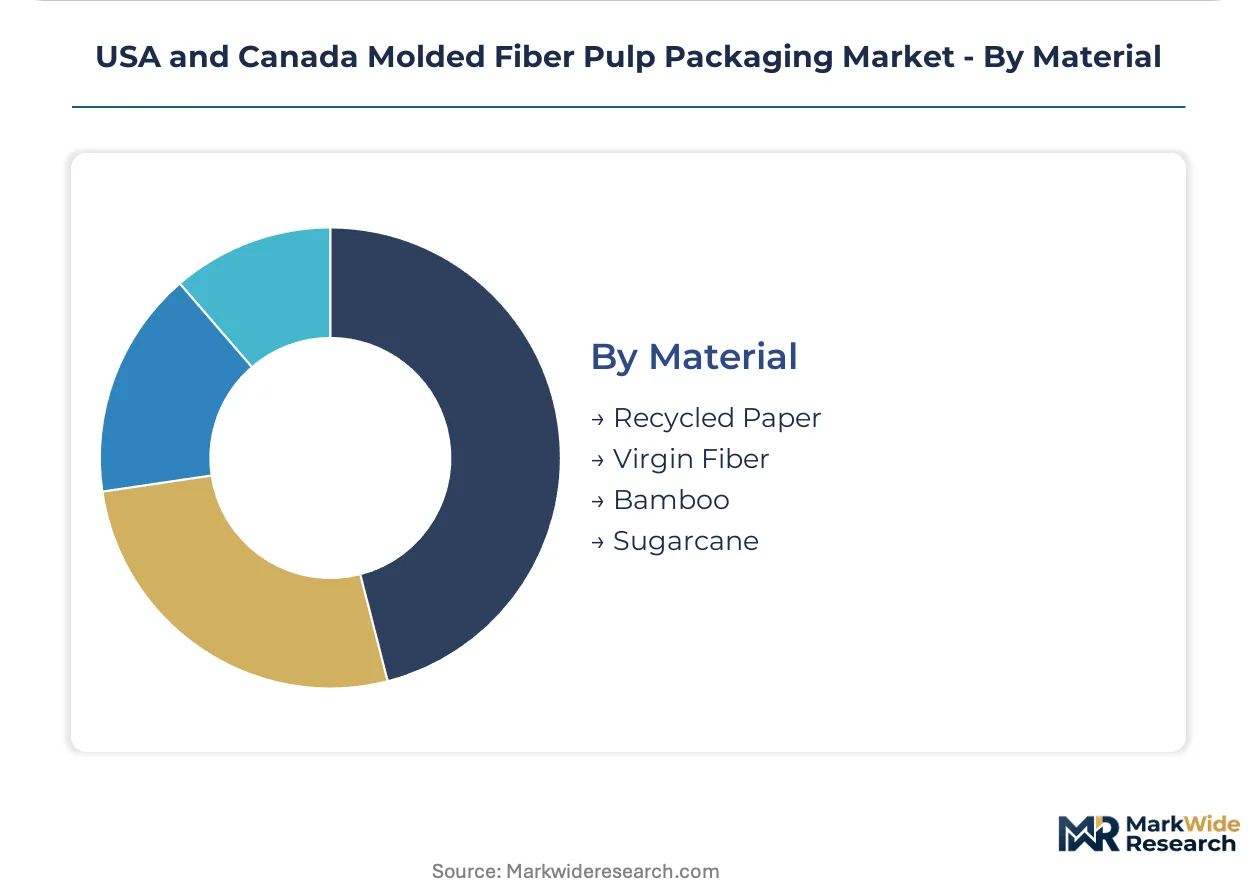
Material:
Supply concentration and feedstock cost volatility separate recycled commodity streams from agricultural residue premiums, with fiber uniformity determining specification tier eligibility.
- Recycled Paper:OCC-derived slurries feed majority volume production through vacuum-filtration processes. Pacific Northwest deinking capacity clusters create regional supply advantages for West Coast converters.
- Sugarcane:Bagasse fiber commands specification premiums in cosmetic and pharmaceutical applications where whiteness and batch uniformity carry brand weight. FDA food-contact notification requirements add 6–12 months to qualification cycles for coated formulations.
- Virgin Fiber:Bleached kraft pulp for premium food-contact whiteness specifications.
- Bamboo:Rapid-renewal grass fiber for sustainability-positioned consumer goods.
Feedstock scale favors Recycled Paper; margin premiums favor Sugarcane.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermoforming capacity clusters in the US Midwest and Southeast, creating freight cost differentials that disadvantage West Coast foodservice distributors sourcing from distant mills. California and Washington municipal composting infrastructure validates end-of-life claims, while Canadian provincial alignment gaps create regulatory arbitrage windows for early supplier positioning.
United States
California's SB 54 extended producer responsibility framework shifts collection infrastructure costs onto brand owners, indirectly subsidizing molded fiber composting access in Los Angeles and San Francisco metro areas. The US EPA restrictions on single-use plastics accelerate polystyrene displacement timelines for quick-service chains. Pacific Northwest deinking capacity clusters around Portland and Seattle supply recycled fiber feedstock to West Coast converters.
Canada
British Columbia advanced its polystyrene ban ahead of Environment Canada's federal schedule, forcing cross-border chains to maintain dual SKU portfolios for compliant formats. Ontario's foodservice distribution hubs in Toronto concentrate institutional procurement demand for certified compostable trays. Alberta and Saskatchewan lag federal implementation timelines, creating positioning windows ahead of harmonized enforcement.
Mexico
Export-oriented electronics assembly in Tijuana and Guadalajara generates protective packaging demand for precision component shipping to US distribution hubs. Mexico's national environmental regulator has not enacted single-use plastics prohibitions equivalent to US or Canadian federal frameworks. Baja California manufacturing clusters currently source molded fiber cushioning from US-based suppliers across the border.
USA and Canada Molded Fiber Pulp Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the molded fiber pulp packaging sector. The market structure fragments between high-volume thermoforming specialists serving quick-service restaurant chains and custom-engineered protective format providers targeting electronics and pharmaceutical specifications. Three strategic archetypes dominate: multinational converters with North American thermoforming footprints, regional fabricators with direct distribution partnerships, and niche specialists differentiating on dimensional stability. Capacity expansion and PFAS-free coating chemistry investments represent the dominant competitive moves as regulatory deadlines compress qualification cycles.
Among North American-based fabricators, Pactiv LLC anchors the institutional foodservice channel through broadline distributor relationships, while EnviroPAK Corporation occupies a position within the precision protective packaging tier. Huhtamaki Oyj exemplifies the multinational converter archetype with thermoforming capacity positioned to supply quick-service chains requiring certified compostable formats at scale.
| Leading Market Players |
|---|
| Pactiv LLC |
| Western Pulp Products Company |
| ProtoPak Engineering Corporation |
| Pacific Pulp Molding, Inc. |
| FiberCel Packaging LLC |
| Henry Molded Products Inc. |
| EnviroPAK Corporation |
| Michelsen Packaging Company |
| Huhtamaki Oyj |
| Others |
Value Network & Pricing Analysis
Thermoforming capacity utilization above 85% in the US Midwest and Southeast establishes price floors that West Coast converters cannot match without freight premiums. This geographic asymmetry concentrates pricing power with regional volume leaders while forcing distant buyers to absorb logistics differentials or accept thinner margins.
Pricing Analysis
Environment Canada's Single-use Plastics Prohibition Regulations dictate the pricing tier structure by accelerating compliance-grade premiums ahead of enforcement deadlines. Three-tier pricing structure across certified compostable, PFAS-free compliant, and uncoated commodity levels separates quick-service chain procurement from institutional cafeteria budgets. Pricing pressure stems from OCC feedstock volatility tracking pulp futures, compressing converter margins during post-consumer fiber spikes. Institutional foodservice buyers exhibit highest price sensitivity due to fixed municipal contract terms, while pharmaceutical secondary packaging buyers absorb premiums for dimensional stability specifications.
Supply Chain Analysis
The United States and Canada anchor molded fiber pulp production through clustered thermoforming capacity in Ohio, Indiana, and Ontario. Feedstock draws from Pacific Northwest deinking facilities for recycled paper slurries and Gulf Coast sugarcane bagasse processing for premium cosmetic grades. Supply chain risk centers on single-source vulnerability for PFAS-free barrier coatings awaiting FDA food-contact notification clearance. Distribution runs through broadline foodservice distributors like Sysco and US Foods, with direct mill-to-chain relationships capturing national quick-service rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal composting infrastructure interoperability across Seattle, San Francisco, and Toronto creates platform-economics dynamics where end-of-life collection access determines supplier viability. This ecosystem shift rewards converters who secure certification alignment ahead of franchise system standardization.
For Market Incumbents: Compound thermoforming capacity advantages by locking multi-year supply contracts with quick-service chains ahead of regulatory deadlines. Defend against rotary-press technology gaps through European equipment partnerships or tolling arrangements. Prioritize PFAS-free coating R&D to maintain certification leadership as FDA notification queues lengthen.
For New Entrants and Emerging Players: Anchor in Alberta and Saskatchewan positioning windows before Environment Canada harmonizes provincial enforcement timelines. Target pharmaceutical secondary packaging for temperature-sensitive biologics where dimensional stability premiums exceed foodservice commodity margins. Pursue custom-engineered protective formats for Toronto and Vancouver electronics clusters as a go-to-market foundation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with multi-year quick-service chain contracts and certified SKU pre-qualification in broadline distributor portfolios. Long-term viability hinges on coating chemistry IP and thermoforming equipment vintage rather than raw scale. Target acquisition archetypes combine rotary-press capacity with ASTM D6400 certification backlog clearance. The signal to watch is municipal composting facility expansion rates validating end-of-life claims.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Development | FDA notification clearance accelerates product launches ahead of seasonal foodservice contract cycles. |
| Rotary Thermoforming Equipment Upgrade | European press technology achieves 45-second cycle times that national quick-service chains now specify exclusively. |
| Cross-Border SKU Harmonization | British Columbia's advanced ban timeline forces dual-portfolio inventory management for US-Canada chains. |
| Municipal Composting Partnership | Curbside organics collection validation in California and Washington secures end-of-life claim credibility. |
| Extended Producer Responsibility Alignment | California SB 54 implementation shifts collection infrastructure costs onto brand owners subsidizing fiber access. |
Research Methodology
A standing panel of thermoforming plant managers, broadline distributor category buyers, quick-service chain procurement directors, and municipal waste management officials provided ongoing calibration across primary fieldwork. Secondary validation drew from US EPA enforcement schedules, Environment Canada regulatory filings, FDA food-contact substance notifications, and ASTM certification databases. Bottom-up volume modeling across product types, end users, and material feedstocks triangulated against top-down market sizing from trade association production surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product format, end-use sector, application function, and material feedstock tier, with provincial regulatory alignment status as a cross-cutting variable. CAGRs were derived from regression analysis of historical capacity expansion and substitution elasticity against polystyrene displacement timelines. Industry-specific inputs incorporated thermoforming press utilization rates and municipal composting facility certification coverage.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement timelines and stable OCC feedstock availability; material deviation in either driver would warrant model refresh. Recalibration cycles align with shifts in Environment Canada provincial harmonization schedules and FDA coating notification clearance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Europe Transfer Molded Pulp Packaging Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Wheat Straw Packaging Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Fiber Based Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market