
 Safety Critical Software Testing Market | 2026-2036
Safety Critical Software Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Critical Software Testing Market Outlook
DO-178C is pivoting the cost-of-entry calculus for aviation software suppliers as airborne systems face stricter verification mandates. Vector Informatik GmbH leverages its embedded-tooling heritage to dominate automotive ECU validation workflows. Rapita Systems Ltd specializes in worst-case execution time analysis for aerospace clients. LDRA sustains decades of standards-track authority across multiple certification frameworks.
Safety critical software testing encompasses systematic verification and validation of software whose failure could result in loss of life, severe injury, or significant environmental harm, requiring deterministic behavior proof through static analysis, dynamic testing, and formal methods against quantified integrity levels. Its primary purpose is to demonstrate compliance with functional safety standards before deployment in autonomous vehicles, avionics, medical devices, and industrial control systems. Static analysis commands mature margin pools in automotive toolchains, while simulation testing captures the fastest expansion as digital twin adoption accelerates validation cycles. Compliance testing anchored to ISO 26262 and DO-178C concentrates pricing power with vendors holding dual-standard accreditation.
FDA scrutiny of software-as-a-medical-device intensifies premarket submission requirements for patient-facing algorithms. EASA and FAA harmonization on multicore processor certification is reshaping avionics testing protocols. China's SAMR and GB standards for intelligent vehicle software add parallel compliance layers for suppliers serving domestic OEMs. Stakeholders must monitor regulatory divergence between jurisdictions to avoid redundant certification investments.
Market Dynamics
Autonomous vehicle deployment timelines are compressing validation cycles as OEMs demand deterministic proof of software integrity before production release, forcing testing vendors to accelerate certification workflows without compromising ISO 26262 compliance thresholds.
Growth Catalysts
- ISO 26262 Functional Safety Mandates:Automotive OEMs in Germany, Japan, and the United States face escalating validation requirements for autonomous driving systems, expanding contract volumes for certified testing providers.
- Digital Twin Simulation:Virtual validation environments reduce physical prototype dependency, enabling earlier-stage defect detection in avionics and medical device software development pipelines.
- China:SAMR and GB standards for intelligent vehicle software create parallel compliance obligations for suppliers serving domestic OEMs, generating incremental certification demand.
Market Restraints
- Specialized Engineering Talent Scarcity:Worst-case execution time analysis and formal methods expertise concentrates in aerospace clusters around Toulouse, Seattle, and Munich, constraining vendor scaling.
- Silicon Supply Concentration:Multicore processor validation dependencies on TSMC and Samsung foundry output create bottlenecks for avionics testing hardware procurement.
- IEC 61508 Certification Costs:Industrial automation suppliers face six-figure accreditation expenses that exclude mid-tier system integrators from safety-critical project bidding.
Strategic Opportunities
- Software-as-a-Medical-Device:FDA premarket submission intensification for patient-facing algorithms opens validation services for diagnostic AI and remote monitoring platforms.
- EASA-FAA Multicore Harmonization:Unified avionics processor certification standards reduce redundant testing investments for suppliers serving transatlantic aerospace programs.
- Formal Methods Convergence:Integration of static analysis with model-based design tools creates unified toolchains for automotive ECU verification workflows.
Industry Challenges
- DO-178C Objective Evidence Documentation:Aviation software suppliers face 50,000+ artifact requirements per certification submission, straining quality assurance bandwidth.
- Legacy System Integration:Industrial control retrofits require backward-compatible testing protocols that extend project timelines and complicate toolchain standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Critical Software Testing Market |
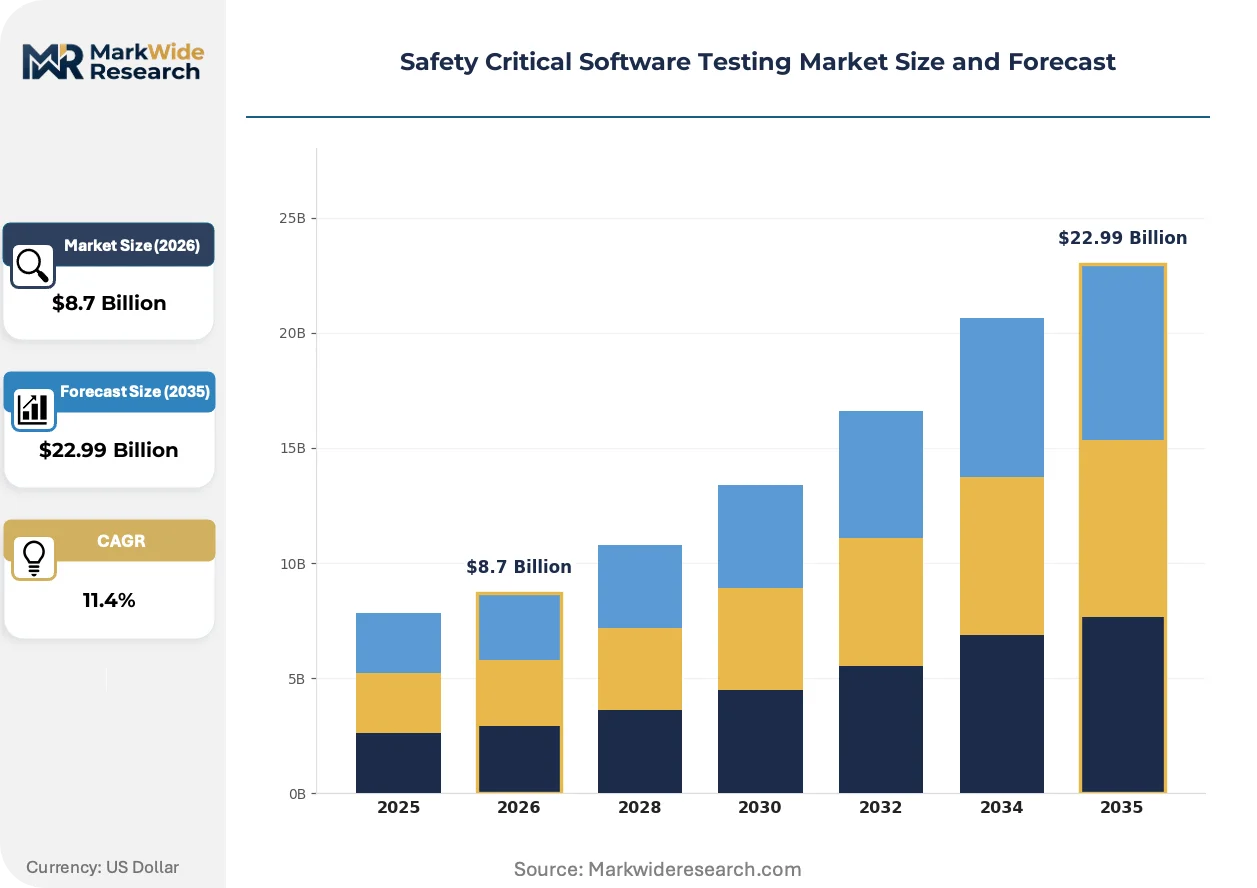
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Aerospace, Automotive, Medical Devices, Industrial Automation Testing Methodology: Static Analysis, Dynamic Testing, Simulation Testing, Compliance Testing End User Type: OEMs, Tier-1 Suppliers, Regulatory Bodies, Software Vendors Certification Standard: ISO 26262, DO-178C, IEC 61508, EN 50128 |
| Companies Covered | Vector Informatik GmbH, Rapita Systems Ltd, Critical Software, Synopsys, Tricentis, Hewlett Packard Enterprise Development LP, LDRA, GrammaTech, Parasoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Critical Software Testing Market Strategic Shifts
Testing methodologies are fragmenting into specialized vertical stacks as deterministic behavior proof requirements diverge across automotive, aerospace, and medical device domains, eroding generalist vendor positioning.
Containerized test environments are modularizing validation infrastructure deployment. Automotive Tier-1 suppliers adopt Kubernetes-orchestrated simulation clusters to parallelize ISO 26262 test execution. This architecture compresses hardware-in-the-loop provisioning from weeks to hours, enabling just-in-time validation capacity scaling.
EASA and FAA alignment on multicore processor certification is reshaping avionics software verification protocols. Harmonized CAST-32A guidance reduces redundant testing for suppliers serving dual-jurisdiction programs. Aerospace integrators in France and the United States are consolidating test artifact repositories to satisfy both regulators simultaneously.
Subscription-based tool licensing is displacing perpetual software purchases among mid-cap automotive suppliers. Vector Informatik and LDRA pivot toward annual recurring revenue models with embedded training credits. Germany's industrial automation corridor shows the fastest uptake of this procurement restructuring.
Safety Critical Software Testing Market Segmentation
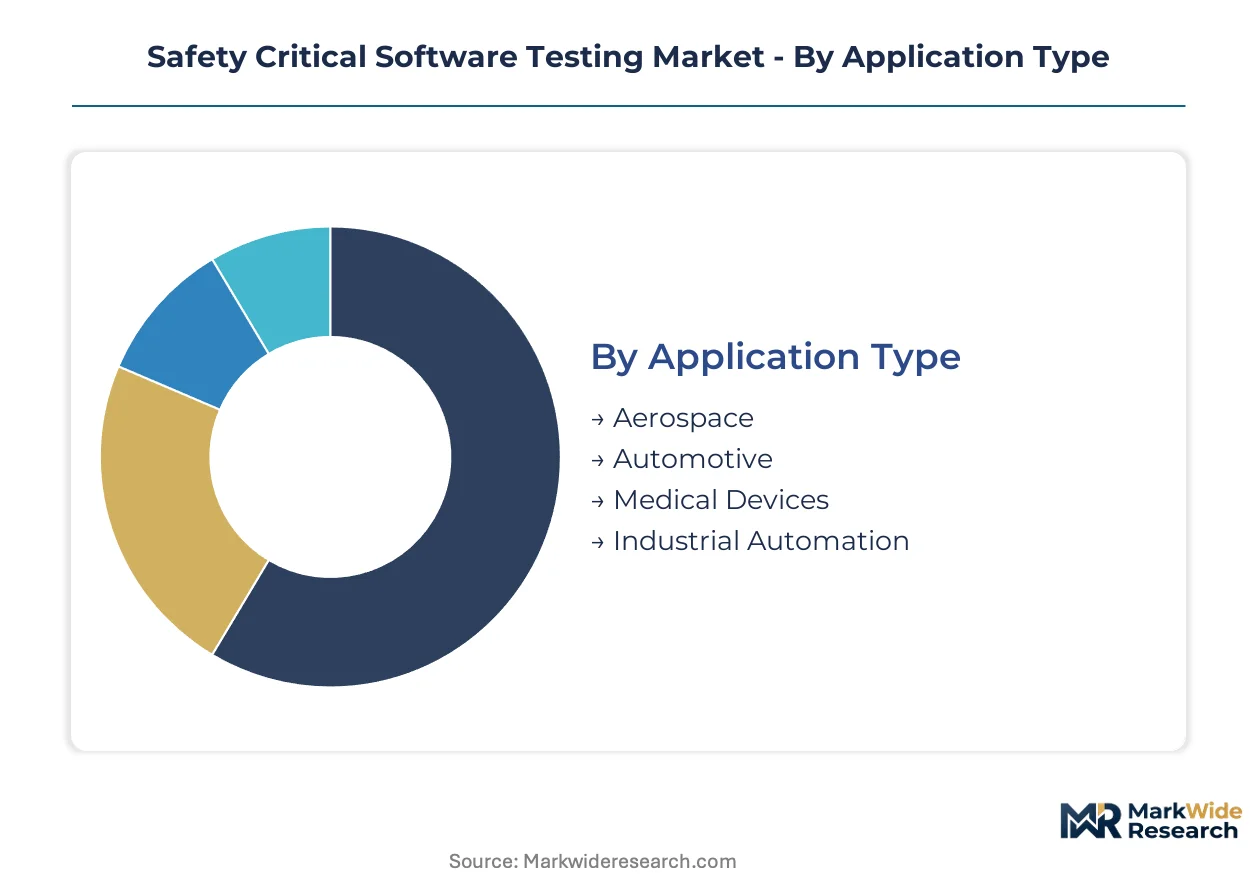
Safety critical software testing demands diverge sharply across certification regimes and application domains. Segmentation reveals how vendor capabilities align with specific compliance workflows rather than generic quality assurance.
Application Type:
Supply concentration clusters around automotive validation as ISO 26262 mandates tighten across Germany, Japan, and the United States.
- Aerospace:DO-178C verification mandates require deterministic proof of airborne software behavior through formal methods and structural coverage analysis. Demand concentrates in Toulouse, Seattle, and Munich aerospace clusters where EASA and FAA certification timelines compress supplier capacity.
- Automotive:Autonomous driving systems validation absorbs the largest contract volumes as OEMs expand functional safety budgets for ADAS and self-driving platforms. German and Japanese manufacturers drive procurement of deterministic testing toolchains.
- Medical Devices:FDA premarket submission requirements for software-as-a-medical-device intensify validation protocols for diagnostic algorithms and patient monitoring systems.
- Industrial Automation:IEC 61508 certification costs in Germany's Ruhr industrial corridor constrain mid-tier integrator participation.
Automotive absorbs the bulk of installed capacity; medical devices is expanding most quickly.
Testing Methodology:
Cost tier stratification separates mature static analysis tools from capital-intensive simulation infrastructure.
- Static Analysis:Automated code inspection without execution dominates automotive ECU verification with mature margin pools. German Tier-1 suppliers standardize on these toolchains for ISO 26262 compliance documentation.
- Dynamic Testing:Runtime behavior verification through hardware-in-the-loop environments commands premium pricing. Aerospace integrators in France and the United States procure these capabilities for multicore processor validation.
- Simulation Testing:Digital twin environments reduce physical prototype dependency for avionics and medical device pipelines.
- Compliance Testing:Standards-track accreditation services concentrate pricing power with vendors holding dual-standard certification authority.
Static analysis captures the widest deployment base; simulation testing shows the steepest expansion trajectory.
End User Type:
Customer type determines procurement scale and certification risk allocation across the value chain.
- OEMs:Vehicle and aircraft manufacturers internalize validation for strategic autonomy over safety-critical release decisions. Toyota, Airbus, and Boeing maintain captive testing infrastructure.
- Tier-1 Suppliers:Continental, Bosch, and Thales outsource specialized compliance testing to accredited third-party vendors.
- Regulatory Bodies:FAA, EASA, and NHTSA define certification protocols but rarely procure testing services directly.
- Software Vendors:Embedded toolchain providers integrate validation modules into integrated development environments.
Tier-1 suppliers absorb the bulk of outsourced contract value; software vendors are climbing the fastest as subscription models displace perpetual licensing.
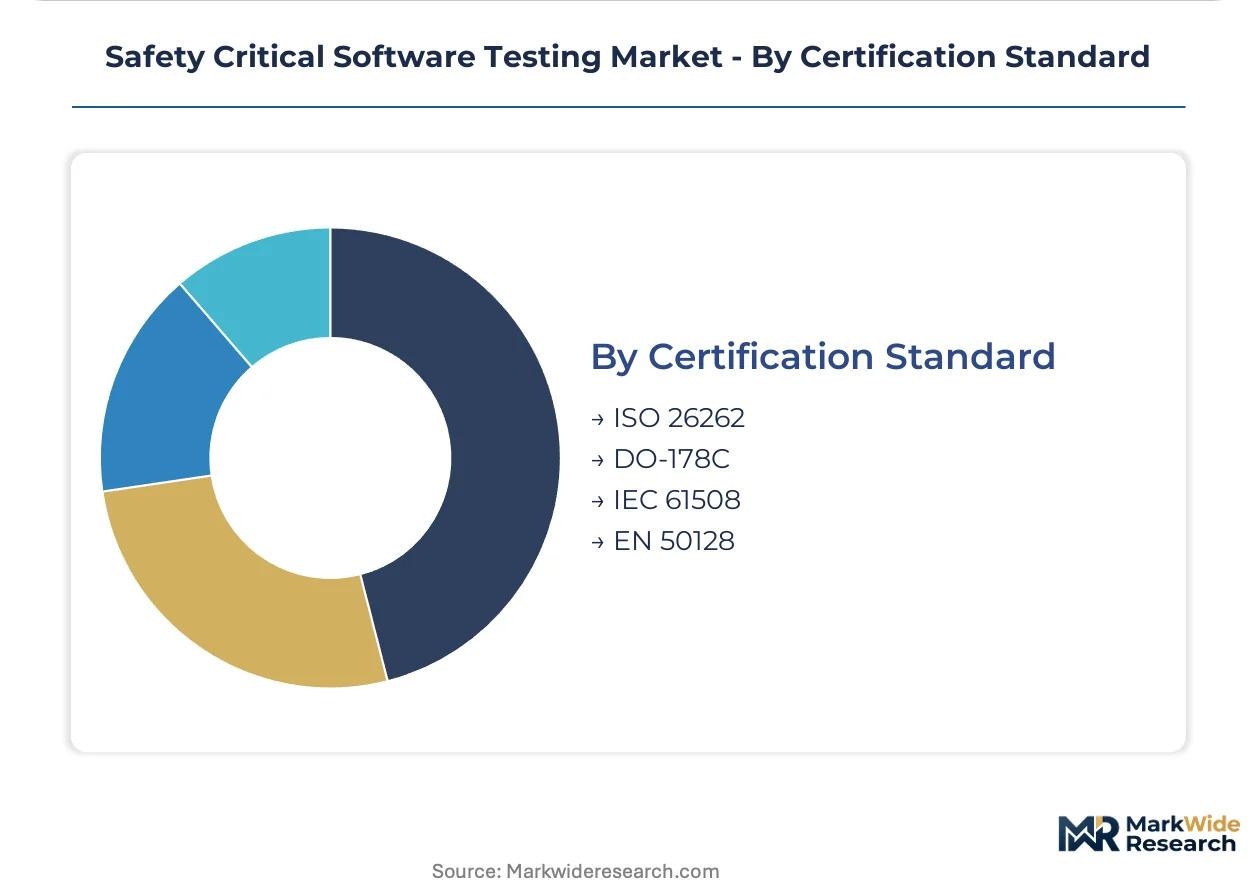
Certification Standard:
Geography of application dictates which standard governs vendor qualification and testing protocol design.
- ISO 26262:Automotive functional safety standard governs validation for road vehicles across European, Japanese, and North American markets. ASIL-D integrity level requirements drive worst-case execution time analysis demand.
- DO-178C:Aviation software standard mandates objective evidence documentation exceeding fifty thousand artifacts per submission. Suppliers serving Boeing and Airbus programs face compressed delivery timelines.
- IEC 61508:Industrial functional safety standard concentrates procurement in Germany's automation corridor.
- EN 50128:Railway software standard governs signaling and control system validation across European rail networks.
ISO 26262 absorbs the bulk of current certification expenditure; DO-178C is gaining share fastest as multicore processor harmonization reduces redundant testing investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrial Automation Corridor special economic zone concentrates IEC 61508 certification demand, while automotive functional safety mandates in Stuttgart and Munich drive ISO 26262 validation spending. Tax incentives for embedded software R&D in Bavaria and Baden-Württemberg anchor European testing infrastructure investment.
United States
FAA DO-178C mandates for multicore processor certification compress supplier capacity in Seattle and Dallas aerospace clusters. NHTSA autonomous vehicle guidance expands validation budgets for Detroit and Silicon Valley automotive developers. FDA premarket submission intensification for software-as-a-medical-device concentrates demand in Boston and San Diego biotech corridors.
Germany
KBA enforcement of ISO 26262 ASIL-D requirements drives worst-case execution time analysis procurement from Munich and Stuttgart automotive OEMs. IEC 61508 certification costs in the Ruhr industrial corridor constrain mid-tier system integrator participation. Vector Informatik GmbH leverages embedded-tooling heritage to dominate ECU validation workflows across Bavaria.
Japan
METI standards for intelligent vehicle software create parallel compliance obligations for Toyota and Honda suppliers in Nagoya and Tokyo. JIS certification requirements govern industrial control system validation in Osaka manufacturing clusters. Japanese Tier-1 suppliers outsource specialized compliance testing to accredited third-party vendors amid domestic talent scarcity.
China
SAMR and GB standards for autonomous driving systems generate incremental certification demand for suppliers serving BYD and NIO in Shenzhen and Shanghai. MIIT software reliability mandates intensify premarket validation for intelligent vehicle platforms. Domestic OEMs in Beijing-Tianjin-Hebei cluster require dual-standard accreditation for export-bound components.
France
EASA multicore harmonization with FAA reduces redundant testing investments for Airbus suppliers in Toulouse aerospace cluster. ANSM scrutiny of medical device software intensifies validation protocols for Paris-based diagnostic algorithm developers. French aerospace integrators consolidate test artifact repositories to satisfy both European and transatlantic regulators simultaneously.
Safety Critical Software Testing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across fragmented certification niches. The vendor base stratifies between standards-track incumbents holding dual-accreditation authority and emerging simulation-platform entrants. Three archetypes dominate: embedded-tooling heritage firms, worst-case execution time analysis boutiques, and automated test orchestration platforms. Competitive moves center on subscription-model displacement of perpetual licensing and containerized test environment modularization.
Within the embedded-tooling tier, Vector Informatik GmbH exemplifies heritage-based market positioning, while Rapita Systems Ltd occupies the aerospace-specialist niche. LDRA represents the multi-standard accreditation archetype with sustained authority across automotive, aviation, and industrial frameworks. These three firms anchor distinct competitive vectors without overlapping capability claims.
| Leading Market Players |
|---|
| Vector Informatik GmbH |
| Rapita Systems Ltd |
| Critical Software |
| Synopsys |
| Tricentis |
| Hewlett Packard Enterprise Development LP |
| LDRA |
| GrammaTech |
| Parasoft |
| Others |
Value Chain & Pricing Dynamics
Specialized engineering talent scarcity in Munich, Toulouse, and Seattle feeds directly into tiered service pricing as vendors pass certification labor premiums downstream to automotive OEMs and aerospace integrators.
Pricing Analysis
Expedited certification timelines command 25-40% premiums over standard delivery schedules as Boeing and Airbus programs compress supplier capacity. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification complexity, with DO-178C artifact documentation at the apex and ISO 26262 static analysis at the base. Price differentiation stems from dual-standard accreditation authority and geographic talent concentration. Tier-1 automotive suppliers exhibit highest price sensitivity as validation budgets face OEM cost-down pressure; captive testing infrastructure at Toyota and Airbus shows lowest sensitivity.
Supply Chain Analysis
Hardware-in-the-loop refurbishment and calibration flows from Seattle and Dallas aerospace clusters back to original equipment vendors reduce capital expenditure for mid-tier testing providers. Multicore processor supply concentrates in Taiwan, South Korea, and the United States, with TSMC and Samsung foundry output governing avionics validation hardware availability. Testing infrastructure draws from FPGA modules, specialized oscilloscopes, and deterministic Ethernet switches. Single-source vulnerability in advanced node semiconductor fabrication threatens certification timeline commitments. Distribution runs through direct vendor relationships with OEM procurement teams and Tier-1 supplier engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors holding dual-standard accreditation as ISO 26262 and DO-178C complexity barriers eliminate generalist competitors.
For Market Incumbents: Hedge certification authority erosion by acquiring worst-case execution time analysis boutiques in Toulouse and Seattle before EASA-FAA harmonization completes. Deepen embedded-tooling integration into automotive ECU development workflows to lock out simulation-platform entrants. Priority lever: containerized test environment standardization. For New Entrants and Emerging Players: The mid-market gap between Vector Informatik's premium subscription tiers and open-source static analysis tools offers white-space for accredited compliance testing services targeting German Tier-2 automotive suppliers. Japan's domestic talent scarcity creates parallel entry opportunity for outsourced METI certification support. Go-to-market angle: outcome-based pricing tied to first-pass certification success. For Investors and Strategic Acquirers: EASA-FAA multicore harmonization announcement is the leading indicator that aerospace testing consolidation will accelerate within a five-to-ten year window. Target acquisition archetype: worst-case execution time analysis boutiques with existing CAST-32A project credentials. Signal to monitor: subscription revenue share crossing threshold at incumbent tool vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Standard Certification Investment | ISO 26262-DO-178C accreditation opens automotive-aerospace cross-selling at LDRA and Vector Informatik. |
| Containerized Test Environment Deployment | Kubernetes-orchestrated simulation clusters compress hardware-in-the-loop provisioning from weeks to hours for Continental. |
| Acquisition of WCET Analysis Specialist | Rapita Systems Ltd heritage in aerospace worst-case execution time anchors multicore processor validation authority. |
| Subscription Model Transition | Annual recurring revenue with embedded training credits displaces perpetual licensing among Germany's mid-cap automotive suppliers. |
| Digital Twin Platform Integration | Virtual validation environments reduce physical prototype dependency for Airbus avionics software pipelines. |
Study Parameters
Independent corroboration across FAA certification documentation, EASA harmonization guidance, and SAMR GB standard filings underwrites the qualitative findings on regulatory divergence. Primary interviews with automotive functional safety managers, aerospace software verification leads, medical device regulatory affairs officers, and industrial automation certification engineers combined with secondary validation from FDA 510(k) submissions, ISO standard revision drafts, and embedded toolchain vendor SEC disclosures. Bottom-up triangulation against top-down market sizing from certification expenditure tracking anchored volume estimates.
Rate-of-change decomposition across the analysis window separated baseline certification demand from incremental autonomous vehicle and software-as-a-medical-device validation requirements. Segmentation dimensions modeled include certification standard, testing methodology, end-user type, and geographic regulatory cluster. CAGRs derived from regression against historical certification expenditure patterns and projected OEM R&D disclosure trends. Forecast inputs incorporated digital twin adoption curves and multicore processor harmonization timeline assumptions.
Inputs from FAA, EASA, and SAMR regulatory filings were available through the study window; gaps in proprietary Tier-1 supplier validation budget disclosures introduce uncertainty bands around automotive segment projections. Forecasts reflect documented assumptions on autonomous vehicle deployment timelines and harmonization completion. Practitioners should monitor EASA-FAA joint guidance publication and FDA software-as-a-medical-device enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wind and Solar Hybrid Street Light Market
Others
Smart Home Technologies Market
Others
Europe Electric Forklift Market
Others
Education and Learning Analytics Market
Others
Global Retail Media Networks Market
Others
Durian Fruit Market
Others
Mainframe Market
Others
Global Simulation in Healthcare Market
Others
Handheld Mobile Computers Market
Others
Moonstone Market
Others
Green Technologies Market
Others
Architectural Fabrics Market
Others
Global Crowdsourced Testing Market
Others
Thailand Travel Retail Market
Others
Europe Military 4D Printing Market
Others
Fresh Apples Market