
 Caralluma Extract Market | 2026-2036
Caralluma Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Caralluma Extract Market Analytics
Ingredient supply revenue is fragmenting between raw extract trading and finished-formulation branding. Sabinsa Corporation anchors its position through backward integration into cultivated Caralluma biomass in India. NOW Foods competes via certified-organic capsule lines stocked across US health food stores. Glanbia Nutritionals leverages its flavor-masked powder platforms to supply co-manufacturers in the sports nutrition channel.
Caralluma extract comprises dried succulent flesh standardized for pregnane glycosides, typically processed through solvent extraction and spray-drying to preserve bioactive integrity for satiety signaling applications. Powder formats dominate bulk ingredient procurement by dietary supplement manufacturers seeking blending flexibility, while liquid extracts gain traction in functional beverage trials. Capsule segments sustain premium shelf positioning in pharmacies and online subscription models. Vegan and organic formulation claims now determine access to European retail listings governed by EFSA novel food assessments.
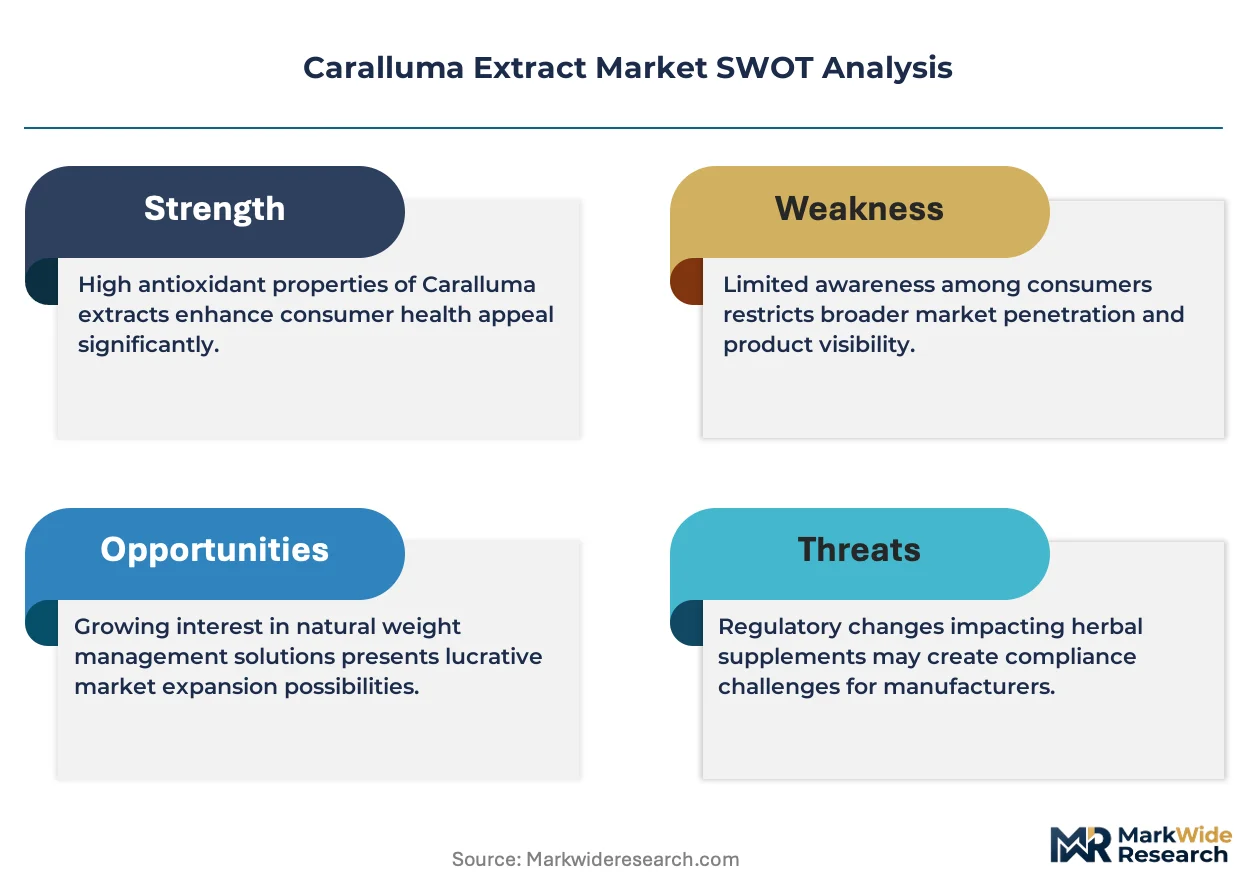
FDA dietary supplement GMPs and FTC substantiation rules govern US market entry, while India's CDSCO and FSSAI regulate export-grade extract certification for botanical APIs. EFSA health claim rejections on appetite modulation have redirected European marketing toward general wellness positioning. Stakeholders must monitor evolving novel food classifications and adapt clinical substantiation portfolios before committing to regional scale-up decisions.
Market Dynamics
Ingredient supply revenue is fragmenting between raw extract trading and finished-formulation branding, with backward integration into cultivated Caralluma biomass in India determining cost structures and quality consistency for dietary supplement manufacturers.
Growth Catalysts
- India's PLI scheme for herbal extracts:The production-linked incentive program accelerates domestic processing capacity for export-grade botanical APIs. CDSCO and FSSAI certification protocols streamline regulatory compliance for international shipment.
- Direct-to-consumer channel expansion:North American e-commerce platforms and European pharmacy networks drive formulation demand for appetite-suppressing botanicals. Subscription models sustain recurring revenue for capsule segment positioning.
- EFSA novel food assessments:Vegan and organic certification requirements create premium access barriers that reward early compliance investment. Standardized pregnane glycoside testing protocols differentiate quality tiers.
Market Restraints
- Wild-harvested supply volatility:Rajasthan and Karnataka collection networks face climate-driven yield fluctuations. Cultivation transition timelines lag behind formulation demand expansion.
- Solvent extraction cost inflation:Food-grade ethanol and methanol procurement expenses compress margin structures for spray-drying operations. Energy-intensive drying stages amplify operational expenditure exposure.
- EFSA health claim rejections:Appetite modulation substantiation failures redirect European marketing toward general wellness positioning. Clinical trial investment requirements exceed mid-tier processor budgets.
Strategic Opportunities
- Functional beverage trials:Liquid extract formats gain traction in sports nutrition and ready-to-drink applications. Flavor-masked powder platforms enable co-manufacturer supply relationships.
- Certified-organic capsule lines:US health food store penetration rewards premium shelf positioning. Third-party organic certification unlocks pharmacy network listings in Germany and France.
- Backward integration into cultivated biomass:Controlled agricultural operations reduce wild-harvest dependency. Sabinsa Corporation's cultivation model demonstrates scalable quality standardization.
Industry Challenges
- Clinical substantiation portfolio gaps:Peer-reviewed satiety signaling studies require multi-year investment timelines. FTC substantiation rules demand rigorous documentation for US marketing claims.
- Formulation stability expertise:Pregnane glycoside preservation through processing stages requires specialized technical knowledge. Talent acquisition for phytochemistry roles competes with broader nutraceutical sector demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caralluma Extract Market |
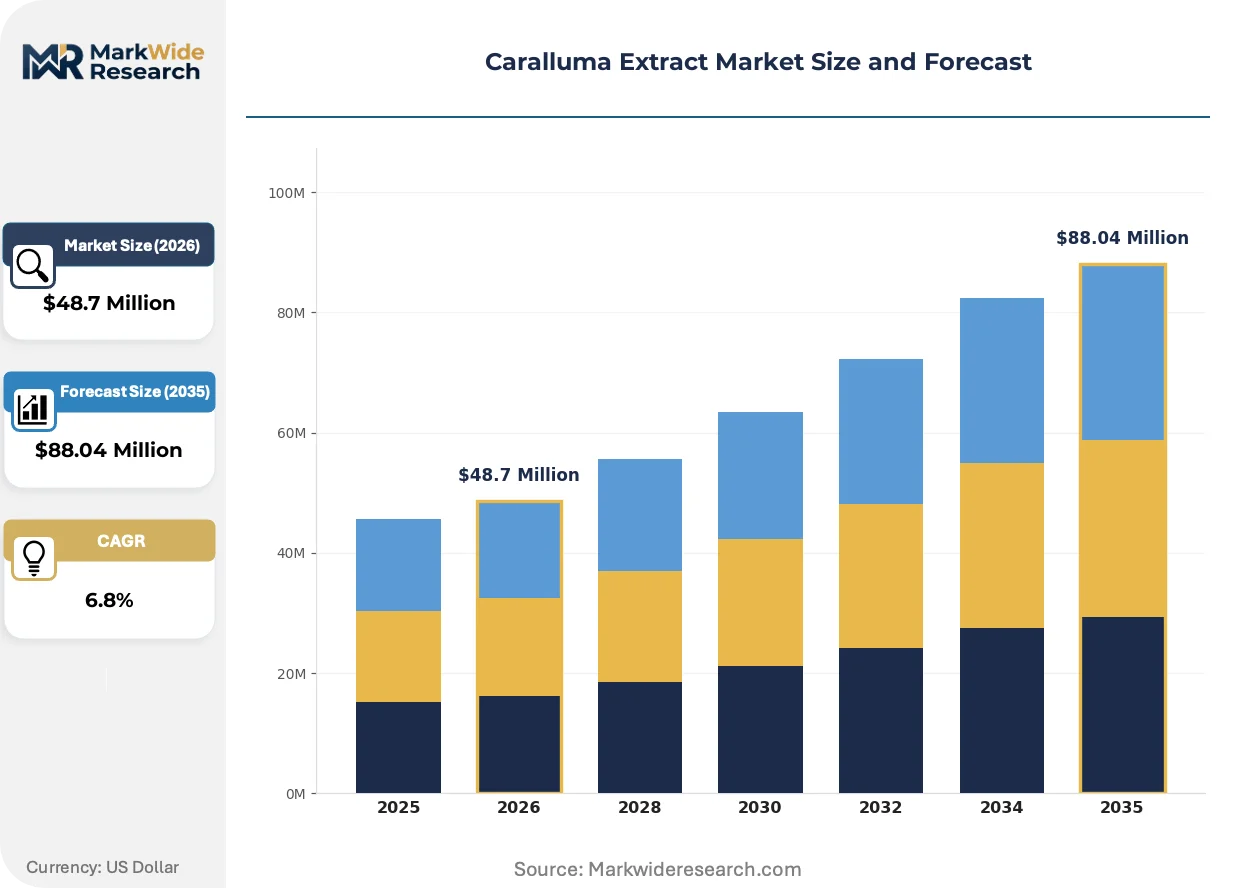
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid Extract, Granules End User: Healthcare Providers, Dietary Supplement Manufacturers, Fitness Enthusiasts, Retail Consumers Distribution Channel: Online Stores, Health Food Stores, Pharmacies, Supermarkets Formulation: Vegan, Organic, Non-GMO, Gluten-Free |
| Companies Covered | Glanbia Nutritionals, Sabinsa Corporation, NOW Foods, Herbalife Nutrition Ltd, Nature's Way Products, Arjuna Natural Extracts Ltd, Herbadiet, Solaray, SA Herbal Bioactives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caralluma Extract Market Evolving Landscape
Processing technology is virtualizing quality assurance workflows while regulatory frameworks tighten novel food classifications. Distribution channels fragment between bulk ingredient procurement and branded finished goods.
Spray-drying automation with inline HPLC monitoring is virtualizing batch release decisions. Dietary supplement manufacturers adopt real-time glycoside standardization to reduce laboratory testing bottlenecks. This compression of quality verification timelines enables just-in-time procurement from Indian extract processors.
EFSA novel food assessments now govern European retail access for Caralluma-derived ingredients. The regulatory friction redirects marketing investment toward wellness positioning rather than appetite suppression claims. German and French pharmacy networks prioritize suppliers with completed novel food dossiers.
Subscription-based capsule replenishment is displacing traditional retail replenishment cycles. Direct-to-consumer brands capture recurring revenue through automated shipment programs. This channel shift concentrates in North American urban markets with established health-conscious consumer bases.
Caralluma Extract Market Segmentation
Caralluma extract procurement patterns diverge sharply between bulk ingredient buyers seeking formulation flexibility and finished-product channels demanding certified positioning. Each segmentation dimension reveals distinct margin structures and regulatory compliance thresholds that determine supplier selection criteria.
Product Type:
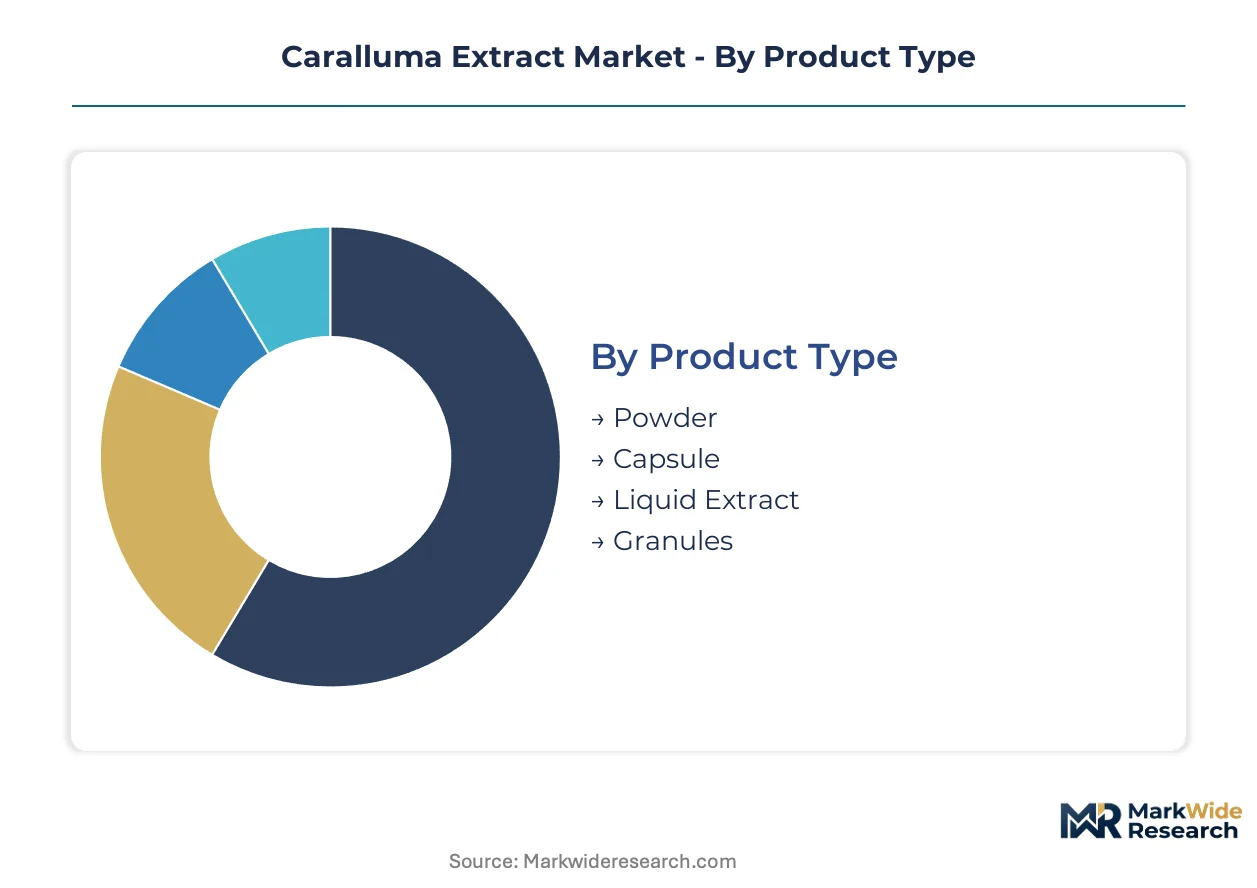
Spray-dried powders dominate procurement volumes from dietary supplement manufacturers, while liquid formats penetrate emerging functional beverage applications.
- Powder:Spray-dried extract standardized for pregnane glycosides offers blending flexibility for capsule and tablet manufacturers. Bulk procurement concentrates among US and German dietary supplement co-manufacturers seeking just-in-time inventory management.
- Capsule:Pre-filled gelatin and vegetable cellulose formats command premium shelf positioning in pharmacy networks and subscription direct-to-consumer models. German and French pharmacy listings require EFSA novel food dossier completion for sustained distribution access.
- Liquid Extract:Alcohol and glycerin-based tinctures serve functional beverage trials and sports nutrition co-manufacturing partnerships.
- Granules:Intermediate processing format enables controlled-release tablet manufacturing for sustained satiety signaling applications.
The dominant share belongs to Powder, while Capsule is closing the gap fastest.
End User:
Customer archetypes span institutional procurement with stringent quality documentation requirements and direct-to-consumer segments prioritizing convenience and certification claims.
- Dietary Supplement Manufacturers:Bulk extract buyers demand Certificate of Analysis documentation for pregnane glycoside standardization and heavy metal testing. CDSCO-certified Indian processors capture procurement contracts through FSSAI export-grade validation.
- Retail Consumers:Direct-to-consumer subscription models concentrate in North American urban markets with established health-conscious demographics. Automated replenishment programs displace traditional retail replenishment cycles for sustained recurring revenue capture.
- Healthcare Providers:Integrative medicine practitioners and naturopathic clinics prescribe standardized extracts with clinical substantiation portfolios.
- Fitness Enthusiasts:Sports nutrition channel demand concentrates in protein powder co-formulations and pre-workout supplement stacks.
Dietary Supplement Manufacturers retain procurement volume leadership, though Retail Consumers are expanding most quickly through channel digitization.
Distribution Channel:
Channel selection determines margin capture, with direct-to-consumer platforms rewarding branding investment and pharmacy networks enforcing certification barriers.
- Online Stores:E-commerce platforms enable subscription-based replenishment models with automated shipment programs. North American direct-to-consumer brands leverage digital marketing for customer acquisition in appetite management categories.
- Pharmacies:German and French pharmacy networks require completed EFSA novel food dossiers and third-party organic certification for shelf access. Premium positioning rewards early regulatory compliance investment.
- Health Food Stores:US regional chains and independent retailers stock certified-organic capsule lines with third-party verification seals.
- Supermarkets:Mass retail placement remains limited due to appetite suppression claim restrictions and novel food classification uncertainties.
Online Stores command transaction volume leadership, while Pharmacies are gaining share fastest through regulatory differentiation.
Formulation:
Certification claims now function as market access prerequisites rather than premium differentiators, particularly for European retail penetration.
- Vegan:Plant-derived capsule excipients and processing aids satisfy European consumer preference and EFSA novel food assessment alignment. German pharmacy procurement specifications increasingly exclude animal-derived ingredients.
- Organic:USDA Organic and EU Organic certification unlocks health food store penetration in the US and pharmacy network listings in Germany and France. Cultivated biomass sourcing from Rajasthan and Karnataka operations enables supply chain traceability documentation.
- Non-GMO:Genetic modification-free verification addresses consumer skepticism in North American markets with established clean-label purchasing patterns.
- Gluten-Free:Allergen exclusion certification expands addressable market among celiac and gluten-sensitive consumer segments.
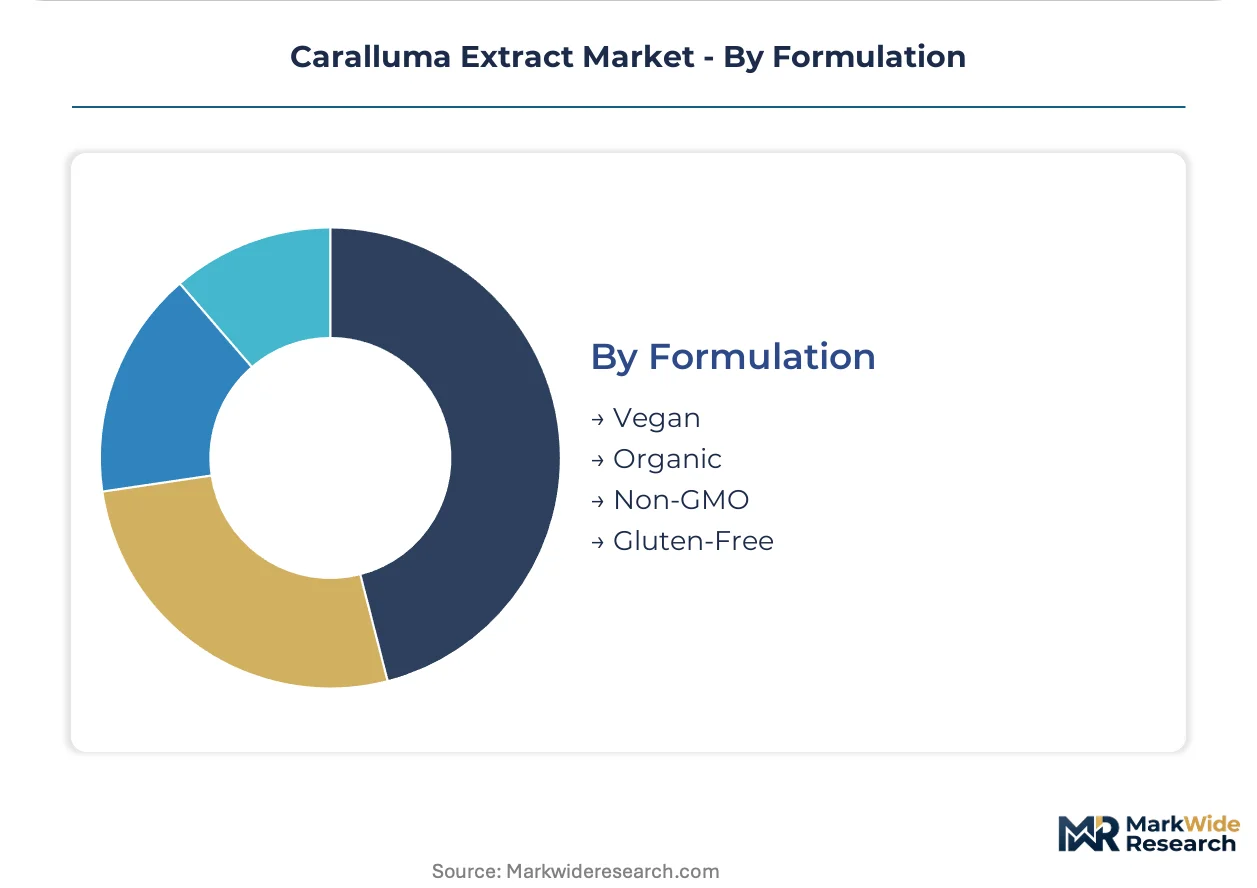
Organic claims dominate procurement specifications, while Vegan certification is climbing the fastest as European retail access tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies. North American direct-to-consumer buyers absorb premium positioning for certified-organic capsules. European pharmacy procurement enforces strict novel food compliance costs that compress mid-tier margins.
United States
Direct-to-consumer subscription models concentrate demand in urban health-conscious demographics. FDA dietary supplement GMPs and FTC substantiation rules govern market entry documentation. Los Angeles and New York metro areas anchor digital-native brand headquarters with automated replenishment logistics.
Germany
Pharmacy network procurement specifications prioritize EFSA novel food dossier completion and third-party organic certification. The country's national pharmaceutical regulator enforces strict botanical API import standards. Bavaria and North Rhine-Westphalia host distribution hubs for Central European supplement supply chains.
India
Export-grade extract processing capacity expands under the PLI scheme for herbal extracts and nutraceuticals. CDSCO and FSSAI certification protocols streamline regulatory compliance for international botanical API shipment. Rajasthan and Karnataka cultivation clusters transition from wild-harvest dependency to controlled agricultural operations.
France
Pharmacy network listings reward early EFSA novel food compliance investment with premium shelf positioning. The country's national pharmaceutical regulator maintains stringent novel food assessment timelines. Paris and Lyon metropolitan areas concentrate integrative medicine practitioner demand for standardized extracts.
United Kingdom
Health food store chains and independent retailers stock certified-organic capsule lines with third-party verification seals. The national food standards agency governs novel food classification for appetite-modulation positioning. London anchors direct-to-consumer brand European headquarters with fulfillment infrastructure.
Caralluma Extract Market Competitive Landscape
Capability concentration sits with cultivation-integrated extract processors; scale advantage sits with diversified nutraceutical platforms. The vendor base stratifies across three tiers: backward-integrated biomass cultivators, certified-organic finished-formulation brands, and flavor-masked powder platform suppliers. Dominant competitive moves include strategic partnerships with sports nutrition co-manufacturers and portfolio diversification into functional beverage ingredient supply.
Within the cultivation-integrated tier, Sabinsa Corporation anchors quality standardization through controlled agricultural operations in India. NOW Foods exemplifies the certified-organic finished-formulation archetype with health food store penetration across US regional chains. Glanbia Nutritionals occupies a position among diversified nutrition platform suppliers leveraging flavor-masked powder technologies.
| Leading Market Players |
|---|
| Glanbia Nutritionals |
| Sabinsa Corporation |
| NOW Foods |
| Herbalife Nutrition Ltd |
| Nature's Way Products |
| Arjuna Natural Extracts Ltd |
| Herbadiet |
| Solaray |
| SA Herbal Bioactives |
| Others |
Value Network & Pricing Analysis
Wild-harvested supply volatility in Rajasthan and Karnataka determines both margin compression thresholds and procurement network configuration for Caralluma extract stakeholders. Climate-driven yield fluctuations force buyers into multi-source qualification programs that stratify pricing tiers by certification grade and biomass origin.
Pricing Analysis
Subscription-based replenishment programs drive lifetime value capture for direct-to-consumer capsule brands. Three-tier pricing structure across premium organic-certified, standard FSSAI-validated, and economy wild-harvested grades separates pharmacy network listings from bulk ingredient procurement. Cost compression in spray-dried powder segments intensifies because energy-intensive drying stages amplify operational expenditure exposure. Dietary supplement manufacturers exhibit highest price sensitivity due to formulation flexibility requirements, while German pharmacy networks absorb premium positioning for EFSA-compliant dossiers.
Supply Chain Analysis
Tariff exposure between India and European Union member states dominates supply chain risk assessment for export-grade botanical APIs. Raw material flows draw from Rajasthan cultivation clusters, Karnataka processing facilities, and US dietary supplement co-manufacturers. Food-grade ethanol and methanol procurement dependencies, combined with pregnane glycoside standardization reagents, create input cost volatility. Single-source vulnerability concentrates in CDSCO-certified extract processors with limited FSSAI export-grade validation. Distribution runs through Indian export terminals, German pharmaceutical distribution hubs, and North American direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional beverage ingredient supply platforms are consolidating around flavor-masked powder technologies, creating interoperability standards that favor early co-manufacturer partnerships over pure extract trading models.
For Market Incumbents: Harden quality standardization through backward integration into cultivated biomass operations in Rajasthan and Karnataka, reducing wild-harvest dependency that threatens margin stability. Lock in pharmacy network shelf access by completing EFSA novel food dossiers before regulatory assessment timelines tighten, defending against emerging entrants with faster compliance investment cycles. For New Entrants and Emerging Players: Build out liquid extract capabilities for sports nutrition co-manufacturing partnerships, the most penetrable segment for unbranded ingredient suppliers seeking volume scale. Target US health food store chains with certified-organic capsule lines, leveraging third-party verification seals as faster market entry credentials than clinical substantiation portfolios. For Investors and Strategic Acquirers: EFSA novel food approval milestones reshape the acquisition landscape toward processors with completed dossiers and cultivated biomass supply chains. Long-term viability centers on platform economics where co-manufacturer relationships generate recurring revenue streams. Prioritize acquisition targets with spray-drying automation and inline HPLC monitoring capabilities. Monitor India PLI scheme disbursement velocity as inflection indicator for domestic processing capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Biomass | Sabinsa Corporation's Rajasthan operations demonstrate scalable quality standardization reducing wild-harvest dependency. |
| EFSA Novel Food Dossier Completion | German and French pharmacy networks prioritize suppliers with completed assessments for sustained distribution access. |
| Flavor-Masked Powder Platform Development | Glanbia Nutritionals leverages taste-masking technologies to supply sports nutrition co-manufacturers with formulation-ready ingredients. |
| Direct-to-Consumer Subscription Launch | Automated replenishment programs in North American urban markets displace traditional retail replenishment cycles. |
| Spray-Drying Automation Investment | Inline HPLC monitoring virtualizes batch release decisions, compressing quality verification timelines for just-in-time procurement. |
Research Methodology
Desk research of CDSCO export certification databases, FSSAI regulatory filings, and EFSA novel food assessment precedents preceded structured interviews with extract processing plant managers, dietary supplement formulation directors, pharmacy network procurement leads, and sports nutrition co-manufacturing partners. Secondary validation drew from Indian PLI scheme disbursement records, customs trade data for botanical API shipments, and SEC filings of publicly traded nutraceutical platforms. Bottom-up procurement volume estimates triangulated against top-down market sizing from ingredient supplier revenue disclosures.
Assumptions held fixed include prevailing EFSA novel food classification timelines, India PLI scheme continuation, and FDA dietary supplement GMP enforcement intensity; variables tested across scenarios included wild-harvest yield volatility, solvent extraction cost inflation, and direct-to-consumer channel share capture. Segmentation modeling spanned product format, end-user archetype, distribution channel, and certification claim dimensions. CAGRs derived from regression analysis of historical procurement volume patterns against macroeconomic health expenditure indicators and consumer wellness trend indices.
The forecast holds incumbent behavior within observed patterns; aggressive cultivation investment by mid-tier processors or accelerated EFSA approval timelines would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
China Food Colorants Market