
 Flavor Oil Market | 2026-2036
Flavor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Oil Market Analysis
Modular flavor dosing systems and single-serve sachet configurations are shifting how food manufacturers evaluate supplier partnerships. Givaudan leverages its integrated botanical extraction network to secure raw material traceability for natural flavor oils. International Flavors & Fragrances Inc. anchors its competitive stance through sustained R&D spending on biotech-derived aroma molecules. Symrise differentiates by controlling specialized citrus and spice oil supply chains across multiple growing regions.
Flavor oils are concentrated lipid-soluble aromatic extracts, typically comprising volatile terpenes, esters, and aldehydes at purity grades between 80% and 99%, manufactured through steam distillation, cold pressing, or solvent extraction for incorporation into finished food and beverage matrices. Natural flavor oils command premium positioning as clean-label reformulation accelerates across beverage and confectionery applications, while synthetic variants retain cost-sensitive volume in bakery and dairy segments. Organic-certified oils represent the fastest-growing margin pool, though emulsified formats are gaining traction in water-based beverage systems where oil solubility limits direct incorporation.
EFSA and REACH in Europe enforce strict contaminant thresholds and labeling disclosures that elevate compliance costs for synthetic flavor oil imports. The FDA in the United States maintains GRAS self-determination pathways, though FSMA traceability rules now extend to flavor ingredient lots. India's FSSAI has tightened additive approval schedules, creating entry barriers for unregistered international suppliers. Stakeholders must monitor evolving naturalness definitions across jurisdictions, as regulatory divergence between EU precautionary standards and US notification-based systems will increasingly dictate formulation strategy and supplier qualification protocols.
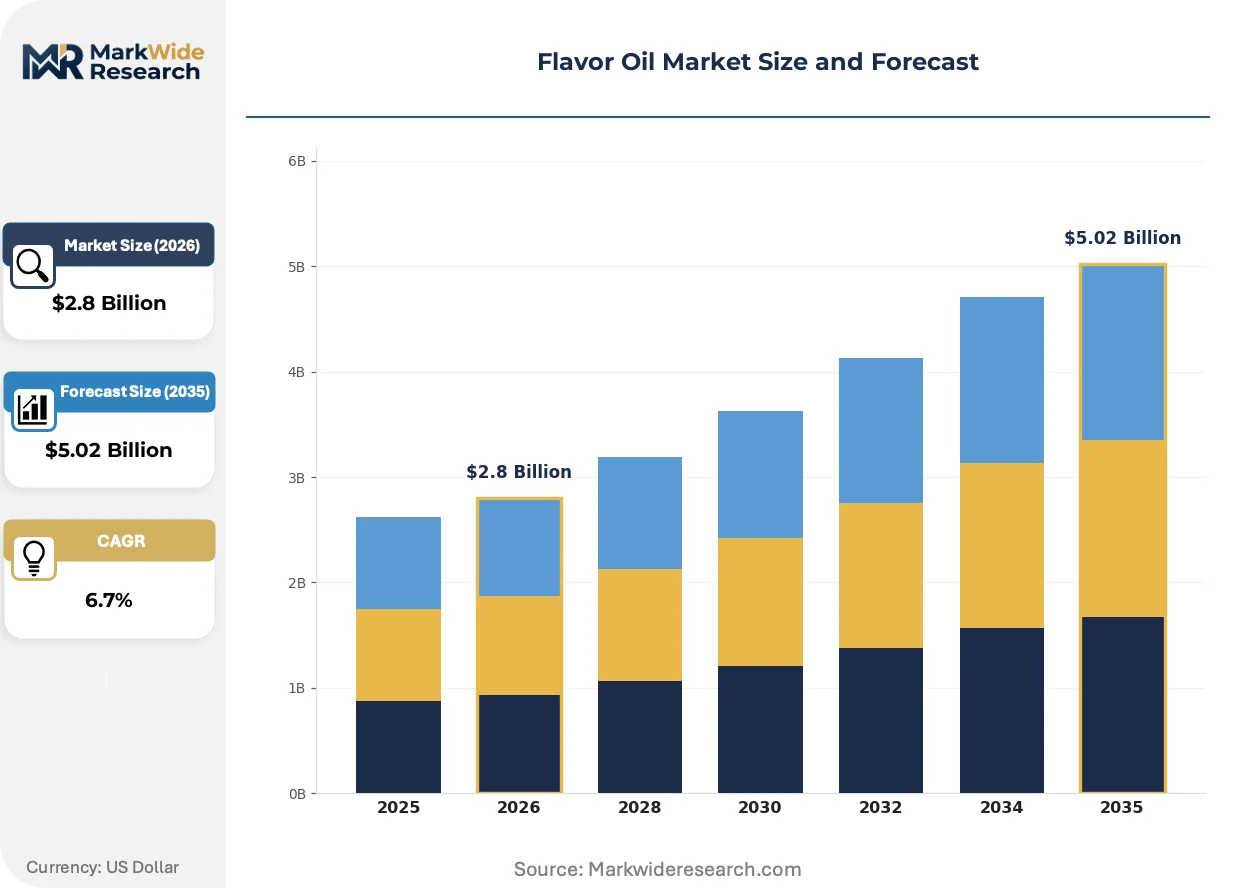
Market Dynamics
Clean-label reformulation mandates across beverage and confectionery sectors are forcing manufacturers to replace synthetic flavor carriers with natural lipid-soluble extracts, compressing formulation cycles and elevating supplier qualification thresholds.
Growth Catalysts
- EU REACH contaminant thresholds:Beverage manufacturers accelerate natural flavor oil adoption to preempt registration bottlenecks for synthetic alternatives entering European ports.
- Functional drink portfolios:Energy and wellness beverage producers expand botanical extract procurement to differentiate premium positioning in saturated retail aisles.
- India PLI scheme for food processing:International suppliers establish local extraction facilities to capture incentives tied to domestic value-add requirements.
Market Restraints
- Citrus oil supply volatility:Weather-induced crop failures in Mediterranean and Floridian growing regions destabilize terpene feedstock pricing for natural variants.
- Steam distillation energy intensity:Natural extraction methods carry 40-60% higher thermal input costs versus solvent-based synthetic production.
- FSSAI additive approval delays:Unregistered international suppliers face 18-24 month queue times for novel flavor molecule clearances in India.
Strategic Opportunities
- Emulsified water-dispersible formats:Oil-in-water nanoemulsion technologies unlock beverage applications previously blocked by lipid solubility constraints.
- Organic certification tier:Premium positioning in European retail chains commands 25-35% price multiples over conventional natural grades.
- Modular dosing systems:Single-serve sachet configurations enable foodservice operators to reduce overage waste and simplify inventory management.
Industry Challenges
- Botanical traceability documentation:FSMA lot-tracking requirements demand upstream digitization of farm-to-extractor records across fragmented agricultural supply bases.
- Biotech aroma molecule IP:Patent thickets around engineered terpene pathways complicate freedom-to-operate assessments for novel natural-identical compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Oil Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Emulsified Application: Beverages, Confectionery, Dairy, Bakery End User: Food Manufacturers, Beverage Companies, Retailers, Restaurants Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Symrise, Firmenich SA, Sensient Technologies Corporation, Robertet SA, Mane, DSM, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Oil Market Emerging Trajectories
Extraction technology convergence and regulatory divergence are compressing product development timelines while fragmenting supplier ecosystems across geographic compliance zones.
Supercritical CO2 extraction is electrifying natural flavor oil production economics by eliminating thermal degradation of heat-sensitive terpenes. Premium chocolate and confectionery manufacturers in Switzerland and Belgium are converting cold-pressing capacity to supercritical systems within 24-month capital cycles. This technology is electrifying competitive positioning for mid-tier extractors seeking organic certification without yield penalties.
EFSA naturalness definition revisions are narrowing acceptable processing aids for extracts labeled as natural. The 2024 guidance disqualifies several common solvent recovery methods previously grandfathered under older flavoring substance evaluations. European beverage reformulation teams are rebuilding supplier specifications to exclude enzymatically modified intermediates that fall outside the revised naturalness boundary.
Direct procurement from certified organic cooperatives is consolidating buyer power among mid-size flavor houses. Regional extractors in Madagascar, Indonesia, and Sri Lanka are disintermediating traditional trading houses through blockchain-verified origin documentation. This pattern concentrates most visibly in vanilla and spice oil categories where geographic indication value supports price transparency investments.
Flavor Oil Market Segmentation
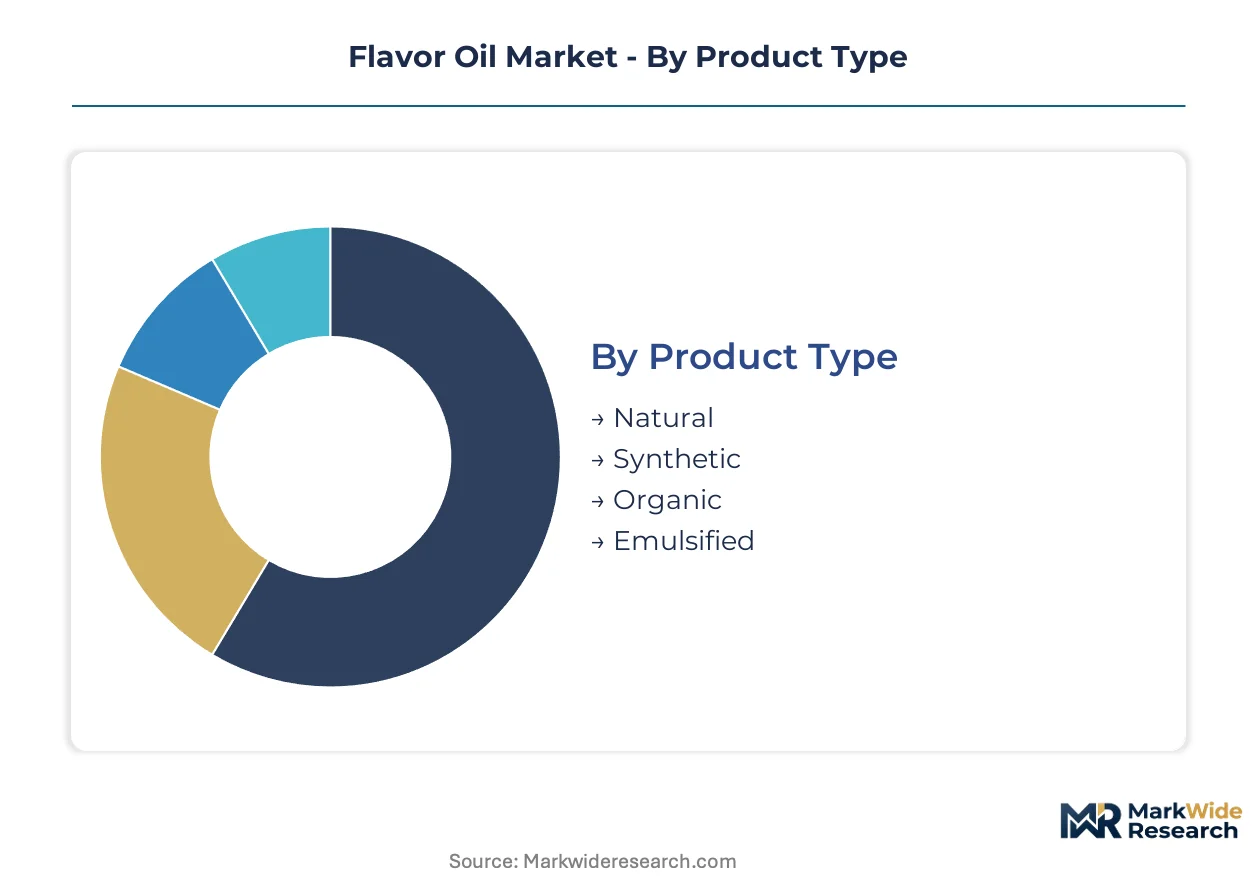
Flavor oil procurement decisions hinge on certification requirements that vary sharply across product grades and end-use applications. Regulatory alignment between supplier capabilities and buyer compliance obligations determines contract viability more than price alone.
Product Type:
Natural and organic variants carry the heaviest certification burden, requiring EFSA naturalness validation, USDA organic accreditation, or India Organic certification depending on destination market. Synthetic and emulsified formats face lighter documentation loads but must still satisfy contaminant thresholds under REACH and FDA GRAS self-determination protocols.
- Natural:Steam-distilled or cold-pressed extracts containing volatile terpenes, esters, and aldehydes at 80-99% purity. Beverage manufacturers in Germany and Switzerland prioritize these for clean-label reformulation under EFSA's evolving naturalness definitions.
- Organic:Certified extracts from agricultural inputs meeting USDA, EU 2018/848, or India Organic standards. Premium chocolate manufacturers in Belgium and Switzerland pay 25-35% multiples for certified grades that unlock retail shelf placement in European organic chains.
- Synthetic:Solvent-derived aroma molecules engineered to replicate natural terpene profiles. Cost-sensitive bakery and dairy processors in the United States rely on these for margin protection in commodity segments.
- Emulsified:Oil-in-water nanoemulsion formats enabling dispersion in water-based beverage matrices. Energy drink producers in India and the United States are expanding procurement as lipid solubility constraints block direct oil incorporation.
Natural sits at the top of the volume ranking, with Organic climbing the fastest.
Application:
Application segments diverge by thermal stability requirements and dosage precision, with beverage systems demanding the most sophisticated delivery formats.
- Beverages:Functional and wellness drink portfolios require heat-stable, water-dispersible flavor systems. Manufacturers in India and the United States are retrofitting production lines for nanoemulsion compatibility.
- Confectionery:Premium chocolate and hard candy applications depend on lipid-soluble extracts with precise melting point control. Swiss and Belgian processors dominate procurement of supercritical CO2-extracted grades.
- Dairy:Flavor oils must withstand pasteurization temperatures without terpene degradation. Ice cream and flavored milk producers in the United States specify high-flash-point variants.
- Bakery:Oven-stable formulations resist volatilization during high-temperature baking. Commercial bakeries prioritize cost-optimized synthetic carriers for consistent batch performance.
Beverages command the steepest expansion trajectory as functional drink portfolios proliferate across retail channels.
End User:
End user categories separate by procurement scale, technical specification depth, and direct versus distributor purchasing patterns.
- Food Manufacturers:Large-scale processors with captive formulation teams and direct supplier relationships. Confectionery and bakery conglomerates in Switzerland, Belgium, and the United States negotiate multi-year extraction contracts.
- Beverage Companies:Specialized buyers prioritizing rapid flavor innovation cycles and modular dosing compatibility. Energy drink specialists in India and the United States are consolidating supplier bases around integrated botanical extraction networks.
- Retailers:Private-label brand owners sourcing finished flavor systems through co-manufacturing arrangements. European organic chains specify certified organic oils with blockchain-verified origin documentation.
- Restaurants:Foodservice operators adopting single-serve sachet configurations to reduce overage waste. Regional chains in India are piloting modular dosing systems for standardized beverage preparation.
Food Manufacturers anchor procurement volume, with Beverage Companies gaining share fastest through premium portfolio expansion.
Distribution Channel:
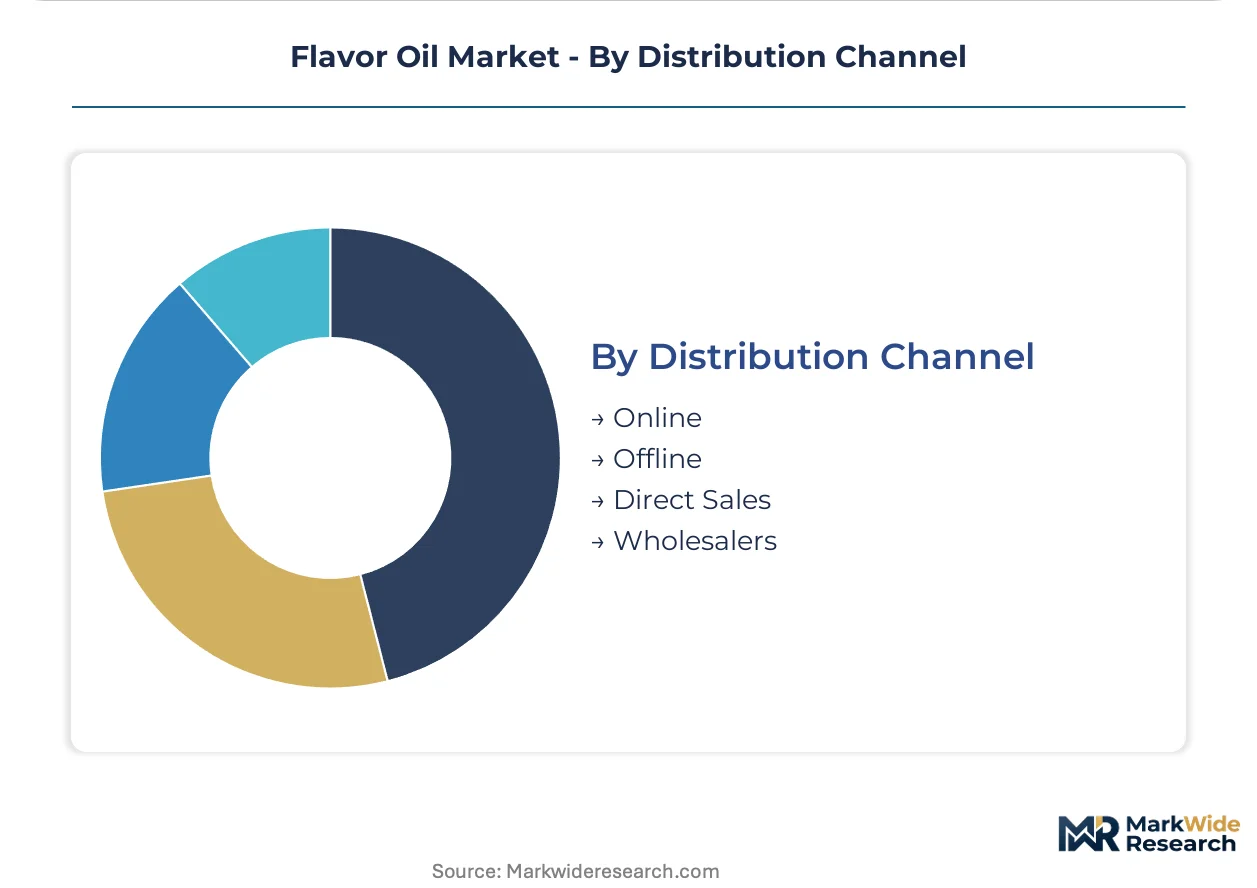
Channel selection reflects order size, technical service requirements, and geographic proximity to extraction facilities.
- Direct Sales:Large-volume contracts with dedicated technical account management and custom formulation support. Major flavor houses maintain direct relationships with multinational beverage and confectionery processors.
- Wholesalers:Regional distributors stocking standard grades for mid-tier food manufacturers. Indian and United States wholesale networks carry inventory for rapid replenishment of bakery and dairy processors.
- Online:E-procurement platforms serving small-batch buyers and specialty food startups. Certified organic cooperatives in Madagascar, Indonesia, and Sri Lanka are disintermediating traditional trading houses through blockchain-enabled direct sales.
- Offline:Traditional broker and agent networks handling spot purchases and specification-matching services. Regional extractors rely on offline channels for relationship-based sales in fragmented agricultural supply bases.
Direct Sales dominates value concentration, with Online expanding most quickly as traceability technology enables disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flavor oil industry traces its modern scaling to nineteenth-century steam distillation advances in Grasse, France, where perfumery techniques migrated into food-grade extraction. Contemporary demand patterns reflect this European heritage while dispersing across multiple regulatory jurisdictions with distinct compliance architectures.
United States
Energy drink manufacturers in Austin and Los Angeles drive procurement of emulsified flavor formats for functional beverage portfolios. FDA GRAS self-determination pathways allow rapid novel molecule introductions, though FSMA lot-tracking rules now mandate upstream digitization of botanical supply chains. Florida citrus belt extractors supply terpene feedstocks to confectionery processors in Chicago and Pennsylvania.
Germany
Beverage reformulation teams in Munich and Hamburg accelerate natural flavor oil adoption to preempt REACH registration bottlenecks for synthetic alternatives. EFSA contaminant thresholds and evolving naturalness definitions compress supplier qualification timelines. Supercritical CO2 extraction facilities in Bavaria serve premium chocolate manufacturers in Switzerland and Belgium through cross-border supply arrangements.
India
Domestic food processing expansion under the PLI scheme attracts international suppliers establishing local extraction facilities in Maharashtra and Gujarat. FSSAI-mandated labeling norms and additive approval queues create 18-24 month entry barriers for unregistered imports. Mumbai-based beverage companies pilot modular dosing systems for standardized foodservice preparation.
Switzerland
Premium chocolate manufacturers in Zurich and Vevey dominate procurement of certified organic grades commanding 25-35% price multiples over conventional natural variants. Swissmedic-aligned quality protocols exceed baseline EU requirements, filtering supplier pools to integrated botanical extraction networks. Basel-area flavor houses maintain direct technical account relationships with multinational confectionery processors.
Indonesia
Spice oil extractors in Java and Sumatra disintermediate traditional trading houses through blockchain-verified origin documentation for vanilla and clove derivatives. Direct procurement partnerships with European organic retail chains consolidate buyer power among mid-tier flavor houses. Jakarta-based distributors serve rapid replenishment needs for regional bakery and dairy processors.
Flavor Oil Market Vendor Landscape
The competitive structure tilts toward integrated botanical extraction networks with captive raw material traceability systems. Tiered player configurations separate multinational flavor houses with dedicated R&D spending on biotech-derived aroma molecules from regional extractors controlling specialized citrus and spice oil supply chains. Dominant competitive moves include backward integration into agricultural sourcing and technology licensing for supercritical CO2 extraction capacity.
Among Swiss and French heritage houses, Givaudan and Firmenich SA exemplify the integrated extraction archetype with in-house botanical networks spanning multiple growing regions. International Flavors & Fragrances Inc. occupies a position representing sustained research investment in engineered terpene pathways. Symrise anchors the specialized supply chain tier through controlled citrus and spice oil procurement across Mediterranean and Asian origins.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Symrise |
| Firmenich SA |
| Sensient Technologies Corporation |
| Robertet SA |
| Mane |
| DSM |
| Cargill, Incorporated |
| Others |
Supply Flow & Price Mechanics
Steam distillation specialists in Grasse and Kannauj represent concentrated craft-labor pools whose wage differentials widen pricing spreads between artisanal natural grades and commodity synthetic tiers. European extraction facilities carry 40-60% higher thermal input costs than solvent-based operations in India, compressing margins on certified organic outputs while creating arbitrage windows for cross-border procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic oils from conventional natural grades and synthetic variants. Quality grade and certification level—USDA Organic, EU 2018/848, or India Organic—drive price differentiation, with European retail chains commanding 25-35% multiples for verified provenance. Cost compression in synthetic tiers is intensifying because energy-intensive natural extraction methods face feedstock volatility. Commercial bakeries in the United States exhibit highest price sensitivity, while Swiss chocolate manufacturers show lowest elasticity for certified organic inputs.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai anchor hub-and-spoke patterns for flavor oil logistics. Supply concentrates in India, Indonesia, and Madagascar for spice and vanilla derivatives, with Mediterranean citrus belts feeding terpene feedstocks. Raw material dependencies rest on citrus peel biomass, clove and vanilla orchid harvests, and specialty mint cultivars. Single-source vulnerability in Madagascar vanilla exposes buyers to cyclone-induced crop failures. Distribution runs through direct sales channels for multinational flavor houses, with blockchain-enabled platforms disintermediating traditional trading structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor oil procurement functions as a geographic-arbitrage play where India's PLI scheme for food processing offers 18-24 month cost advantages against REACH compliance burdens in Europe.
For Market Incumbents: Anchor competitive position through backward integration into certified organic cooperatives in Madagascar and Sri Lanka. Biotech-derived aroma molecule patent thickets threaten freedom-to-operate for novel natural-identical compounds. Incumbents should deepen captive supply of supercritical CO2 extraction capacity to defend margin position against mid-tier disintermediators. For New Entrants and Emerging Players: Emulsified water-dispersible nanoemulsion technologies offer entry into beverage applications previously blocked by lipid solubility constraints. India's FSSAI-mandated labeling norms create white-space for domestic extraction facilities serving energy drink manufacturers. New entrants should pursue direct procurement partnerships with regional extractors in Indonesia and Sri Lanka, leveraging blockchain-verified origin documentation as go-to-market differentiation. For Investors and Strategic Acquirers: Beverage companies are the most active acquirer in this space, consolidating supplier bases around integrated botanical extraction networks. Long-term viability centers on traceability infrastructure and regulatory compliance capabilities rather than commodity extraction assets. Investors should monitor EFSA naturalness definition revisions as inflection indicators for synthetic-to-natural substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cooperatives | Givaudan's botanical extraction network secures raw material traceability for EFSA compliance. |
| Supercritical CO2 Capacity Expansion | Swiss and Belgian confectionery processors convert cold-pressing facilities to eliminate thermal degradation. |
| Blockchain-Verified Origin Documentation | Madagascar and Sri Lankan extractors disintermediate traditional trading houses through direct sales platforms. |
| Emulsified Format R&D Investment | Energy drink producers in India and the United States retrofit lines for nanoemulsion compatibility. |
| FSSAI Registration and Local Extraction | International suppliers establish Maharashtra facilities to bypass 18-24 month additive approval queues. |
Methodological Framework
Direct dialogue with extraction facility managers, beverage formulation chemists, organic certification auditors, and FSSAI regulatory consultants grounded qualitative insights. Secondary validation drew from EFSA flavoring substance evaluations, REACH registration databases, India PLI scheme disclosures, and customs trade records for citrus and spice oil categories. Bottom-up and top-down triangulation cross-checked procurement volume estimates against extraction capacity utilization rates.
Bottom-up modeling anchored volume projections in segment-level consumption patterns across beverages, confectionery, dairy, and bakery applications. Segmentation dimensions included product type certification tier, application thermal stability requirements, end-user procurement scale, and distribution channel technical service intensity. CAGRs were derived from trend extrapolation of natural versus synthetic substitution rates, adjusted for regulatory divergence between EU precautionary standards and US notification-based systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA naturalness definition revisions and citrus belt climate volatility. Forecasts reflect documented assumptions around PLI scheme incentive continuity and REACH enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Water Flavoring Drop Market