
 De Oiled Lecithin Market | 2026-2036
De Oiled Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
De Oiled Lecithin Market Intelligence
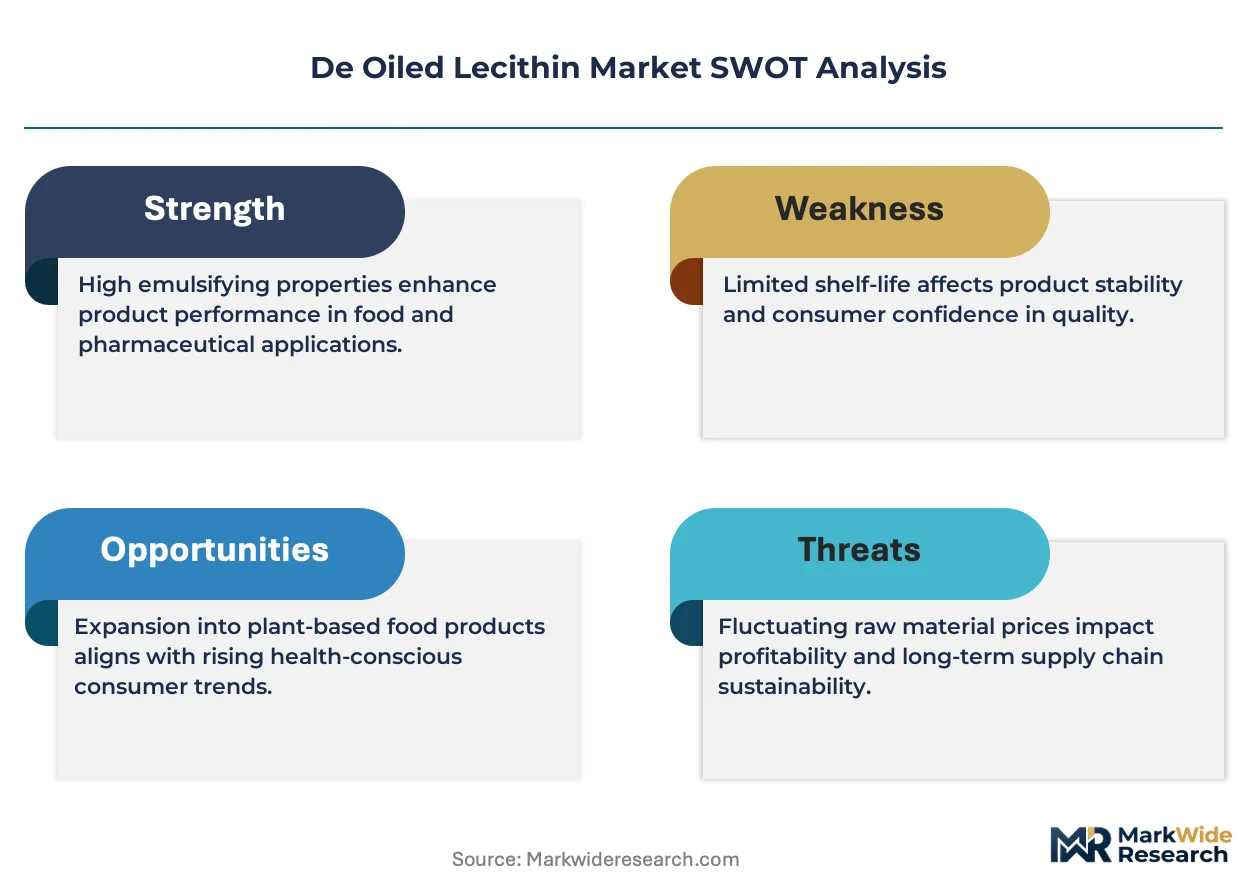
Traceability and non-GMO certification services are expanding the value proposition beyond the raw material itself. Global food producers increasingly require documented proof of origin and processing standards for their ingredients. Cargill Incorporated leverages its extensive global supply chain to meet this demand for certified products. Archer-Daniels-Midland Company specializes in providing a wide range of lecithin grades tailored to specific food and pharmaceutical applications. Bunge Limited competes on its large-scale processing capabilities and integrated logistical network to supply major industrial clients.
De-oiled lecithin is a purified phospholipid concentrate derived from sources like soy, sunflower, or rapeseed after the oil fraction has been removed. This process yields a product with a higher concentration of phospholipids, typically above 95%, enhancing its emulsifying and stabilizing properties. Its primary industrial purpose is to improve texture, shelf-life, and homogeneity in food, pharmaceutical, and cosmetic products. Powder and granulated forms are gaining share over traditional liquid lecithin due to superior handling, dosing accuracy, and stability. The food & beverage end-use industry, driven by demand for clean-label and non-GMO forms, represents the largest segment.
Regulatory frameworks significantly influence market access and product formulation. In the United States, the FDA classifies lecithin as Generally Recognized as Safe (GRAS) for food use, facilitating its broad application. The European Union regulates its use as a food additive under the designation E322, with specific purity criteria. In China, GB standards dictate the quality and safety requirements for lecithin used in food products. Navigating the varied global standards for allergen labeling, particularly for soy-based lecithin, remains a critical consideration for manufacturers.
Market Dynamics
The fundamental market dynamic is the growing consumer-led demand for non-GMO and organic food ingredients. This pressure for clean labels and transparent sourcing directly influences raw material selection, processing technology investment, and the value placed on certified supply chains for de-oiled lecithin.
Growth Catalysts
- Clean Label Formulations:The food and beverage industry's move towards natural, recognizable ingredients boosts demand for de-oiled lecithin as a preferred emulsifier over synthetic alternatives, particularly in bakery and confectionery products.
- Regulatory Acceptance:Broad classification as Generally Recognized as Safe (GRAS) by the US FDA and approval as E322 in the European Union provides a clear pathway for its use in a vast range of food products globally.
- Powder Form Factor:The increasing preference for powdered and granulated lecithin over liquid forms improves handling, dosing precision, and shelf stability, expanding its applicability in automated industrial food production lines.
Market Restraints
- Input Price Volatility:The market is subject to price fluctuations of key raw materials like non-GMO soybeans and sunflower seeds, which are influenced by weather, agricultural policies, and geopolitical events.
- Allergen Concerns:Soy-based lecithin requires strict allergen labeling, prompting some manufacturers in sensitive categories like infant formula to seek alternative sources like sunflower, which have a less developed supply chain.
- Substitution by Synthetics:In highly price-sensitive applications or regions with less stringent clean-label demands, synthetic emulsifiers like mono- and diglycerides can present a lower-cost alternative, capping price ceilings.
Strategic Opportunities
- Plant-Based Foods:The expansion of the plant-based meat and dairy alternative sector creates a significant opportunity, as de-oiled lecithin is highly effective at emulsifying fats and improving the texture of these products.
- Nutraceutical Applications:High-phosphatidylcholine (PC) concentrates from de-oiled lecithin are gaining traction in dietary supplements and functional foods for their purported cognitive and liver health benefits, opening a high-value segment.
- Novel Source Development:Investment in commercializing lecithin from alternative sources such as rapeseed or even algae can mitigate soy-related allergen issues and create new products with unique functional properties.
Industry Challenges
- Certification Complexity:Maintaining dual supply chains to ensure strict segregation between GMO and non-GMO sources is operationally complex and costly, creating a high barrier for smaller producers to meet premium market demands.
- Functional Consistency:Ensuring a consistent phospholipid profile and functional performance across different crop years and geographic sources remains a technical challenge for suppliers and a quality control concern for buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | De Oiled Lecithin Market |
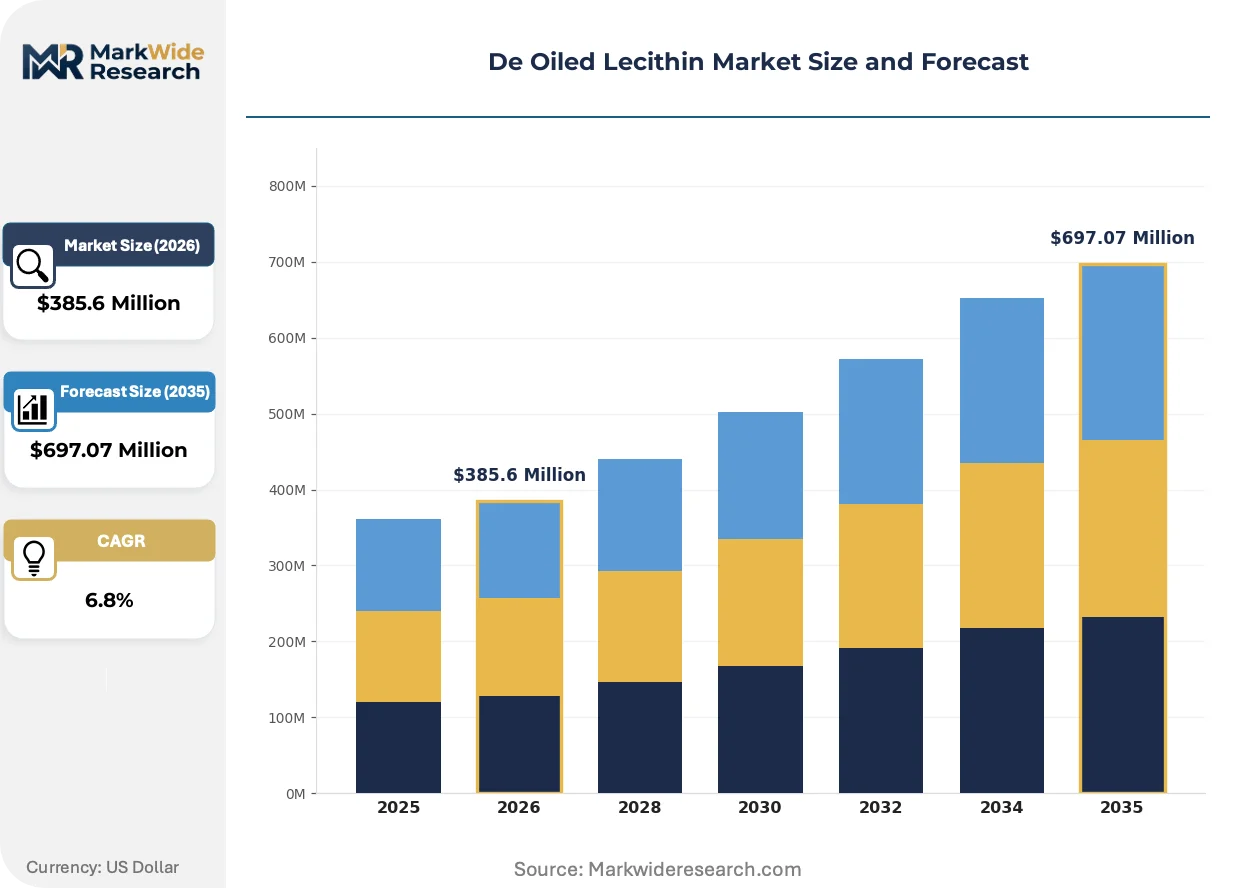
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Lecithin, Powder Lecithin, Granulated Lecithin, Emulsifier Lecithin End Use Industry: Food & Beverage, Pharmaceuticals, Nutraceuticals, Animal Feed Application: Baking, Dairy, Confectionery, Cosmetics Form: Organic, Non-GMO, Conventional, Others |
| Companies Covered | Cargill Incorporated, Archer-Daniels-Midland Company, Bunge Limited, American Lecithin Company, Sonic Biochem Extraction Pvt Ltd, Stern-Wywiol Gruppe, IMCD Group B.V., Avril Group, Avi Agri Business Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
De Oiled Lecithin Market Strategic Shifts & Innovations
Technological advancements in purification and the rising importance of digital traceability are defining the innovation landscape. These trends are moving de-oiled lecithin from a simple commodity ingredient to a highly functional, value-added component with documented provenance.
Advanced enzymatic and chromatographic separation methods are enabling the isolation of specific phospholipids. Pharmaceutical and nutraceutical formulators are the primary adopters, seeking high-purity phosphatidylcholine or phosphatidylserine fractions for targeted health applications. This technology is automating the creation of bespoke, high-value lecithin grades that deliver specific functional benefits beyond basic emulsification.
Regulatory frameworks for food allergen labeling are becoming more stringent globally. For instance, the EU's Food Information to Consumers (FIC) Regulation No 1169/2011 mandates clear declaration of soy as an allergen, even when used as an additive like lecithin. This forces manufacturers targeting the European market to either use non-allergenic sources like sunflower or invest in highly refined soy lecithin that may qualify for an exemption.
Demand for radical transparency is altering procurement patterns for food ingredients. Large CPG companies are moving beyond simple certificates of analysis and requiring suppliers to provide digital, verifiable proof of origin and non-GMO status for each batch. This shift is most visible in the infant formula and organic food segments, particularly in North America and Europe, where brand reputation depends on supply chain integrity.
De Oiled Lecithin Market Segmentation
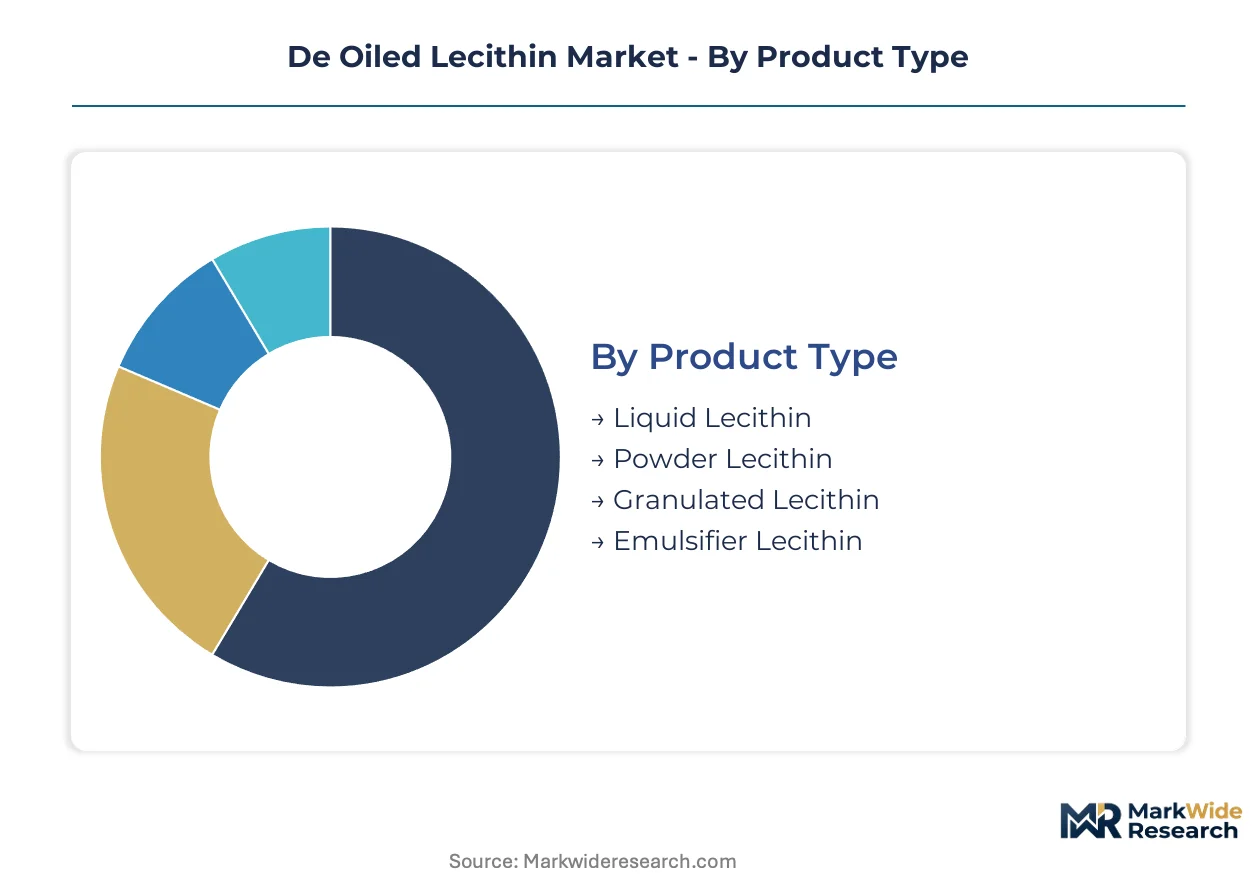
The de oiled lecithin market diversifies across various attributes, reflecting distinct product specifications, end-use requirements, and consumer preferences. Understanding these segments is critical for manufacturers to tailor product offerings and for stakeholders to identify growth pockets within the market.
Product Type:
The market delineates product types based on their physical form and processing characteristics, influencing handling and application. These technical specifications dictate suitability for different industrial processes.
- Powder Lecithin:This form offers superior handling, precise dosing accuracy, and enhanced stability compared to liquid varieties, making it highly preferred in automated industrial food production lines. Demand for powdered lecithin is particularly strong in bakery and confectionery for consistent texture.
- Granulated Lecithin:Granulated lecithin provides excellent flow properties and reduced dust during handling, appealing to food manufacturers seeking operational efficiency and improved workplace safety. Its stability also extends product shelf-life in various food applications.
- Liquid Lecithin:This traditional form serves as a versatile emulsifier in numerous food and industrial applications, valued for its ease of dispersion in liquid systems. Its cost-effectiveness makes it a staple in bulk ingredient procurement.
- Emulsifier Lecithin:This category encompasses specialized lecithin grades optimized for their emulsifying properties, crucial for blending immiscible liquids in food, pharmaceutical, and cosmetic formulations. It ensures product homogeneity and stability.
Mature deployment sits with Liquid Lecithin. Newer deployment is concentrated in Powder Lecithin.
End Use Industry:
Market segmentation by demand driver reveals the primary sectors leveraging de oiled lecithin's functional properties. Each industry utilizes lecithin for specific product enhancement and processing benefits.
- Food & Beverage:This industry represents the largest segment, driven by demand for clean-label emulsifiers in products ranging from confectionery to baked goods, improving texture and shelf life. Consumer preference for non-GMO and organic ingredients significantly influences sourcing decisions within this sector.
- Nutraceuticals:High-phosphatidylcholine (PC) concentrates derived from de oiled lecithin are gaining traction in dietary supplements and functional foods, addressing cognitive and liver health benefits. This application commands a premium due to its specific health claims and purity requirements.
- Pharmaceuticals:De oiled lecithin functions as an excipient, emulsifier, and solubilizer in drug formulations, enhancing bioavailability and stability of active pharmaceutical ingredients. Its natural origin and GRAS status support its use in various medicinal products.
- Animal Feed:Lecithin improves fat digestion, nutrient absorption, and feed palatability in animal nutrition, particularly in aquaculture and poultry feeds. It contributes to animal health and growth performance.
Food & Beverage commands the largest share, while Nutraceuticals exhibits the steepest expansion trajectory.
Application:
The market segments by functional purpose, indicating specific product categories where de oiled lecithin provides critical performance benefits. These applications highlight its versatility as an ingredient.
- Confectionery:De oiled lecithin acts as an anti-blooming agent, emulsifier, and viscosity modifier in chocolate, caramels, and other sweets, preventing fat separation and improving mouthfeel. This application is a significant growth catalyst for the market.
- Baking:In bakery products, lecithin enhances dough workability, extends shelf-life, and improves crumb structure by acting as an emulsifier and dough conditioner. It is critical for consistent product quality in industrial baking.
- Dairy:Lecithin stabilizes dairy products like ice cream and milk-based beverages, preventing fat separation and improving texture. It contributes to a smoother consistency and enhanced mouthfeel.
- Cosmetics:In cosmetic formulations, lecithin serves as an emulsifier, emollient, and conditioning agent, contributing to product stability, skin hydration, and sensory attributes. It is valued for its natural origin.
Confectionery applications drive significant volume. Baking applications are gaining share most quickly.
Form:
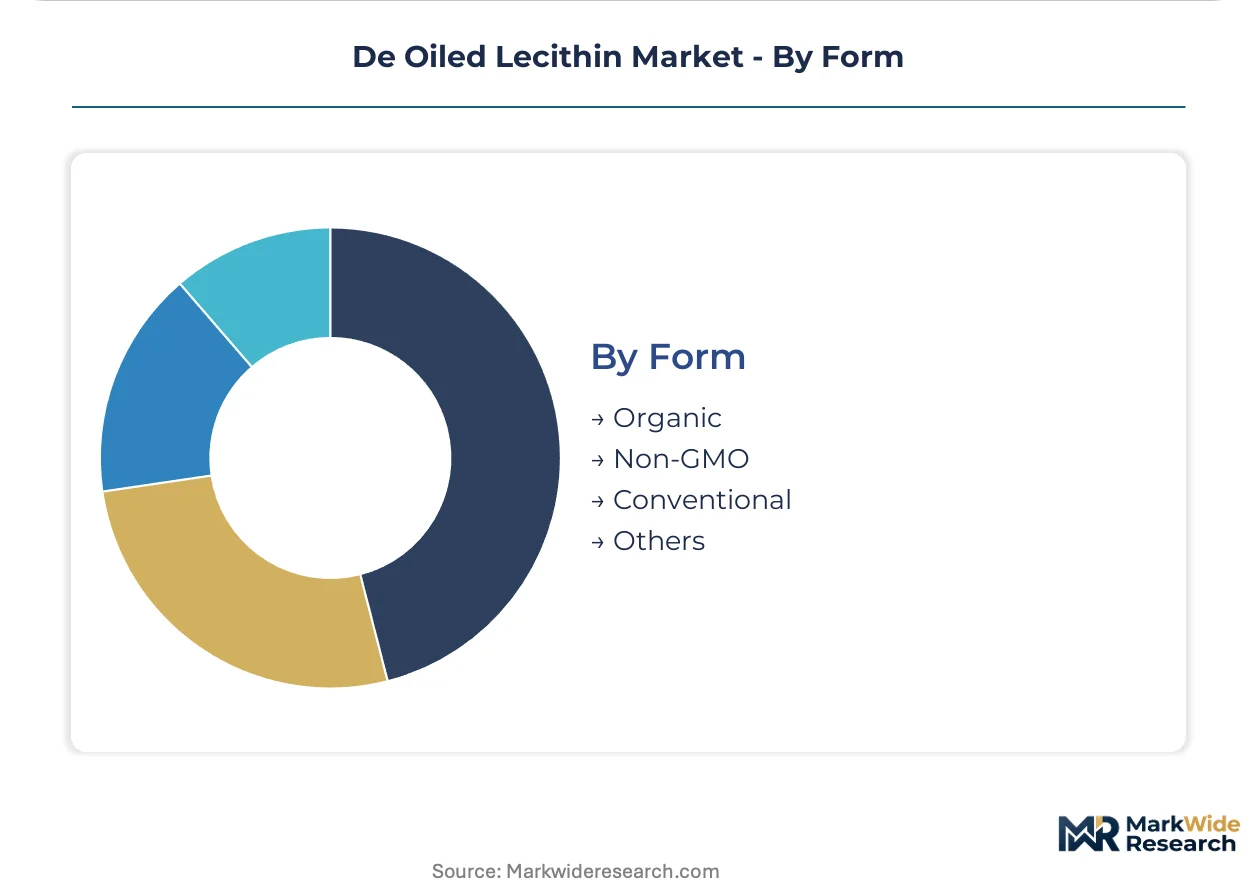
Segmentation by sourcing and purity standards reflects evolving consumer demand for specific ingredient attributes. These forms address concerns around genetic modification and agricultural practices.
- Non-GMO:This form caters to consumers and food producers demanding ingredients free from genetically modified organisms, requiring stringent supply chain segregation and certification. Demand for non-GMO de oiled lecithin is a fundamental market dynamic.
- Organic:Organic de oiled lecithin is produced from organically certified crops, adhering to strict agricultural and processing standards without synthetic pesticides or fertilizers. This premium segment aligns with the clean-label trend and commands higher prices.
- Conventional:Conventional lecithin is derived from standard agricultural practices and represents the most widely available and cost-effective form. It meets general food safety and quality standards without specific non-GMO or organic certifications.
- Others:This category includes specialized lecithin forms, potentially derived from novel sources like rapeseed or algae, or specifically modified for unique functional properties. These forms address niche applications or allergen concerns.
Conventional forms anchor traditional markets. Non-GMO forms are expanding fastest due to consumer preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The de oiled lecithin market exhibits a clear production-vs-consumption divide, with major agricultural economies driving raw material supply and industrialized nations leading ingredient demand. Global food manufacturers increasingly seek certified and traceable lecithin for diverse applications. This dynamic shapes regional market development.
United States
Demand for clean-label food ingredients fuels de oiled lecithin consumption in the United States. The FDA's GRAS classification facilitates broad application in food and pharmaceutical products. California's food processing hubs, particularly around Los Angeles and the Central Valley, show strong demand for non-GMO lecithin.
Germany
Germany's robust confectionery and bakery sectors drive significant de oiled lecithin uptake. The European Union's E322 designation provides a clear regulatory framework for its use. Industrial food ingredient clusters in North Rhine-Westphalia actively integrate advanced lecithin formulations.
China
China's expanding food and beverage industry, especially dairy and infant formula, consumes substantial volumes of de oiled lecithin. GB standards dictate stringent quality and safety requirements for food additives. Shanghai and Guangzhou's large food manufacturing bases are key consumption centers.
India
Growing health consciousness and a burgeoning middle class in India increase demand for functional food ingredients. The FSSAI regulates food additives, ensuring quality and safety standards for lecithin. Food processing zones near Mumbai and Delhi exhibit rising uptake in bakery and confectionery.
Brazil
Brazil's large agricultural output, particularly soy, positions it as a significant raw material supplier for lecithin production. ANVISA oversees food ingredient regulations, influencing product formulations. São Paulo's extensive food industry clusters require emulsifiers for diverse product lines.
De Oiled Lecithin Market Key Industry Players
Top-tier vendors anchor the global de oiled lecithin market, while specialized regional players and new entrants target niche applications. The market structure features integrated agricultural giants, ingredient specialists, and smaller, agile producers. Dominant competitive moves include strategic partnerships for supply chain security and continuous investment in processing technology.
Integrated agricultural companies, including Cargill Incorporated and Archer-Daniels-Midland Company, exemplify the scale-driven archetype within the de oiled lecithin market. These entities leverage extensive raw material sourcing and global distribution networks to serve a broad industrial client base. Bunge Limited also occupies a position within this segment, focusing on large-scale processing capabilities and a robust logistical infrastructure. These major players often provide a wide range of lecithin grades, ensuring consistent supply for diverse food and pharmaceutical applications worldwide.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer-Daniels-Midland Company |
| Bunge Limited |
| American Lecithin Company |
| Sonic Biochem Extraction Pvt Ltd |
| Stern-Wywiol Gruppe |
| IMCD Group B.V. |
| Avril Group |
| Avi Agri Business Limited |
| Others |
Cost & Logistics Intelligence
Certification-driven pricing divergence between conventional and non-GMO/organic de-oiled lecithin shapes both procurement strategies and supply chain complexity. This stratification reflects consumer demand for documented provenance and clean-label ingredients.
Pricing Analysis
Margin tightening across conventional de-oiled lecithin reflects competition from synthetic emulsifiers in price-sensitive applications. The dominant pricing model combines commodity spot pricing for conventional forms with contract-based long-term offtake for certified non-GMO and organic grades. Price differentiation stems from certification level, raw material source, and specific phospholipid purity. Nutraceutical and pharmaceutical buyers exhibit the lowest price sensitivity, while bulk food manufacturers for conventional products are most sensitive.
Supply Chain Analysis
De-oiled lecithin supply rests heavily on agricultural output from Brazil and the United States for soy, and European regions for sunflower. Key dependencies include non-GMO soybeans, sunflower seeds, and rapeseed. A structural risk is the operational complexity and cost of maintaining segregated supply chains for certified non-GMO and organic products. Distribution runs through integrated agricultural giants and specialized ingredient distributors serving industrial clients globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The de-oiled lecithin market operates as a supply-constrained story, with the high cost and complexity of non-GMO and organic raw material segregation propping pricing for premium grades. This bottleneck ensures value retention for certified products.
For Market Incumbents:Anchor global supply chains through deepened backward integration into certified non-GMO and organic raw material sourcing. Invest in advanced enzymatic and chromatographic purification technologies to isolate high-value phospholipid fractions. Counter margin pressure from synthetic emulsifiers by highlighting de-oiled lecithin's clean-label and functional benefits in premium applications. Expand processing capacity in key agricultural regions to secure future supply.
For New Entrants and Emerging Players:Launch via specialized distribution channels targeting the high-value nutraceutical and pharmaceutical segments. Focus on commercializing de-oiled lecithin from novel sources like rapeseed or algae to address soy allergen concerns and create unique functional profiles. Penetrate under-served regional markets in Asia and Latin America with certified non-GMO product offerings. Emphasize digital traceability for supply chain transparency.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized mid-cap ingredient processors demonstrating strong intellectual property in purification technologies, given sustained clean-label and plant-based food trends. Long-term viability over the next 5-10 years remains robust, driven by expanding nutraceutical and pharmaceutical applications. Target acquisition archetypes include firms with established non-GMO supply chains or proprietary alternative source development. A key signal to watch is the increasing consolidation among smaller certified lecithin producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Sunflower Lecithin | Increasing sunflower processing capacity mitigates soy allergen concerns and diversifies raw material sourcing. |
| High-Purity Phospholipid Concentrate Development | Creating specialized fractions for nutraceuticals captures premium value and addresses targeted health applications. |
| Digital Supply Chain Traceability Implementation | Enhancing verifiable proof of origin builds brand trust and meets stringent regulatory requirements. |
| Strategic Partnerships with Plant-Based Food Brands | Collaborating with plant-based innovators secures early-stage demand for specialized emulsifiers. |
| Investment in Novel Lecithin Source R&D | Exploring alternative sources like algae reduces dependency on traditional crops and offers unique functional properties. |
Research Approach
Independent corroboration across primary interviews with R&D directors, procurement leads, and regulatory affairs specialists, alongside secondary validation from regulatory filings and trade association reports, underwrites the qualitative findings. This approach integrates insights from food scientists and ingredient buyers. Secondary sources included FDA GRAS notices, EU E322 regulations, and GB standards. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
The forecast window was anchored to historical demand and supply trends, establishing a baseline for future projections across the analysis window. Segmentation dimensions modeled included product type, end-use industry, application, form, and raw material source. Compound annual growth rates were derived from historical growth patterns and projected market drivers. Key forecast inputs included clean-label ingredient adoption rates and plant-based food market expansion.
Input price volatility, new regulatory restrictions, and novel synthetic emulsifier introductions are the dominant revision risks. Forecasts reflect assumptions documented through expert consensus and historical data. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market