
 Global Vanilla (B2B) Market | 2026-2036
Global Vanilla (B2B) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vanilla (B2B) Market Foresight
Commodity trading margins is narrowing as flavor houses deepen direct farm partnerships in Indian Ocean basin origins. Givaudan leverages vertical integration into Malagasy curing stations to secure traceable bean supply. Symrise sustains competitive positioning through biotechnology-derived vanillin platforms that complement its natural extraction network. Firmenich anchors premium pricing via proprietary bean selection protocols and long-term grower contracts.
Vanilla (B2B) denotes the commercial trade of vanilla-derived flavoring materials between agricultural processors, extraction houses, and industrial buyers, encompassing cured Vanilla planifolia and V. tahitensis beans with vanillin content typically ranging from 1.5% to 2.5% by dry weight, alongside synthetic vanillin produced from guaiacol or lignin substrates. The primary commercial purpose centers on delivering standardized flavor potency, aromatic complexity, and regulatory-compliant labeling for packaged goods manufacturers. Natural vanilla extract and vanilla beans command the deepest margin pools due to clean-label positioning, while synthetic vanillin occupies high-volume, price-sensitive applications in beverage flavoring. Powder and liquid forms dominate industrial handling efficiency, though vanilla paste gains traction among mid-tier bakery and confectionery producers seeking visual seed presence without bean processing overhead.
FDA food additive regulations, EFSA flavoring substance evaluations under Regulation (EC) No 1334/2008, and ISO 5563 standards for vanilla extract composition collectively define product specifications and cross-border market access conditions. Madagascar's national vanilla quality control protocols and Indonesia's agricultural export certification requirements further shape origin-specific supply reliability. Stakeholders must monitor biotechnology fermentation advances and evolving clean-label thresholds as these forces recalibrate the natural-synthetic competitive boundary.
Market Dynamics
The EU Green Deal's sustainable sourcing mandates are compressing traceability timelines for tropical agricultural imports, forcing flavor houses to restructure procurement from Madagascar, Indonesia, and Uganda curing stations toward direct farm partnerships with blockchain documentation.
Growth Catalysts
- Clean-label mandates:EFSA Regulation (EC) No 1334/2008 tightening natural flavoring definitions drives ice cream and confectionery manufacturers toward certified vanilla extract with full provenance documentation.
- Biotechnology maturation:Precision fermentation platforms for vanillin production are expanding supply elasticity beyond weather-dependent bean harvests, reducing price volatility spikes.
- Madagascar quality protocols:National curing standard enforcement is differentiating origin-specific bean grades, enabling premium tier pricing for traceable Malagasy supply.
Market Restraints
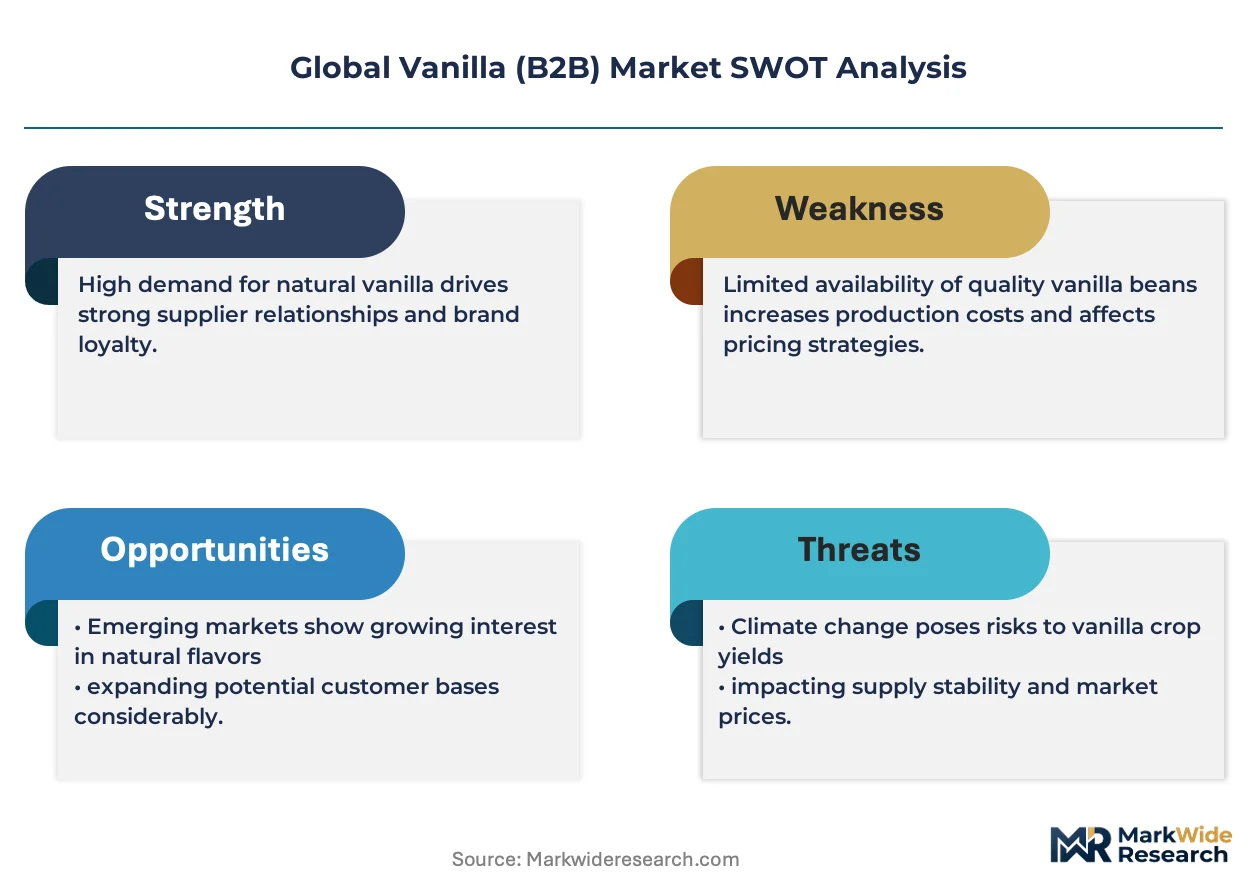
- Cyclone exposure:Madagascar's SAVA region concentrates 80% of global Bourbon vanilla production, creating catastrophic single-origin failure risk during Indian Ocean storm seasons.
- Guaiacol price volatility:Synthetic vanillin feedstock costs track petrochemical indices, compressing margins for lignin-derived alternatives during energy price spikes.
- FDA-EFSA divergence:Differing vanillin labeling thresholds between US and European markets force dual formulation runs, inflating compliance overhead for multinational flavor houses.
Strategic Opportunities
- Uganda upstream development:Underinvested curing infrastructure in Rwenzori and Bundibugyo regions offers first-mover vertical integration potential for extraction houses seeking non-Malagasy supply.
- Carbon accounting integration:EU Green Deal scope 3 emissions reporting requirements create service revenue streams for origin-certified vanilla with verified sequestration documentation.
- Paste format penetration:Mid-tier bakery producers seeking visual seed presence without bean processing overhead represent an underserved channel between commodity extract and whole bean tiers.
Industry Challenges
- Curing expertise scarcity:Traditional Malagasy scalding and sun-withering craftsmanship requires multi-year apprenticeship, constraining quality bean supply expansion regardless of planting increases.
- ISO 5563 compliance timelines:Third-party vanillin content verification and solvent residue testing for extract certification extends batch release cycles, complicating just-in-time procurement.
- Legacy contract renegotiation:Long-term grower agreements signed during 2018-2020 price peaks must be unwound or restructured as spot markets normalize, straining supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vanilla (B2B) Market |
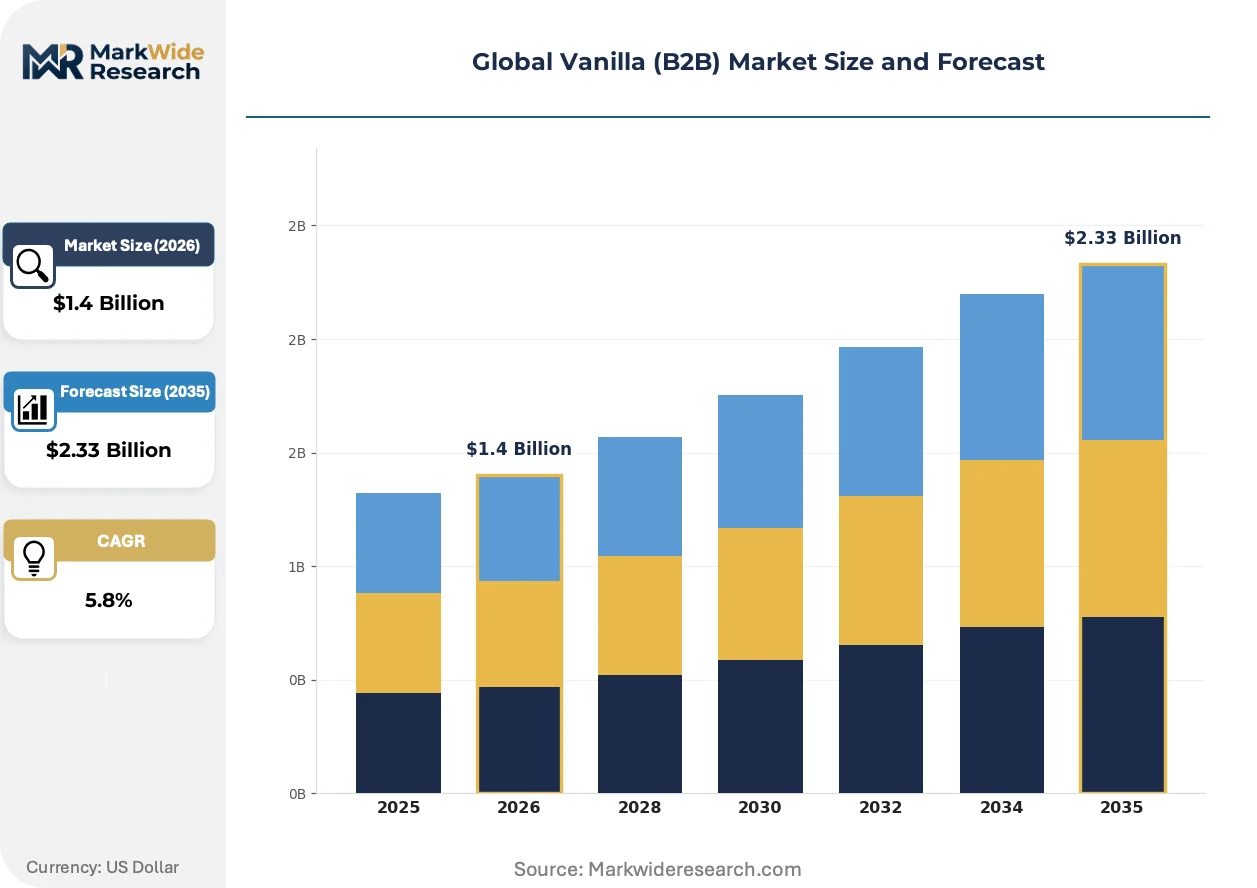
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Vanilla, Synthetic Vanilla, Vanillin Extracts, Vanilla Beans, Vanilla Paste Application: Food Flavoring, Beverage Flavoring, Fragrance, Pharmaceuticals, Cosmetics Form: Powder, Liquid, Solid, Oil, Extract End User: Food & Beverage Manufacturers, Cosmetic Companies, Pharmaceutical Producers, Fragrance Houses, Specialty Ingredient Suppliers |
| Companies Covered | Givaudan, Symrise, Firmenich, IFF, McCormick, Nielsen-Massey Vanillas, Sensient Technologies, Kerry Group, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vanilla (B2B) Market Shifts & Advancements
Blockchain-enabled traceability and biotechnology fermentation are converging to restructure competitive boundaries between natural extraction and synthetic production, while regulatory carbon accounting forces supply chain transparency investments.
Spectral imaging and AI-driven bean grading is digitizing quality assessment at Malagasy curing stations. Artisanal confectionery manufacturers in Western Europe are adopting this technology-enabled provenance data within 18-month procurement cycles. The structural compression of information asymmetry between origin and end-buyer is digitizing price discovery, reducing traditional trader margins.
REACH regulation expansion into deforestation-linked supply chains is mandating geolocation verification for vanilla imports entering EU customs territory. Flavor houses must now document farm-level GPS coordinates and harvest dates, not just exporter certificates. Premium ice cream manufacturers with EU manufacturing footprints are accelerating supplier audits to preempt 2025 enforcement deadlines.
Direct farm contracting is displacing spot market procurement among North American flavor houses. Large bakery and beverage manufacturers are consolidating supplier panels from twelve to three approved extraction houses, exchanging volume commitments for price caps and priority allocation rights. This concentration is most visible in California and Illinois processing clusters serving CPG brand headquarters.
Global Vanilla (B2B) Market Segmentation
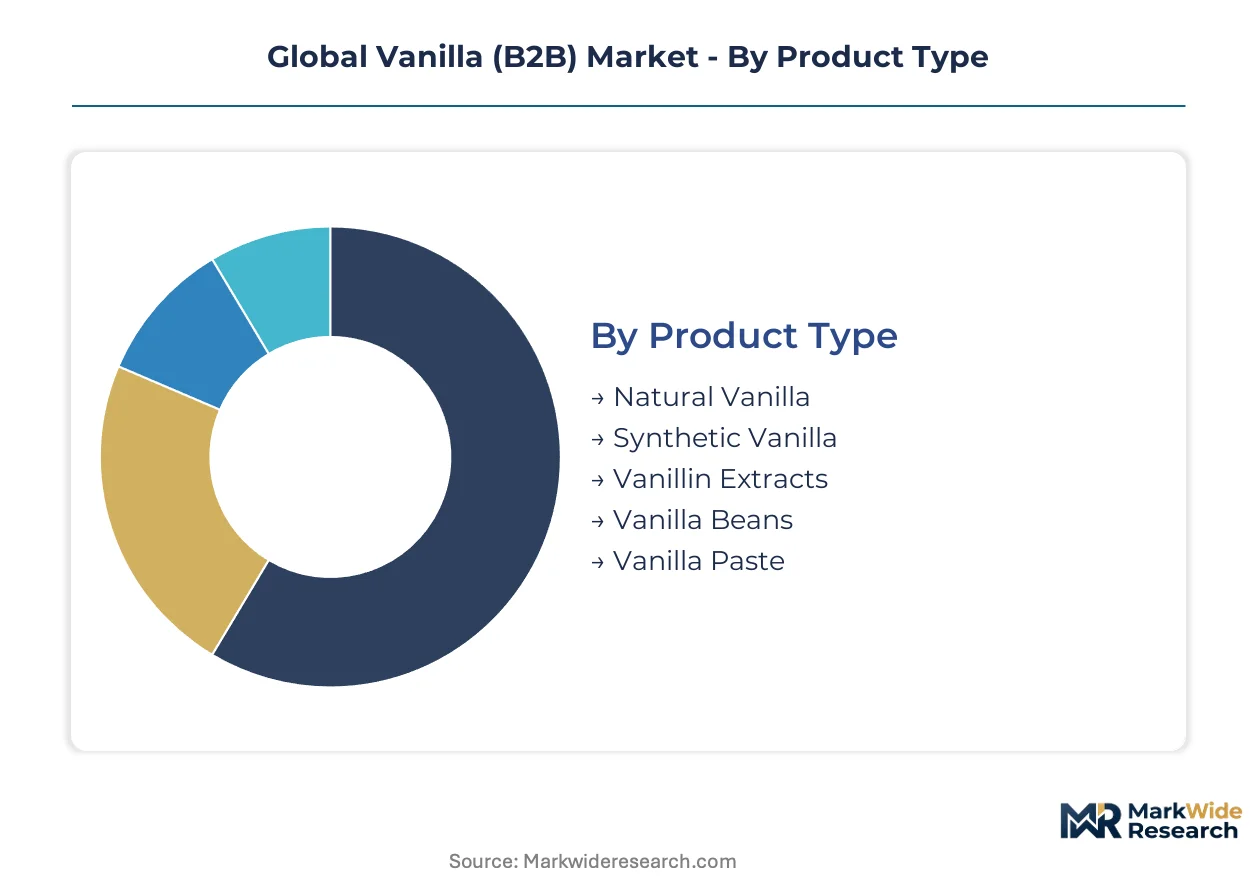
Vanilla B2B procurement patterns diverge sharply across product grades and end-use specifications. Flavor houses structure supplier portfolios around form factor efficiency, regulatory labeling requirements, and customer clean-label thresholds.
Product Type:
Cost tier differentiation separates commodity synthetics from premium natural extraction grades with full traceability documentation.
- Natural Vanilla:Bourbon and Tahitian bean varieties deliver 1.5-2.5% vanillin content by dry weight with complex aromatic profiles. Premium ice cream manufacturers in Western Europe concentrate procurement here, driven by EFSA Regulation (EC) No 1334/2008 natural flavoring definitions and EU Green Deal scope 3 reporting mandates.
- Synthetic Vanilla:Guaiacol or lignin-derived vanillin offers standardized potency at price points accessible to high-volume beverage applications. Energy price volatility compresses margins unpredictably, forcing formulation hedging strategies among multinational flavor houses.
- Vanillin Extracts:Concentrated vanillin solutions for industrial dosing efficiency.
- Vanilla Beans:Whole cured pods for visual seed presence and premium positioning.
- Vanilla Paste:Seed-suspension formats bridging extract convenience with bean aesthetics.
Natural vanilla commands the established base. The steepest expansion runs through vanilla paste as mid-tier producers seek visual differentiation without processing overhead.
Application:
End-use functionality dictates vanillin purity thresholds and aromatic complexity requirements.
- Food Flavoring:Bakery, confectionery, and dairy applications require heat-stable vanillin delivery through bake cycles and pasteurization. FDA food additive regulations and EFSA flavoring evaluations create divergent compliance pathways for multinational product lines.
- Beverage Flavoring:Soft drink and ready-to-drink coffee formulations prioritize cost-efficient synthetic vanillin at high dosing volumes. Clean-label migration in premium segments is pulling some procurement toward natural extraction despite price premiums.
- Fragrance:Fine fragrance and personal care applications leverage vanilla's fixative properties.
- Pharmaceuticals:Excipient and masking agent applications with USP-grade purity requirements.
- Cosmetics:Skin care and color cosmetic formulations requiring regulatory-compliant labeling.
Food flavoring anchors volume demand. Fragrance applications are climbing the fastest as fine perfume houses rebuild post-pandemic inventories.
Form:
Handling efficiency and dosing precision drive industrial form selection.
- Powder:Spray-dried vanillin crystals enable dry blend incorporation in bakery premixes and powdered beverages. Illinois and California processing clusters serving CPG headquarters concentrate procurement here for inventory stability and extended shelf life.
- Liquid:Alcohol or propylene glycol solutions facilitate automated dosing in liquid processing lines. ISO 5563 vanillin content verification extends batch release cycles, complicating just-in-time procurement for beverage manufacturers.
- Solid:Crystalline formats for specific industrial handling requirements.
- Oil:Lipid-soluble vanillin for fat-based confectionery applications.
- Extract:Alcohol-based solutions with full aromatic complexity for premium positioning.
Liquid formats dominate current throughput. Powder is gaining share fastest as dry blend applications expand in emerging markets.
End User:
Customer scale and specification sophistication determine supplier relationship structures.
- Food & Beverage Manufacturers:Large CPG brands consolidate approved supplier panels from twelve to three extraction houses, exchanging volume commitments for price caps and priority allocation rights. Direct farm contracting with Malagasy curing stations is displacing spot market procurement among North American headquarters.
- Cosmetic Companies:Skin care and color cosmetic formulators require REACH-compliant documentation for EU market access. Geolocation verification mandates under deforestation-linked supply chain regulations force farm-level GPS coordinate tracking.
- Pharmaceutical Producers:USP-grade vanillin for excipient applications with batch certification requirements.
- Fragrance Houses:Fine fragrance compounders with proprietary selection protocols and long-term grower contracts.
- Specialty Ingredient Suppliers:Distributors and blenders serving regional food manufacturers.
Food and beverage manufacturers represent the core revenue base. Specialty ingredient suppliers are expanding most quickly as regional bakery and confectionery producers professionalize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Western European ice cream manufacturers prioritize EFSA-compliant natural extraction grades with full farm-level traceability. North American beverage giants optimize procurement around synthetic vanillin price points and FDA labeling thresholds.
United States
California and Illinois processing clusters serve consolidated CPG brand headquarters with spray-dried vanillin crystals for dry blend efficiency. FDA food additive regulations govern vanillin purity thresholds for interstate commerce. Direct farm contracting with Malagasy curing stations is displacing spot market procurement among North American flavor houses seeking supply security.
Germany
REACH regulation expansion into deforestation-linked supply chains mandates geolocation verification for vanilla imports entering EU customs territory. EFSA Regulation (EC) No 1334/2008 natural flavoring definitions drive ice cream manufacturers toward certified extract with provenance documentation. Premium confectionery producers in Bavaria and North Rhine-Westphalia accelerate supplier audits to preempt 2025 enforcement deadlines.
France
Fine fragrance houses in Paris and Grasse leverage vanilla's fixative properties for post-pandemic inventory rebuilding. EU Green Deal scope 3 emissions reporting requirements create service revenue streams for origin-certified vanilla with verified sequestration documentation. Artisanal confectionery manufacturers in Western Europe adopt blockchain-enabled provenance data within compressed procurement cycles.
Madagascar
The SAVA region concentrates 80% of global Bourbon vanilla production, creating catastrophic single-origin failure risk during Indian Ocean storm seasons. National vanilla quality control protocols differentiate origin-specific bean grades, enabling premium tier pricing for traceable supply. Traditional scalding and sun-withering craftsmanship requires multi-year apprenticeship, constraining quality bean supply expansion regardless of planting increases.
Indonesia
Agricultural export certification requirements shape origin-specific supply reliability for extraction houses. Underinvested curing infrastructure in secondary growing regions offers first-mover vertical integration potential for firms seeking non-Malagasy supply. Flavor houses restructure procurement toward direct farm partnerships with blockchain documentation to satisfy EU Green Deal traceability mandates.
Global Vanilla (B2B) Market Competitive Landscape
Capability concentration sits with extraction specialists mastering curing station partnerships and fermentation platforms; scale advantage sits with diversified ingredient houses serving multinational CPG panels. The vendor base structures around three archetypes: biotechnology-enabled vanillin producers, vertically integrated natural extract houses, and commodity synthetic distributors. Dominant competitive moves include backward integration into Malagasy and Ugandan curing infrastructure, plus strategic consolidation of approved supplier panels from twelve to three approved extraction houses.
Within the biotechnology-enabled tier, Symrise occupies a position exemplifying precision fermentation platforms that complement natural extraction networks. Among Swiss-origin flavor houses, Givaudan and Firmenich represent contrasting archetypes: Givaudan anchors upstream control over Malagasy curing stations, while Firmenich exemplifies premium positioning via proprietary bean selection protocols and long-term grower contracts. These three firms collectively illustrate how competitive boundaries restructure around traceability investments and clean-label certification depth.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| Firmenich |
| IFF |
| McCormick |
| Nielsen-Massey Vanillas |
| Sensient Technologies |
| Kerry Group |
| Archer Daniels Midland |
| Others |
Supply & Pricing Matrix
Madagascar's SAVA region concentrates 80% of global Bourbon vanilla production, creating acute pricing power asymmetries between Malagasy curing stations and downstream extraction houses. Cyclone exposure and multi-year apprenticeship requirements for traditional scalding craftsmanship constrain quality bean supply expansion, amplifying spot price volatility during harvest disruptions.
Pricing Analysis
Long-term offtake contracts signed during 2018-2020 price peaks now strain supplier relationships as spot markets normalize. Three-tier pricing structure across certified natural, commodity natural, and synthetic vanillin separates EFSA-compliant traceable supply from uncertified origins and lignin-derived alternatives. Cost compression in synthetic tiers intensifies because guaiacol feedstock costs track petrochemical indices. Beverage manufacturers exhibit highest price sensitivity, while premium ice cream producers absorb natural extraction premiums for clean-label positioning.
Supply Chain Analysis
Tariff exposure between EU customs territory and Indian Ocean basin origins dominates supply chain risk calculus for flavor houses serving Western European manufacturers. Madagascar, Indonesia, and Uganda anchor upstream curing capacity, with Madagascar's quality protocols differentiating origin-specific bean grades. Raw material dependencies center on cured Vanilla planifolia pods, guaiacol petrochemical feedstock, and precision fermentation substrates. Single-origin vulnerability in the SAVA region threatens catastrophic supply interruption during Indian Ocean storm seasons. Distribution runs through vertically integrated extraction houses serving consolidated CPG brand panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology fermentation platforms are disrupting competitive boundaries between natural extraction and synthetic production, creating asymmetric growth opportunities for firms mastering both capability sets.
For Market Incumbents: Harden Malagasy supply security through backward integration into Rwenzori and Bundibugyo curing infrastructure in Uganda, diversifying beyond SAVA region concentration. Deepen blockchain-enabled traceability investments to preempt EU Green Deal enforcement timelines and defend premium tier pricing against precision fermentation substitutes. Certification depth serves as the critical lever for maintaining margin pools in natural extraction grades. For New Entrants and Emerging Players: Uganda's underinvested curing infrastructure offers first-mover vertical integration potential for extraction houses seeking non-Malagasy supply with lower entry multiples than established Madagascar partnerships. Vanilla paste format penetration among mid-tier bakery producers represents an underserved channel between commodity extract and whole bean tiers. Direct farm contracting with blockchain documentation provides the essential go-to-market credential for EU-facing procurement cycles. For Investors and Strategic Acquirers: Long-term, this sits as a traceability infrastructure play because regulatory carbon accounting and deforestation-linked supply chain mandates are recalibrating competitive advantage toward origin-certified platforms with verified sequestration documentation. Acquisition targets should emphasize firms with captive curing station relationships and ISO 5563 compliance capabilities. The signal to watch is REACH regulation expansion velocity into geolocation verification requirements for tropical agricultural imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ugandan Curing Infrastructure | Diversifies supply beyond Madagascar's SAVA concentration risk while capturing EU Green Deal traceability premiums. |
| Precision Fermentation Platform Scale-Up | Reduces weather-dependent harvest volatility and expands supply elasticity for price-sensitive beverage applications. |
| Blockchain-Enabled Provenance Documentation | Satisfies EFSA Regulation (EC) No 1334/2008 tightening and REACH deforestation-linked supply chain mandates. |
| Vanilla Paste Format Development | Captures mid-tier bakery producers seeking visual seed presence without whole bean processing overhead. |
| Carbon Accounting Integration Service | Creates service revenue streams from EU Green Deal scope 3 emissions reporting requirements for origin-certified supply. |
Research Methodology
Desk research of customs and trade data, FDA food additive filings, EFSA flavoring substance evaluations, and ISO standards documentation preceded structured interviews with flavor house procurement directors, Malagasy curing station operators, extraction house technical directors, and premium ice cream manufacturer supply chain managers. Primary fieldwork across Madagascar's SAVA region, Indonesian agricultural export zones, and Ugandan Rwenzori growing areas validated secondary estimates. Bottom-up bean production and curing capacity modeling triangulated against top-down flavor house procurement spend analysis.
Assumptions held fixed across the projection horizon include EU Green Deal enforcement timelines, EFSA natural flavoring definition stability, and precision fermentation cost reduction curves. Segmentation dimensions modeled span product type (natural, synthetic, paste, extract), application (food flavoring, beverage, fragrance), form (powder, liquid), and end user scale. CAGRs derived from regression analysis against historical price volatility patterns and procurement volume trends. Industry-specific inputs incorporated cyclone frequency distributions and curing apprenticeship pipeline constraints.
Macroeconomic conditions sit as an overlay; deviation in petrochemical indices, Indian Ocean storm season severity, or biotechnology substrate costs would shift the trajectory. Forecasts reflect documented assumptions without guarantee of realization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Natural and Organic Flavors Market