
 Chokeberry Extract Market | 2026-2036
Chokeberry Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Chokeberry Extract Market Analytics
Specialized agronomy expertise in cold-climate berry cultivation is redrawing competitive boundaries for chokeberry extract suppliers. Sawmill Hollow Family Farm leverages its integrated orchard-processing infrastructure to secure raw material consistency across seasons. Microstructure Sp. sustains extraction yield advantages through proprietary low-temperature concentration protocols. Tecofood Sp. anchors its position by controlling distribution into Polish and German nutraceutical contract manufacturers.
Chokeberry extract is a concentrated preparation derived from Aronia melanocarpa fruit, standardized typically to anthocyanin content between fifteen and twenty-five percent by weight, obtained through aqueous ethanol extraction followed by spray-drying or membrane filtration. The extract functions primarily as a natural colorant, antioxidant stabilizer, and polyphenol fortificant in dietary supplements and functional foods. Powder formats dominate current volume due to superior stability in dry-blend applications and lower logistics costs, while liquid extracts command premium placement in beverage formulations where solubility performance determines procurement decisions. Nutraceutical applications absorb the largest value share as capsule and tablet brands seek substantiated cardiovascular and glycemic support positioning.
EFSA novel food evaluations and FDA New Dietary Ingredient notifications impose parallel substantiation burdens on chokeberry extract suppliers seeking health claim authorization or supplement market access. USDA organic certification and EU organic regulation 2018/848 further segment pricing tiers by restricting permissible extraction solvents and agricultural chemical residues. Stakeholders must monitor evolving polyphenol bioavailability research and adapt clinical substantiation investments to preempt tightening regulatory acceptance thresholds.
Market Dynamics
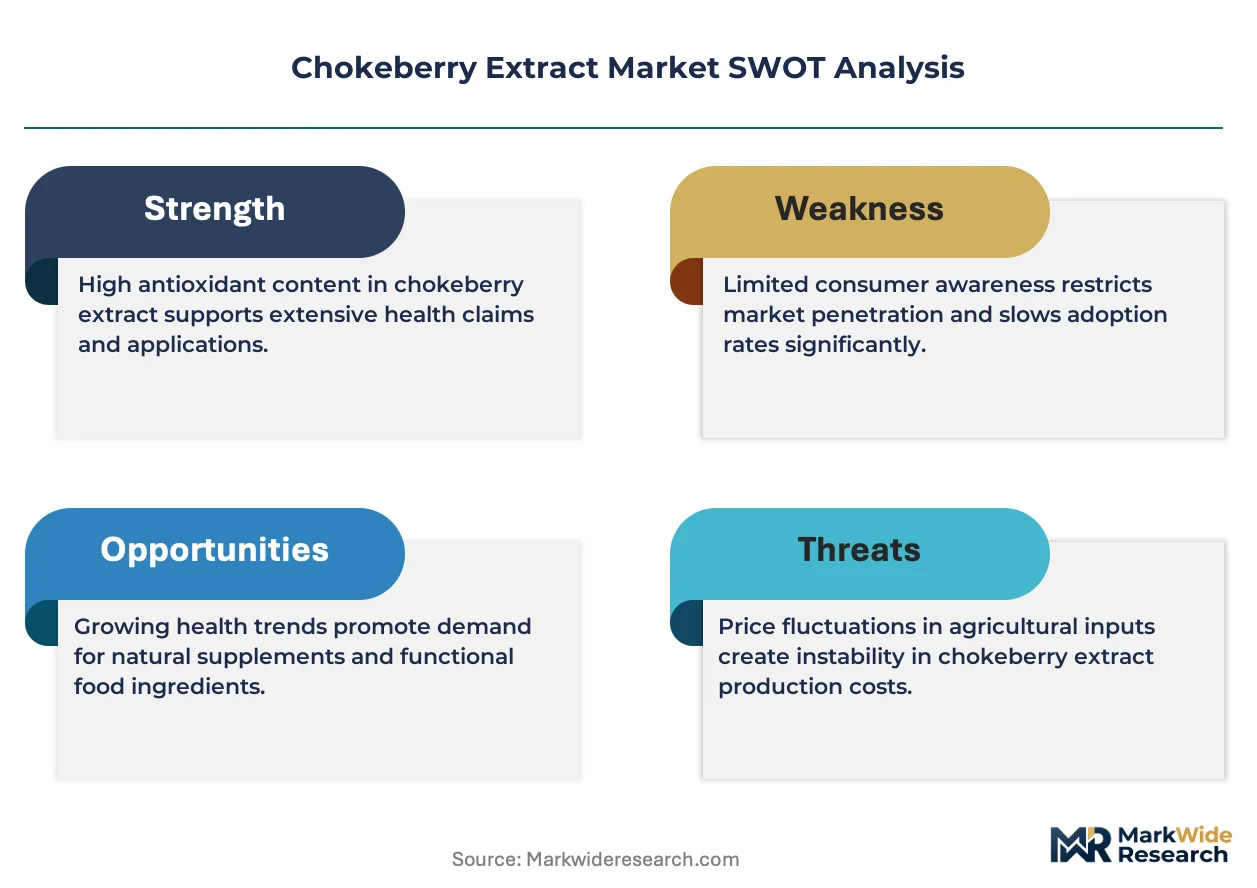
Clean-label substantiation requirements under EFSA novel food pathways and FDA New Dietary Ingredient notifications are compressing supplier margins while concentrating procurement among vertically integrated orchard-processors with captive clinical data assets.
Growth Catalysts
- EU organic regulation 2018/848:Certification premiums for solvent-restricted extracts are pulling Polish and German contract manufacturers toward certified supply chains, tightening raw material qualification standards.
- Cardiovascular positioning:Nutraceutical capsule brands are expanding anthocyanin fortification in glycemic support formulations, absorbing powder extract volumes at standardized 15-25% polyphenol grades.
- Poznan cultivation belt:Polish farmer cooperative consolidation is securing cold-climate berry supply consistency, reducing season-to-season raw material variability for aqueous ethanol processors.
Market Restraints
- Input cost volatility:Ethanol pricing fluctuations and energy-intensive spray-drying operations are squeezing extraction economics, particularly for membrane filtration specialists without captive energy assets.
- Supply concentration risk:Three-quarters of European aronia cultivation clusters within 200 kilometers of Poznan, creating geographic vulnerability to climate events and single-region logistics disruptions.
- Substitution threat:Bilberry and elderberry extracts with established EFSA health claim dossiers are displacing chokeberry in premium antioxidant positioning where clinical substantiation timelines matter.
Strategic Opportunities
- Underpenetrated US beverage channel:Liquid extract solubility advantages remain underexploited in American functional drink formulations, creating white space for European suppliers with USDA organic certification.
- Technology convergence:Low-temperature concentration protocols combined with rapid anthocyanin stability testing are enabling just-in-time production models that reduce working capital requirements.
- Japanese nutraceutical demand:METI functional food labeling standards are creating regulatory tailwinds for polyphenol-fortified products, opening import channels for standardized extract grades.
Industry Challenges
- Clinical substantiation talent scarcity:Polyphenol bioavailability research expertise sits concentrated within academic institutions, forcing extract suppliers to fund captive PhD programs or outsource to CROs with extended timelines.
- Dual certification complexity:Simultaneous USDA organic and EU organic 2018/848 compliance requires parallel residue testing protocols, extending batch release cycles by 15-20 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chokeberry Extract Market |
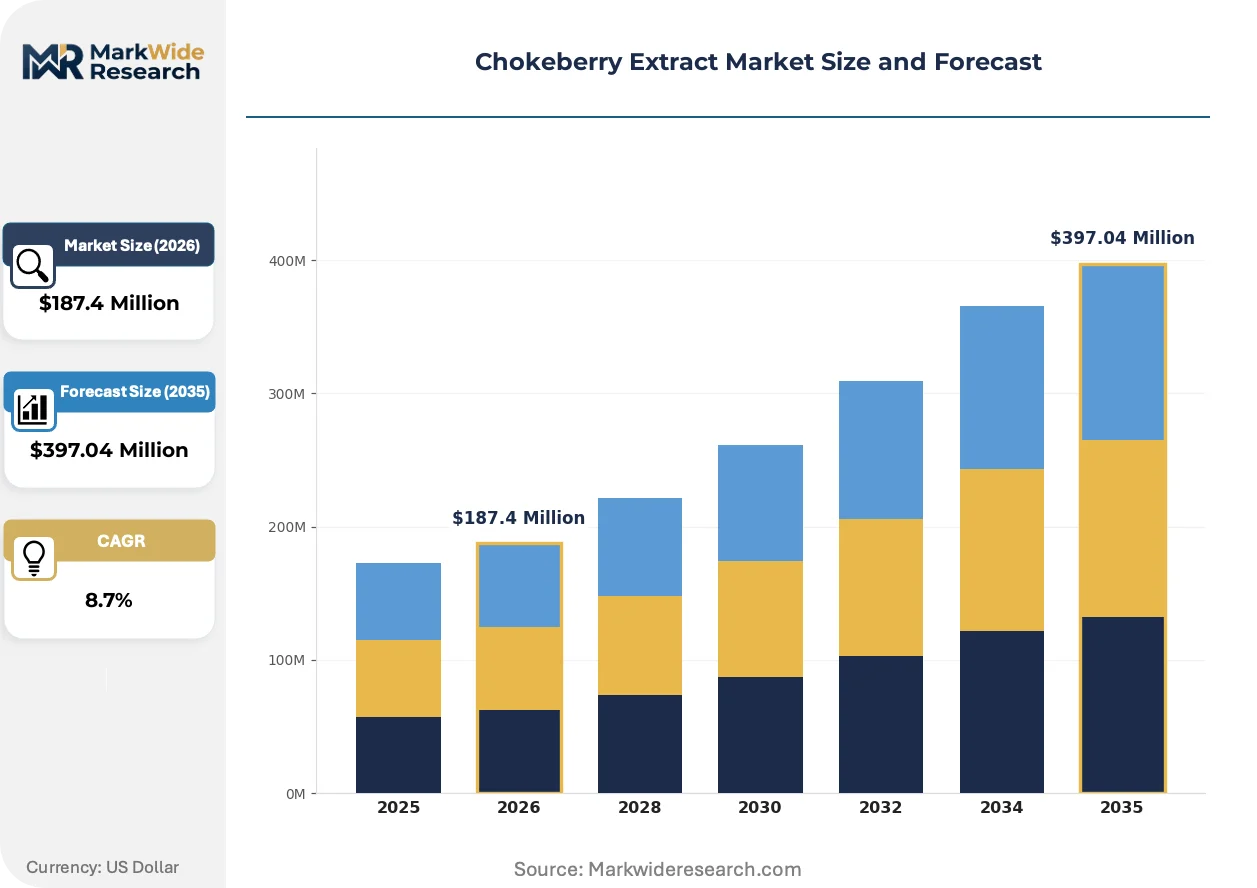
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder, Capsule, Tincture Application: Nutraceuticals, Cosmetics, Food & Beverages, Pharmaceuticals End User: Retail Consumers, Food Manufacturers, Cosmetic Companies, Health Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Bellbrook Berry Farm, Microstructure Sp., Sawmill Hollow Family Farm, Mae's Health and Wellness, Cedar Gardens LLC, B.T. Aronia Farm, OPG Medic, P.P.H.U. Bio Juice, Tecofood Sp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chokeberry Extract Market Evolving Landscape
Extraction technology and regulatory substantiation pathways are diverging sharply between premium clinical-grade suppliers and commodity colorant producers, fragmenting competitive strategy across the value chain.
Membrane filtration is replacing conventional spray-drying for high-anthocyanin retention in liquid extract formats. Beverage formulators in Germany and Poland are adopting these concentrates at triple the rate of dry-blend powder alternatives. The technology is bifurcating supplier tiers between capital-intensive membrane operators and legacy spray-dryers locked in price competition for standard-grade powders.
EFSA novel food evaluations are tightening polyphenol-specific health claim requirements beyond generic antioxidant positioning. Extract suppliers must now submit human intervention studies for cardiovascular or glycemic endpoints before market authorization. Polish and Baltic processors with existing clinical trial infrastructure are capturing disproportionate share of premium nutraceutical contracts.
Direct procurement relationships between orchard cooperatives and German contract manufacturers are displacing traditional ingredient distributor networks. These bilateral arrangements specify harvest timing, cultivar selection, and post-harvest handling protocols. The shift is most visible in Poznan-region supply chains where farmer-processor integration has compressed raw material qualification from 18 months to 90 days.
Chokeberry Extract Market Segmentation
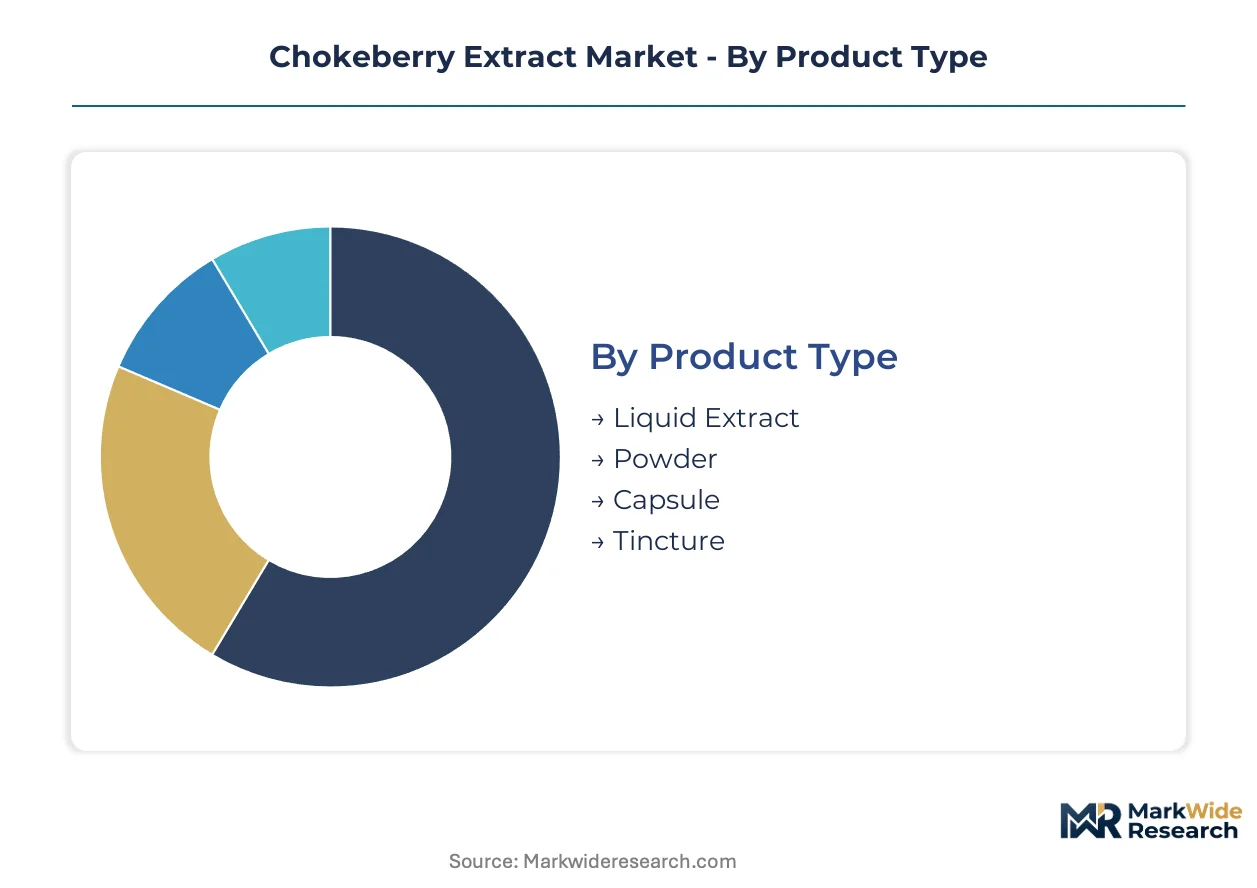
Chokeberry extract procurement patterns diverge sharply across product formats and end-use channels, with solubility requirements and regulatory substantiation burdens reshaping supplier priorities. Manufacturers must align extraction technology investments with the specific stability and bioavailability demands of each segment tier.
Product Type:
Substitution pressure from elderberry and bilberry extracts hits powder and liquid formats hardest where antioxidant positioning lacks differentiated clinical dossiers.
- Liquid Extract:Aqueous concentrates standardized to 15-25% anthocyanin content deliver superior solubility in functional beverages. German beverage formulators are expanding procurement of membrane-filtered liquid grades where rapid dispersion determines supplier selection.
- Powder:Spray-dried or freeze-dried formats dominate dry-blend nutraceutical applications with extended shelf stability. Polish contract manufacturers absorb the largest powder volumes for capsule and tablet fortification, though spray-drying energy costs compress margins for non-captive processors.
- Capsule:Pre-encapsulated extracts reduce formulation complexity for mid-tier supplement brands. Health Stores in North America drive demand for unit-dose convenience formats.
- Tincture:Alcohol-based preparations serve traditional medicine channels and artisanal cosmetic formulators. Specialty Stores in German-speaking Europe sustain niche procurement of tincture-grade materials.
Powder retains volume leadership; liquid extract holds the steepest expansion curve.
Application:
Margin compression from dual certification requirements falls heaviest on nutraceutical and pharmaceutical tiers where EFSA and FDA substantiation pathways overlap.
- Nutraceuticals:Dietary supplement capsules and tablets targeting cardiovascular and glycemic support absorb standardized polyphenol grades. Polish and Baltic processors with clinical trial infrastructure capture premium contract manufacturing relationships.
- Cosmetics:Antioxidant serums and anti-aging formulations utilize chokeberry anthocyanins for natural colorant and active ingredient positioning. Cosmetic Companies in France and Germany are expanding clean-label procurement of solvent-restricted extracts.
- Food & Beverages:Functional drinks and fortified snacks require high-solubility liquid concentrates. Food Manufacturers prioritize USDA organic certification for North American clean-label positioning.
- Pharmaceuticals:Investigational drug applications and medical food formulations demand GMP-compliant extract grades with full traceability documentation. Regulatory burden limits supplier qualification to vertically integrated orchard-processors.
Nutraceuticals command value concentration; food and beverages are climbing fastest.
End User:
Procurement scale and technical specification intensity separate institutional buyers from retail channels, with Food Manufacturers and Cosmetic Companies driving contract standardization.
- Food Manufacturers:Large-scale buyers specify harvest timing, cultivar selection, and post-harvest handling through direct orchard cooperative relationships. Poznan-region integration has compressed raw material qualification timelines dramatically.
- Cosmetic Companies:Clean-label and natural positioning requirements restrict permissible extraction solvents and agricultural chemical residues. EU organic regulation 2018/848 compliance is becoming a baseline qualification threshold.
- Retail Consumers:Direct purchase of supplements and functional foods through online and specialty channels. Price sensitivity favors standard-grade powder formats over premium liquid concentrates.
- Health Stores:Curated product selection emphasizes certified organic and clinically substantiated positioning. Staff recommendation drives brand switching toward polyphenol-standardized extracts.
Food Manufacturers anchor procurement volume; Cosmetic Companies are expanding specification intensity fastest.
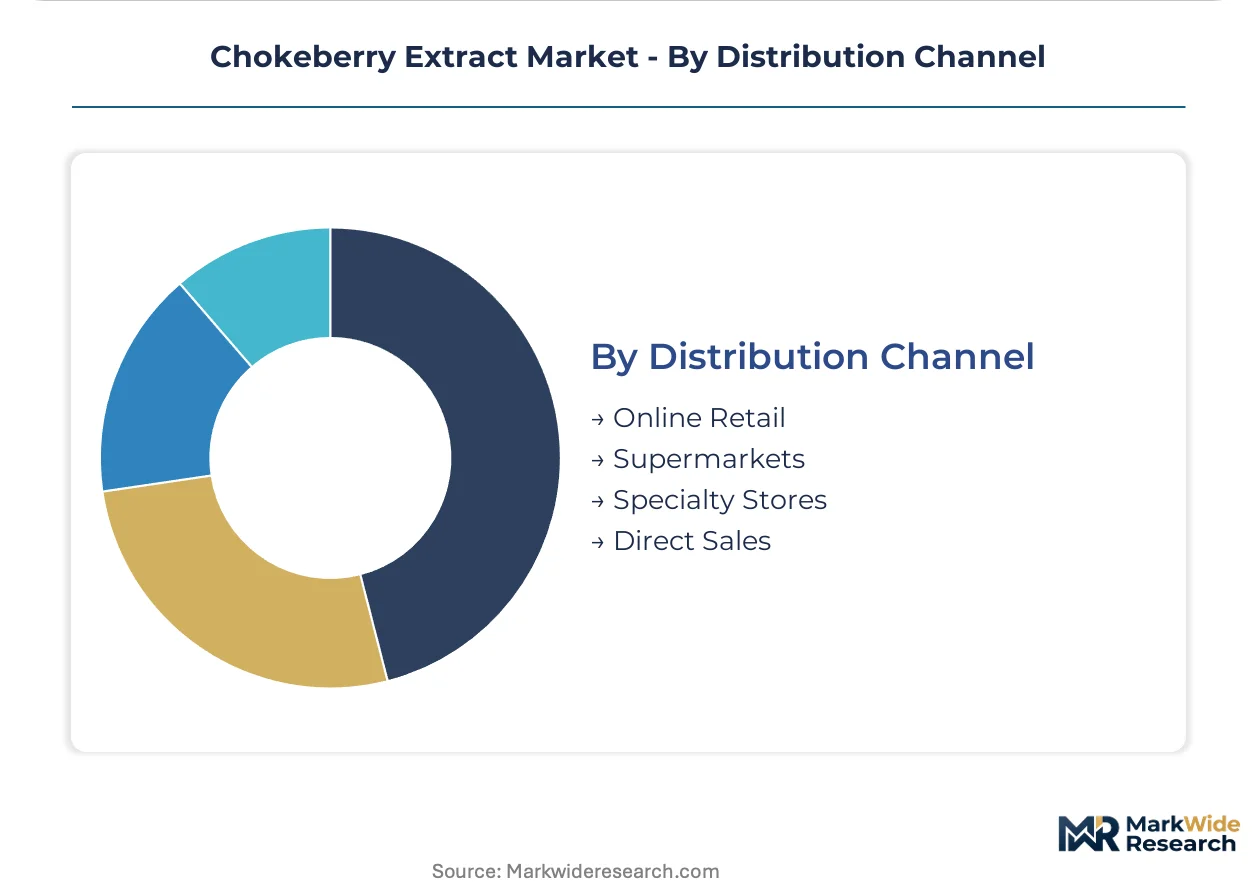
Distribution Channel:
Direct procurement bilateralism between Polish cooperatives and German manufacturers is displacing traditional distributor intermediaries, reshaping channel economics.
- Direct Sales:Orchard cooperatives and integrated processors supply contract manufacturers under long-term offtake agreements. These relationships specify quality parameters and delivery schedules that bypass conventional distribution markups.
- Online Retail:E-commerce platforms enable mid-tier extract suppliers to reach Nutraceutical and Cosmetics end users without geographic distributor coverage. Polish processors are expanding digital sales infrastructure for North American market access.
- Specialty Stores:Health food retailers and apothecary channels curate premium-grade extracts with organic certification and clinical substantiation. German and Austrian markets sustain the densest specialty store penetration.
- Supermarkets:Mass-market retail placement requires price-competitive standard-grade powders and established consumer recognition. Limited shelf space constrains chokeberry extract visibility against elderberry and bilberry alternatives.
Direct Sales captures institutional volume; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food pathways anchor regulatory gravity in Poland, where the Poznan cultivation belt concentrates European supply. German contract manufacturers drive demand for certified organic extracts, while North American beverage formulators expand procurement of membrane-filtered liquid grades.
Poland
Polish farmer cooperatives around Poznan supply three-quarters of European aronia raw material. EU organic regulation 2018/848 compliance has become mandatory for German nutraceutical contracts. The Greater Poland Voivodeship hosts integrated orchard-processor clusters that compress raw material qualification timelines from 18 months to 90 days.
Germany
German beverage formulators absorb membrane-filtered liquid extracts at triple the rate of powder alternatives. EFSA health claim substantiation requirements filter supplier qualification to vertically integrated orchard-processors with captive clinical data. Bavaria-based contract manufacturers specify harvest timing and cultivar selection through direct Poznan cooperative relationships.
United States
American functional beverage channels remain underpenetrated by European liquid extract suppliers despite solubility advantages. FDA New Dietary Ingredient notifications impose parallel substantiation burdens to EFSA pathways. Midwestern health stores drive capsule and tablet demand for cardiovascular positioning.
Japan
Japanese nutraceutical brands seek polyphenol-fortified products under METI functional food labeling standards. Import channels for standardized extract grades are opening as clinical substantiation investments align with local regulatory acceptance thresholds. Tokyo-based distributors specify rapid anthocyanin stability testing protocols.
France
French cosmetic companies expand clean-label procurement of solvent-restricted extracts for antioxidant serum formulations. ANSM and CNIL oversight intersects with EU organic residue restrictions. The Provence-Alpes-Côte d'Azur region sustains specialty apothecary channels that curate premium-grade tincture materials.
Chokeberry Extract Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in chokeberry extract supply. Orchard-processor integration defines the upper tier, while membrane filtration specialists and commodity spray-dryers occupy distinct rungs below. Strategic archetypes include captive cultivation operators, extraction technology licensors, and regional distribution anchors. Competitive moves concentrate on backward integration into orchard assets and geographic expansion into underpenetrated beverage channels.
Among Polish integrated operators, Microstructure Sp. and Tecofood Sp. exemplify the captive-processing archetype, while Sawmill Hollow Family Farm represents North American orchard-control positioning. These anchors occupy positions across the vertical spectrum from raw material qualification through contract manufacturing relationships.
| Leading Market Players |
|---|
| Bellbrook Berry Farm |
| Microstructure Sp. |
| Sawmill Hollow Family Farm |
| Mae's Health and Wellness |
| Cedar Gardens LLC |
| B.T. Aronia Farm |
| OPG Medic |
| P.P.H.U. Bio Juice |
| Tecofood Sp. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Polish orchard cooperatives and German contract manufacturers lock in both chokeberry raw material access and price visibility across harvest cycles, compressing spot market exposure for integrated processors while amplifying margin pressure on non-captive spray-drying operators.
Pricing Analysis
Contract-based long-term offtake dominates chokeberry extract procurement, with pricing stratifying across premium, standard, and economy tiers based on EU organic regulation 2018/848 certification status and anthocyanin standardization grade. Price differentiation hinges on dual USDA-EU organic compliance and membrane filtration versus spray-drying technology. Cost compression in standard-grade powders is intensifying because of ethanol pricing volatility and energy-intensive drying operations. Food Manufacturers exhibit highest price sensitivity due to volume scale, while Pharmaceutical buyers prioritize traceability documentation over unit cost.
Supply Chain Analysis
Inventory cycles for membrane-filtered liquid concentrates run 60-90 days shorter than spray-dried powder equivalents due to just-in-time production protocols. Supply concentrates in Poland, Germany, and the Baltic states, with raw material dependencies on aronia melanocarpa cultivar consistency, aqueous ethanol solvent supply, and energy inputs for concentration operations. Single-source vulnerability clusters around the Poznan cultivation belt, where climate events or logistics disruptions threaten three-quarters of European raw material. Distribution runs through direct bilateral arrangements between orchard cooperatives and contract manufacturers, displacing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chokeberry extract procurement is evolving into a service-attach opportunity as clinical substantiation packages and rapid anthocyanin stability testing protocols expand faster than commodity extract volumes, creating recurring-revenue layers for integrated orchard-processors.
For Market Incumbents: Fortify backward integration into Poznan-region orchard assets to secure cultivar-specific supply consistency against elderberry and bilberry substitution threats. Expand captive clinical trial infrastructure for EFSA novel food dossiers, as regulatory substantiation requirements filter premium contract access to vertically integrated operators with human intervention study capabilities. For New Entrants and Emerging Players: USDA organic certification fast-tracks offer the most penetrable entry path into underexploited American functional beverage channels, where liquid extract solubility advantages remain undeveloped. Target North American beverage formulators with membrane-filtered concentrate samples and rapid stability testing protocols, bypassing saturated European nutraceutical capsule markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Polish integrated orchard-processors with captive clinical data assets and long-term German offtake agreements. Five-to-ten year viability favors backward-integrated operators over commodity spray-dryers. The signal to watch is METI functional food labeling standard adoption in Japan, which would validate polyphenol bioavailability investments and open import channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Poznan-region cultivation control secures raw material qualification timelines and cultivar standardization for EFSA dossiers. |
| Membrane Filtration Technology Deployment | German beverage formulators absorb liquid concentrates at triple powder rates due to superior anthocyanin retention and solubility performance. |
| Dual Organic Certification Investment | Simultaneous USDA and EU organic 2018/848 compliance opens premium pricing tiers in North American clean-label channels. |
| Clinical Substantiation Infrastructure Buildout | Human intervention studies for cardiovascular endpoints satisfy tightening EFSA novel food evaluation requirements beyond generic antioxidant positioning. |
| Direct Procurement Relationship Establishment | Bilateral orchard-processor-manufacturer arrangements compress raw material qualification from 18 months to 90 days while eliminating distributor markups. |
Research Methodology
A standing panel of extraction technology specialists, Polish farmer cooperative managers, German nutraceutical contract manufacturing procurement leads, and EFSA regulatory affairs consultants provided ongoing calibration throughout the study. Primary interviews with membrane filtration equipment operators and spray-drying facility managers combined with secondary validation from EU Novel Food approval databases, USDA organic certification registries, and Polish agricultural ministry aronia cultivation statistics. Bottom-up volume modeling across product formats triangulated against top-down value estimates derived from contract manufacturer procurement disclosures.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for chokeberry extract shipments, SEC filings from publicly traded nutraceutical ingredient suppliers, and EFSA novel food application tracking databases. The analytical framework segmented the market by product type, application channel, end-user archetype, and distribution model across the analysis window. CAGRs were derived from regression analysis of historical procurement volumes and forward projection of regulatory pathway completion timelines. Forecast inputs incorporated polyphenol bioavailability research publication trends and METI functional food labeling standard evolution.
Underlying assumptions cover EFSA novel food evaluation throughput rates, FDA New Dietary Ingredient notification processing timelines, and EU organic regulation 2018/848 enforcement consistency, with deviation risk concentrated in clinical substantiation study completion delays and climate volatility affecting Poznan-region harvest yields. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Tangerine Extract Market