
 Beverage Flavoring Agent Market | 2026-2036
Beverage Flavoring Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Flavoring Agent Market Outlook
Modular flavor systems is hardening as the dominant configuration pattern, letting beverage brands swap base profiles and functional actives without reformulating entire product lines. Givaudan leverages its integrated taste and nutrition platforms to supply turnkey modular kits to multinational bottlers. Kerry Group anchors its position through captive dairy and plant-protein flavor expertise that extends into hybrid beverage applications. Symrise AG competes by controlling regional botanical supply chains from cultivation through extraction.
Beverage flavoring agents comprise aromatic compounds, essential oils, extracts, and synthesized molecules engineered to impart taste, aroma, or functional character to liquid consumables, typically dosed at parts-per-million to percent-level concentrations depending on carrier medium and heat stability requirements. Their primary purpose is to standardize sensory identity across production batches while masking off-notes from vitamins, proteins, or reduced-sugar bases. Natural flavors and extracts now command the deepest margin pools as procurement contracts attach sustainability premiums to verified-origin botanicals, while powder formulations gain share in ready-to-mix sports and immunity-positioned drinks where shelf stability and transport efficiency outweigh liquid convenience. Emulsion formats occupy a technical leadership niche for fat-soluble flavor delivery in plant-based milk alternatives where homogenization performance determines consumer acceptance.
Regulators including the FDA, EFSA, and FSSAI enforce divergent positive-list frameworks for permitted flavoring substances, creating compliance complexity for suppliers serving multiple geographies from shared manufacturing assets. REACH and evolving EU flavoring regulations are progressively restricting certain synthetic molecules, compelling reformulation investments that favor suppliers with established natural extraction capabilities and regulatory dossier expertise. Stakeholders must monitor accelerating divergence between permissive and precautionary regulatory philosophies when allocating R&D capacity and regional production footprints.
Market Dynamics
Clean-label mandates from retail chains and tightening additive restrictions under EU flavoring regulations are forcing beverage manufacturers to abandon synthetic formulations and rebuild supply chains around verified-origin botanicals.
Growth Catalysts
- EU Flavoring Regulation (EC 1333/2008 amendments):Progressive restriction of artificial molecules redirects formulation budgets toward natural extraction capabilities, expanding addressable demand for botanical-derived alternatives.
- Functional water segment:Brands positioning around immunity and hydration are procuring modular flavor systems that integrate actives with taste masking, creating pull-through for premium natural extracts.
- China and India manufacturing upgrade:Local beverage producers are replacing synthetic flavor systems with premium natural alternatives to serve domestic middle-class consumers and export markets.
Market Restraints
- Botanical raw material volatility:Climate-sensitive cultivation of vanilla, citrus, and spice crops in Madagascar, Indonesia, and India creates input cost instability that compresses margin predictability for extract suppliers.
- Extraction capacity concentration:Supercritical CO2 and cold-press extraction infrastructure clusters in Switzerland, France, and southern Germany, creating geographic supply risk and freight cost burdens for distant formulators.
- Heat stability limitations:Natural flavor compounds degrade under pasteurization and retort processing, restricting application in shelf-stable beverage categories that rely on thermal treatment.
Strategic Opportunities
- India FSSAI clean-label incentives:Domestic procurement preferences for naturally flavored beverages in government and institutional channels create a protected demand pool for local extract suppliers.
- Precision fermentation-derived aromatics:Convergence of synthetic biology with traditional extraction is expanding into cost-competitive production of rare botanical molecules previously limited by agricultural constraints.
- Direct-to-mix ecommerce channels:Ready-to-mix powder formats are bypassing traditional bottler intermediaries, allowing flavor houses to capture margin through subscription and DTC models in North American and European fitness segments.
Industry Challenges
- Regulatory dossier compilation:Suppliers must maintain parallel compliance documentation for FDA, EFSA, and FSSAI positive-list frameworks, stretching technical affairs teams and extending product launch timelines.
- Flavorist talent scarcity:The specialized skill of balancing off-note masking with clean-label ingredient restrictions is concentrating among aging professionals in Grasse, Geneva, and New Jersey corridors, constraining R&D throughput for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Flavoring Agent Market |
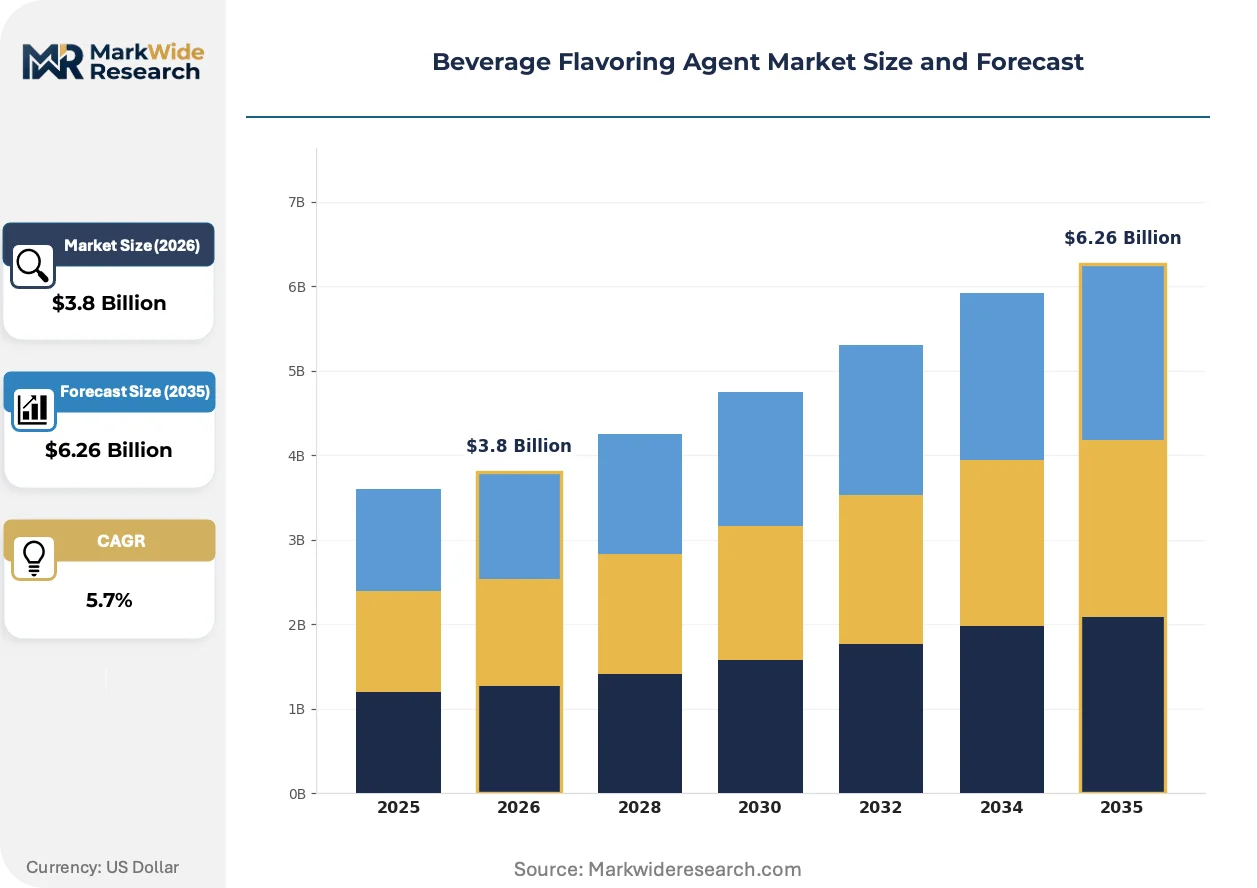
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Essential Oils, Extracts Formulation Type: Liquid, Powder, Concentrate, Emulsion Application: Soft Drinks, Alcoholic Beverages, Dairy Products, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Givaudan, International Flavors & Fragrances, Symrise AG, Sensient Technologies Corporation, Kerry Group, Firmenich, Cargill, Archer Daniels Midland Company, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Flavoring Agent Market Strategic Shifts
Formulation science is pivoting from molecule replication to systems engineering, where flavor houses compete on integration speed rather than single-compound fidelity. This shift rewards suppliers with captive extraction, regulatory dossier depth, and modular platform architectures.
Encapsulation technologies using modified starch and protein-based matrices are expanding into fat-soluble flavor delivery for plant-based milk alternatives. Oat and almond beverage manufacturers in North America and Europe are adopting these systems to overcome homogenization failures that previously limited flavor loadings. The technology is expanding into high-protein sports drinks where thermal stability during UHT processing determines shelf-life claims.
REACH authorization requirements and evolving EU flavoring regulations are progressively delisting synthetic molecules including certain aldehydes and esters. Formulators serving European retail chains must now source natural replacements and validate sensory parity through consumer panels. This regulatory compression most acutely affects citrus and cola flavor categories where synthetic molecules historically dominated cost structures.
Retail chain private-label programs are consolidating procurement around turnkey flavor systems rather than commodity extracts. Beverage brands now specify finished sensory profiles and functional outcomes, transferring formulation risk to suppliers. This specification shift is most visible in German and UK discount retail channels where speed-to-shelf and regulatory compliance are non-negotiable entry requirements.
Beverage Flavoring Agent Market Segmentation
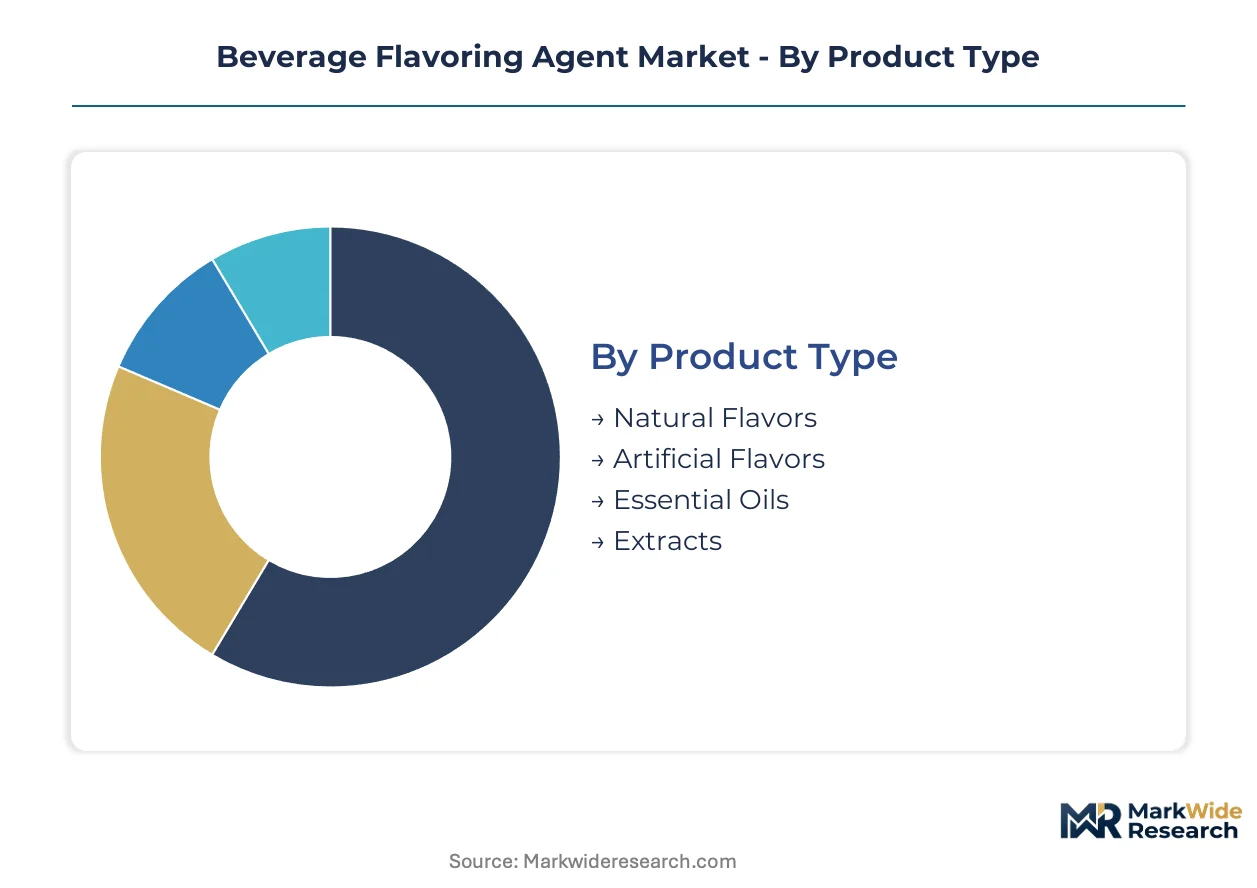
Segmentation in the beverage flavoring agent market reveals where capital commitments concentrate and how procurement patterns diverge across technical requirements. Formulation choices directly determine extraction infrastructure needs, regulatory compliance burdens, and margin structures.
Product Type:
Natural flavors demand the heaviest upfront capital due to cultivation contracts, supercritical CO2 extraction equipment, and traceability verification systems. Artificial flavors require lower fixed investment but face escalating regulatory compliance costs.
- Natural Flavors:Derived from botanical sources through cold-press, solvent, or supercritical extraction methods with verified-origin documentation. Demand concentrates in EU retail chains and North American premium beverage brands where EFSA and FDA clean-label scrutiny is tightening fastest.
- Artificial Flavors:Synthesized molecules engineered to replicate sensory profiles at lower unit cost. Formulators in China and India still procure heavily here, though FSSAI and SAMR are incrementally restricting permitted substance lists.
- Essential Oils:Highly concentrated volatile compounds from citrus peel, spice, and herb distillation.
- Extracts:Water, alcohol, or glycerin-based infusions capturing broader compound profiles.
Most installed capacity flows through Natural Flavors. Expansion is steepest in Extracts as hybrid beverage applications multiply.
Formulation Type:
Volume throughput varies dramatically by physical state, with liquid formats dominating bottler procurement and powder formats accelerating in direct-to-consumer channels.
- Liquid:Standard aqueous or oil-based solutions for immediate dosing into beverage production lines. Soft drink manufacturers in Germany and Mexico run continuous liquid dosing systems that lock in supplier relationships through technical integration.
- Powder:Spray-dried or plated flavor systems optimized for shelf stability and transport efficiency. Sports nutrition brands in the US and UK are shifting procurement here for ready-to-mix ecommerce fulfillment.
- Concentrate:High-potency reduced-water formulations for freight cost minimization.
- Emulsion:Stabilized oil-in-water systems for fat-soluble flavor delivery in plant-based milk alternatives.
Liquid formats retain the largest production footprint. Powder is gaining share fastest in subscription and fitness-directed channels.
Application:
End-use differentiation determines heat stability requirements, regulatory scrutiny intensity, and flavor load specifications.
- Soft Drinks:Carbonated and still beverages requiring flavor systems compatible with acidic pH and pasteurization protocols. Procurement in Brazil and Nigeria favors high-volume, cost-optimized formulations for price-sensitive consumers.
- Alcoholic Beverages:Flavor integration into beer, spirits, and ready-to-drink cocktails demanding ethanol compatibility and maturation stability. Distillers in Scotland and Kentucky specify oak-derived and botanical extracts with proven aging performance.
- Dairy Products:Flavored milk, yogurt drinks, and cream-based beverages requiring emulsion stability.
- Nutraceuticals:Functional beverages with vitamin, mineral, or protein fortification needing off-note masking.
Soft Drinks anchor current volume. Nutraceuticals show the steepest trajectory as immunity and hydration positioning proliferates.
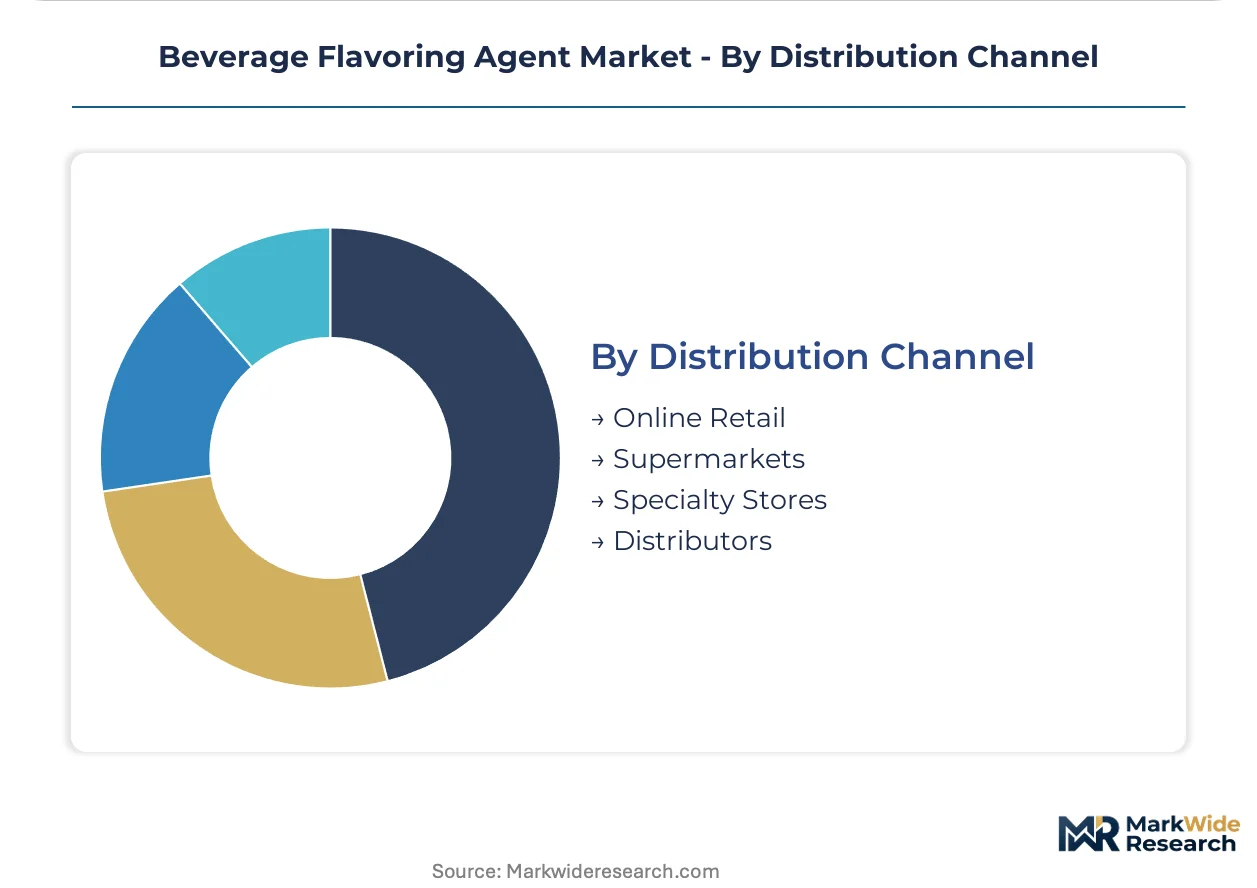
Distribution Channel:
Channel selection shapes minimum order quantities, technical service intensity, and margin capture mechanisms.
- Online Retail:Direct-to-consumer and B2B platform sales enabling small-batch procurement with rapid formulation iteration. Specialty and startup beverage brands in California and the Netherlands source here for speed-to-market.
- Supermarkets:Mass retail procurement through centralized category management with stringent compliance requirements. UK and French retail chains now mandate modular flavor systems with full regulatory dossiers.
- Specialty Stores:Premium and craft-focused channels with technical consultation.
- Distributors:Regional intermediaries providing inventory management and local regulatory navigation.
Distributors still handle the largest flavor volumes. Online Retail is climbing fastest as direct brand relationships bypass traditional bottler intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern flavor extraction industry traces its commercial roots to Grasse, France, where perfume houses first adapted distillation techniques for food applications in the nineteenth century. Swiss and German chemical engineers later industrialized these methods, establishing the supercritical CO2 extraction infrastructure that now supplies premium botanical concentrates worldwide.
Switzerland
Geneva and the Lake Geneva corridor host the densest concentration of flavor extraction R&D facilities outside Paris. REACH authorization requirements and evolving EU flavoring regulations compel Swiss suppliers to maintain parallel natural and synthetic dossiers for cross-border shipment. Basel-based technical teams coordinate regulatory submissions for EFSA, FDA, and FSSAI markets simultaneously.
Germany
Baden-Württemberg and Bavaria concentrate supercritical CO2 extraction capacity serving Central European bottlers. The country's national food regulator enforces strict additive limits that exceed baseline EU requirements, forcing reformulation investments from suppliers seeking supermarket shelf placement. Munich and Stuttgart industrial clusters specialize in emulsion systems for plant-based milk alternatives.
United States
New Jersey and New York Metro corridors retain the deepest flavorist talent pools, though California startup beverage brands now drive procurement innovation. FDA clean-label scrutiny and Prop 65 litigation risk push formulators toward verified-origin botanicals with full supply chain documentation. Los Angeles and San Francisco direct-to-consumer brands bypass traditional bottler intermediaries for powder-format flavor systems.
India
Maharashtra and Karnataka beverage manufacturers upgrade from synthetic to natural flavor systems for domestic middle-class consumers and export markets. FSSAI clean-label incentives create protected demand pools in government and institutional channels. Kerala and Tamil Nadu spice cultivation belts supply cardamom, vanilla, and citrus extracts through cold-press infrastructure.
China
Shanghai and Guangdong beverage producers expand procurement of premium natural extracts as SAMR incrementally restricts permitted synthetic substance lists. Yangtze River Delta formulation labs develop hybrid natural-synthetic systems for cost-sensitive domestic brands. Sichuan and Yunnan botanical cultivation regions supply regional extractors with verified-origin documentation.
Beverage Flavoring Agent Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory dossier depth and extraction infrastructure ownership. The vendor base organizes into three tiers: integrated taste-and-nutrition platforms with captive supply chains, regional specialists controlling single botanical categories, and commodity traders sourcing standardized extracts. Consolidation pressure intensifies as retail chains mandate turnkey modular systems. Dominant competitive moves include backward integration into cultivation contracts and technology licensing for precision fermentation-derived aromatics.
Within the integrated platform tier, Givaudan and Kerry Group exemplify suppliers competing on formulation speed rather than single-compound fidelity. Symrise AG occupies a position anchored in regional botanical supply chain control. Sensient Technologies Corporation and Takasago International Corporation represent the geographic diversification archetype, maintaining technical service presence across multiple regulatory jurisdictions. Firmenich and International Flavors & Fragrances sit within the premium-tier vector where taste masking expertise for functional beverages commands pricing power.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Symrise AG |
| Sensient Technologies Corporation |
| Kerry Group |
| Firmenich |
| Cargill |
| Archer Daniels Midland Company |
| Takasago International Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap extract specialists in Grasse and Geneva anchor premium pricing through captive cultivation contracts, while private-equity-rolled-up commodity traders compete on volume scale without backward integration. This ownership split concentrates margin capture upstream with botanical-origin verifiers and compresses returns for distributors lacking extraction assets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified natural extracts from FSSAI-compliant regional grades and commodity synthetic molecules. Price differentiation rests on certification tier and volume scale, with EU retail chains paying sustainability premiums for verified-origin botanicals. Pricing pressure stems from climate-driven vanilla and citrus crop failures in Madagascar and Indonesia. Economy-tier synthetic flavors face the sharpest buyer price sensitivity as Chinese and Indian manufacturers upgrade formulations.
Supply Chain Analysis
Direct-to-bottler channels handle multinational procurement through technical integration contracts in Germany and Mexico. Geographic supply concentrates in Switzerland, France, and southern Germany for supercritical CO2 extraction infrastructure. Raw material dependencies include Madagascar vanilla, Indonesian citrus peel, and Indian spice crops. Supply chain risk centers on single-source vulnerability for rare botanical molecules with no agricultural substitutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beverage flavoring agent market functions as a geographic-arbitrage play where EFSA regulatory stringency in Europe creates 40-60% pricing premiums over FSSAI-monitored Indian supply, rewarding suppliers with dual-hemisphere extraction footprints.
For Market Incumbents: Cement regulatory dossier depth as the primary defensive moat against precision fermentation disruptors by maintaining parallel FDA, EFSA, and FSSAI compliance teams. Lock in long-term cultivation contracts for vanilla and citrus in climate-resilient zones before agricultural constraints tighten. Prioritize backward integration into Kerala and Tamil Nadu spice processing to secure cardamom and extract supply.
For New Entrants and Emerging Players: Precision fermentation-derived rare botanical molecules offer a technology-first wedge into cost-prohibitive natural flavor categories previously limited by agricultural constraints. Target India's FSSAI clean-label procurement incentives in government and institutional channels as the most penetrable white-space opportunity. Lead with direct-to-mix powder formats for North American fitness ecommerce subscriptions.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists controlling single-botanical supply chains without integrated formulation platforms. Long-term viability over a 5-10 year window favors extractors with verified-origin documentation systems and supercritical CO2 asset ownership. Watch for SAMR synthetic restriction announcements as the inflection signal triggering accelerated Chinese natural flavor procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captures margin from Madagascar vanilla and Indonesian citrus through owned agricultural assets. |
| Precision Fermentation Scale-Up | Produces rare botanical molecules like saffron and vanilla without climate-dependent crop cycles. |
| Modular Flavor System Licensing | Enables Givaudan-style turnkey supply to multinational bottlers seeking formulation speed. |
| Regulatory Dossier Expansion | Opens EFSA, FDA, and FSSAI markets simultaneously for cross-border shipment compliance. |
| Direct-to-Mix Channel Development | Bypasses traditional bottler intermediaries for subscription revenue in fitness-directed ecommerce. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flavor house R&D directors, beverage manufacturer procurement leads, supercritical extraction plant managers, and retail chain category buyers with secondary validation. Secondary sources included EFSA flavoring substance databases, FDA GRAS notices, FSSAI additive regulations, and customs trade records for botanical imports. Bottom-up volume modeling and top-down value triangulation anchored market size estimates.
Comparable-period anchoring linked historical extraction capacity utilization to forward procurement contract visibility across the projection horizon. Segmentation dimensions modeled included natural versus artificial origin, liquid versus powder versus emulsion formulation, soft drink versus nutraceutical application, and supermarket versus online retail channel. CAGRs derived from supply-side capacity expansion plans and demand-side clean-label procurement shifts. Forecast inputs incorporated REACH authorization timelines and SAMR synthetic restriction trajectories.
The model holds under stable regulatory enforcement intensity; deviation in EFSA or SAMR delisting schedules would shift natural flavor demand curves. Forecasts reflect assumptions about climate stability in Madagascar and Indonesia, precision fermentation cost reduction curves, and retail chain clean-label mandate adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market