
 Fiber Optic Test Equipment (FOTE) Market | 2026-2036
Fiber Optic Test Equipment (FOTE) Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Test Equipment (FOTE) Market Foresight
Silicon photonics is decoupling test equipment architectures from legacy discrete component designs, enabling smaller form factors and lower per-port validation costs. EXFO Inc. leverages vertically integrated photonic chip testing to sustain margin advantages in high-density data center applications. Anritsu Corporation anchors its competitive position through specialized mmWave-to-optical convergence instruments for 5G fronthaul networks.
Fiber optic test equipment encompasses instruments that characterize optical fiber performance through parameters such as insertion loss, return loss, and optical time domain reflectometry across wavelengths from 1260 nm to 1625 nm, serving the essential function of certifying network integrity before service activation. OTDR and power meter product types currently occupy the largest installed base, while fusion splicer demand is accelerating fastest among data center end users deploying ribbon fiber architectures. Network monitoring applications now generate the highest-margin recurring revenue streams as telecom providers shift from capital-intensive installation contracts toward subscription-based remote diagnostics.
The FCC's broadband equity access and deployment program shapes procurement standards for US-based operators, while the EU AI Act and CSRD frameworks are beginning to influence environmental disclosure requirements for European equipment vendors. China's MIIT enforces GB standards compliance for optical test instruments deployed in state-backed fiber infrastructure projects. Stakeholders must monitor how divergent national certification regimes affect product platform commonality and service localization strategies.
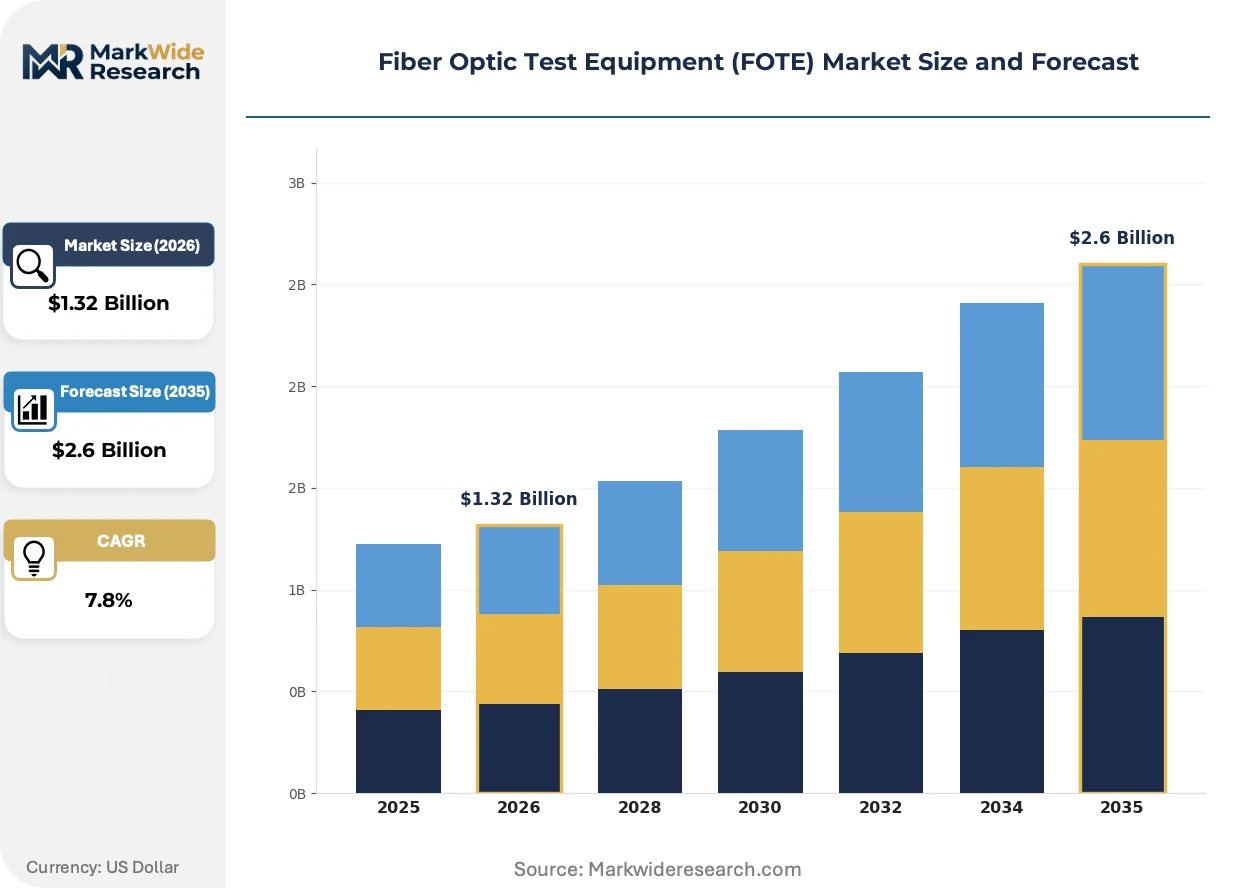
Market Dynamics
Silicon photonics is compressing test equipment form factors while decoupling architectures from legacy discrete component designs, forcing incumbents to rebuild hardware platforms around photonic integrated circuits or surrender port-density advantages to specialized challengers.
Growth Catalysts
- FCC Broadband Equity Programs:The FCC's broadband equity access and deployment program mandates standardized certification protocols that accelerate replacement cycles for legacy field instruments across US operator fleets.
- Data Center Ribbon Fiber Deployment:Hyperscale facilities deploying multi-fiber push-on architectures are electrifying demand for fusion splicers capable of mass-fusion termination.
- China MIIT GB Standards Enforcement:China's Ministry of Industry and Information Technology requires GB-compliant optical test instruments for state-backed fiber infrastructure, creating captive procurement pools for certified vendors.
Market Restraints
- Indium Phosphide Supply Concentration:Photonic integrated circuit fabrication depends on indium phosphide substrates concentrated among limited specialty foundries, exposing equipment margins to raw material volatility.
- Calibration Equipment Lead Times:National metrology institutes in Germany and Japan control primary optical power standards, creating bottlenecks for manufacturers seeking traceable calibration chains.
- Copper-to-Fiber Substitution in Short-Reach:Active optical cable assemblies with embedded signal conditioning are displacing discrete fiber test requirements in rack-scale interconnects below 100 meters.
Strategic Opportunities
- India BharatNet Phase III:India's rural broadband expansion under the Department of Telecommunications creates underpenetrated demand for ruggedized OTDR units capable of dusty, high-temperature field operation.
- EU CSRD Environmental Disclosure:The Corporate Sustainability Reporting Directive incentivizes European operators to specify test equipment with modular, repairable architectures that extend service life and reduce e-waste liabilities.
- AI-Driven Predictive Maintenance:Machine learning algorithms processing OTDR trace data are converging with cloud analytics platforms to enable subscription-based remote fiber monitoring services.
Industry Challenges
- Photonic Integration Specialist Scarcity:Equipment manufacturers face acute competition for silicon photonics design engineers capable of translating discrete optical benches onto monolithic chips.
- Multi-Standard Certification Overlap:Vendors must simultaneously satisfy FCC Part 15 emissions, EU CE marking, and China GB electromagnetic compatibility requirements, fragmenting product variant strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Test Equipment (FOTE) Market |
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.6 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OTDR, Fusion Splicer, Power Meter, Light Source End User: Telecom Providers, Data Centers, Enterprises, Government Agencies Application: Installation, Maintenance, Network Monitoring, Testing Technology: Single Mode, Multimode, Hybrid, Optical Time Domain |
| Companies Covered | EXFO Inc., Anritsu Corporation, VIAVI Solutions Inc., Fluke Corporation, Keysight Technologies, Yokogawa Electric Corporation, VeEX Inc., Tektronix Inc., AFL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Test Equipment (FOTE) Market Shifts & Advancements
Test instrumentation architectures are bifurcating between portable field units optimized for technician productivity and rack-mounted systems designed for autonomous data center monitoring, with silicon photonics enabling both trajectories through shared component platforms.
Coherent optical engines operating at 400G and 800G line rates are electrifying test equipment specifications, forcing manufacturers to integrate complex modulation format analysis into previously simple power-and-loss instruments. Data center operators deploying CPO (co-packaged optics) architectures now demand test systems capable of validating lane-level performance across 51.2 Tbps switch capacities. This capability compression is collapsing the historical separation between physical layer and protocol test functions.
The EU AI Act's risk classification framework is reshaping procurement documentation for automated fiber monitoring systems deployed in critical infrastructure. European operators must now maintain algorithmic transparency logs for AI-driven fault prediction tools, adding compliance overhead to software-defined test platforms. German and French utilities are responding by requiring vendor-provided model cards detailing training data provenance and decision boundary specifications.
Telecom procurement departments are unbundling hardware acquisition from calibration and firmware update services, treating test equipment as connected assets rather than depreciated capital. US tier-one operators now structure five-year total-cost-of-ownership contracts where remote diagnostics subscriptions exceed upfront instrument pricing. This preference shift concentrates vendor relationships among platforms with robust API architectures and cloud-native telemetry pipelines.
Fiber Optic Test Equipment (FOTE) Market Segmentation
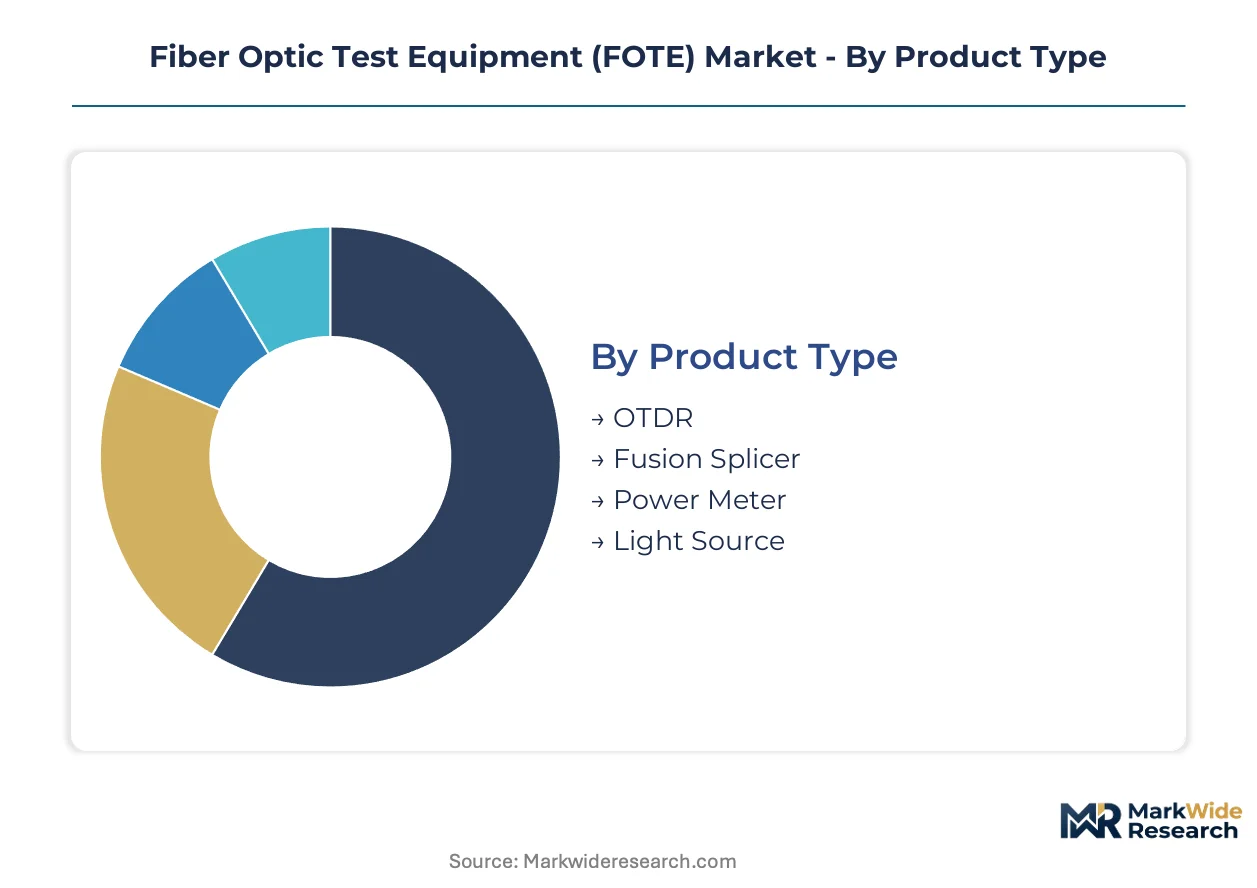
Test equipment procurement patterns diverge sharply across deployment contexts. Product specifications, end-user operational models, and technology choices each create distinct margin structures and replacement cycles that vendors must navigate.
Product Type:
Silicon photonics is compressing form factors across all instrument categories while preserving measurement fidelity.
- OTDR:Optical time domain reflectometers transmit laser pulses through fiber to locate faults, splice points, and bends with sub-meter precision. Telecom providers in the United States and Germany specify these for outside plant certification, with FCC-mandated documentation requirements accelerating fleet replacement cycles.
- Fusion Splicer:Electric arc fusion systems align and weld fiber ends for low-loss permanent connections. Data centers deploying ribbon fiber architectures in China and the United States are electrifying demand for mass-fusion models capable of terminating twelve fibers simultaneously.
- Power Meter:Calibrated photodetectors measure absolute optical power levels across standard telecom wavelengths. Field technicians rely on these for quick loss verification during installation.
- Light Source:Stabilized laser or LED emitters provide reference signals for insertion loss testing. These pair with power meters in basic certification kits.
OTDR leads on scale; fusion splicer leads on momentum.
End User:
Procurement authority concentrates differently across customer types, shaping contract structures and service attach rates.
- Telecom Providers:Tier-one operators in the United States, China, and Germany drive volume through standardized fleet purchases. These entities are shifting from capital acquisition to five-year total-cost-of-ownership contracts where remote diagnostics subscriptions exceed upfront instrument pricing.
- Data Centers:Hyperscale facilities and colocation operators demand rack-mounted autonomous monitoring systems. Ribbon fiber deployment and co-packaged optics validation requirements are collapsing the historical separation between physical layer and protocol test functions.
- Enterprises:Corporate IT departments purchase portable units for campus network maintenance. Procurement typically occurs through distributor channels with limited service bundling.
- Government Agencies:Defense and utility operators specify ruggedized instruments with extended calibration intervals. Bureaucratic procurement cycles extend replacement timelines versus commercial counterparts.
Telecom providers command volume; data centers command margin expansion.
Application:
Revenue model transformation varies by operational phase, with monitoring applications generating the highest-margin recurring streams.
- Installation:Initial fiber deployment requires comprehensive certification before service activation. Technicians execute insertion loss, return loss, and OTDR validation across all fiber pairs.
- Maintenance:Reactive troubleshooting and scheduled inspection preserve network integrity. Field teams prioritize portable instruments with simplified user interfaces.
- Network Monitoring:Continuous remote diagnostics through permanently installed OTDR units enable subscription-based service models. AI-driven predictive maintenance algorithms processing trace data are converging with cloud analytics platforms.
- Testing:Manufacturing and R&D environments require laboratory-grade precision for component characterization. These applications demand NIST-traceable calibration chains.
Installation anchors absolute revenue; network monitoring anchors profitability trajectories.
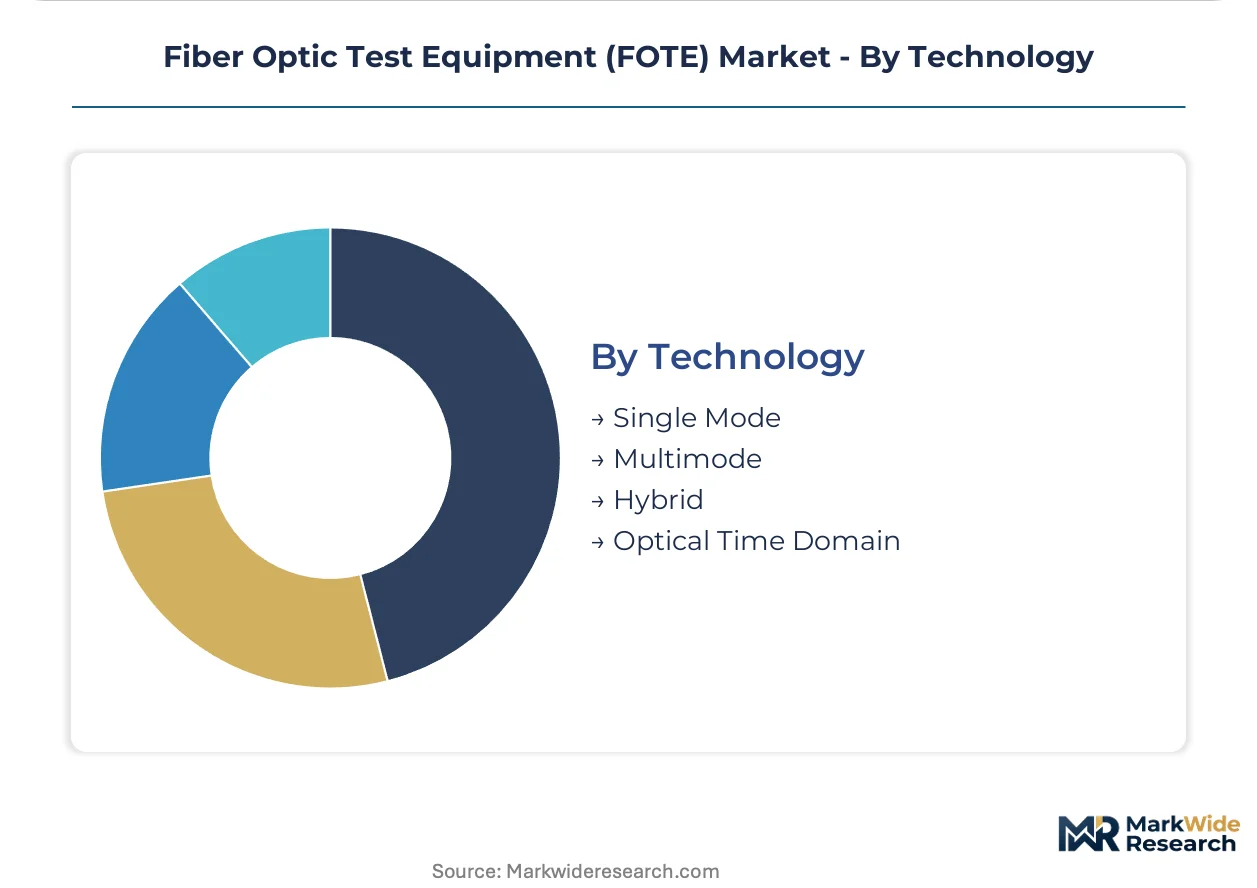
Technology:
Wavelength and mode specifications determine instrument compatibility with deployed fiber infrastructure.
- Single Mode:9-micron core fiber designed for long-haul and metro networks using 1310 nm and 1550 nm wavelengths. Dominates telecom provider procurement for outside plant applications.
- Multimode:50-micron or 62.5-micron core fiber for short-reach data center interconnects. VCSEL-based 850 nm testing dominates this segment.
- Hybrid:Instruments supporting both single-mode and multimode operation through swappable modules. Enterprise and contractor fleets favor these for operational flexibility.
- Optical Time Domain:Specialized OTDR architectures optimized for specific wavelength ranges or dynamic range requirements. Sub-segment includes coherent detection systems for 400G/800G validation.
Single mode leads on installed base; coherent optical time domain systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley data center clusters and Shenzhen manufacturing hubs concentrate procurement authority for high-density test instrumentation across divergent regulatory environments.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth drive fusion splicer demand for ribbon fiber architectures. The FCC's Broadband Equity Access and Deployment program mandates OTDR certification standards that accelerate replacement cycles for legacy field instruments. Atlanta and Phoenix emerge as secondary logistics hubs for ruggedized technician equipment serving rural broadband contractors.
China
State-backed fiber-to-the-premises rollouts in Jiangsu and Guangdong provinces electrify procurement volumes for GB-compliant optical test instruments. MIIT enforcement of national standards creates captive certification requirements for equipment deployed in government infrastructure projects. Chengdu and Wuhan house emerging photonic integrated circuit foundries that compress test equipment form factors through local component sourcing.
Germany
Deutsche Telekom's outside plant modernization concentrates demand for OTDR units with sub-meter fault precision in North Rhine-Westphalia and Bavaria. The EU AI Act's risk classification framework reshapes procurement documentation for automated fiber monitoring systems in critical utility networks. Berlin-Brandenburg hosts specialized calibration laboratories serving Central European metrology traceability requirements.
India
BharatNet Phase III rural expansion under the Department of Telecommunications generates underpenetrated demand for dust-resistant OTDR units in Rajasthan and Uttar Pradesh. BIS certification requirements for optical test instruments deployed in government-backed projects create compliance barriers for uncertified imports. Bangalore and Hyderabad clusters incubate domestic assembly operations for cost-optimized field technician kits.
Japan
NTT's 5G fronthaul densification drives mmWave-to-optical convergence instrument demand in Tokyo-Osaka corridor data centers. METI standards for photonic device reliability influence procurement specifications for high-precision power meters in submarine cable landing stations. Yokohama and Nagoya maintain specialized foundry relationships for indium phosphide substrate supply to test equipment manufacturers.
Fiber Optic Test Equipment (FOTE) Market Competitive Landscape
Global majors compete with regional champions across certification compliance and service localization dimensions. The vendor base stratifies between integrated photonics specialists and legacy discrete component manufacturers. Three archetypes dominate: silicon photonics platform builders, mmWave-optical convergence instrument specialists, and ruggedized field equipment fabricators. Competitive moves concentrate on backward integration into photonic integrated circuit supply and API-native software platform development.
Among North American platform builders, EXFO Inc. and VIAVI Solutions Inc. occupy positions emphasizing cloud-native telemetry architectures. Japanese precision instrument heritage manifests in Yokogawa Electric Corporation and Anritsu Corporation, exemplifying mmWave-to-optical convergence specialization. These entities represent divergent strategic bets on whether test equipment becomes a connected service asset or remains a capital-acquisition category.
| Leading Market Players |
|---|
| EXFO Inc. |
| Anritsu Corporation |
| VIAVI Solutions Inc. |
| Fluke Corporation |
| Keysight Technologies |
| Yokogawa Electric Corporation |
| VeEX Inc. |
| Tektronix Inc. |
| AFL |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up test equipment specialists have consolidated fragmented field instrument portfolios across North America and Europe, compressing procurement costs for telecom operators while enforcing disciplined pricing tiers calibrated to GB, FCC, and CE certification levels. This ownership pattern concentrates bargaining power against indium phosphide substrate suppliers and photonic foundry capacity, creating asymmetric margin pressure that flows downstream into five-year total-cost-of-ownership contract structures.
Pricing Analysis
Input-cost pass-through from indium phosphide substrate volatility and silicon photonics foundry premiums shapes instrument pricing across three tiers calibrated to certification grade and after-sales service bundling. Premium OTDR units with NIST-traceable calibration chains command substantial markups over economy field kits lacking remote diagnostics APIs. Price erosion runs through economy-tier portable power meters as Chinese domestic manufacturers expand BIS-certified assembly capacity for India's BharatNet contractors. Data center operators exhibit lowest price sensitivity, prioritizing autonomous monitoring uptime over per-unit acquisition cost, while rural broadband contractors in the United States face acute budget constraints under FCC reimbursement schedules.
Supply Chain Analysis
Photonic integrated circuit fabrication rests on Japanese and German specialty chemical producers for indium phosphide substrates, with Taiwan and South Korea providing advanced packaging capacity for coherent optical engines. Test equipment manufacturers source stabilized laser diodes from Japanese precision optics houses and calibrated photodetectors from German metrology institutes. Single-source vulnerability concentrates in primary optical power standards controlled by national metrology institutes in Germany and Japan, creating calibration bottlenecks. Distribution runs through authorized distributor networks for field technician kits, while hyperscale data centers procure rack-mounted systems through direct vendor relationships with embedded firmware subscription terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FCC's Broadband Equity Access and Deployment program functions as a regulatory compounder, mandating standardized OTDR certification protocols that accelerate replacement cycles and concentrate procurement authority among API-native platform vendors.
For Market Incumbents: Anchor defensive positioning through backward integration into photonic integrated circuit supply chains, capturing captive margin from silicon photonics component platforms. Fortify against emerging Chinese domestic challengers by deepening GB standards compliance engineering for state-backed fiber infrastructure pools. Prioritize cloud-native telemetry architecture investment to sustain subscription revenue attach rates as telecom procurement shifts from capital acquisition to operational expenditure models. For New Entrants and Emerging Players: Capture white-space opportunity in India's BharatNet Phase III rural expansion, where dust-resistant OTDR units face underpenetrated demand and BIS certification barriers filter out uncertified imports. Target data center ribbon fiber deployment segments in Northern Virginia and Dallas-Fort Worth, where mass-fusion splicer procurement concentrates among hyperscale operators. Pursue go-to-market partnerships with regional calibration laboratories to overcome metrology traceability bottlenecks that disadvantage smaller vendors. For Investors and Strategic Acquirers: Telecom equipment manufacturers seeking optical test capability adjacencies represent the most active acquirer category in this space, driven by converged 5G fronthaul and fiber infrastructure deployment strategies. Long-term viability hinges on software-defined test platform transitions over hardware-centric legacy models. Acquisition target archetypes include silicon photonics design houses with coherent optical engine expertise and API-native remote monitoring software developers. Watch for MIIT procurement pool certification announcements as inflection indicators for Chinese market access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Backward Integration | Captures margin compression from indium phosphide substrate volatility while enabling form factor advantages. |
| Cloud-Native Telemetry Platform Development | Aligns with US tier-one operator preference for subscription-based remote diagnostics exceeding upfront pricing. |
| GB Standards Compliance Certification | Unlocks captive procurement pools in China's state-backed fiber-to-the-premises infrastructure projects. |
| AI-Driven Predictive Maintenance Service Launch | Addresses EU AI Act algorithmic transparency requirements while generating highest-margin recurring revenue streams. |
| Ruggedized Field Unit Localization for India | Positions for BharatNet Phase III rural expansion under BIS certification mandates and dusty environment specifications. |
Research Methodology
Coverage spans the United States, China, Germany, India, and Japan, with primary inputs from each market's distinct regulatory and procurement environment. Field research combined structured interviews with network engineering directors at tier-one telecom operators, data center infrastructure procurement leads, optical test equipment product managers, and national metrology institute calibration specialists. Secondary validation drew from FCC broadband deployment filings, MIIT GB standards documentation, EU AI Act implementation guidance, SEC 10-K equipment vendor disclosures, and hyperscaler capital expenditure reports. Bottom-up instrument shipment data triangulated against top-down infrastructure investment forecasts across the analysis window.
Rate-of-change decomposition anchored the analytical framework, segmenting growth drivers by product type, end user procurement model, application revenue structure, and technology wavelength specification. Modeled dimensions included OTDR versus fusion splicer versus power meter category trajectories, telecom provider fleet replacement cycles versus data center autonomous monitoring adoption, installation versus network monitoring service revenue mix, and single-mode versus coherent optical time domain system technology shifts. CAGRs were derived from regression analysis against fiber infrastructure deployment pipelines, with specific weighting for FCC reimbursement schedule timing and China MIIT procurement batch releases.
Indium phosphide supply disruption, divergent national certification regime fragmentation, and AI Act compliance cost inflation are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding silicon photonics yield improvement trajectories and cloud telemetry platform adoption curves. A small set of named triggers—MIIT procurement pool announcements, FCC BEAD program milestone releases, and EU CSRD environmental disclosure enforcement patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Pump Testers Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Industrial Direct Radiography Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Fluorometers Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Test Benches Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Analog Multimeters Market
Test and Measurement
Digital Oscilloscope Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market