
 Norway Data Center Physical Security Market | 2026-2036
Norway Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Physical Security Market Insights
Multi-source procurement for integrated security stacks is repositioning how Norwegian data center operators balance vendor lock-in against system interoperability. Axis Communications AB leverages its Nordic engineering heritage to dominate video surveillance deployments in Oslo-region facilities. Schneider Electric anchors power-integrated physical security solutions, merging electrical infrastructure with access control. Siemens AG competes through building management system convergence, offering unified command platforms.
Norway Data Center Physical Security encompasses perimeter barriers, biometric access control, video analytics, intrusion detection, and environmental monitoring systems engineered to protect critical infrastructure from unauthorized physical access, sabotage, and espionage. Systems typically integrate IP-based cameras with minimum 4K resolution, multi-factor authentication readers, and seismic sensors rated for Nordic climate extremes to ensure continuous facility protection. Surveillance Systems capture the largest value pool given regulatory requirements for audit-ready footage retention across colocation and enterprise deployments. Access Control represents the fastest-expanding segment as biometric systems displace legacy card readers in new hyperscale builds. Managed Services installations are gaining share as operators outsource security operations to specialists capable of round-the-clock monitoring compliance.
Norwegian data center operators must comply with the Personal Data Act implementing GDPR, the EU NIS2 Directive transposed through national cybersecurity legislation, and DSB directives on critical infrastructure protection. DSB facility security assessments now mandate layered physical access controls for operators designated as critical infrastructure, directly shaping procurement specifications. Stakeholders must monitor whether Norway's forthcoming critical infrastructure regulations extend physical security audits to Tier II and III facilities previously exempt from mandatory inspections.
Market Dynamics
Norwegian data center operators face mounting pressure from the EU NIS2 Directive's transposition into national law, which mandates layered physical access controls and audit-ready surveillance infrastructure for critical infrastructure designation.
Growth Catalysts
- Regulatory Mandate Expansion:The EU NIS2 Directive's implementation through Norwegian cybersecurity legislation compels Tier II and III facilities to upgrade perimeter protection and biometric access systems to meet DSB facility security assessment standards.
- Hyperscale Facility Proliferation:Cloud service providers expanding footprints across the Oslo metropolitan area drive demand for integrated security stacks capable of protecting submarine cable landing zones and high-density compute environments.
- Climate-Resilient Infrastructure:Seismic sensors and environmental monitoring systems rated for Nordic climate extremes are becoming standard procurement specifications as operators harden facilities against temperature fluctuations and geological risks.
Market Restraints
- Specialized Labor Scarcity:Norway's limited pool of certified security systems integrators familiar with DSB compliance protocols creates bottlenecks for facility commissioning timelines.
- Import Dependency for Biometric Hardware:Multi-factor authentication readers and 4K IP camera assemblies concentrate manufacturing in Asian supply chains, exposing Norwegian operators to extended lead times and currency volatility.
- Stringent Data Localization Requirements:The Personal Data Act's implementation of GDPR restricts cross-border footage storage and processing, complicating managed security service provider architectures.
Strategic Opportunities
- Tromsø and Northern Norway Expansion:Arctic data center development for high-performance computing and research applications creates demand for physical security systems engineered for sub-zero operational envelopes.
- Building Management System Convergence:Integration of access control, power monitoring, and environmental sensors into unified command platforms offers vendors differentiation through reduced operator cognitive load.
- Managed Security Service Outsourcing:Round-the-clock monitoring compliance requirements are pushing colocation operators toward specialist security operations centers rather than in-house staffing models.
Industry Challenges
- Legacy Card Reader Migration Complexity:Biometric system deployment in existing facilities requires phased retrofitting without disrupting 24/7 operations, demanding careful sequencing of reader replacement and database migration.
- Interoperability Certification Delays:Multi-vendor security stack integration faces prolonged validation cycles as operators verify IP-based camera, access control, and intrusion detection system compatibility across proprietary protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Physical Security Market |
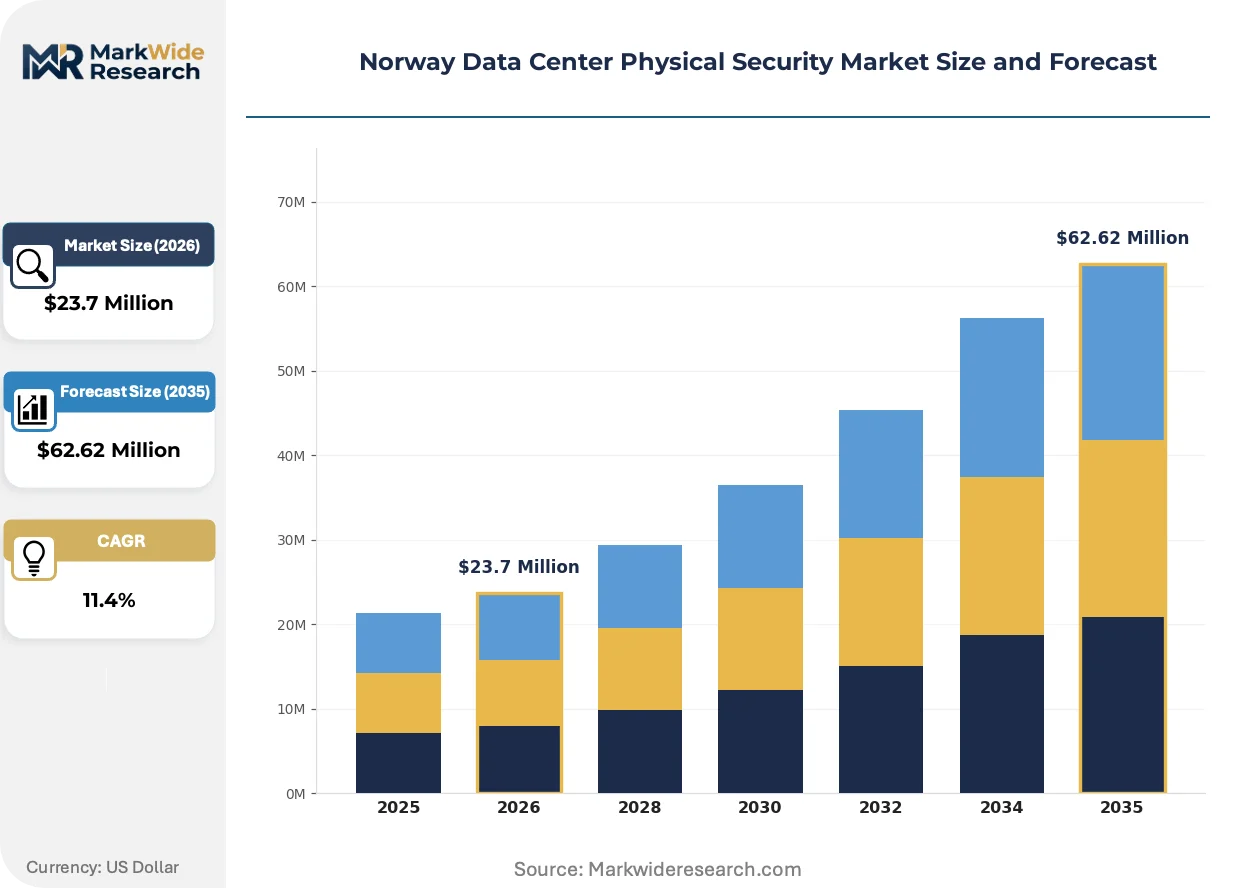
| Market Size in 2026 | $23.7 Million |
| Market Size in 2035 | $62.62 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Access Control, Surveillance Systems, Intrusion Detection, Fire Safety Installation Type: On-premises, Offsite, Managed Services, Hybrid Solutions End User: Colocation Providers, Enterprises, Cloud Service Providers, Government Technology: Biometric Systems, Smart Locks, CCTV, Alarms |
| Companies Covered | Axis Communications AB, ABB Ltd, Bosch Sicherheitssysteme GmbH, Johnson Controls, Honeywell International Inc, Siemens AG, Schneider Electric, Cisco Systems Inc, ASSA ABLOY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Physical Security Market Trends and Innovations
Video analytics powered by edge computing is transforming how Norwegian facilities process surveillance data, reducing bandwidth requirements while enabling real-time threat detection at perimeter boundaries.
Artificial intelligence-enhanced video analytics is rewriting facility protection protocols by enabling automated anomaly detection without continuous human monitoring. Hyperscale operators in the Oslo region are deploying these systems at greenfield builds to minimize security operations center headcount. The technology is compressing response times from minutes to seconds for unauthorized perimeter breaches.
Norway's transposition of the EU NIS2 Directive into national cybersecurity legislation is mandating documented physical access control audits for critical infrastructure operators. The DSB now requires layered authentication systems with audit trails retained for regulatory inspection. Colocation providers are responding by consolidating vendor relationships to simplify compliance documentation.
Security-as-a-service procurement models are displacing capital-intensive equipment purchases among mid-sized enterprise data center operators. Subscription-based managed security offerings from specialized providers are capturing share as buyers prioritize operational expenditure predictability over asset ownership. This shift concentrates most visibly in Bergen and Trondheim secondary markets where facility scale does not justify dedicated security operations teams.
Norway Data Center Physical Security Market Segmentation
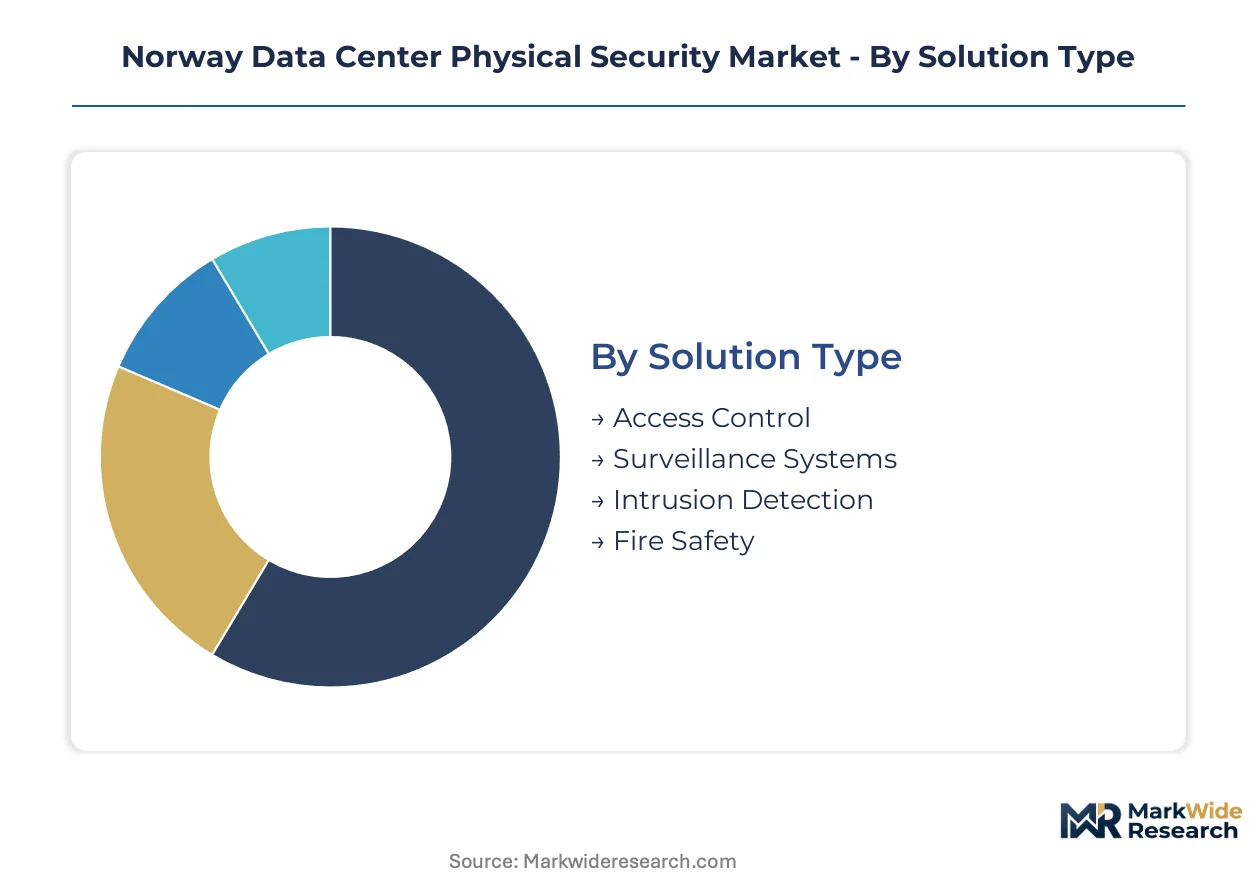
Physical security procurement in Norwegian data centers fragments across solution architectures, deployment models, and compliance requirements. Understanding these dimensions reveals where operators concentrate spending and where technology substitution is reshaping competitive dynamics.
Solution Type:
Standardized perimeter barriers dominate Tier II facilities while hyperscale operators demand customized integrated stacks with unified command interfaces.
- Access Control:Biometric readers and multi-factor authentication systems displace legacy card readers in new Oslo-region builds. Hyperscale facilities drive specification upgrades as DSB facility security assessments mandate layered authentication with audit-ready trails.
- Surveillance Systems:IP-based cameras with minimum 4K resolution form the core infrastructure for regulatory footage retention. Colocation providers in the Oslo metropolitan area prioritize these deployments to satisfy DSB inspection protocols and submarine cable landing zone protection mandates.
- Intrusion Detection:Perimeter sensors and seismic monitoring rated for Nordic climate extremes protect against unauthorized physical access and geological risks.
- Fire Safety:Suppression systems integrated with environmental monitoring ensure continuous facility protection against thermal events.
Leading the category by volume: Surveillance Systems. Growing fastest: Access Control.
Installation Type:
Capital expenditure preference varies sharply by facility scale, with mid-sized operators gravitating toward operational expenditure models that convert fixed costs to subscription structures.
- On-premises:Dedicated security infrastructure owned and operated by the data center operator. Enterprise facilities in Bergen and Trondheim favor this model to maintain direct control over sensitive authentication databases.
- Offsite:Security operations conducted from remote monitoring centers. Cloud service providers leverage this architecture to centralize protection across distributed Oslo-region footprints.
- Managed Services:Specialist providers deliver round-the-clock monitoring compliance through subscription arrangements. Secondary market operators adopt these offerings to avoid dedicated security operations center staffing costs.
- Hybrid Solutions:Blended architectures combining on-premises hardware with outsourced monitoring functions. Colocation providers deploy this approach to balance control requirements against operational complexity reduction.
Highest deployment concentration: On-premises. Expanding most quickly: Managed Services.
End User:
Procurement sophistication correlates directly with facility scale and regulatory exposure, creating distinct specification tiers across buyer categories.
- Colocation Providers:Multi-tenant facilities serving enterprise clients with heterogeneous security requirements. These operators standardize on integrated security stacks to simplify compliance documentation across diverse customer contracts.
- Enterprises:Single-tenant facilities with customized protection protocols aligned to internal risk management frameworks. Financial services and research institutions in Oslo drive demand for biometric access control with granular audit capabilities.
- Cloud Service Providers:Hyperscale operators with homogeneous, high-density compute environments. These buyers prioritize automated threat detection and minimal security operations center headcount at greenfield builds.
- Government:Critical infrastructure facilities subject to DSB facility security assessments and national cybersecurity legislation. Layered physical access controls with documented audit trails are mandatory procurement specifications.
Dominant buyer by project volume: Colocation Providers. Steepest expansion trajectory: Cloud Service Providers.
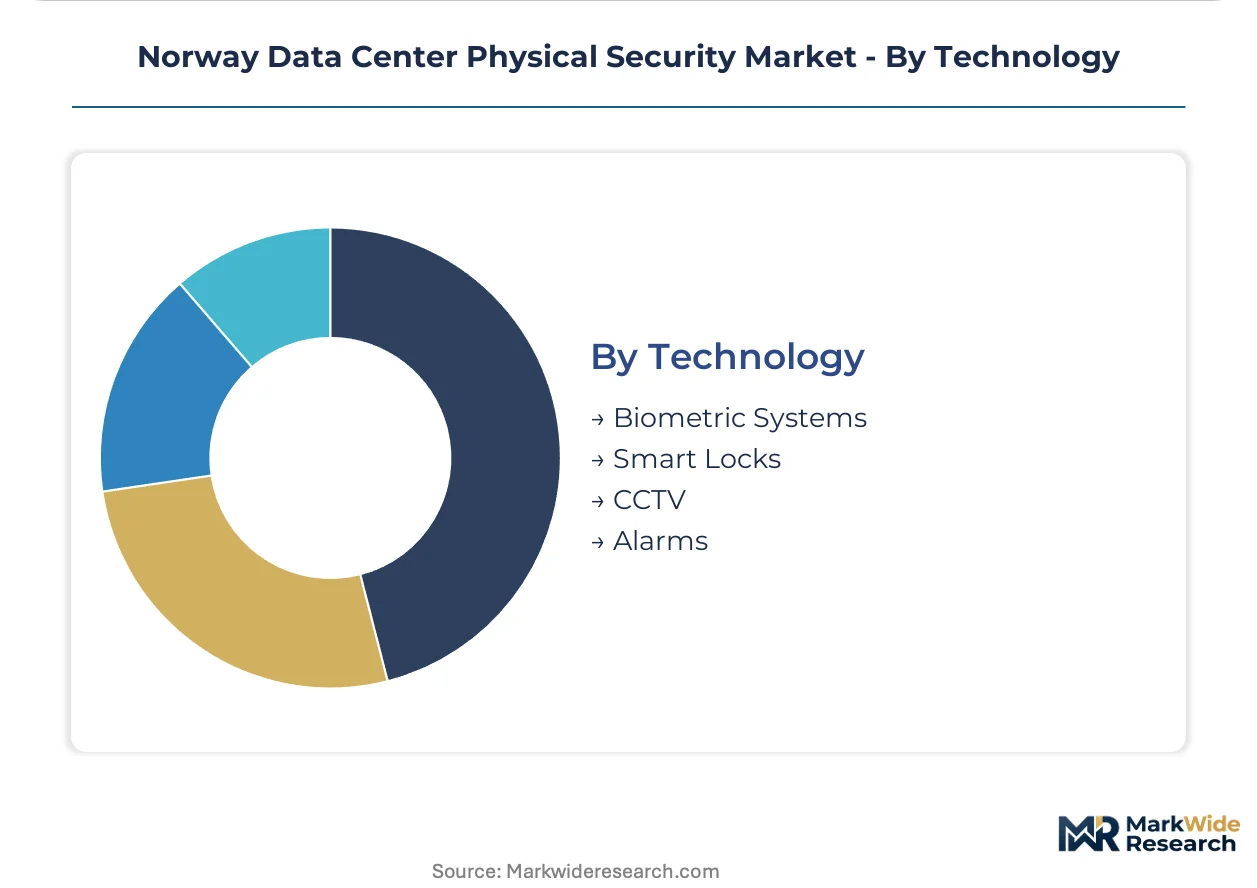
Technology:
Technology selection reflects a maturity gradient, with established CCTV infrastructure coexisting alongside emerging biometric and smart lock deployments.
- Biometric Systems:Fingerprint, iris, and facial recognition readers replacing card-based authentication. New hyperscale builds in the Oslo metropolitan area specify these systems to satisfy NIS2 Directive transposition requirements.
- Smart Locks:Network-connected access points with remote management capabilities. These devices enable centralized credential revocation and real-time status monitoring across distributed facility footprints.
- CCTV:Conventional video surveillance infrastructure with analog-to-IP migration ongoing. Legacy facilities maintain these systems while planning phased upgrades to 4K resolution standards.
- Alarms:Perimeter and internal intrusion notification systems integrated with central monitoring stations. Environmental sensors trigger these devices for temperature and seismic anomaly detection.
Widest installed base: CCTV. Gaining share fastest: Biometric Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing zones along Norway's coastline anchor data center development patterns across the Nordic region. Oslo's metropolitan fiber corridors concentrate hyperscale facility investment, while Arctic latitudes attract high-performance computing deployments seeking natural cooling advantages.
Oslo Metropolitan Area
Hyperscale cloud operators cluster around submarine cable landings in Fornebu and Nannestad, driving demand for layered perimeter protection and biometric access systems. DSB facility security assessments mandate audit-ready surveillance infrastructure for critical infrastructure designation. Greenfield builds in this corridor specify integrated security stacks with unified command interfaces to satisfy NIS2 Directive transposition requirements.
Vestland
Bergen's enterprise data centers prioritize on-premises security infrastructure to maintain direct control over sensitive authentication databases. The Personal Data Act's GDPR implementation restricts cross-border footage processing, complicating managed service architectures. Secondary market operators here adopt hybrid security models blending local hardware with regional monitoring centers.
Trøndelag
Trondheim's research computing facilities drive specialized procurement for environmental monitoring systems rated for seismic and temperature extremes. The Norwegian Water Resources and Energy Directorate oversees critical infrastructure protection standards for facilities serving academic and government clients. Colocation providers in this region standardize on integrated security stacks to simplify compliance documentation across heterogeneous tenant requirements.
Troms og Finnmark
Arctic data center development for high-performance computing creates demand for physical security systems engineered for sub-zero operational envelopes. The Norwegian Polar Institute and research institutions anchor facility investment in Tromsø. Security specifications here emphasize climate-resilient perimeter sensors and remote monitoring capabilities given limited local technical labor pools.
Rogaland
Stavanger's energy sector data centers integrate physical security with industrial control system protection protocols. The Petroleum Safety Authority Norway's facility requirements influence procurement specifications for facilities serving offshore operations. Operators here prioritize seismic monitoring and environmental sensors to protect against geological risks in this tectonically active region.
Norway Data Center Physical Security Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors merge electrical infrastructure with access control and surveillance capabilities. The vendor base concentrates around Nordic engineering heritage firms and multinational industrial conglomerates with building management system portfolios. Two archetypes prevail: power-integrated security specialists and unified command platform providers. M&A activity and technology licensing agreements represent the primary competitive vectors as firms seek to reduce operator cognitive load through system convergence.
Among Nordic-origin specialists, Axis Communications AB and ASSA ABLOY exemplify engineering-driven positioning in video surveillance and access hardware respectively. German industrial conglomerates including Bosch Sicherheitssysteme GmbH and Siemens AG occupy positions emphasizing building management system convergence. Multinational electrical infrastructure leaders such as Schneider Electric and ABB Ltd anchor the power-integrated security tier, merging electrical distribution with physical protection systems. These named entities represent distinct strategic archetypes rather than exhaustive market coverage, with each exemplifying a particular approach to the compliance-driven procurement environment shaping Norwegian facility specifications.
| Leading Market Players |
|---|
| Axis Communications AB |
| ABB Ltd |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls |
| Honeywell International Inc |
| Siemens AG |
| Schneider Electric |
| Cisco Systems Inc |
| ASSA ABLOY |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud service providers in the Oslo metropolitan area concentrate procurement volume and anchor project-based pricing for integrated security stacks. Their preference for bundled installation and compliance documentation shifts vendor economics toward service-heavy contracts rather than equipment-only transactions.
Pricing Analysis
Warranty and maintenance bundling separates premium-tier suppliers from standard competitors in Norwegian data center physical security procurement. Project-based pricing dominates, with differentiation driven by DSB certification tier and customization depth for NIS2 Directive compliance. Pricing pressure stems from hyperscale buyers consolidating vendor relationships to simplify audit documentation. Mid-sized colocation operators in Bergen and Trondheim exhibit highest price sensitivity, while government-designated critical infrastructure facilities prioritize compliance over cost.
Supply Chain Analysis
Multi-factor authentication readers and 4K IP camera assemblies rest on manufacturing concentration in China, Taiwan, and South Korea. Nordic-engineered seismic sensors and climate-rated perimeter hardware draw from regional specialists in Sweden and Finland. Single-source vulnerability for biometric hardware exposes Norwegian operators to logistics chokepoints at Asian ports. Distribution runs through certified systems integrators familiar with DSB facility security assessment protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical security vendors face a vertical-integration race as power infrastructure and access control converge. Players are pursuing downstream control over managed security service operations to capture recurring revenue streams.
For Market Incumbents: Deepen integration between electrical infrastructure and physical security systems to defend against pure-play building management competitors. Acquire certified Norwegian systems integrators to address specialized labor scarcity. Expand managed security service portfolios before colocation operators consolidate vendor relationships. For New Entrants and Emerging Players: The EU NIS2 Directive's transposition into Norwegian cybersecurity legislation opens a window for biometric access control specialists to penetrate Tier II and III facilities previously exempt from mandatory DSB assessments. Target Tromsø and Arctic research computing deployments where climate-resilient hardware specifications create specification barriers for incumbent suppliers. Partner with regional electrical contractors to bypass direct competition with established security integrators. For Investors and Strategic Acquirers: Distressed-cycle entries favor managed security service providers with established DSB compliance track records in secondary Norwegian markets. Long-term viability hinges on recurring revenue predictability rather than project-based equipment sales. Watch hyperscale facility commissioning timelines as an inflection indicator for integrated security stack demand.| Strategic Initiative | Industry Significance |
|---|---|
| Building Management System Convergence | Unified command platforms reduce operator cognitive load at hyperscale Oslo-region facilities. |
| Managed Security Service Expansion | Subscription models capture colocation operators seeking to avoid dedicated security operations staffing. |
| Arctic Climate Hardware Certification | Sub-zero operational ratings differentiate suppliers for Tromsø high-performance computing deployments. |
| DSB Compliance Documentation Automation | Audit-ready trail generation accelerates procurement cycles for critical infrastructure designation. |
| Biometric Retrofit Sequencing Services | Phased migration without 24/7 disruption commands premium pricing in legacy facility upgrades. |
Research Methodology
Independent corroboration across facility security directors, DSB compliance officers, and systems integration specialists underwrites the qualitative findings in this analysis. Primary interviews with data center operators, electrical infrastructure procurement leads, and managed security service providers combined with secondary validation from Norwegian regulatory filings, EU NIS2 transposition documents, and hyperscaler capex disclosures. Bottom-up facility counts and top-down vendor revenue triangulation anchored market sizing.
Comparable-period anchoring to historical DSB assessment cycles and hyperscale construction timelines structured the forecast window across the analysis window. Segmentation modeling incorporated solution type, installation model, end-user category, and technology maturity dimensions. CAGRs derived from facility pipeline analysis and procurement specification trend extrapolation. Climate resilience requirements and regulatory compliance cost trajectories informed projection inputs.
Caveats apply where DSB regulatory scope expansion or submarine cable landing zone development delays could materially shift the outlook. Forecasts reflect assumptions about NIS2 Directive enforcement intensity and hyperscale facility completion rates. A small set of named triggers—critical infrastructure designation threshold changes, biometric hardware supply disruptions, and Arctic data center investment acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Canada Data Center Storage Market