
 US Data Center Construction Market | 2026-2036
US Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
US Data Center Construction Market Outlook
The gap between premium hyperscale facilities and commodity enterprise builds is shifting project economics across the sector. Turner Construction leverages in-house engineering to sustain dominance in mission-critical environments. DPR Construction anchors its position through specialized cleanroom and power-delivery expertise. Kiewit Corporation competes via self-perform electrical and mechanical capabilities that reduce subcontractor dependency.
US data center construction encompasses the design, engineering, and build-out of facilities housing servers, storage, and networking equipment with power densities now routinely exceeding 50 kW per rack and precision cooling to within one degree Fahrenheit. The primary commercial purpose is creating controlled environments that guarantee uptime for digital infrastructure operators. Modular construction leads in speed-to-market for cloud deployments, while mega-scale projects concentrate margin pools among firms with billion-dollar bonding capacity. Sustainable construction methods represent the fastest-growing segment as operators face Scope 3 emissions scrutiny from enterprise customers.
OSHA governs worker safety during complex electrical and mechanical installations, while EPA Clean Air Act permits constrain diesel generator deployments in non-attainment zones. FERC interconnection queue reforms directly shape project timelines for grid-tied facilities exceeding 100 MW. State-level building codes and utility commission rate structures further fragment compliance requirements across jurisdictions. Stakeholders must monitor interconnection agreement execution as the primary bottleneck variable rather than construction labor availability.
Market Dynamics
AI workload density requirements above 50 kW per rack are compressing construction timelines while forcing power-delivery redesigns across every US market tier.
Growth Catalysts
- NEPA Environmental Review Streamlining:Federal permitting acceleration under the Fiscal Responsibility Act compresses environmental clearance timelines for hyperscale campuses in federal lands-adjacent zones.
- State Renewable Portfolio Standards:Virginia, Texas, and Arizona mandates for carbon-free electricity procurement pull data center operators toward jurisdictions with utility-scale solar and wind interconnection availability.
- Liquid Cooling Infrastructure:Direct-to-chip and immersion cooling systems enable rack densities exceeding 100 kW, unlocking AI training cluster deployment in previously capacity-constrained facilities.
Market Restraints
- Electrical Switchgear Lead Times:Medium-voltage switchgear delivery stretches beyond 52 weeks due to transformer core steel and copper supply concentration in Asian manufacturing hubs.
- FERC Interconnection Queue Congestion:Grid connection delays exceeding 36 months for 100 MW-plus facilities freeze capital deployment in PJM and ERCOT territories.
- Diesel Generator Non-Attainment Restrictions:EPA Clean Air Act permitting constraints in ozone non-attainment zones block backup power deployment in Northern New Jersey and California's South Coast Air Basin.
Strategic Opportunities
- Secondary Market Expansion:Columbus, Ohio and Reno, Nevada offer lower land costs and favorable utility rate structures for enterprise colocation builds outside saturated primary markets.
- Behind-the-Meter Generation:On-site fuel cells and microgrids bypass interconnection queues while satisfying corporate renewable energy procurement targets.
- Modular Factory Fabrication:Pre-fabricated power modules and cooling skids compress field construction duration by 40 percent compared to stick-built approaches.
Industry Challenges
- Licensed Electrician Scarcity:Journeyman and master electrician availability constrains project staffing in Texas, Virginia, and Arizona markets simultaneously.
- Commissioning Complexity:Integrated systems testing for concurrent maintainability requires specialized commissioning agents with Uptime Institute Tier certification experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Data Center Construction Market |
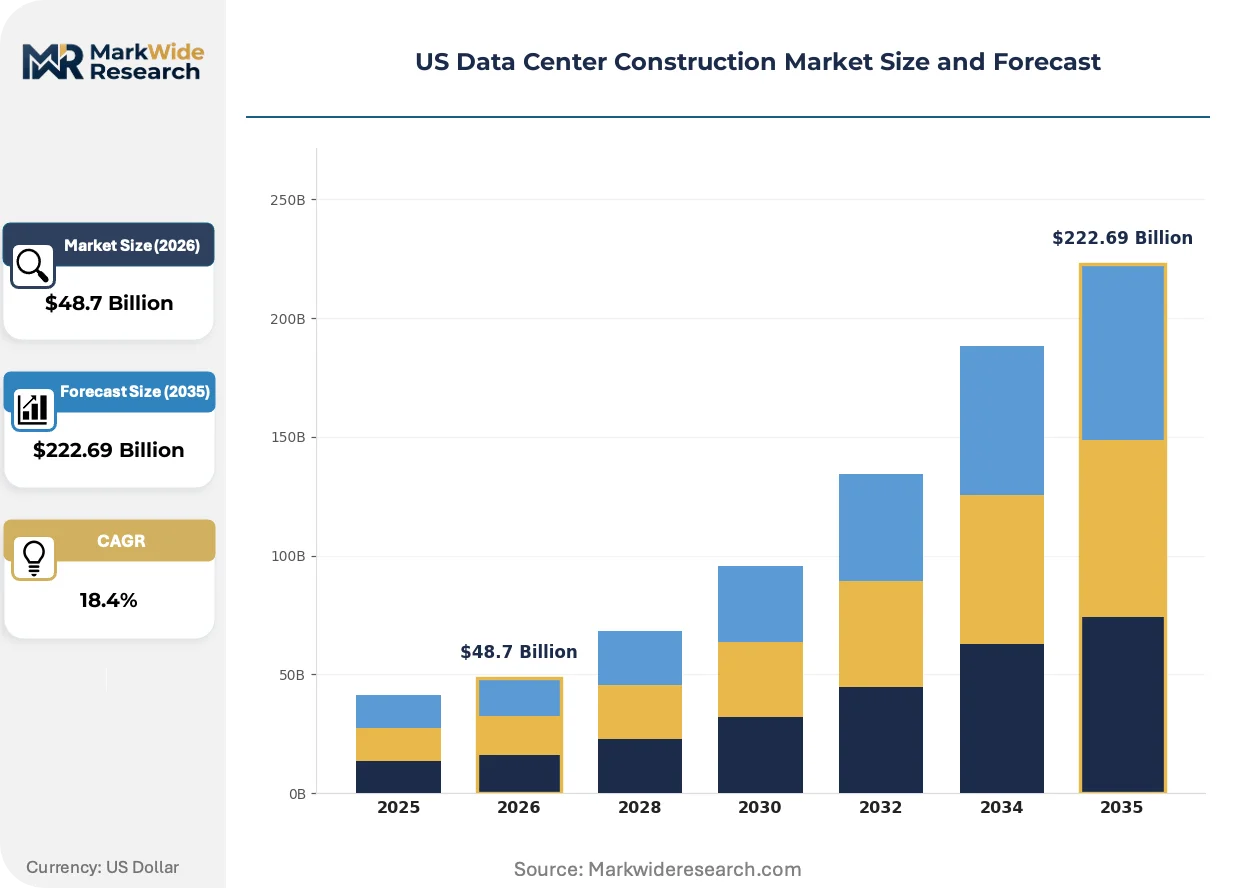
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Modular, Prefabricated, Traditional, Sustainable Project Size: Small-Scale, Medium-Scale, Large-Scale, Mega-Scale End User: Cloud Service Providers, Enterprises, Telecommunications, Colocation Power Infrastructure: UPS, Generators, Transformers, Power Distribution |
| Companies Covered | AECOM, Turner Construction, DPR Construction, Holder Construction, Skanska USA, Fortis Construction, Kiewit Corporation, Clark Construction Group, Gilbane Building Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Data Center Construction Market Strategic Shifts
Construction methodology and power architecture are converging around speed-to-market compression, with factory-based fabrication displacing traditional field assembly for critical path systems.
Prefabricated electrical houses (e-houses) and skid-mounted substations are unifying medium-voltage distribution with protective relaying in weatherproof enclosures. Hyperscale operators deploy these systems across greenfield campuses in Texas and Arizona. Factory acceptance testing prior to shipment compresses on-site commissioning schedules by eliminating weather-dependent construction phases.
EPA enforcement of Good Neighbor Plan provisions under the Clean Air Act tightens NOx emissions limits for emergency generators in 23 upwind states. Operators in the Ohio River Valley and Mid-Atlantic must retrofit selective catalytic reduction systems or procure Tier 4 final engines. Compliance capital requirements favor operators with multi-site portfolios capable of spreading engineering costs across facilities.
Enterprise buyers now require Scope 3 emissions disclosure from construction partners prior to contract award. General contractors respond by embedding embodied carbon tracking into procurement decisions for concrete and steel. This specification shift concentrates award volume with firms maintaining certified environmental product declarations and supplier sustainability scorecards.
US Data Center Construction Market Segmentation
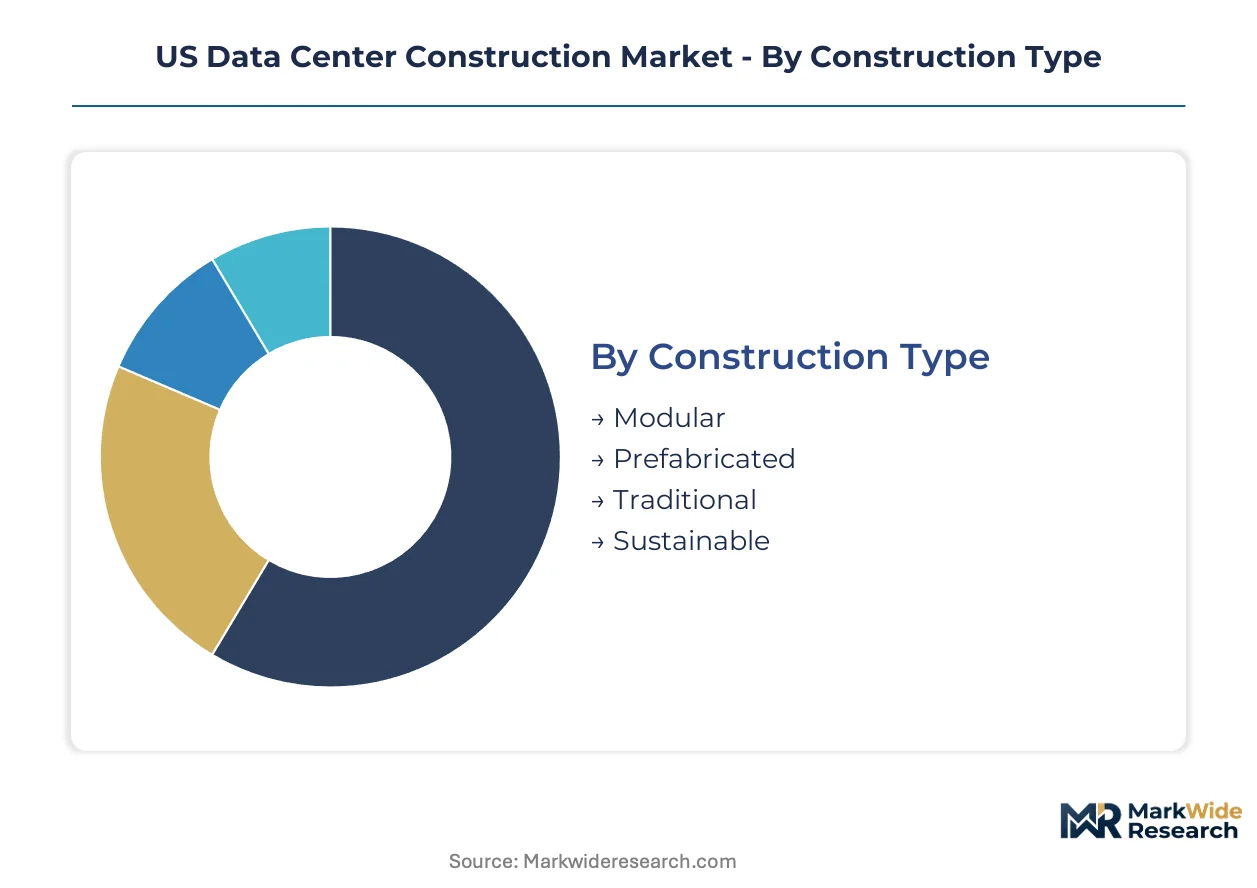
Construction methodology, project scale, and power architecture create distinct margin pools and capability requirements across the US data center build-out sector. Segmentation reveals where specialist contractors command premiums versus where commodity competition erodes returns.
Construction Type:
Speed-to-market pressure and sustainability mandates differentiate buyer priorities across delivery methodologies.
- Modular:Factory-fabricated power and cooling skids enable field assembly compression of 40 percent versus stick-built timelines. Hyperscale operators in Texas and Arizona deploy modular units across multi-building campuses to bypass weather-dependent construction phases and accelerate revenue recognition.
- Sustainable:Embodied carbon tracking and environmental product declarations now gate contract eligibility for enterprise buyers requiring Scope 3 disclosure. LEED and BREEAM certification paths concentrate award volume with contractors maintaining certified supplier scorecards and low-carbon concrete procurement relationships.
- Prefabricated:Pre-assembled electrical houses unify medium-voltage distribution with protective relaying in weatherproof enclosures.
- Traditional:Stick-built approaches persist in enterprise colocation and retrofit expansions where site constraints defeat modular logistics.
Traditional construction leads volumes today; sustainable methodology is gaining share fastest.
Project Size:
Bonding capacity and specialized labor deployment scale determine contractor eligibility across project tiers.
- Mega-Scale:Facilities exceeding 100 MW demand billion-dollar bonding capacity and self-perform electrical capabilities that eliminate subcontractor dependency. Northern Virginia's Data Center Alley and Dallas-Fort Worth concentrate mega-scale awards among firms with concurrent multi-site execution experience.
- Large-Scale:50-100 MW builds balance speed requirements with capital efficiency, favoring contractors with modular fabrication partnerships and in-house commissioning agents.
- Medium-Scale:Enterprise and regional colocation builds in secondary markets like Columbus and Reno.
- Small-Scale:Edge deployments and telecommunications huts with standardized designs.
Mega-scale projects lead volumes today; medium-scale builds in secondary markets are expanding most quickly.
End User:
Workload density requirements and uptime specifications create divergent technical specifications across buyer categories.
- Cloud Service Providers:AI training clusters above 50 kW per rack force liquid cooling integration and power-delivery redesigns. Microsoft, Amazon, and Google procurement teams prioritize contractors with direct-to-chip cooling installation experience and Uptime Institute Tier III+ commissioning credentials.
- Enterprises:Fortune 500 internal builds emphasize concurrent maintainability and hybrid cloud connectivity over raw density.
- Telecommunications:5G edge and central office retrofits with latency-sensitive latency requirements.
- Colocation:Multi-tenant designs balancing tenant flexibility with operational efficiency.
Cloud service providers lead volumes today; enterprise direct builds are climbing the fastest.
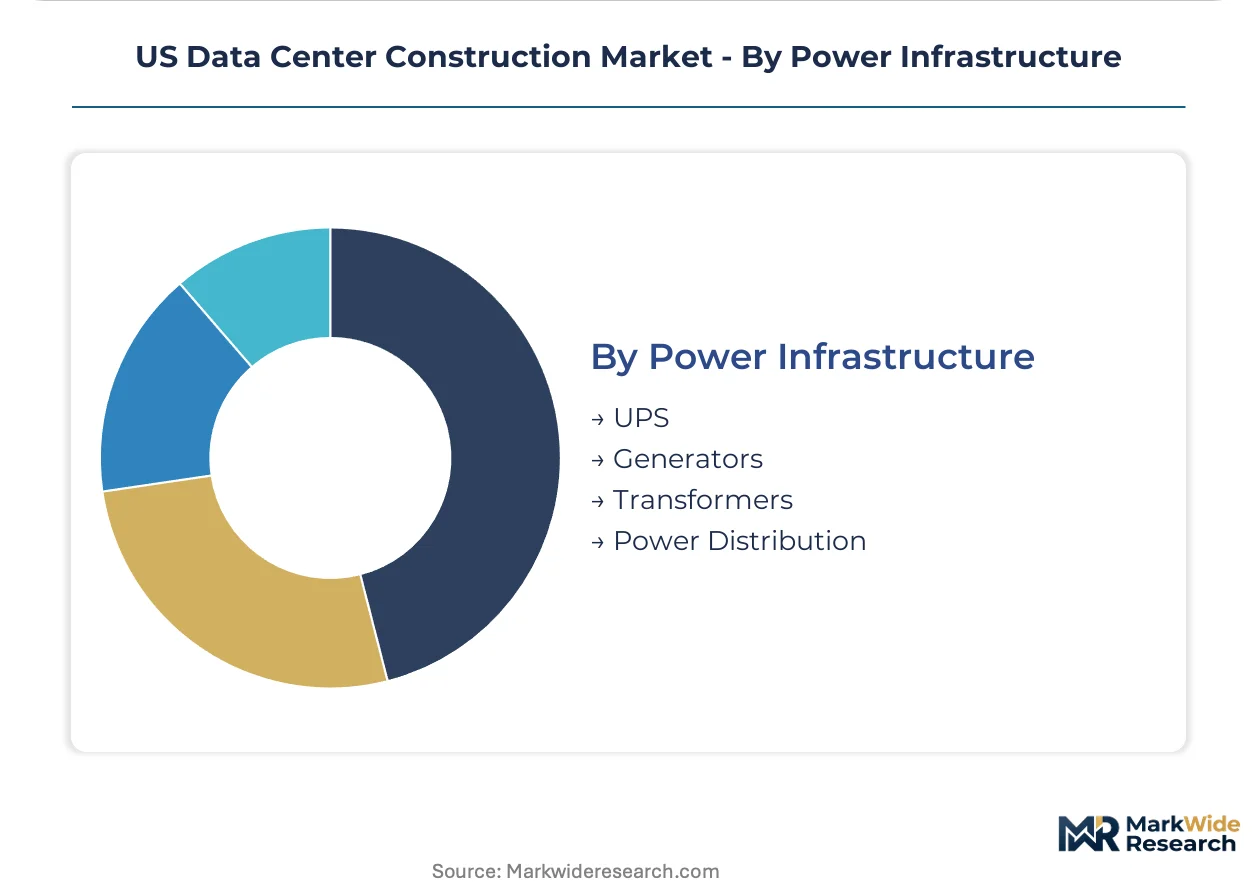
Power Infrastructure:
Supply chain concentration and interconnection queue dynamics reshape equipment specification priorities.
- Transformers:Medium-voltage unit substations face 52-week lead times due to grain-oriented electrical steel concentration in Asian manufacturing. Contractors with pre-positioned transformer inventory or domestic fabrication relationships capture schedule certainty premiums in PJM and ERCOT territories.
- Generators:EPA Clean Air Act non-attainment restrictions in Northern New Jersey and California's South Coast Air Basin block diesel deployment without selective catalytic reduction retrofits or Tier 4 final engine procurement.
- UPS:Lithium-ion battery integration replacing valve-regulated lead-acid systems for footprint reduction.
- Power Distribution:Busway and remote power panel configurations for flexible rack-level delivery.
Transformer procurement leads capital allocation today; behind-the-meter generation alternatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed electricians and specialized commissioning agents cluster in Northern Virginia, Dallas-Fort Worth, and Phoenix, anchoring the geographic distribution of data center construction expertise across US markets.
Northern Virginia
Hyperscale cloud deployments and AI training clusters drive permitting intensity in Loudoun and Prince William counties. Virginia's renewable portfolio standard mandates carbon-free electricity procurement, pulling operators toward Dominion Energy's utility-scale solar interconnections. Data Center Alley hosts the densest concentration of mega-scale facilities, with contractors competing for limited substation capacity along the I-66 corridor.
Dallas-Fort Worth
Lower land costs and favorable ERCOT rate structures attract enterprise colocation builds and cloud expansion campuses. Texas lacks statewide renewable mandates, though municipal utilities in Denton and Georgetown offer green tariff programs. The Sherman-Denison submarket and AllianceTexas corridor concentrate new mega-scale ground-up development.
Phoenix
Free cooling hours and Arizona's renewable energy standard draw hyperscale operators seeking water-efficient designs. Salt River Project and Arizona Public Service compete for large-load interconnections through expedited queue processes. The Mesa-Chandler-Queen Creek triangle hosts the fastest-growing cluster of liquid-cooled AI facilities.
Columbus
Enterprise demand for disaster recovery capacity and Midwest latency coverage drives secondary market expansion. Ohio's absence of state-level renewable mandates simplifies procurement for carbon-neutral operators with direct corporate PPAs. The New Albany-Intel corridor anchors development, with Facebook and Google maintaining existing campuses.
Reno
Nevada tax abatements and proximity to California demand without South Coast Air Basin restrictions enable backup generator deployment. NV Energy's green energy rider satisfies corporate renewable targets for operators avoiding diesel permitting constraints. The Tahoe-Reno Industrial Center hosts Tesla and Switch facilities with expansion land reserves.
US Data Center Construction Market Competitive Environment
Top-tier vendors anchor billion-dollar bonding capacity, while mid-tier specialists compete on cleanroom expertise and regional relationships. The market structures around three capability tiers: integrated self-perform contractors, modular fabrication partners, and regional enterprise builders. Two dominant competitive moves reshape positioning: backward integration into electrical and mechanical trades, and geographic expansion into secondary markets with pre-positioned workforce development.
Among integrated self-perform contractors, Turner Construction, DPR Construction, and Kiewit Corporation exemplify the capability archetype that reduces subcontractor dependency. Turner represents the engineering-led model with in-house mission-critical design capacity. DPR occupies a position defined by specialized cleanroom and power-delivery expertise. Kiewit anchors the self-perform electrical and mechanical tier with direct control over critical path trades.
| Leading Market Players |
|---|
| AECOM |
| Turner Construction |
| DPR Construction |
| Holder Construction |
| Skanska USA |
| Fortis Construction |
| Kiewit Corporation |
| Clark Construction Group |
| Gilbane Building Company |
| Others |
Value Chain & Pricing Dynamics
Backward integration into electrical and mechanical trades anchors both supply security and pricing power for tier-one contractors, as self-perform capabilities eliminate subcontractor markup layers while compressing critical path timelines in hyperscale builds.
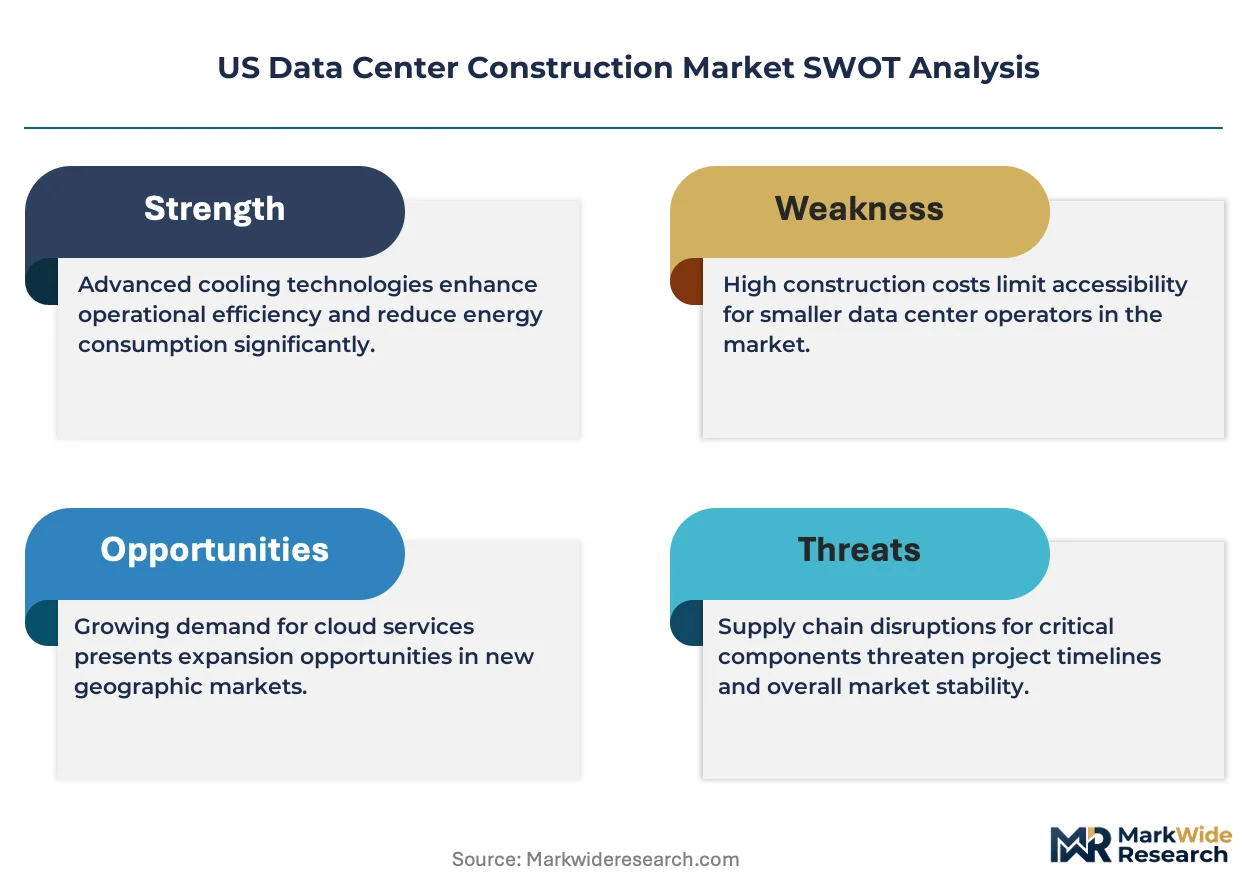
Pricing Analysis
Bundled design-build contracts dominate mega-scale projects, while unbundled procurement persists in enterprise retrofits. Three-tier pricing structure across premium hyperscale, standard enterprise, and economy edge deployments reflects bonding capacity and commissioning complexity. Cost compression in standard-tier builds intensifies as modular fabrication diffuses, eroding field-assembly premiums. Enterprise buyers exhibit highest price sensitivity, while cloud providers prioritize schedule certainty over unit cost.
Supply Chain Analysis
Regional distribution centers for electrical equipment cluster in Dallas-Fort Worth and Northern Virginia, feeding hub-and-spoke patterns into active construction corridors. Manufacturing concentrates in China, South Korea, and Germany for transformer core steel, power semiconductors, and precision cooling components. Raw material dependencies center on grain-oriented electrical steel, copper busbar, and fluorinated refrigerants. Single-source vulnerability in Asian transformer winding capacity exposes projects to FERC interconnection queue delays. Distribution runs through manufacturer-direct and authorized distributor channels with 52-week order horizons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US data center construction functions as a stable compounder, with AI workload density requirements driving sustained capital deployment across multiple market cycles.
For Market Incumbents: Cement dominance by expanding self-perform electrical crews into Phoenix and Columbus secondary markets, countering licensed electrician scarcity. Deepen modular fabrication partnerships to defend margin position against stick-built competitors. Prioritize Uptime Institute Tier IV commissioning credentials as cloud provider procurement gates tighten.
For New Entrants and Emerging Players: Equipment lessors represent the most accessible channel partner type for penetrating medium-scale enterprise builds in Reno and Columbus. Target disaster recovery and hybrid cloud connectivity specifications where incumbent bonding requirements are lower. Lead with behind-the-meter generation integration as differentiated service bundling.
For Investors and Strategic Acquirers: Consolidation pressure builds where FERC interconnection queue congestion strands capital in PJM and ERCOT territories, favoring contractors with pre-positioned transformer inventory. Long-term viability frames around five-to-ten year AI infrastructure buildout cycles. Target acquisition archetypes include regional electrical contractors with master electrician workforces and cleanroom commissioning specialists. Watch FERC queue reform implementation as inflection indicator for capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Scale-Up | Factory-built power skids compress field schedules by 40 percent in Texas and Arizona campuses. |
| Self-Perform Electrical Expansion | In-house journeyman crews eliminate subcontractor dependency and accelerate critical path completion. |
| Secondary Market Geographic Entry | Columbus and Reno builds capture enterprise demand outside saturated Northern Virginia corridors. |
| Behind-the-Meter Generation Partnership | Fuel cell and microgrid deployments bypass FERC interconnection queues while satisfying renewable targets. |
| Sustainability Certification Investment | LEED and BREEAM credentials gate enterprise contract eligibility under Scope 3 disclosure mandates. |
Study Parameters
Coverage spans Northern Virginia, Dallas-Fort Worth, Phoenix, Columbus, and Reno, with primary inputs from each construction corridor. Primary interviews incorporated data center development executives, EPC project directors, utility interconnection planners, commissioning agents with Uptime Institute credentials, and electrical contractor operations managers. Secondary validation drew from FERC interconnection queue filings, EIA electricity market data, state utility commission rate case dockets, and EPA Clean Air Act permitting records. Bottom-up project pipelines triangulated against top-down capital expenditure disclosures from hyperscale operators.
Rate-of-change decomposition separated volume growth from unit cost movements across the projection horizon. Segmentation dimensions modeled include construction methodology, project scale tier, end user category, and power infrastructure type. CAGRs derived from installed base expansion rates, workload density trajectories, and regional permitting velocity differentials. Forecast inputs incorporated AI training cluster deployment schedules, transformer manufacturing capacity constraints, and state renewable portfolio standard compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FERC interconnection queue reforms, grain-oriented electrical steel trade flows, and EPA generator emissions rulemakings. Outputs reflect documented assumptions on labor productivity, equipment lead times, and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Brazil Data Center Server Market