
 Box and Carton Overwrap Films Market | 2026-2036
Box and Carton Overwrap Films Market Size, Share, and Industry Trends Forecast 2026-2036
Box and Carton Overwrap Films Market Outlook
Subscription-based film management programs is repositioning how converters and brand owners procure overwrap materials, bundling inventory optimization with technical support. Amcor PLC leverages its global manufacturing footprint to sustain supply security for multinational CPG accounts. Berry Global Inc. anchors North American capacity through vertical control of resin-to-film operations. Jindal Poly Films Ltd. dominates biaxially oriented polypropylene output from its Indian production bases.
Box and carton overwrap films are thin-gauge, transparent or printed flexible substrates, typically 12–30 microns in biaxially oriented polypropylene or cast polyethylene, applied via heat-seal or cold-glue overlap to secure and display retail-ready packaging. Their primary purpose is to provide tamper evidence, moisture barrier, and optical clarity while enabling high-speed wrapping on horizontal or vertical form-fill-seal lines. Polypropylene films lead in food packaging applications where stiffness and gloss drive shelf appeal, while polyethylene grades gain ground in e-commerce for softer hand and puncture resistance. Lightweight and ultra-thin specifications are capturing margin pools as resin efficiency and freight cost reduction become structural priorities for converters.
EMA's evolving guidance on pharmaceutical packaging materials, combined with REACH restrictions on PVC plasticizers and the EU Green Deal's recyclability mandates, are reshaping material qualification pathways and accelerating mono-polyethylene and paper-substitute development. FDA food-contact notification requirements and EPA resin manufacturing emissions standards add compliance layers for suppliers serving dual-region accounts. Stakeholders must monitor how extended producer responsibility schemes in France and Germany alter film specification contracts and recyclability certification requirements.
Market Dynamics
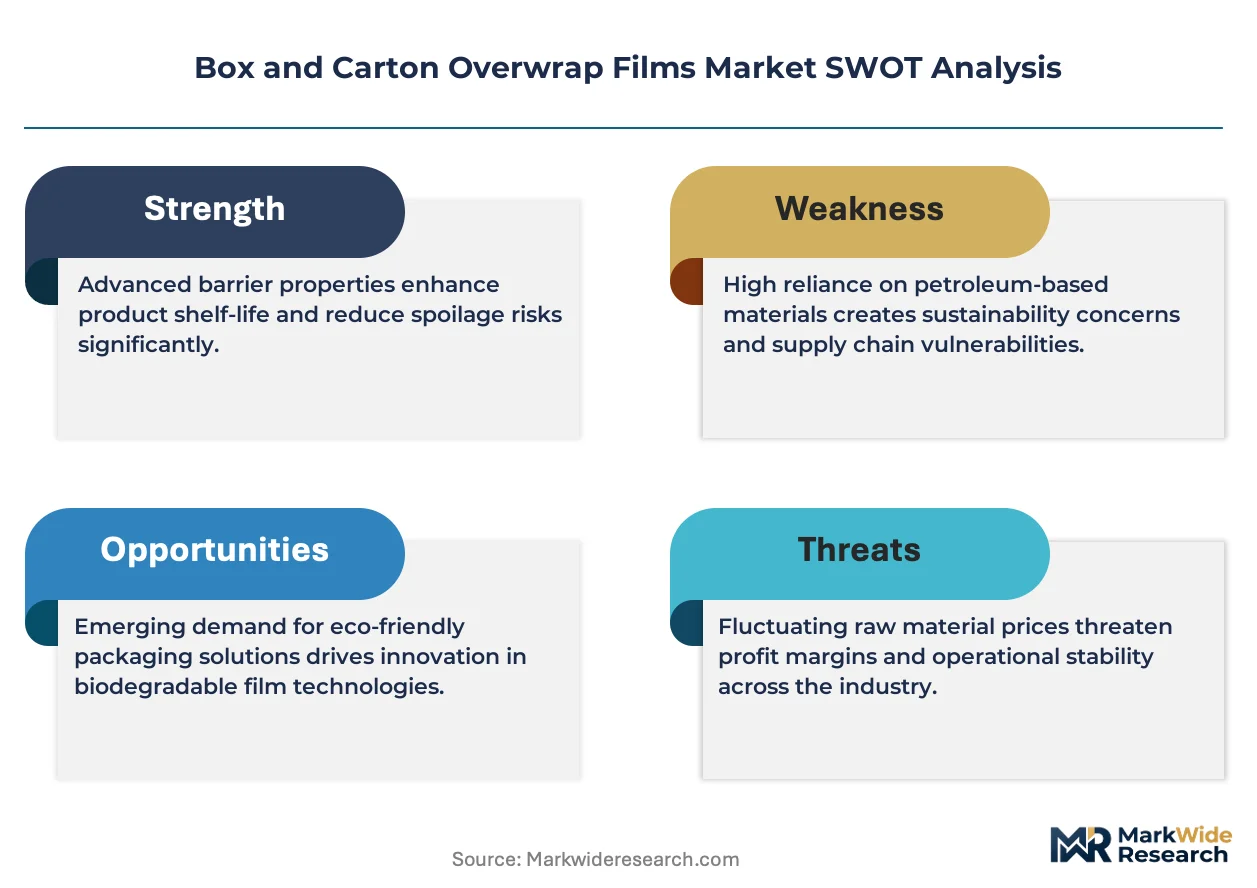
The EU Green Deal and F-Gas Regulation are compressing specification windows for box and carton overwrap films, forcing converters to requalify entire product lines around mono-material recyclability while maintaining optical and barrier performance.
Growth Catalysts
- E-commerce fulfillment automation:Unitization demand from automated picking systems drives 12-30 micron film specifications for shelf-ready display. Amazon and regional logistics hubs specify puncture-resistant polyethylene grades.
- REACH PVC plasticizer restrictions:Phthalate bans in pharmaceutical and food contact applications accelerate polypropylene and polyethylene substitution. EMA guidance reinforces material qualification pathways.
- German pharmaceutical export growth:Premium biaxially oriented polypropylene specifications concentrate demand in Düsseldorf and Hamburg port clusters for temperature-stable overwrap.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in Rotterdam and Antwerp transmit directly to biaxially oriented polypropylene film margins. Converters lack pricing power to pass through resin spikes.
- Chinese resin-to-film capacity concentration:Jindal Poly Films and domestic Chinese producers control biaxially oriented polypropylene supply security. European buyers face extended lead times during port congestion.
- Multi-layer laminate incompatibility:Existing high-barrier structures combining polyethylene terephthalate, ethylene vinyl alcohol, and polyamide fail mechanical recycling streams. Sorting infrastructure cannot separate bonded layers.
Strategic Opportunities
- Indian pharmaceutical contract manufacturing:CDSCO export certification requirements create specification pull for tamper-evident overwrap. Hyderabad and Ahmedabad clusters lack qualified local film converters.
- Extended producer responsibility schemes:French and German packaging laws mandate recyclability certification. Early movers capture premium positioning through dual-logo licensing.
- Paper-substitute film convergence:Cellulose and polylactic acid barrier coatings combine with heat-seal polyethylene layers. Food retail chains pilot shelf-ready formats at Carrefour and REWE.
Industry Challenges
- Mono-material requalification timelines:FSSAI and FDA food-contact notification cycles extend 18-24 months for new polyethylene specifications. Brand owners delay line conversions.
- High-speed line integration complexity:Horizontal form-fill-seal equipment retrofits for thinner gauges require mechanical and thermal recalibration. Engineering talent concentrates at OEM headquarters in Bologna and Chicago.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box and Carton Overwrap Films Market |
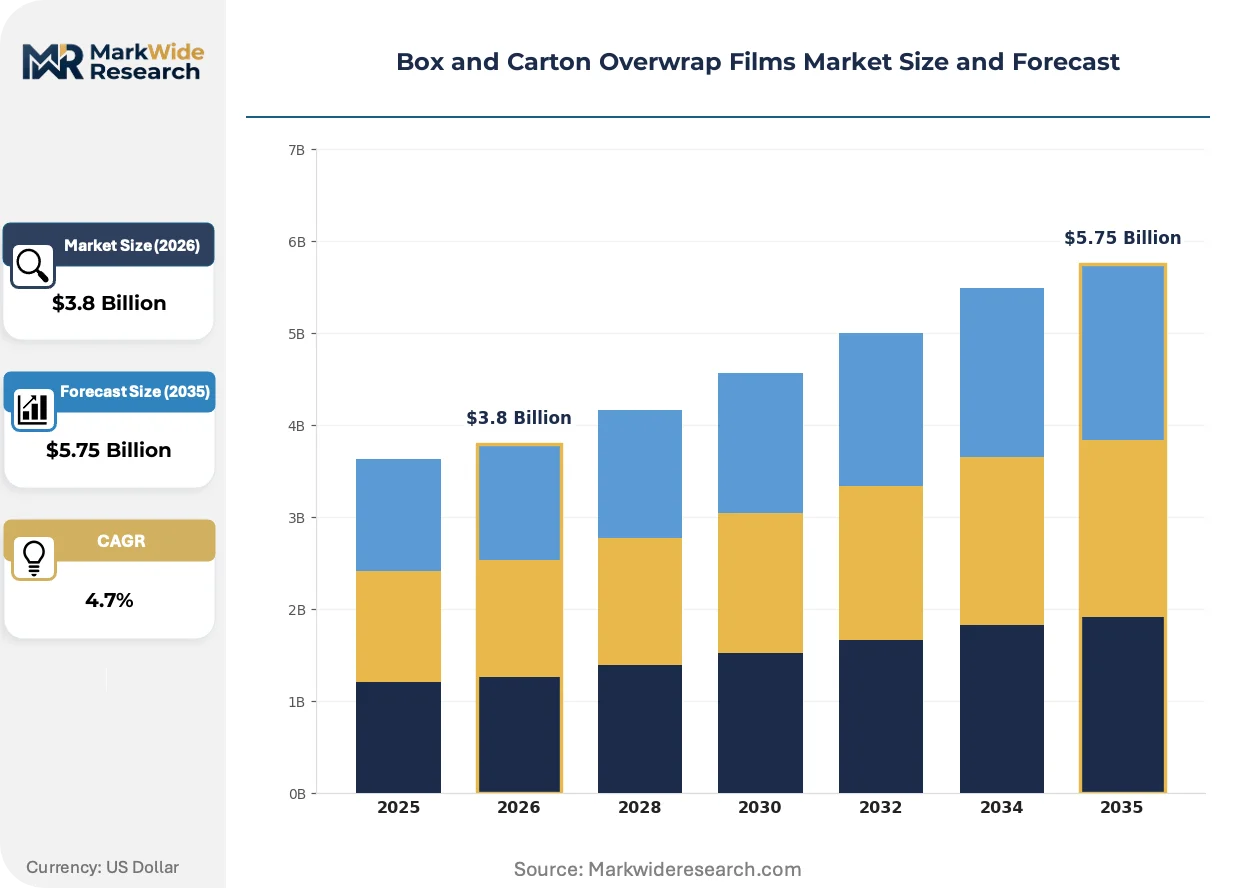
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polypropylene, Polyethylene, PVC, Paper Application: Food Packaging, Beverage Packaging, Pharmaceuticals, Consumer Goods End User: Retail, E-commerce, Manufacturing, Wholesale Thickness: Lightweight, Standard, Heavy-Duty, Ultra-Thin |
| Companies Covered | Amcor PLC, Berry Global Inc., Sealed Air Corporation, Taghleef Industries, Jindal Poly Films Ltd., UFlex Limited, Treofan Group, Innovia Films, Cosmo Films Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box and Carton Overwrap Films Market Strategic Shifts
Material science advances and regulatory compression are collapsing traditional film specification hierarchies, creating technical differentiation around recyclability certification rather than barrier performance alone.
Downgauging to sub-15 micron biaxially oriented polypropylene is consolidating premium positioning in food retail display applications. German and French supermarket chains specify these ultra-thin grades for private-label confectionery and baked goods. The technology is consolidating margin pools toward resin-efficient converters with metallization and coating capabilities.
The EU F-Gas Regulation and national extended producer responsibility implementations are fragmenting material approval pathways. Converters must maintain parallel stock-keeping units for REACH-compliant mono-polyethylene and legacy multi-layer structures. Pharmaceutical exporters in Germany face the steepest requalification burden as EMA guidance tightens on extractables and leachables testing.
Subscription-based film management programs are displacing spot purchasing for multinational consumer packaged goods accounts. Inventory optimization and technical support bundling locks in converter relationships. This model concentrates most visibly at North American e-commerce fulfillment centers where demand volatility complicates traditional procurement.
Box and Carton Overwrap Films Market Segmentation
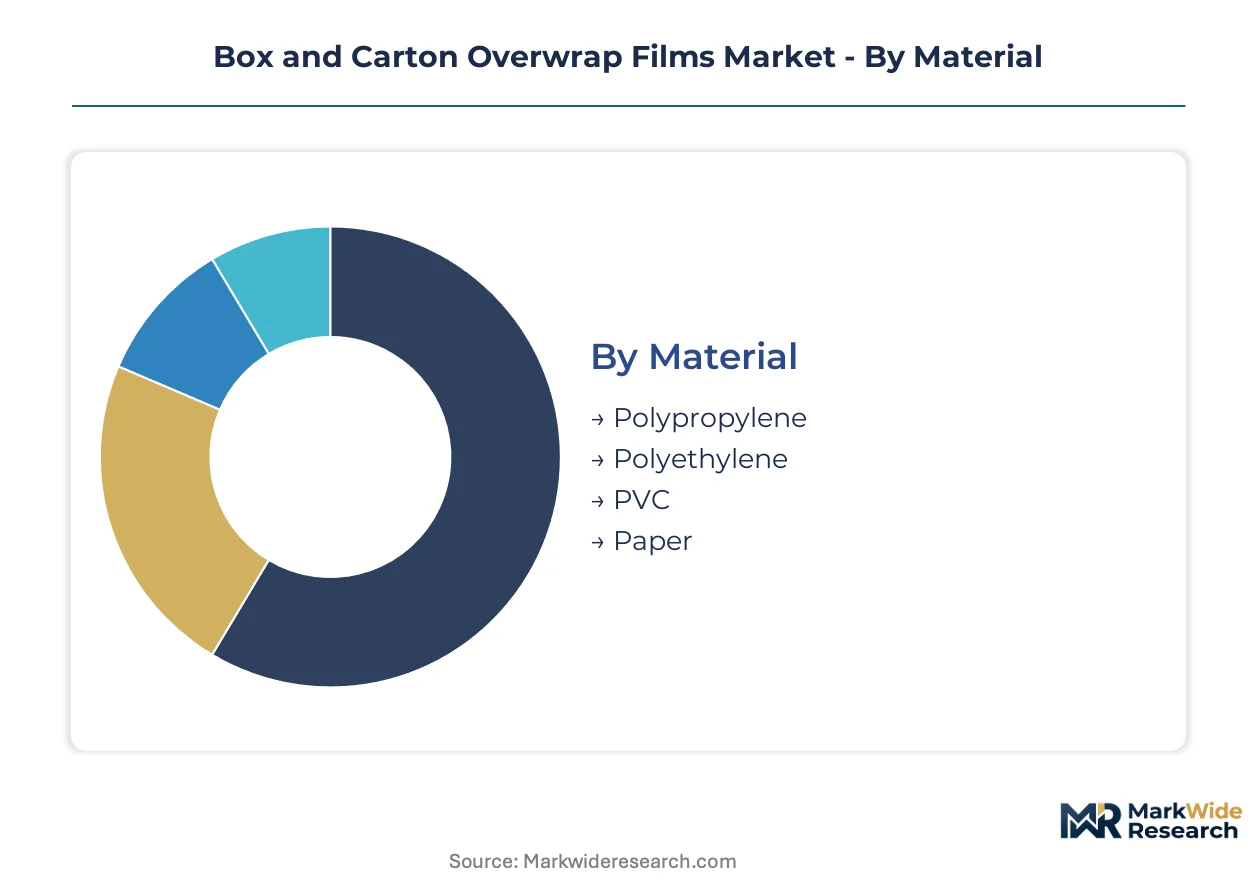
Segmentation in box and carton overwrap films reveals how resin chemistry, gauge specifications, and end-use requirements fragment procurement strategies across converters. Material selection and thickness tiers directly determine barrier performance, recyclability compliance, and line-speed compatibility.
Material:
Polypropylene commands volume share through stiffness and optical clarity, while polyethylene gains ground in softer-hand applications and mono-material recyclability mandates.
- Polypropylene:Biaxially oriented grades deliver the gloss and dimensional stability that German food retail chains specify for shelf-ready confectionery displays. Heat-seal layers on coextruded structures maintain line speeds above 200 packages per minute on horizontal form-fill-seal equipment.
- Polyethylene:Cast and blown grades penetrate e-commerce fulfillment where puncture resistance and cold-temperature toughness matter more than shelf optics. Amazon robotics hubs specify these films for automated unitization lines that reject rigid, noisy substrates.
- PVC:REACH plasticizer restrictions have collapsed pharmaceutical and food-contact demand, relegating remaining volume to industrial applications with less stringent extractables testing.
- Paper:Barrier-coated cellulose substrates pilot at Carrefour and REWE as fiber-based alternatives, though heat-seal consistency and moisture resistance lag polymer films.
Today's leader: Polypropylene. Tomorrow's challenger: Polyethylene.
Application:
Food packaging concentrates revenue through high-volume, short-shelf-life cycles, while pharmaceutical applications command premium pricing for compliance-intensive specifications.
- Food Packaging:Bakery and confectionery segments drive ultra-thin biaxially oriented polypropylene consumption in French and German private-label programs. Downgauging to sub-15 micron specifications reduces resin input while maintaining optical clarity for impulse-purchase visibility.
- Pharmaceuticals:Temperature-stable overwrap for German export shipments demands premium biaxially oriented polypropylene with extractables documentation under EMA guidance. Hamburg and Düsseldorf port clusters concentrate specification pull.
- Beverage Packaging:Multi-pack collation films favor polyethylene for flexibility around irregular bottle geometries, though shrink-tunnel compatibility limits gauge reduction.
- Consumer Goods:Cosmetics and electronics overwrap prioritizes tamper-evidence and printability over barrier performance, opening niche for coated paper trials.
Food packaging anchors current volume. Pharmaceuticals offer the steepest expansion trajectory as EMA qualification pathways lengthen and tighten.
End User:
Retail and e-commerce procurement patterns diverge sharply on inventory turnover, specification stability, and technical support requirements.
- Retail:German and French supermarket chains enforce rigid specification sheets for shelf-ready display, locking converters into 12-24 month qualification cycles with minimal deviation tolerance.
- E-commerce:Fulfillment centers prioritize puncture resistance and machine compatibility over optical properties, with Amazon and regional logistics hubs driving polyethylene adoption for automated handling systems.
- Manufacturing:Contract packers serving multiple brand owners maintain parallel stock-keeping units for REACH-compliant and legacy films, fragmenting production runs.
- Wholesale:Bulk distribution channels accept standard-gauge polypropylene with minimal customization, pressuring margin through price-transparent tender processes.
Retail chains dictate material specifications today. E-commerce fulfillment is climbing fastest as automation penetration deepens.
Thickness:
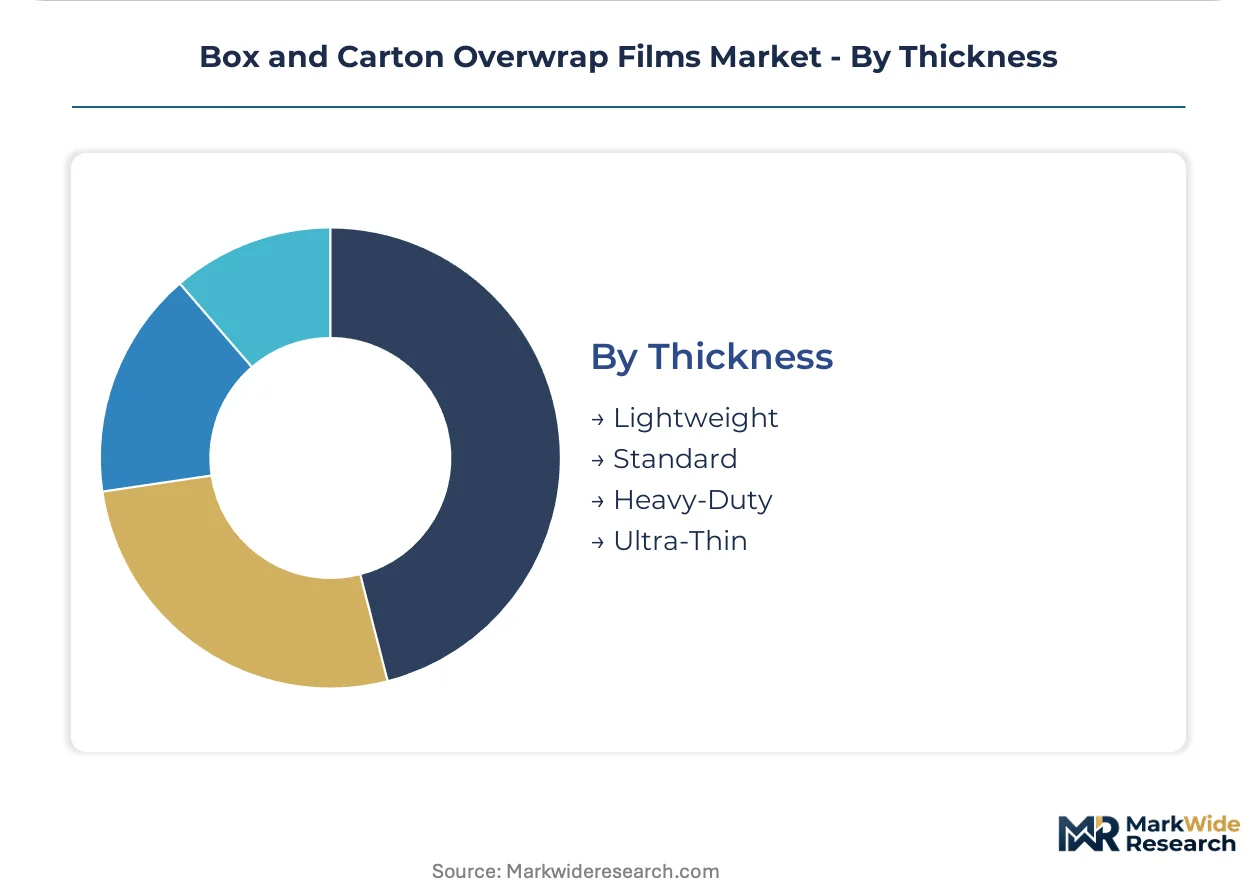
Gauge selection balances resin efficiency against mechanical performance, with sub-15 micron films capturing margin through technical differentiation rather than commodity positioning.
- Ultra-Thin:Sub-15 micron biaxially oriented polypropylene consolidates premium positioning in German confectionery and baked goods displays. Metallization and coating capabilities separate qualified converters from commodity suppliers.
- Lightweight:15-20 micron specifications serve mainstream food retail where freight cost reduction and line-speed compatibility intersect. French extended producer responsibility schemes favor these gauges for recyclability scoring.
- Standard:20-30 micron films retain volume in beverage collation and pharmaceutical bundling where puncture resistance cannot be sacrificed.
- Heavy-Duty:Above-30 micron grades retreat to industrial and export applications with extreme handling requirements, losing share to corrugated alternatives.
Ultra-thin films command technical premiums now. Lightweight specifications are gaining share fastest as dual-logo recyclability certification becomes a procurement filter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical export demand while India drives contract manufacturing growth, creating divergent specification requirements across these two production hubs.
United States
Amazon robotics fulfillment centers specify puncture-resistant polyethylene grades for automated unitization lines. FDA food-contact notification requirements govern material qualification pathways for converters serving dual-region accounts. Chicago and Pacific Northwest logistics clusters anchor e-commerce film consumption.
Germany
EMA guidance on pharmaceutical packaging materials tightens extractables and leachables testing for temperature-stable overwrap exports. The EU Green Deal and F-Gas Regulation compress specification windows around mono-material recyclability. Düsseldorf and Hamburg port clusters concentrate premium biaxially oriented polypropylene demand.
France
Extended producer responsibility schemes mandate recyclability certification for shelf-ready display formats. Carrefour pilots paper-substitute films with cellulose and polylactic acid barrier coatings. Paris and Lyon retail procurement centers enforce rigid specification sheets with minimal deviation tolerance.
India
CDSCO export certification requirements create specification pull for tamper-evident overwrap in pharmaceutical contract manufacturing. FSSAI food-contact notification cycles extend qualification timelines for new polyethylene specifications. Hyderabad and Ahmedabad clusters lack qualified local film converters.
China
Domestic resin-to-film capacity concentration controls biaxially oriented polypropylene supply security for regional buyers. NMPA pharmaceutical packaging standards align with international extractables documentation requirements. Yangtze River Delta production bases serve both domestic consumption and export markets.
Box and Carton Overwrap Films Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational converters commanding pharmaceutical and food retail accounts while regional players capture wholesale and industrial volume. The vendor base organizes around three archetypes: resin-integrated film producers, independent converters with metallization capabilities, and subscription-based film management providers. Consolidation pressures favor backward integration into resin operations and geographic expansion through strategic partnerships. Technology licensing agreements for ultra-thin gauge production separate premium-positioned suppliers from commodity competitors.
Among the integrated multinational tier, Amcor PLC and Berry Global Inc. exemplify scale-driven positioning through global manufacturing footprints and captive supply security. Jindal Poly Films Ltd. occupies a specialist position within biaxially oriented polypropylene production, anchoring supply from Indian production bases. These three entities represent distinct competitive vectors: Amcor through multinational CPG account coverage, Berry through vertical control of resin-to-film operations, and Jindal through regional dominance in specific resin chemistry output.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Inc. |
| Sealed Air Corporation |
| Taghleef Industries |
| Jindal Poly Films Ltd. |
| UFlex Limited |
| Treofan Group |
| Innovia Films |
| Cosmo Films Ltd. |
| Others |
Value Chain & Pricing Dynamics
Downgauging to sub-15 micron biaxially oriented polypropylene specifications simultaneously compresses resin input costs and concentrates margin capture among converters with metallization capabilities. This technical shift rewards backward-integrated producers while fragmenting pricing power across tiered supplier bases serving German food retail and Indian pharmaceutical contract manufacturing clusters.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard-gauge polypropylene films. Three-tier pricing structure across premium, standard, and economy levels separates metallized ultra-thin grades from commodity cast polyethylene and legacy PVC alternatives. Price differentiation rests on EMA extractables certification and dual-logo recyclability licensing under French and German extended producer responsibility schemes. Cost compression in standard gauges is intensifying because Chinese resin-to-film integration eliminates converter margin buffers. Wholesale distributors exhibit highest price sensitivity, while pharmaceutical exporters in Hamburg and Düsseldorf accept technical premiums for temperature-stable specifications.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Singapore anchor hub-and-spoke patterns for European and Asia-Pacific pharmaceutical fulfillment. Supply concentrates in China, India, and Germany for biaxially oriented polypropylene resin and film conversion. Raw material dependencies draw from naphtha-cracker propylene output, ethylene feedstocks for polyethylene grades, and metallization aluminum sources. Single-source vulnerability runs through Yangtze River Delta resin production during port congestion episodes. Distribution runs through converter-direct relationships for multinational CPG accounts and tiered distributor networks for regional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-thin gauge proliferation creates margin-expansion headroom as resin efficiency gains outpace commodity pricing erosion. Premium positioning through recyclability certification and extractables documentation captures pricing power in German pharmaceutical and French food retail procurement.
For Market Incumbents: Cement backward integration into naphtha-cracker propylene supply to defend against Chinese resin-to-film cost advantages. Lock in 24-36 month subscription-based film management contracts with Amazon and REWE to secure volume visibility against spot-market volatility. Prioritize metallization and coating capability investments to maintain technical differentiation as sub-15 micron specifications commoditize. For New Entrants and Emerging Players: Capture white-space demand in Indian pharmaceutical contract manufacturing where Hyderabad and Ahmedabad clusters lack qualified local converters. Target paper-substitute film trials at Carrefour and REWE as fiber-based alternatives gain shelf-ready format traction. Lead with CDSCO and FSSAI certification services bundled with technical support to differentiate from established resin-integrated competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among independent converters without metallization capabilities facing requalification cost burdens under EU Green Deal mandates. Five-to-ten year viability favors suppliers with parallel REACH-compliant and legacy film stock-keeping units serving dual-region accounts. Watch for EMA guidance tightening on extractables testing as inflection indicator for premium specification demand concentration in German port clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive propylene supply from Rotterdam and Antwerp crackers insulates margin against naphtha volatility. |
| Recyclability Certification Investment | Dual-logo licensing under French and German extended producer responsibility schemes unlocks premium positioning. |
| Ultra-Thin Gauge Production Scale-Up | Sub-15 micron biaxially oriented polypropylene capacity consolidates technical differentiation in German confectionery display. |
| Subscription-Based Film Management Programs | Inventory optimization bundling locks in Amazon and multinational CPG relationships against spot purchasing. |
| Indian Pharmaceutical Contract Manufacturing Partnership | CDSCO export certification capabilities address Hyderabad and Ahmedabad converter scarcity for tamper-evident overwrap. |
Study Parameters
Bottom-up food packaging and pharmaceutical application modeling reconciled against top-down resin-to-film capacity tracking forms the analytical core of this study. Primary interviews with converter plant managers, procurement leads at German retail chains, pharmaceutical packaging engineers, and distribution channel partners were validated against secondary sources including EMA guidance documents, REACH regulatory filings, CDSCO export certification databases, and customs trade data for polypropylene and polyethylene film flows. Triangulation across these sources ensures segmentation integrity for material, application, end user, and thickness tiers.
Historical trendline analysis of biaxially oriented polypropylene and polyethylene film consumption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include resin chemistry grade, end-use industry vertical, gauge thickness tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce automation penetration rates and pharmaceutical export growth trajectories. Forecast inputs specifically incorporate EU F-Gas Regulation compliance timelines and Indian FSSAI notification cycle durations.
Propylene feedstock volatility, port congestion in Chinese export corridors, and EMA guidance revision schedules are the dominant revision risks to forecast assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
PET Strap Market
Packaging Materials
France Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
North America Single-Use Packaging Market