
 Global Liquid Packaging Market | 2026-2036
Global Liquid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Packaging Market Foresight
Polyethylene terephthalate is broadening its addressable use cases in carbonated soft drinks and bottled water as barrier-coated paperboard challenges its cost position in ambient dairy. Amcor plc leverages multilayer coextrusion capabilities to sustain global supply contracts for pharmaceutical blow-fill-seal applications. Tetra Pak International SA anchors its installed base through aseptic filling equipment lock-in, while SIG Combibloc Group AG competes aggressively on carton format flexibility for portion-sized beverages.
Liquid packaging encompasses engineered containment systems designed to preserve fluid integrity across distribution, incorporating specifications such as oxygen transmission rates below 0.1 cc per square meter per day for sensitive beverages and multilayer coextrusion walls ranging from 0.2 to 2.0 millimeters depending on barrier requirements. The primary commercial purpose centers on extending shelf life, enabling safe transport, and supporting brand differentiation at point of sale. Paperboard cartons command dominant share in ambient dairy and juice due to efficient cube utilization and renewable material credentials, while pouch formats are capturing fastest growth in personal care and food ingredients where lightweighting and dispensing convenience outweigh premium positioning. Plastic bottles remain the margin pool for high-volume carbonated and still water categories where scale economies and recycling infrastructure maturity protect incumbent positions.
The U.S. FDA regulates food-contact substance notifications under 21 CFR, while the EU's REACH framework and F-Gas Restrictions constrain fluorinated barrier chemistries in carton coatings, collectively steering R&D toward mineral and bio-based barrier alternatives. China's SAMR enforces GB 4806 standards for food-contact plastics and composites, creating divergent compliance pathways for multinational suppliers operating across jurisdictions. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions to anticipate which material-platform investments will retain structural cost advantage.
Market Dynamics
Barrier-coated paperboard is decentralizing packaging procurement authority from beverage multinationals toward regional dairy cooperatives and private-label retailers across Asia-Pacific and Latin America, compressing polyethylene terephthalate's historical dominance in ambient shelf-stable categories.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for virgin plastic foodware are redirecting beverage brand R&D budgets toward fiber-based composite substrates with mineral barrier coatings.
- Aseptic carton equipment lock-in:Dairy processors in India and Indonesia are committing to 10-year filling equipment contracts that structurally favor carton over bottle formats for UHT milk expansion.
- Cold-chain infrastructure:Urban refrigerated logistics networks in São Paulo and Mexico City are enabling premium barrier pouch penetration for fresh juice and functional beverages previously limited to ambient distribution.
Market Restraints
- Aluminum foil supply concentration:Aseptic carton multilayer structures depend on thin-gauge foil supply from a concentrated Chinese smelter base, exposing converters to energy-cost volatility and export quota uncertainty.
- Fluorinated barrier chemistry sunset:REACH F-Gas restrictions and impending EPA PFAS designations are forcing rapid reformulation of high-barrier carton coatings without fully qualified mineral alternatives at scale.
- Mechanical recycling incompatibility:Laminated paperboard-polyethylene-aluminum structures lack economically viable sorting and reprocessing infrastructure in most municipal waste systems outside Northern Europe.
Strategic Opportunities
- India organized retail growth:Reliance Retail and DMart expansion into Tier-2 cities is creating first-mover advantage for domestic aseptic carton converters with localized filling equipment partnerships.
- Bio-based barrier convergence:Integration of polylactic acid sealant layers with nanocellulose oxygen barriers offers compostable end-of-life credentials for premium organic beverage positioning.
- Direct-to-subscription dispensing:Concentrate and refill pouch systems for household cleaners and personal care liquids are bypassing traditional retail shelf-space constraints through e-commerce subscription channels.
Industry Challenges
- Multilayer coextrusion technician scarcity:Barrier film production requires operators trained in rheology control and die gap calibration, with vocational pipeline gaps acute in Southeast Asian manufacturing hubs.
- Extended producer responsibility compliance:Divergent national EPR fee structures and reporting requirements across EU member states, UK, and Australian jurisdictions create administrative burden for multinational format portfolios.
- Legacy filling line retrofit costs:Converting existing polyethylene terephthalate blow-molding assets to handle paperboard sleeve application or pouch form-fill-seal demands capital expenditure exceeding depreciation schedules for mid-cap beverage bottlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Packaging Market |
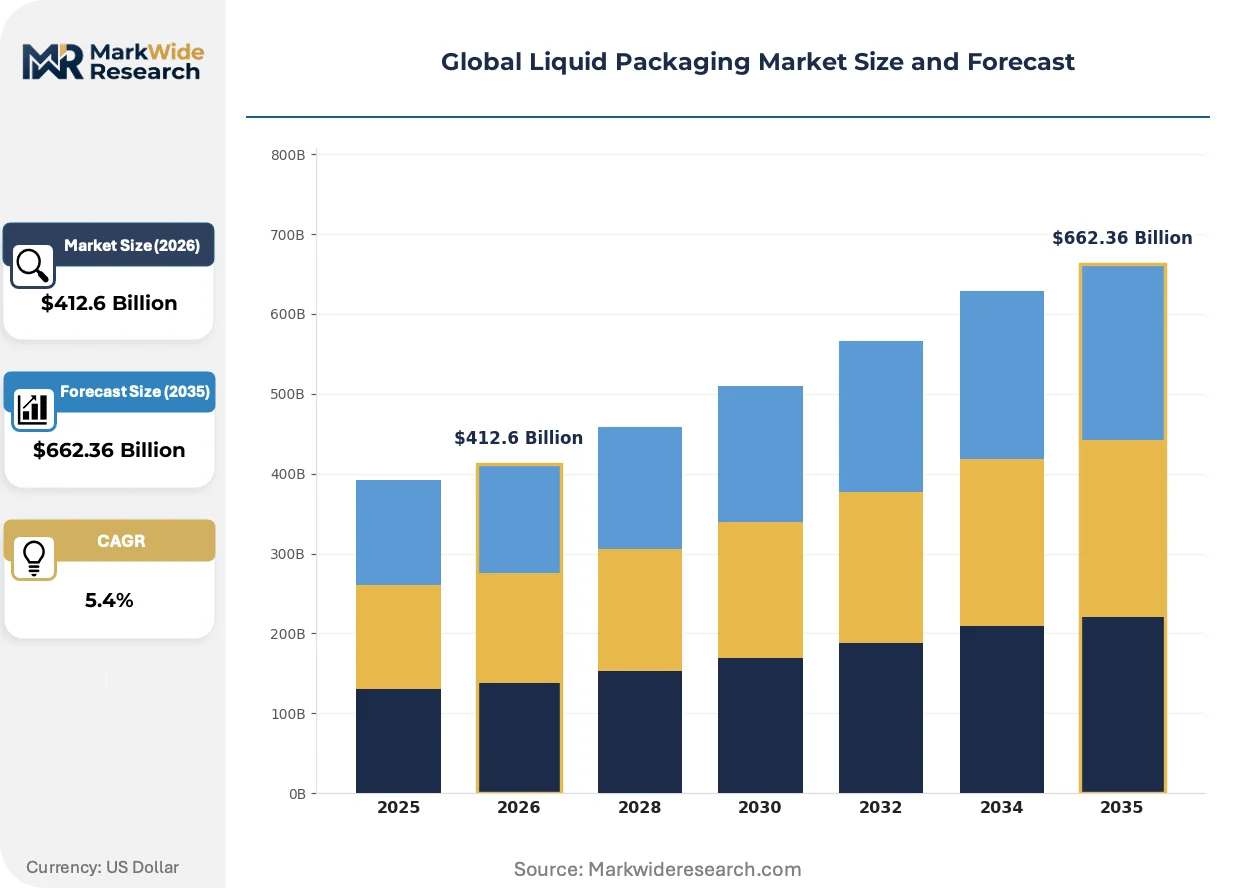
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $662.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottle, Carton, Pouch, Can, Drum, Bag Material: Plastic, Paperboard, Glass, Metal, Biodegradable Composite, Foil Application: Beverages, Pharmaceuticals, Personal Care, Chemicals, Food Ingredients, Agriculture End User: Manufacturers, Distributors, Retailers, Exporters, Brand Owners, Packaging Firms |
| Companies Covered | Amcor plc, Ball Corporation, Crown Holdings, Inc., Tetra Pak International SA, Ardagh Group, SIG Combibloc Group AG, Elopak AS, O-I Glass, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Packaging Market Shifts & Advancements
Digital printing and smart packaging integration are compressing minimum order quantities and enabling mass customization, while regulatory chemistry bans and carbon accounting requirements accelerate material platform transitions.
Water-based barrier coatings incorporating nanoclay platelets are decentralizing aseptic carton manufacturing geography by eliminating solvent-based drying equipment requirements. Regional dairy processors in Vietnam and Thailand are adopting these coatings to qualify for domestic government green procurement preferences. This decentralization is eroding Tetra Pak and SIG Combibloc's historical advantage in centralized high-volume converting facilities.
China's GB 4806 food-contact composite standards and SAMR enforcement protocols are mandating migration testing documentation for every substrate layer, including adhesives and printing inks. Converters serving multinational beverage brands must maintain parallel formulation libraries to satisfy both Chinese and EU compliance pathways. Pharmaceutical and infant nutrition applications face the steepest documentation burden, driving some suppliers to abandon dual-market product lines.
Retail buyer consolidation through cooperative purchasing alliances is compressing supplier negotiation cycles from annual to quarterly frameworks. European grocery chains including Ahold Delhaize and Carrefour are unbundling packaging specification authority from beverage category managers to centralized sustainability procurement teams. This shift is most advanced in Germany and the Netherlands, where private-label shelf-stable milk and juice volumes concentrate negotiating leverage.
Global Liquid Packaging Market Segmentation
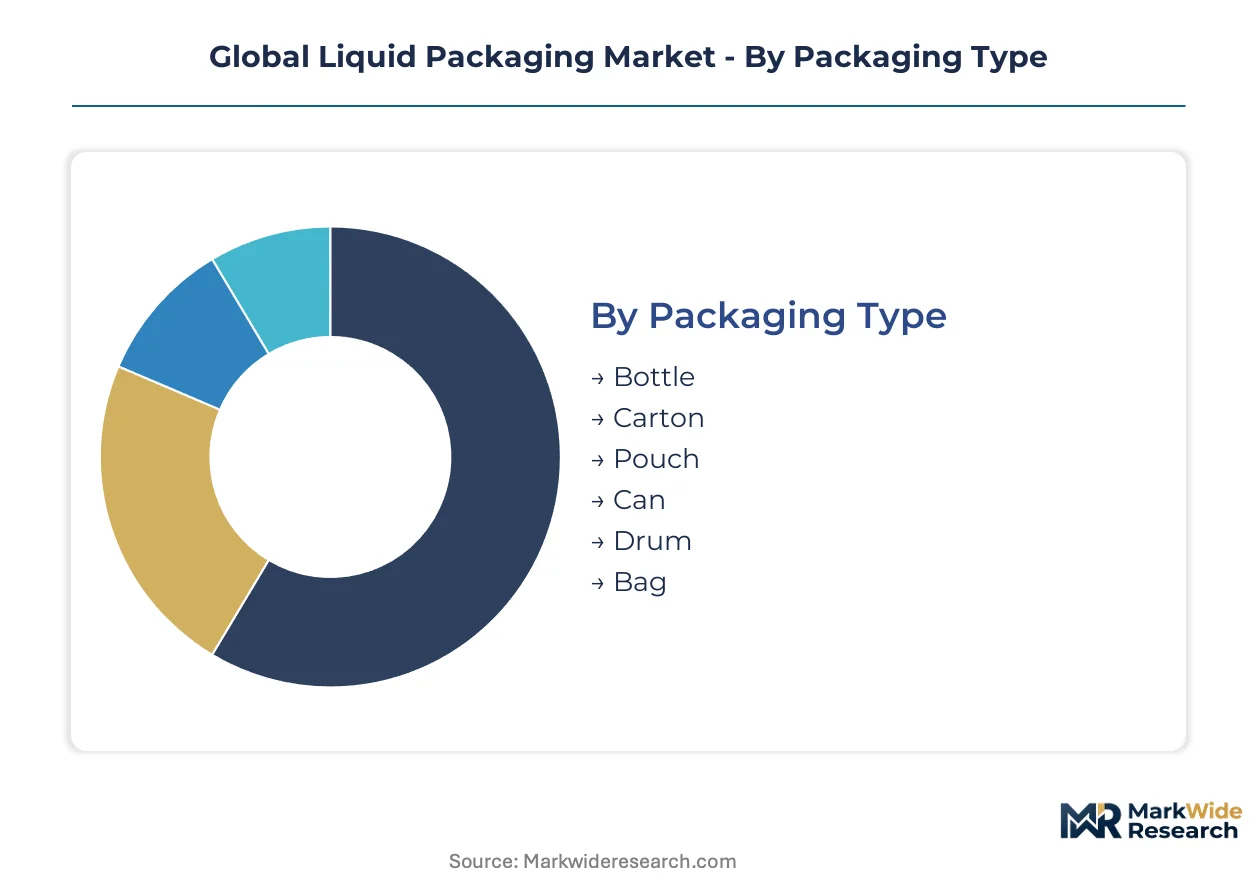
Liquid packaging procurement decisions fragment across material-platform tradeoffs, barrier specifications, and filling equipment compatibility. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Packaging Type:
Supply concentration for aseptic filling equipment locks dairy and juice processors into format-specific capital commitments spanning decade-long depreciation cycles.
- Bottle:Polyethylene terephthalate blow-molding dominates carbonated soft drinks and bottled water with established recycling infrastructure across Germany, Japan, and the United States. Brand owners in São Paulo and Mexico City defend this format through deposit-return system participation and lightweighting investments.
- Carton:Multilayer paperboard-polyethylene-aluminum structures command ambient dairy and juice through efficient cube utilization and renewable material credentials. India's Reliance Retail and DMart expansion pulls aseptic carton volumes into Tier-2 cities where cold-chain infrastructure remains underdeveloped.
- Pouch:Flexible barrier films capture personal care and food ingredient applications where dispensing convenience and shipping cube efficiency outweigh shelf presence requirements.
- Can:Aluminum two-piece construction retains carbonated beverage share through infinite recyclability claims and chilled distribution networks.
- Drum:Industrial-scale containment for chemicals and agriculture inputs leverages steel and plastic rotational molding with UN-certified stackability.
- Bag:Bag-in-box configurations reduce wine and edible oil logistics costs through collapsible empty-state transport.
Today's leader: Carton. Tomorrow's challenger: Pouch.
Material:
Cost tier differentiation separates commodity substrates from certified renewable alternatives commanding sustainability premiums.
- Plastic:Polyethylene terephthalate and high-density polyethylene retain volume leadership through scale economies and mechanical recycling compatibility. EU Single-Use Plastics Directive targets are forcing brand owners toward post-consumer recycled content minimums without fully qualified supply chains.
- Paperboard:Virgin and recycled fiber grades anchor aseptic carton structures with FSC certification requirements from European grocery cooperative purchasing alliances. Water-based nanoclay barrier coatings are decentralizing converting geography across Vietnam and Thailand.
- Glass:Premium beverage and pharmaceutical applications defend this material through inertness and reuse system participation in Germany and Switzerland.
- Metal:Tinplate and aluminum provide absolute oxygen and light barriers for infant nutrition and wine with steel supply concentration exposing converters to energy cost volatility.
- Biodegradable Composite:Polylactic acid sealant layers with nanocellulose oxygen barriers offer compostable end-of-life credentials for organic beverage positioning.
- Foil:Thin-gauge aluminum dependence on Chinese smelter supply creates export quota risk for aseptic carton multilayer structures.
Plastic retains volume dominance. Biodegradable composite climbs the fastest.
Application:
Application-specific barrier requirements range from oxygen transmission below 0.1 cc per square meter per day for sensitive beverages to chemical resistance for agricultural formulations.
- Beverages:Ambient dairy and juice penetration in India and Indonesia drives aseptic carton procurement, while carbonated soft drinks defend polyethylene terephthalate bottle share through fountain and vending channel integration.
- Pharmaceuticals:Blow-fill-seal applications demand multilayer coextrusion with validated sterility assurance levels for parenteral solutions.
- Personal Care:Concentrate and refill pouch systems bypass retail shelf-space constraints through direct-to-subscription e-commerce channels.
- Chemicals:UN-certified drum and intermediate bulk container specifications govern hazardous material transport with compliance documentation burden concentrated in German and Dutch manufacturing.
- Food Ingredients:Edible oils and sauces migrate toward bag-in-box and pouch formats for foodservice dispensing efficiency.
- Agriculture:Pesticide and fertilizer packaging faces tightening EPA and REACH registration requirements for container residue management.
Beverages anchor procurement volume. Personal care gains share fastest.
End User:
Customer type determines specification authority location, with retail buyer consolidation shifting negotiation leverage toward centralized sustainability procurement teams.
- Manufacturers:Beverage and pharmaceutical producers with captive filling lines specify material-platform combinations compatible with existing capital equipment.
- Distributors:Third-party logistics operators prioritize shipping cube efficiency and pallet optimization for ambient and temperature-controlled networks.
- Retailers:Ahold Delhaize and Carrefour cooperative purchasing alliances compress supplier negotiation cycles and unbundle packaging specification authority to sustainability teams.
- Exporters:Cross-border shippers navigate divergent GB 4806, REACH, and FDA food-contact compliance pathways with parallel formulation libraries.
- Brand Owners:Multinational beverage companies balance global format standardization against regional material-platform preferences.
- Packaging Firms:Converters serving dual China-EU markets face steepest documentation burden for pharmaceutical and infant nutrition applications.
Retailers concentrate negotiating leverage. Packaging firms absorb compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European converting capacity for aseptic carton substrates, while emerging economy cold-chain buildouts reshape procurement geography.
United States
Deposit-return system expansion in Oregon and Maine drives polyethylene terephthalate bottle circularity investments. The EPA's impending PFAS designation for fluorinated barriers accelerates mineral coating qualification timelines. Converters in the Great Lakes region are retrofitting lines for post-consumer recycled content minimums.
Germany
Retail cooperative purchasing alliances concentrate specification authority for private-label dairy volumes. The F-Gas Regulation constrains fluorinated chemistry in carton barrier layers. Bavarian packaging engineering clusters specialize in blow-fill-seal pharmaceutical validation systems.
China
Organized retail penetration in Chengdu and Xi'an pulls aseptic carton demand into inland provinces. SAMR enforcement of GB 4806 migration testing documentation burdens dual-market exporters. Yangtze River Delta converters localize water-based nanoclay coating production.
India
Reliance Retail and DMart expansion into Tier-2 cities concentrates aseptic carton procurement growth. FSSAI alignment with Codex standards harmonizes food-contact compliance for multinational brands. Gujarat dairy cooperatives commit to decade-long filling equipment contracts.
Brazil
São Paulo's refrigerated logistics network enables premium barrier pouch penetration for fresh juice. ANVISA pharmaceutical packaging regulations drive blow-fill-seal validation investments. Southeastern converting clusters retrofit polyethylene terephthalate assets for carton sleeve compatibility.
Global Liquid Packaging Market Competitive Landscape
Global majors compete with regional champions across filling equipment lock-in and substrate technology vectors. The market structures around three tiers: integrated converters with captive equipment financing arms, specialized barrier film suppliers, and regional dairy-processor joint ventures. Strategic moves concentrate on aseptic filling equipment contract duration extension and water-based barrier coating qualification.
Within the integrated converter tier, Tetra Pak International SA and SIG Combibloc Group AG exemplify equipment-lock-in business models that structurally favor carton formats. Amcor plc occupies a position spanning multilayer coextrusion capabilities across pharmaceutical and beverage applications. Ball Corporation and Crown Holdings, Inc. represent metal packaging specialists defending carbonated beverage share through infinite recyclability positioning.
| Leading Market Players |
|---|
| Amcor plc |
| Ball Corporation |
| Crown Holdings, Inc. |
| Tetra Pak International SA |
| Ardagh Group |
| SIG Combibloc Group AG |
| Elopak AS |
| O-I Glass |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
Multilayer coextrusion technician scarcity in Vietnam and Thailand widens labor-cost differentials between Southeast Asian converting hubs and European engineering clusters, stretching pricing spreads across premium certified-pharmaceutical grades and economy beverage tiers. This workforce asymmetry compounds raw material volatility in aluminum foil and barrier resin markets.
Pricing Analysis
Input-cost pass-through from thin-gauge aluminum foil and fluorinated barrier chemistry shortages intensifies margin compression across aseptic carton converters. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified pharmaceutical grades from private-label dairy volumes and commodity beverage sleeves. Cost compression in economy tiers reflects post-consumer recycled content mandates without qualified supply chains. Brand owners in carbonated soft drinks exhibit highest price sensitivity, while infant nutrition and pharmaceutical buyers absorb premiums for validated sterility assurance.
Supply Chain Analysis
Reverse-logistics flows for aseptic carton multilayer structures remain economically unviable outside Northern European deposit-return systems, trapping most laminated paperboard-polyethylene-aluminum waste in linear disposal. Supply concentrates in China for thin-gauge foil, Germany for converting equipment engineering, and India for emerging dairy-processor joint ventures. Raw material dependencies encompass Yangtze River Delta aluminum smelters, Middle Eastern polyethylene feedstocks, and Nordic pulp fiber grades. Single-source vulnerability in Chinese foil supply exposes converters to export quota uncertainty. Distribution runs through beverage multinational central procurement, regional dairy cooperative networks, and organized retail private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive compounds regulatory-driven substrate transitions, accelerating demand for fiber-based barrier alternatives and mineral coating qualification investments across beverage and food-contact applications.
For Market Incumbents: Hedge fluorinated barrier chemistry exposure through accelerated mineral and bio-based coating R&D partnerships, particularly in water-based nanoclay formulations. Secure decade-long filling equipment contracts with Indian and Indonesian dairy processors before regional champions consolidate local partnerships. Vertical integration into Yangtze River Delta foil converting mitigates Chinese smelter supply concentration risk.
For New Entrants and Emerging Players: Begin with bio-based barrier composite substrates targeting premium organic beverage positioning in European cooperative purchasing alliances. Tier-2 Indian cities present the most penetrable geography, where Reliance Retail and DMart expansion outpaces established converter localization. Direct-to-subscription concentrate and refill pouch systems for personal care liquids bypass retail shelf-space constraints through e-commerce channel partnerships.
For Investors and Strategic Acquirers: Beverage multinational sustainability procurement teams are the most active acquirer in this space, seeking water-based barrier coating capabilities and regional filling equipment partnerships. Long-term viability hinges on mineral barrier qualification timelines and extended producer responsibility scheme maturation. Monitor EPA PFAS designation implementation and REACH F-Gas restriction enforcement as inflection indicators for fluorinated chemistry sunset acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Qualification | Eliminates solvent-based drying equipment, enabling Vietnam and Thailand dairy processors to meet government green procurement preferences. |
| Aseptic Filling Equipment Contract Extension | Locks Indian dairy cooperatives into decade-long commitments that structurally favor carton formats over polyethylene terephthalate bottles. |
| Post-Consumer Recycled Content Integration | Addresses EU Single-Use Plastics Directive targets while exposing brand owners to supply chain qualification gaps. |
| Regional Converting Joint Venture Formation | Captures organized retail growth in Tier-2 Indian cities through localized production partnerships with Reliance Retail and DMart. |
| Mineral Barrier Chemistry R&D Partnership | Accelerates fluorinated coating replacement timelines ahead of EPA PFAS designations and REACH F-Gas restrictions. |
Research Methodology
Multiple input streams — primary interviews with aseptic filling equipment engineers, barrier film procurement leads at beverage multinationals, and sustainability directors at European retail alliances — were reconciled against secondary validation from SAMR GB 4806 enforcement protocols, EU F-Gas Regulation implementation guidance, and FDA food-contact substance notification databases. Bottom-up volume modeling across packaging type, material platform, and application segments was cross-checked with top-down macroeconomic indicators and trade flow analysis.
Historical volume trajectories were cross-referenced against expert panel inputs from Tetra Pak and SIG Combibloc equipment financing specialists to anchor growth assumptions across the analysis window. Segmentation dimensions encompassed packaging format compatibility, barrier specification tier, filling equipment depreciation cycles, and regional regulatory cluster divergence. CAGRs were derived from slope-intercept modeling of installed base expansion and substrate substitution elasticities, incorporating cold-chain infrastructure buildout rates and extended producer responsibility fee structures as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen aluminum export quota restrictions, rapid PFAS regulatory acceleration beyond current EPA timelines, and breakthrough bio-based barrier performance thresholds. Forecasts reflect documented assumptions regarding mineral coating qualification schedules and dairy processor capital commitment durability. Practitioners should monitor FSSAI-Codex alignment progress, Chinese dual carbon goal enforcement intensity, and deposit-return system expansion announcements for early signals of substrate demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Printed Aluminium Foil Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Standard Liner Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Reel in Box Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
China Packaging Market