
 Pregnancy Care Products Market | 2026-2036
Pregnancy Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pregnancy Care Products Market Analysis
Market Dynamics
Plant-derived squalane is hardening as the preferred emollient base in premium maternity skincare, displacing petrochemical-derived mineral oils across mid-tier and luxury product lines. Johnson & Johnson sustains broad pharmacy shelf presence through legacy trust and pediatric-maternity crossover brand equity. Procter & Gamble leverages its mass-market distribution infrastructure to dominate volume-oriented segments in developing retail channels. The Honest Company, Inc. differentiates through clean-ingredient positioning and direct-to-consumer subscription models that bypass traditional retail markups.
Product Landscape
Pregnancy care products encompass topical formulations, oral supplements, and nutritional consumables engineered to address dermatological changes, micronutrient deficiencies, and metabolic demands during gestation and lactation, with typical topical formulations specifying pH-balanced, fragrance-free, and teratogen-screened ingredient decks. Skincare and vitamins anchor current revenue pools, while nutritional snacks represent the fastest-growing segment as functional food formats gain preference over pill-based regimens among millennial and Gen-Z expecting mothers. Delivery mode stratification shows oral formats retaining volume leadership, though transdermal magnesium and vitamin patches are carving niche positions in wellness-oriented retail.
Regulatory Environment
FDA oversight governs prenatal supplement labeling and teratogenicity screening, while EPA and state-level cosmetic safety frameworks in California and New York impose additional ingredient disclosure burdens on topical manufacturers. REACH compliance in Europe and analogous GB standards in China create divergent formulation requirements that multinational portfolios must navigate. Stakeholders should monitor evolving teratogen classification protocols and state-level clean beauty legislation that could force reformulation cycles ahead of federal harmonization.
Market Dynamics
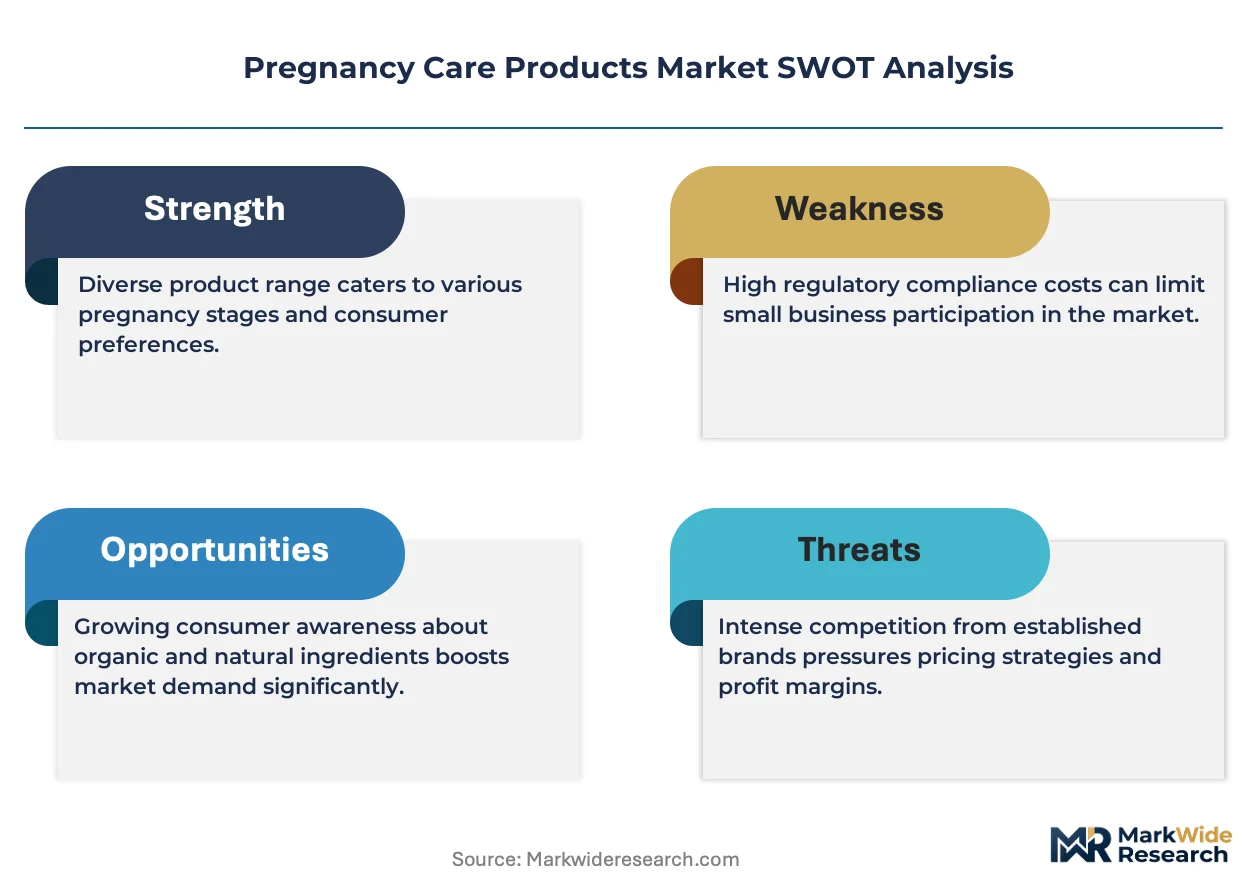
Clean-label formulation mandates from the FDA and analogous EFSA standards are forcing wholesale ingredient deck revisions across maternity skincare portfolios, compressing product development cycles and elevating compliance costs for mid-tier manufacturers.
Growth Catalysts
- Teratogen screening protocols:FDA's expanded prenatal safety classification requirements drive premium positioning for verified clean-ingredient brands in the United States.
- Magnesium transdermal delivery:Wellness-oriented retail channels accelerate adoption of vitamin patches among millennial expecting mothers seeking alternatives to pill-based regimens.
- Functional food formats:Nutritional snack segments capture preference shifts as gestational nutrition moves beyond traditional supplement tablets.
Market Restraints
- Plant-derived squalane supply:Olive and sugarcane feedstock volatility constrains emollient availability for premium maternity skincare lines.
- REACH compliance divergence:European chemical safety frameworks impose formulation incompatibilities that fragment multinational product portfolios.
- Petrochemical emollient substitution:Mineral oil price advantages persist in mass-market channels despite clean-label consumer preferences.
Strategic Opportunities
- Subscription direct-to-consumer models:Recurring revenue formats bypass traditional retail markups and capture lifetime value across gestation and lactation periods.
- India's maternity wellness expansion:FSSAI-aligned prenatal supplement categories remain underpenetrated relative to birth-rate demographics.
- GB standard harmonization:China's evolving cosmetic safety classifications create first-mover advantages for compliant multinational entrants.
Industry Challenges
- Toxicologist certification bottlenecks:Teratogen screening expertise scarcity extends product validation timelines for topical formulations.
- Cross-border formulation reconciliation:Divergent FDA-REACH-GB standards force parallel SKU maintenance and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pregnancy Care Products Market |
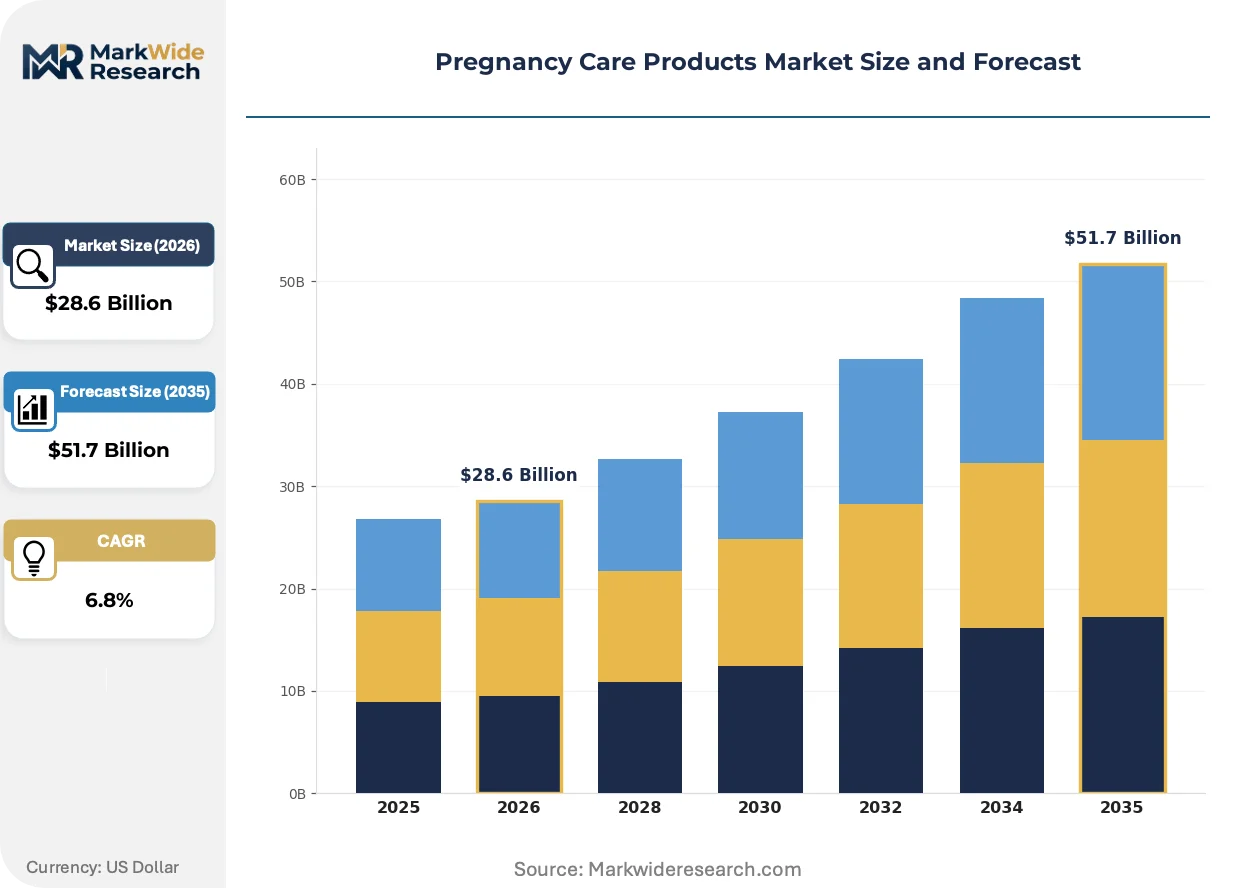
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Supplements, Skincare, Nutritional Snacks Delivery Mode: Oral, Topical, Injectables, Transdermal End User: Expecting Mothers, Healthcare Providers, Clinics, Pharmacies Packaging Type: Bottles, Blister Packs, Tubes, Pouches |
| Companies Covered | Clarins Group, Mama Mio U.S. Inc., Johnson & Johnson, Procter & Gamble, Abbott Laboratories, E.T. Browne Drug Co., Inc., Expanscience Laboratories, Inc., Noodle & Boo, The Honest Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pregnancy Care Products Market Emerging Trajectories
Biotechnology-derived ingredients and AI-assisted teratogen screening are compressing development timelines while reshaping how maternity brands validate safety claims and communicate transparency to expecting mothers.
Fermentation-based squalane production is expanding into premium maternity skincare as a functionally equivalent alternative to plant-derived sources. Biotech suppliers in South Korea and Singapore scale manufacturing capacity to serve clean-label formulators. This synthetic biology approach is expanding into price-competitive positioning against traditional olive-extraction methods.
REACH's 2024 microplastic restriction amendments tighten scrutiny on rinse-off maternity products containing synthetic polymers. European formulators accelerate biodegradable emulsifier substitution programs ahead of enforcement deadlines. Maternity skincare lines targeting Germany and France face compressed reformulation windows to maintain shelf access.
Expecting mothers increasingly demand ingredient provenance verification through blockchain-anchored supply chain transparency. Direct-to-consumer brands deploy QR-code-linked batch testing data to displace legacy trust mechanisms. This verification-first purchasing behavior concentrates most visibly in California and New York state markets where clean beauty legislation outpaces federal standards.
Pregnancy Care Products Market Segmentation
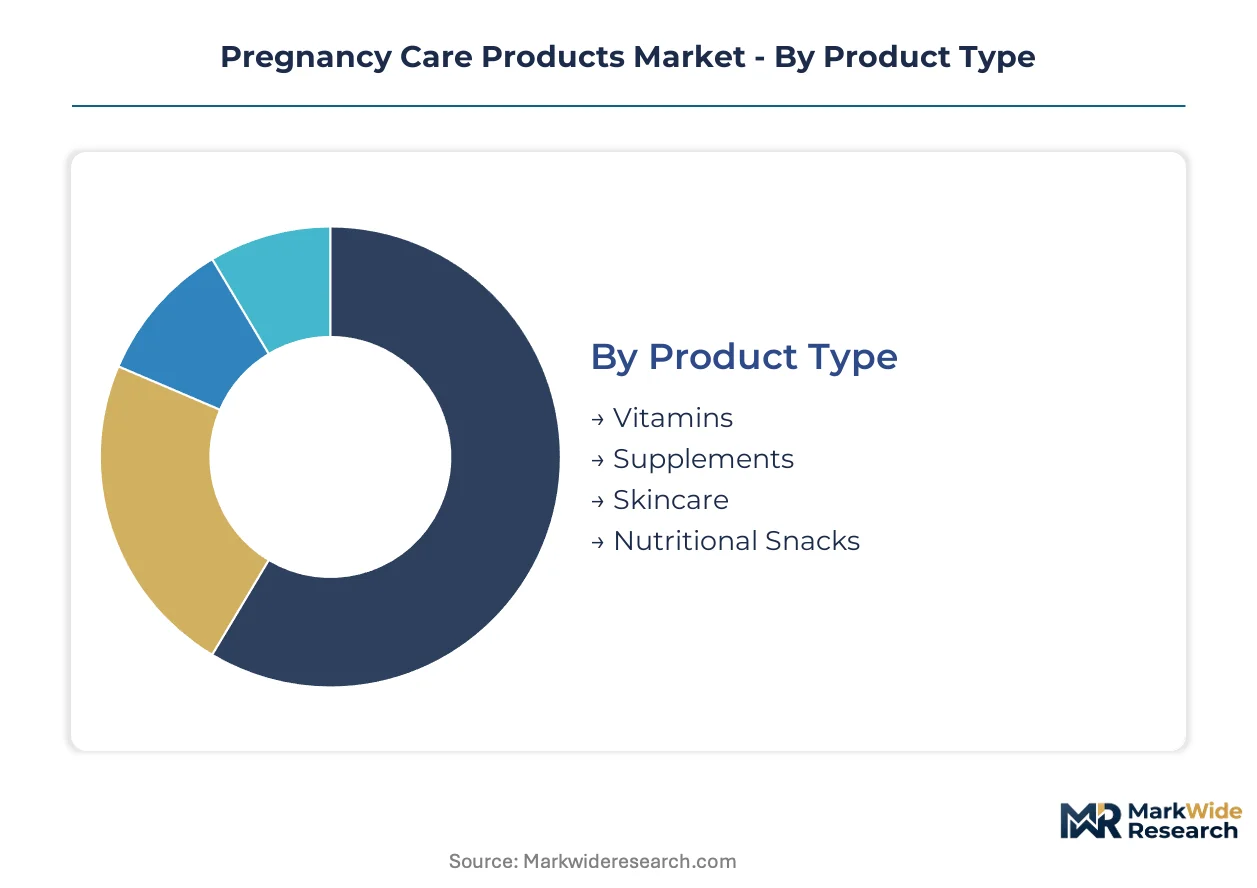
Pregnancy care purchasing decisions cascade through multiple dimensions simultaneously—product efficacy claims, delivery convenience, and channel accessibility each filter buyer choice differently. Understanding how these segments intersect reveals where formulation investments convert to revenue and where distribution gaps persist.
Product Type:
Expecting mothers prioritize ingredient transparency over brand heritage when selecting pregnancy-specific formulations, elevating clean-label verification to a primary screening mechanism.
- Vitamins:Folic acid, iron, and DHA complexes dominate prenatal protocols with standardized USP verification. Demand concentrates in the United States where OB-GYN prescription patterns and insurance reimbursement frameworks sustain volume leadership despite pill fatigue among younger demographics.
- Supplements:Magnesium glycinate, probiotic strains, and choline derivatives address gestational-specific deficiencies beyond standard prenatal multivitamins. Millennial and Gen-Z expecting mothers in California and New York drive preference for subscription-based supplement regimens with third-party purity certification.
- Skincare:Stretch mark oils, acid-free cleansers, and melasma-targeting serums formulated without retinoids or salicylic acid derivatives.
- Nutritional Snacks:Protein-fortified bars, omega-3 enriched crackers, and nausea-relief ginger chews gaining traction as functional food alternatives.
Vitamins lead on scale; nutritional snacks lead on momentum.
Delivery Mode:
Route of administration selection tracks directly with symptom severity and lifestyle integration constraints, splitting the market between clinical oversight requirements and self-directed wellness routines.
- Oral:Tablets, capsules, and softgels retain volume dominance through pharmacy distribution infrastructure and physician familiarity. The United States maintains the highest per-capita consumption of prescription prenatal vitamins, though pill burden drives exploration of alternative formats among working mothers seeking regimen simplification.
- Topical:Emollient creams, belly balms, and perineal massage oils applied directly to skin with teratogen-screened ingredient decks. Premium positioning in Germany and France demands REACH-compliant formulation documentation that mass-market channels often bypass.
- Injectables:Prescription iron dextran and antiemetic formulations administered in clinical settings for severe deficiency or hyperemesis gravidarum cases.
- Transdermal:Magnesium and vitamin B6 patches delivering micronutrients through dermal absorption, bypassing gastrointestinal intolerance.
Oral formats dominate current volume; transdermal applications show steepest expansion trajectory.
End User:
Channel selection determines pricing power and loyalty mechanics, with direct-to-consumer models capturing lifetime value across gestation and lactation windows that transactional pharmacy purchases cannot replicate.
- Expecting Mothers:Primary decision-makers conducting independent research on teratogenicity databases and clean beauty certification platforms. Self-directed buyers in urban California and New York markets demonstrate highest willingness-to-pay for blockchain-verified supply chain transparency.
- Healthcare Providers:OB-GYN practices and midwifery clinics influencing supplement selection through prescription authority and sample distribution. Provider networks in the United States increasingly face patient demand for clean-label alternatives to legacy pharmaceutical brands.
- Clinics:Fertility centers and prenatal care facilities bundling nutritional protocols with diagnostic services.
- Pharmacies:Retail and specialty pharmacy channels maintaining shelf presence through insurance reimbursement relationships.
Expecting mothers drive margin expansion; healthcare providers anchor volume stability.
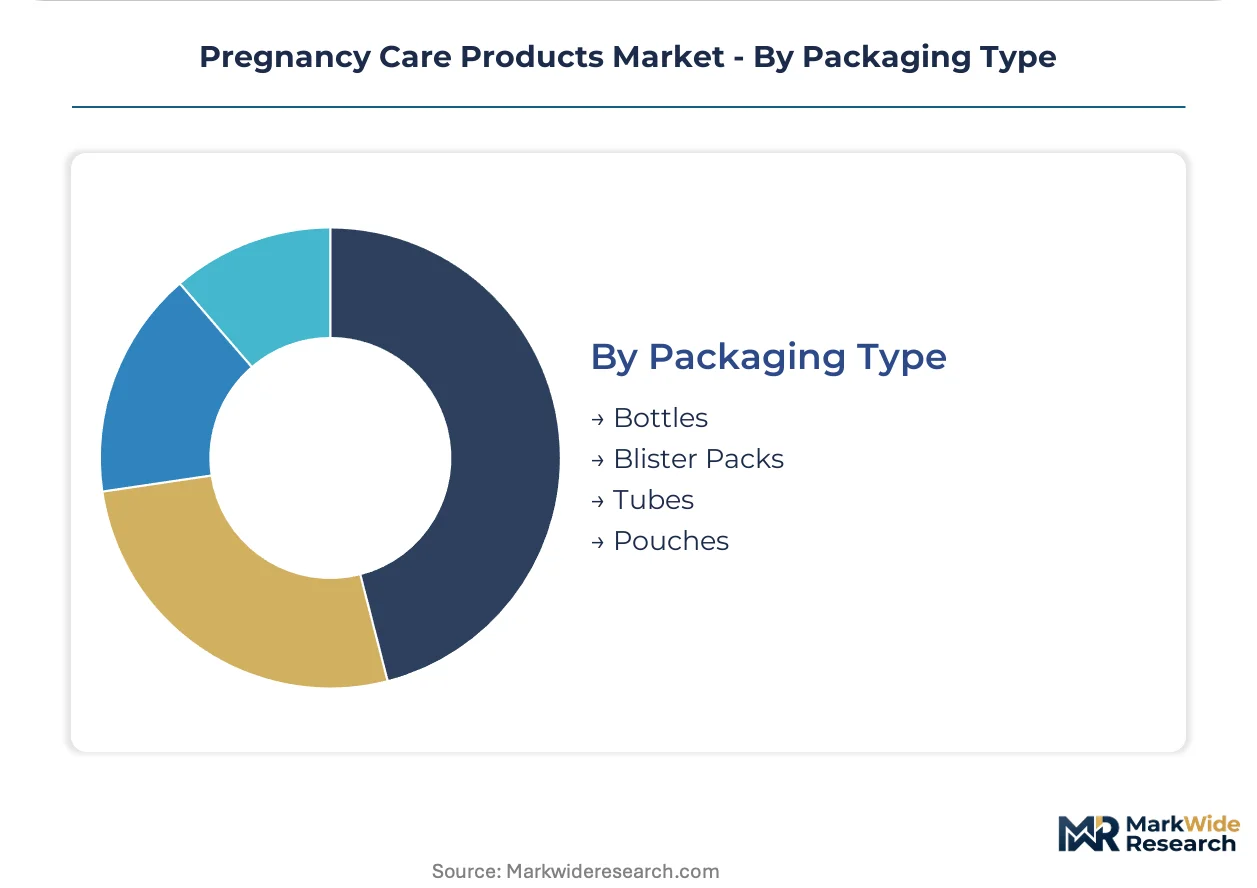
Packaging Type:
Format selection balances convenience, preservation requirements, and sustainability positioning as ESG criteria penetrate maternal purchasing decisions.
- Bottles:Amber glass and post-consumer recycled plastic containers for liquid supplements and oil-based skincare with oxidation sensitivity. European markets under REACH microplastic scrutiny accelerate biodegradable material transitions ahead of enforcement deadlines.
- Blister Packs:Aluminum-plastic laminate cards enabling precise dosing compliance and portability for prenatal vitamin regimens. Single-unit packaging dominates pharmacy dispensing in the United States where insurance-driven 30-day supply norms prevail.
- Tubes:Collapsible aluminum and sugarcane-derived bioplastic for topical creams and ointments.
- Pouches:Flexible film packaging for nutritional snacks and single-serve supplement powders targeting on-the-go consumption.
Bottles retain format leadership; pouches gain share fastest among millennial convenience seekers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors premium maternity skincare formulation activity, with clean-label startups clustering near ingredient biotechnology hubs. Subscription direct-to-consumer models concentrate in coastal metropolitan zones where millennial density supports recurring revenue economics. Regulatory divergence between FDA, ECHA, and GB standards forces parallel inventory management across multinational distribution networks.
United States
OB-GYN prescription patterns and insurance reimbursement frameworks sustain prenatal vitamin volume leadership. FDA teratogen screening protocols elevate compliance costs for topical manufacturers entering pharmacy channels. California's clean beauty legislation outpaces federal standards, driving blockchain-verified supply chain investments among Los Angeles and San Francisco formulators.
Germany
REACH microplastic restrictions accelerate biodegradable emulsifier substitution in rinse-off maternity products. ECHA documentation requirements fragment multinational portfolios serving pharmacy and wellness retail channels. Berlin and Munich house specialized toxicology consultancies addressing teratogen classification bottlenecks for European market entry.
China
GB cosmetic safety standards create first-mover advantages for compliant multinational entrants in tier-one cities. NMPA prenatal supplement registration timelines extend product launch windows versus Western markets. Shanghai and Guangzhou concentrate cross-border e-commerce distribution infrastructure targeting millennial expecting mothers.
India
FSSAI-aligned prenatal supplement categories remain underpenetrated relative to birth-rate demographics in Maharashtra and Gujarat. Domestic Ayurveda-inspired maternity wellness brands compete with multinational pharmacy chains for urban market share. Mumbai and Bangalore emerge as direct-to-consumer subscription logistics hubs.
France
ANSM pharmacovigilance requirements elevate documentation burdens for maternity skincare claiming dermatological benefits. Pharmacy channel concentration preserves premium pricing power for heritage cosmetic houses. Paris clusters formulation R&D activity targeting REACH-compliant export markets.
Pregnancy Care Products Market Vendor Landscape
Global majors compete with regional champions across distribution infrastructure and clean-label credibility. The vendor base stratifies between mass-market pharmacy incumbents, direct-to-consumer subscription specialists, and biotechnology-enabled ingredient suppliers. Three archetypes dominate: legacy pharmaceutical conglomerates with pediatric-maternity crossover equity, venture-backed clean-beauty pure-plays, and fermentation technology suppliers scaling plant-derived emollient alternatives. Competitive intensity centers on M&A activity consolidating subscription platforms and capacity expansion in South Korean biotech squalane production.
Within the clean-label specialist tier, The Honest Company, Inc. and Mama Mio U.S. Inc. occupy positions exemplifying direct-to-consumer subscription economics and premium topical positioning respectively. Johnson & Johnson anchors mass-market pharmacy presence through legacy trust mechanisms. These three entities represent divergent strategic bets on channel structure: owned digital relationships versus wholesale retail dependency versus institutional prescription authority.
| Leading Market Players |
|---|
| Clarins Group |
| Mama Mio U.S. Inc. |
| Johnson & Johnson |
| Procter & Gamble |
| Abbott Laboratories |
| E.T. Browne Drug Co., Inc. |
| Expanscience Laboratories, Inc. |
| Noodle & Boo |
| The Honest Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Plant-derived squalane feedstock costs cascade through premium maternity skincare tiers, with olive and sugarcane extraction economics separating luxury formulations from mid-market alternatives that still carry mineral oil price advantages in mass pharmacy channels.
Pricing Analysis
Input-cost pass-through from biotech fermentation capacity expansion in South Korea and Singapore is compressing squalane pricing differentials between synthetic biology and traditional plant-extraction methods. Pricing stratifies across premium, standard, and economy tiers based on clean-label certification depth and teratogen-screening documentation rigor. Cost compression in mid-tier topical segments is intensifying because REACH microplastic compliance investments elevate European formulation expenses that mass-market channels resist absorbing. Millennial expecting mothers in California and New York demonstrate lowest price sensitivity, while pharmacy-dependent buyers in developing retail channels anchor volume at economy positioning.
Supply Chain Analysis
Direct-to-consumer subscription channels handle recurring revenue buyer demand, bypassing traditional retail markups that fragment margin capture across gestation and lactation windows. Manufacturing concentration centers on South Korea and Singapore for fermentation-based squalane, the United States for clean-label formulation R&D, and China for GB-compliant packaging materials. Raw material dependencies include olive-derived emollients, sugarcane feedstocks, and post-consumer recycled plastics facing ESG sourcing verification. Single-source vulnerability runs through South Korean biotech suppliers scaling capacity ahead of demand curves. Distribution runs through owned digital platforms, pharmacy wholesale networks, and cross-border e-commerce infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pregnancy care economics favor margin expansion through subscription lifetime value capture and biotech ingredient cost curves, as clean-label certification premiums sustain pricing power against commodity alternatives.
For Market Incumbents: Cement pharmacy shelf presence through pediatric-maternity crossover brand equity while accelerating teratogen-screening certification investments that emerging clean-label specialists cannot match. Defend against direct-to-consumer subscription erosion by acquiring recurring revenue platforms or building captive subscription logistics in coastal metropolitan zones. Capacity addition in South Korean fermentation partnerships secures squalane supply advantages. For New Entrants and Emerging Players: The premium-economy price gap in India's underpenetrated FSSAI-aligned categories creates white-space entry before multinational pharmacy chains consolidate distribution. Target Maharashtra and Gujarat urban corridors with Ayurveda-inspired positioning that domestic buyers trust over imported formulations. Direct-to-consumer subscription logistics anchored in Mumbai and Bangalore bypass legacy wholesale dependency. For Investors and Strategic Acquirers: Roll-up economics work for direct-to-consumer subscription platforms because gestation-lactation recurring revenue windows generate customer lifetime values that transactional pharmacy purchases cannot replicate. Acquisition target archetype: clean-label specialists with blockchain-verified supply chain infrastructure and toxicologist certification relationships. Watch FDA-REACH-GB standard harmonization progress as inflection indicator for multinational portfolio consolidation viability.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Squalane Capacity Expansion | Fermentation-based production in South Korea displaces olive extraction cost structures for clean-label formulators. |
| Subscription Platform Acquisition | Recurring revenue models capture lifetime value across gestation and lactation that pharmacy transactions forfeit. |
| Blockchain Supply Chain Verification | QR-code-linked batch testing data satisfies California and New York clean beauty legislation ahead of federal standards. |
| REACH Microplastic Compliance Reformulation | Biodegradable emulsifier substitution preserves Germany and France shelf access ahead of enforcement deadlines. |
| India Direct-to-Consumer Logistics Buildout | Mumbai and Bangalore distribution hubs address FSSAI-aligned category underpenetration relative to birth-rate demographics. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maternity skincare formulators, OB-GYN practice administrators, pharmacy category buyers, direct-to-consumer brand operators, and toxicology certification consultants with secondary validation against FDA teratogen classification databases, REACH compliance filings, FSSAI prenatal supplement registrations, and customs trade data for squalane feedstock flows. Bottom-up product-level demand modeling and top-down demographic birth-rate projections were triangulated for convergence.
Historical reference periods anchored the forecast window to pre-pandemic baseline consumption patterns and post-acceleration normalization trends across the modeling period. Segmentation dimensions modeled include product type, delivery mode, end user archetype, packaging format, and regional regulatory cluster. CAGRs were derived from exponential smoothing of annual growth trajectories. Industry-specific forecast inputs incorporated teratogen screening protocol evolution timelines and biotech fermentation capacity expansion announcements.
Caveats apply where FDA-REACH-GB standard divergence, squalane feedstock commodity volatility, or toxicologist certification bottlenecks could materially shift the outlook. Forecasts reflect documented assumptions about clean-label adoption curves and subscription model penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
IVF Services Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Contraceptives Market
Reproductive Health
In Vitro Fertilization (IVF) Market