
 Surrogacy Market | 2026-2036
Surrogacy Market Size, Share, and Industry Trends Forecast 2026-2036
Surrogacy Market Analysis
Clinic networks and independent surrogacy agencies are reshaping how intended parents access cross-border reproductive services. Circle Surrogacy leverages integrated legal and medical coordination to sustain its position in complex international arrangements. Growing Generations anchors its competitive stance through specialization in LGBTQ+ family formation. ConceiveAbilities differentiates via rigorous surrogate screening protocols and geographic coverage across multiple U.S. states.
Surrogacy encompasses assisted reproductive arrangements where a gestational carrier bears a child for intended parents, typically involving in vitro fertilization with embryos created from the intended parents' or donors' genetic material and transferred to the carrier's uterus. The practice serves individuals and couples unable to conceive or carry pregnancies, including infertility patients, same-sex partners, and single parents seeking biological children. Gestational surrogacy dominates clinical volume due to reduced legal and emotional complexity compared to traditional arrangements. The intended parents dimension shows LGBTQ+ couples and single parents as the fastest-expanding demand cohorts. Legal framework segmentation reveals regulated jurisdictions commanding premium pricing while unregulated markets attract cost-sensitive cross-border clients.
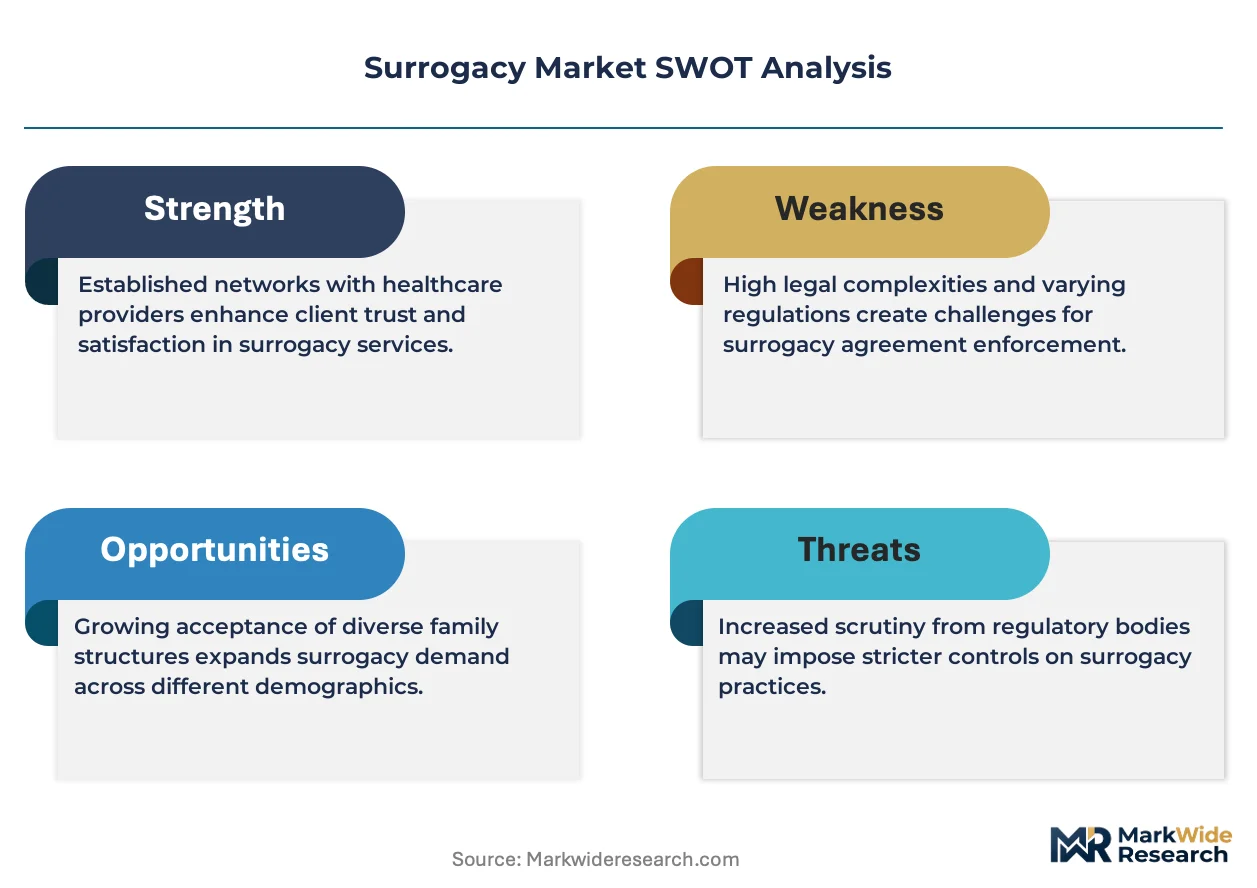
The FDA oversees gamete and embryo handling standards in the United States while state-level statutes create a patchwork of enforceability for surrogacy contracts. The EMA and national health technology assessment bodies in Europe influence reimbursement and clinical practice standards for fertility treatments. Forward-looking stakeholders must monitor pending legislative revisions in destination countries and assess how insurance coverage expansion for infertility services alters patient out-of-pocket exposure.
Market Dynamics
Cross-border reproductive tourism is fragmenting service delivery models as intended parents arbitrage legal frameworks and cost differentials across multiple jurisdictions simultaneously.
Growth Catalysts
- Preimplantation Genetic Testing:Embryo screening protocols now detect chromosomal abnormalities with precision that reduces transfer failures. Fertility clinics in Georgia and Ukraine deploy these tools to attract international clients.
- Commercial Surrogacy Legislation:California's statutory framework provides contractual enforceability that domestic agencies leverage to structure arrangements with reduced legal uncertainty.
- Gestational Carrier Matching Platforms:Digital intake systems compress the timeline between initial inquiry and medical clearance. LGBTQ+ couples utilize these tools at accelerating rates.
Market Restraints
- Compensation Cost Escalation:Base surrogate payments in the United States now exceed $50,000, excluding medical and legal fees. Cost-sensitive intended parents migrate to unregulated markets.
- Jurisdictional Concentration Risk:Ukraine's surrogacy infrastructure depends on stable diplomatic relations and exit documentation procedures. Geopolitical disruption threatens service continuity.
- Gamete Quality Limitations:Advanced maternal age among intended mothers reduces viable embryo yields. Donor oocyte utilization introduces additional coordination complexity.
Strategic Opportunities
- Insurance Reimbursement Expansion:Several U.S. states now mandate fertility coverage including surrogacy-related medical costs. Employers in these jurisdictions add surrogacy benefits to compete for talent.
- Artificial Intelligence Matching:Machine learning algorithms analyze psychological profiles and medical histories to predict carrier-intended parent compatibility. Early adopters report reduced match dissolution rates.
- Integrated Legal-Medical Bundling:Full-service agencies that control both clinical coordination and contract drafting capture margin that fragmented providers forfeit.
Industry Challenges
- Reproductive Endocrinologist Scarcity:Fellowship-trained specialists concentrate in coastal metropolitan areas. Interior regions face appointment backlogs exceeding six months.
- Cross-Border Documentation Complexity:Citizenship acquisition for infants born via international surrogacy requires navigation of consular procedures and DNA verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surrogacy Market |
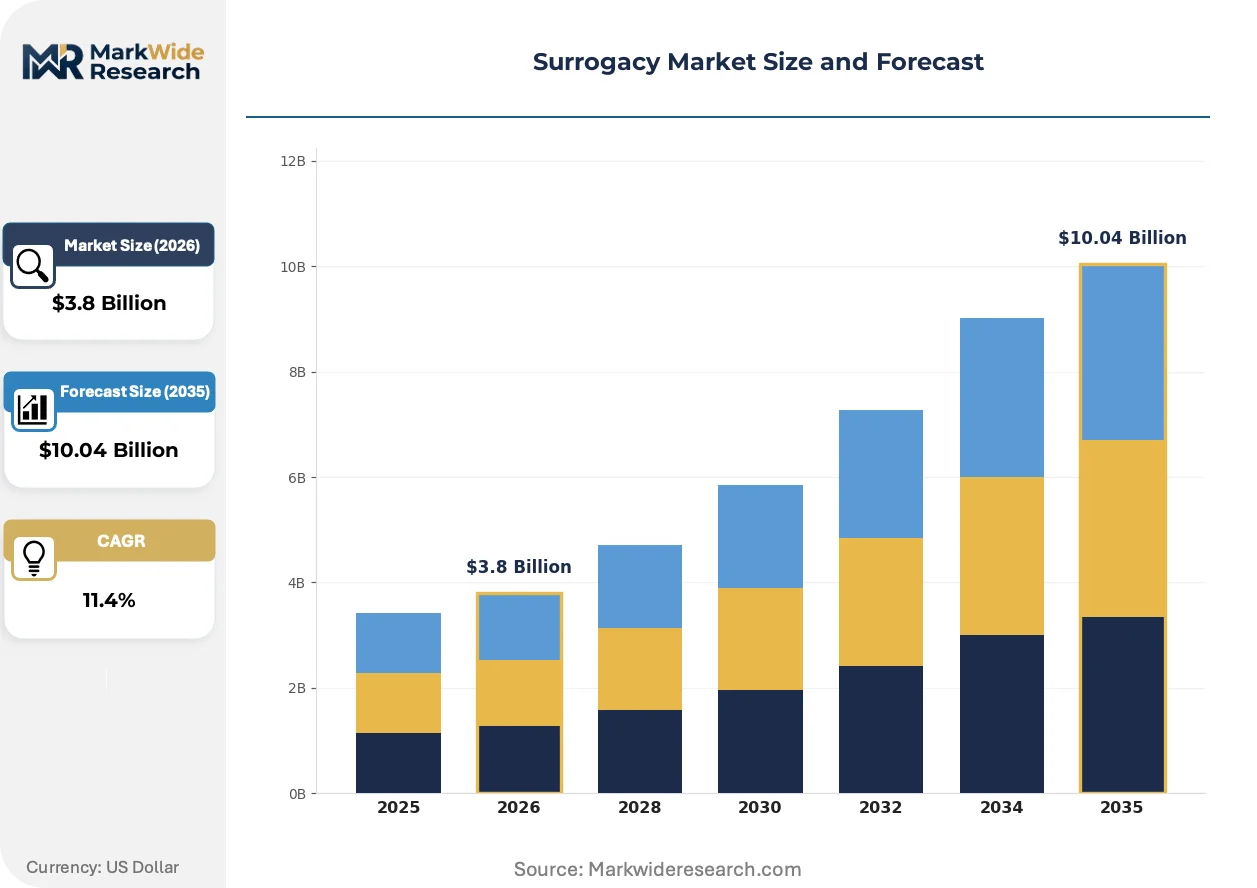
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Surrogacy Type: Traditional Surrogacy, Gestational Surrogacy, Altruistic Surrogacy, Commercial Surrogacy Intended Parents: Single Parents, Heterosexual Couples, LGBTQ+ Couples, Infertility Patients Legal Framework: Restricted, Regulated, Unregulated, Legalized Payment Structure: Direct Payment, Installment Plans, Insurance Coverage, Donor Compensation |
| Companies Covered | Creative Family Connections, All Families Surrogacy, Hatch Fertility, American Surrogacy, Southern Surrogacy, Circle Surrogacy, Growing Generations, Family Source Consultants, ConceiveAbilities, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surrogacy Market Emerging Trajectories
Reproductive medicine is experiencing simultaneous compression of treatment timelines and expansion of addressable patient populations through automation and policy adaptation.
Non-invasive prenatal testing combined with expanded carrier screening is collapsing the diagnostic window for fetal anomalies. Fertility clinics in the United States and Spain integrate these tools into standard pre-transfer protocols. Intended parents now expect comprehensive genetic risk assessment before embryo selection, compressing the traditional sequence of conception-then-screening into a single pre-implantation decision point.
France's Bioethics Law revisions and Germany's ongoing legislative debates signal approaching liberalization of surrogacy access within previously restrictive European jurisdictions. These frameworks currently criminalize commercial arrangements, forcing residents into cross-border structures. Policy committees in both countries are evaluating regulated altruistic models that would retain domestic clinical volume and reduce legal exposure for citizens.
Subscription-based fertility navigation services are displacing traditional agency retainers among first-time intended parents. These platforms charge monthly fees for education, provider matching, and milestone tracking rather than lump-sum placement fees. Younger demographics in the United States and Australia demonstrate strongest uptake, preferring transparent cost structures and self-directed research tools over conventional full-service representation.
Surrogacy Market Segmentation
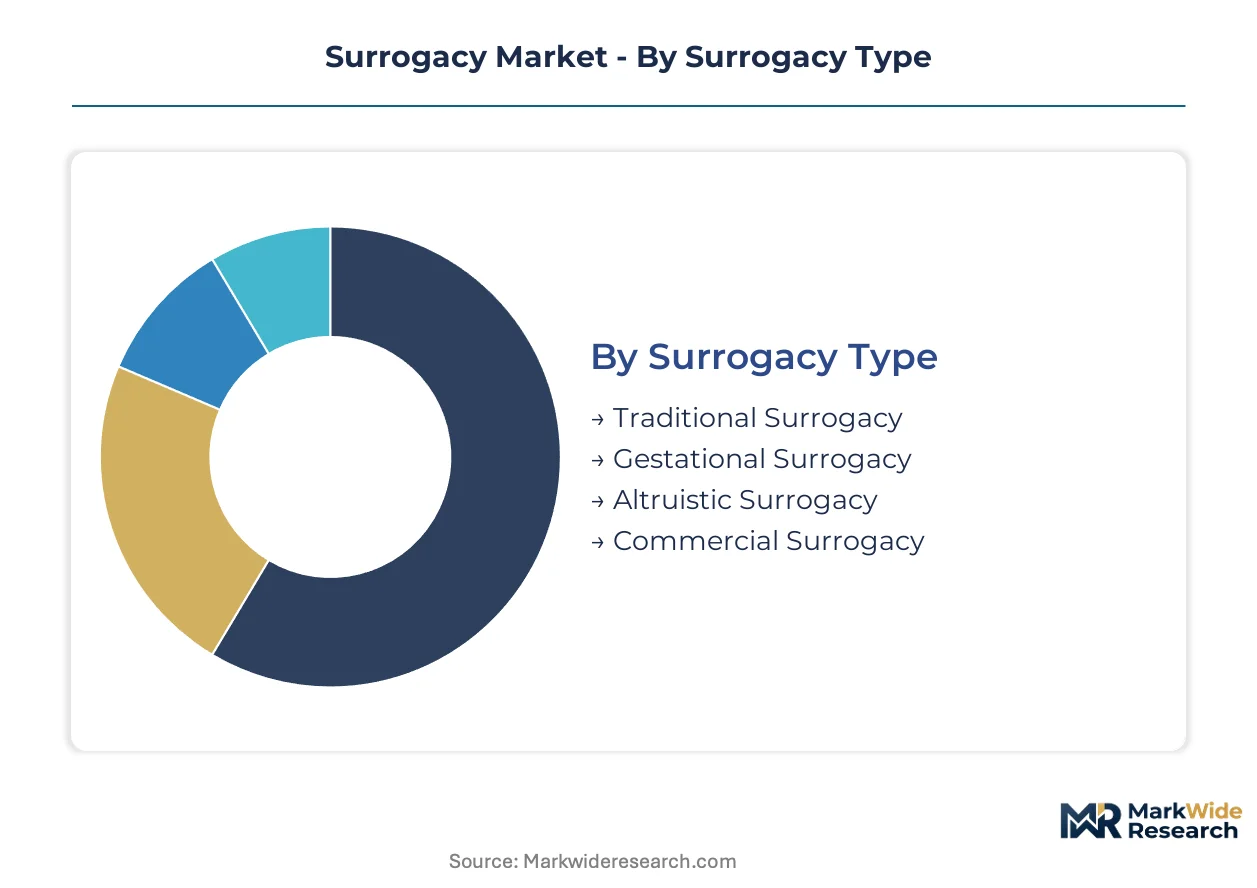
Segmentation in the surrogacy market reveals divergent commercial cycles across arrangement types and client profiles. Understanding these patterns enables providers to allocate clinical capacity and legal resources toward segments with the shortest conversion timelines and highest lifetime value.
Surrogacy Type:
Gestational arrangements turn over fastest from inquiry to embryo transfer, while traditional surrogacy cycles extend longest due to genetic relationship counseling and elevated legal complexity.
- Gestational Surrogacy:The carrier bears no genetic relationship to the embryo, created via IVF using intended parents' or donor gametes. Demand concentrates in California and Georgia where statutory clarity accelerates matching timelines. Preimplantation genetic testing integration reduces transfer failure rates and shortens overall treatment duration.
- Commercial Surrogacy:Carriers receive monetary compensation beyond expense reimbursement, creating structured payment schedules that attract full-time participants. Ukraine and Georgia clinics leverage this model to capture cost-sensitive international clients from restrictive European jurisdictions. Regulatory arbitrage sustains pricing advantages over domestic U.S. arrangements.
- Traditional Surrogacy:The carrier contributes her own oocyte, creating genetic motherhood that complicates legal finalization. U.S. jurisdictions increasingly discourage this structure through unenforceable contract statutes.
- Altruistic Surrogacy:Carriers receive only medical and ancillary expense coverage, reducing total arrangement cost. Canadian and Australian frameworks mandate this model, extending match timelines due to smaller candidate pools.
Gestational surrogacy dominates installed base. Commercial surrogacy is where expansion concentrates.
Intended Parents:
Cost tier stratification separates premium full-service clients from self-directed budget segments, with payment capacity determining agency selection and geographic destination.
- LGBTQ+ Couples:Male couples require both egg donation and gestational carriage, doubling coordination complexity and extending preparation phases. California agencies and Israeli reproductive tourism operators have built specialized intake protocols serving this cohort. Employer-sponsored fertility benefits increasingly cover surrogacy for this demographic.
- Infertility Patients:Heterosexual couples with failed IVF cycles or absolute uterine factor infertility pursue surrogacy as final reproductive pathway. U.S. fertility clinic networks capture this segment through integrated referral pathways from failed autologous treatment.
- Single Parents:Solo intended parents, predominantly women using donor sperm, present streamlined legal profiles that accelerate contract finalization. Australian and Canadian frameworks show rising single-parent application volumes.
- Heterosexual Couples:Married couples with female-factor infertility represent the historical core demographic, now declining as a share of total volume due to faster growth in other segments.
Infertility patients retain the largest historical volume. LGBTQ+ couples are climbing the fastest.
Legal Framework:
Geographic concentration of demand follows regulatory permissiveness, with patient flows migrating toward jurisdictions offering contractual enforceability and exit documentation certainty.
- Regulated:Statutory frameworks in California, Illinois, and Ukraine provide pre-birth order mechanisms that eliminate post-birth adoption requirements. These jurisdictions command premium pricing due to reduced legal risk.
- Unregulated:Absence of specific prohibition enables practice without statutory guidance, creating interpretive uncertainty that cost-sensitive clients accept. Georgia operates in this space, attracting European cross-border traffic.
- Legalized:Explicit statutory authorization with procedural requirements, as in Greece and certain U.S. states, establishes clear governmental oversight that reassures risk-averse intended parents.
- Restricted:Criminal or civil penalties for commercial arrangements force residents into cross-border structures. France and Germany maintain these frameworks despite active legislative reconsideration.
Regulated frameworks dominate installed base. Unregulated markets are gaining share fastest.
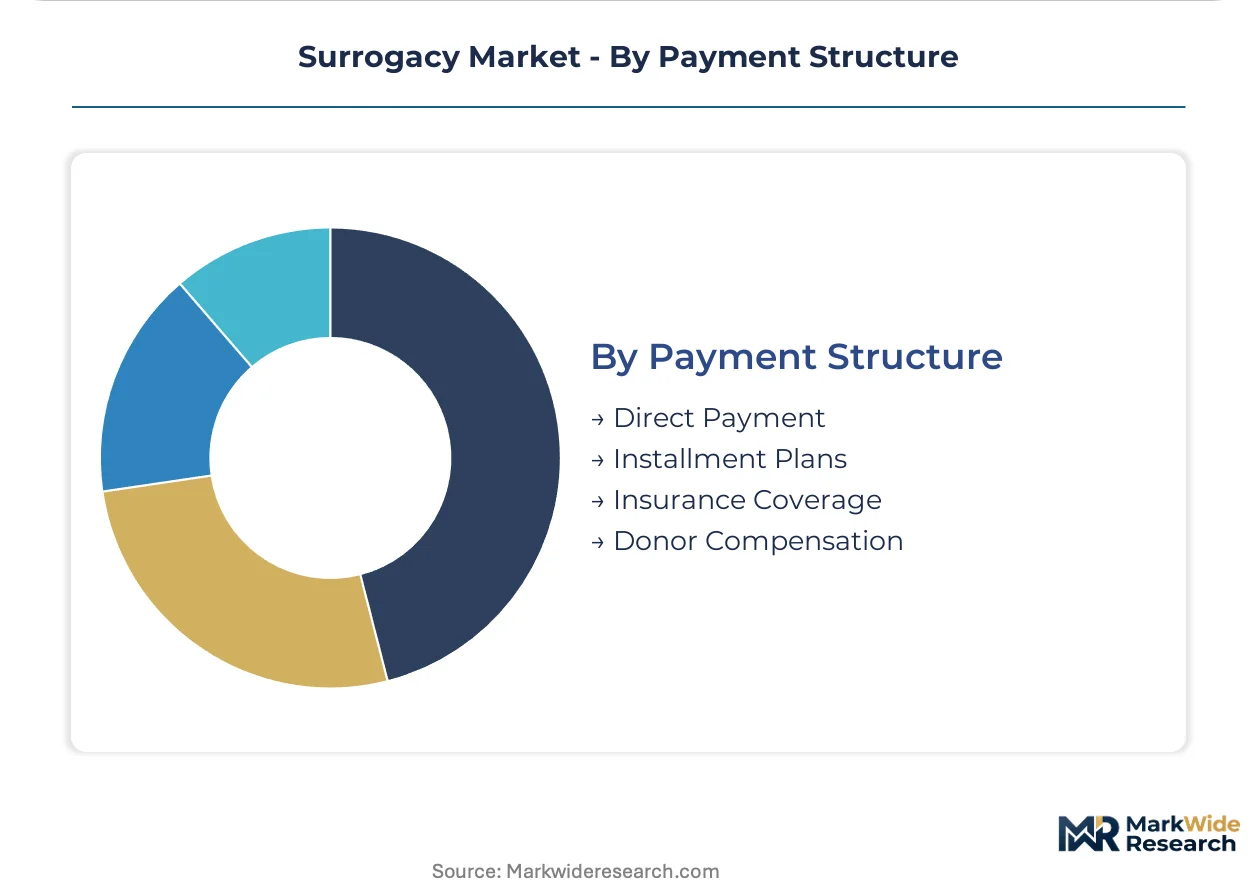
Payment Structure:
Margin distribution across the value chain varies sharply by payment mechanism, with insurance intermediation capturing administrative fees that would otherwise accrue to agencies.
- Direct Payment:Lump-sum transfers from intended parents to escrow agents, then to carriers and clinics, minimize administrative overhead. U.S. domestic arrangements predominantly utilize this structure.
- Insurance Coverage:Employer-sponsored fertility benefits and state mandates in Massachusetts, New York, and Illinois now include surrogacy-related medical costs. This mechanism is displacing out-of-pocket funding for qualifying employees.
- Installment Plans:Agency-structured payment schedules aligned with pregnancy milestones reduce upfront capital requirements. Emerging subscription-based navigation platforms favor this approach.
- Donor Compensation:Separate payment streams for egg or sperm providers add coordination layers to financial management. Donor oocyte utilization introduces this complexity into gestational arrangements.
Direct payment dominates installed base. Insurance coverage is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of gamete and embryo handling standards anchors the United States as the dominant geography, while state-level statutes create the regulatory patchwork that shapes patient flows and clinic location decisions across the surrogacy market.
United States
California's statutory framework provides pre-birth order mechanisms that eliminate post-birth adoption requirements, attracting LGBTQ+ couples and international intended parents seeking legal certainty. The state's commercial surrogacy legislation permits enforceable contracts with structured compensation schedules. Los Angeles and San Diego fertility clinic clusters specialize in gestational carrier matching for cross-border clients from restrictive European jurisdictions.
Ukraine
Cost-sensitive intended parents from Germany and France arbitrage Ukraine's unregulated commercial framework against domestic prohibitions on compensated arrangements. The country's surrogacy infrastructure depends on stable diplomatic relations and exit documentation procedures for infant citizenship acquisition. Kyiv-based clinic networks deploy preimplantation genetic testing to attract international clients seeking reduced transfer failure rates.
Georgia
Absence of specific statutory prohibition enables practice without regulatory guidance, creating interpretive uncertainty that European cross-border traffic accepts in exchange for pricing advantages. Tbilisi reproductive health centers leverage this unregulated status to capture cost-conscious clients from France and Germany. The capital's fertility clinics integrate embryo screening technologies to compete with Ukrainian providers on clinical outcomes.
Canada
Altruistic surrogacy mandates reduce total arrangement costs but extend match timelines due to smaller candidate pools of uncompensated carriers. Health Canada oversees gamete and embryo handling standards through federal regulations that parallel FDA protocols. Toronto and Vancouver agency networks specialize in navigating the extended coordination timelines that altruistic frameworks impose on LGBTQ+ couples and single parents.
Israel
Regulated commercial frameworks with explicit statutory authorization establish governmental oversight that reassures risk-averse intended parents from domestic and international cohorts. The country's national health technology assessment bodies influence reimbursement policies for fertility treatments including surrogacy-related medical costs. Tel Aviv reproductive medicine clusters serve as a regional hub for Middle Eastern intended parents seeking regulated legal pathways.
Surrogacy Market Vendor Landscape
Full-service surrogacy agencies and specialized fertility clinic networks split the market between integrated legal-medical bundling and standalone clinical service provision. The vendor base concentrates around three strategic archetypes: premium full-service coordinators, technology-enabled matching platforms, and boutique specialists in demographic niches. Dominant competitive moves include geographic expansion into unregulated destination markets and backward integration into in-house legal and escrow services.
Within the premium full-service tier, Circle Surrogacy and Growing Generations exemplify integrated coordination models that control both clinical pathways and contract drafting. ConceiveAbilities occupies a position emphasizing rigorous surrogate screening protocols and multi-state geographic coverage. These three entities represent the archetype that captures margin through bundled service control rather than fragmented provider referrals.
| Leading Market Players |
|---|
| Creative Family Connections |
| All Families Surrogacy |
| Hatch Fertility |
| American Surrogacy |
| Southern Surrogacy |
| Circle Surrogacy |
| Growing Generations |
| Family Source Consultants |
| ConceiveAbilities |
| Others |
Supply Flow & Price Mechanics
Jurisdictional concentration risk in Ukraine and Georgia determines both pricing tier spreads and supply chain shape, as geopolitical instability compresses margins in unregulated markets while statutory clarity in California sustains premium positioning.
Pricing Analysis
The customization-premium spread separates full-service bundled arrangements from self-directed navigation platforms. Three-tier pricing structure across premium, standard, and economy levels reflects legal framework enforceability, clinical integration depth, and surrogate screening rigor. Pricing pressure stems from insurance reimbursement expansion in Massachusetts, New York, and Illinois, which displaces out-of-pocket funding. Cost-sensitive intended parents exhibit highest price sensitivity, migrating to Ukrainian and Georgian clinics, while risk-averse LGBTQ+ couples in California demonstrate lowest sensitivity.
Supply Chain Analysis
Contract-manufacturing concentration among Los Angeles and San Diego fertility clinic clusters anchors gestational carrier matching capacity. Supply draws from the United States, Ukraine, and Georgia, with Tbilisi and Kyiv reproductive health centers competing on embryo screening technology integration. Raw material dependencies include donor oocyte procurement, cryopreservation media, and preimplantation genetic testing reagents. Single-source vulnerability concentrates in Ukrainian exit documentation procedures for infant citizenship acquisition. Distribution runs through full-service agency networks, subscription-based navigation platforms, and direct clinic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics are reshaping competitive positioning as subscription-based fertility navigation services displace traditional agency retainers, creating interoperability between self-directed research tools and milestone-tracking infrastructure.
For Market Incumbents: Insulate market position through backward integration into in-house legal and escrow services, capturing margin that fragmented providers forfeit. Deepen vertical control over clinical coordination and contract drafting to defend against technology-enabled matching platforms. Certification investment in preimplantation genetic testing protocols sustains differentiation against unregulated market competitors. For New Entrants and Emerging Players: Establish a beachhead in altruistic surrogacy frameworks within Canada and Australia, where uncompensated carrier pools create extended match timelines that technology can compress. Target single-parent demographics in these jurisdictions with streamlined legal profiles that accelerate contract finalization. Deploy AI-powered psychological and medical compatibility matching as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated legal-medical bundlers over standalone clinical providers. Long-term viability hinges on regulatory arbitrage sustainability across the analysis window. Acquisition target archetype: full-service agencies with captive escrow and multi-state geographic coverage. The signal to watch is pending legislative revisions in France and Germany that would domesticize previously cross-border demand.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Legal-Medical Bundling | Full-service agencies capture margin that fragmented providers forfeit through coordinated contract drafting. |
| AI-Powered Carrier Matching | Machine learning algorithms reduce match dissolution rates by analyzing psychological and medical compatibility profiles. |
| Insurance Reimbursement Expansion | Employer-sponsored fertility benefits in mandated states displace out-of-pocket funding for qualifying employees. |
| Geographic Expansion to Unregulated Markets | Clinic networks in Georgia leverage absence of statutory prohibition to capture European cross-border cost-sensitive demand. |
| Preimplantation Genetic Testing Integration | Embryo screening protocols reduce transfer failure rates and shorten overall treatment duration for international clients. |
Methodological Framework
A spread of perspectives from reproductive endocrinologists, surrogacy agency operators, legal practitioners specializing in family formation, and intended parent advocacy groups converged on the working assumptions underlying this analysis. Primary interviews with clinic network executives and cross-border reproductive tourism facilitators combined with secondary validation from FDA guidance documents, state-level statutory compilations, EMA fertility treatment assessments, and Health Canada regulatory filings. Bottom-up enumeration of clinic capacity and top-down demand calibration from demographic trend analysis were triangulated to establish volume baselines.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include surrogacy type, intended parent demographic, legal framework classification, and payment structure mechanism. CAGRs were derived from scenario-weighted growth trajectory analysis incorporating fertility benefit expansion rates and cross-border patient flow elasticity. Industry-specific forecast inputs encompassed reproductive endocrinologist supply constraints and pending legislative revision timelines in restrictive European jurisdictions.
Stress conditions across geopolitical stability in Ukraine, insurance mandate adoption rates in U.S. states, and gamete quality limitations from advanced maternal age were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory continuity and clinical technology diffusion rates. Quarterly review of legislative committee activity in France and Germany, employer fertility benefit announcements, and Ukrainian consular processing capacity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
US Contraceptive Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
Contraceptives Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Vaginal Exam Specula Market