
 Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market | 2026-2036
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market Outlook
Indian bulk drug manufacturers is repositioning toward finished dosage capabilities. Samsung Biologics anchors large-scale mammalian cell culture production in South Korea. WuXi STA leverages integrated small-molecule development across multiple Asia-Pacific sites. Asymchem Laboratories specializes in continuous flow chemistry for complex intermediates.
Pharmaceutical Contract Manufacturing Organizations provide outsourced drug substance and drug product services under formal quality agreements, encompassing chemical synthesis, bioprocessing, formulation, fill-finish, and analytical validation to GMP standards. The primary commercial purpose involves enabling originator companies to access specialized capacity without capital-intensive facility construction. Injectables command premium pricing due to aseptic processing complexity and regulatory scrutiny. Biotechnology services represent the fastest-expanding segment as monoclonal antibody and cell therapy pipelines mature. Oral Solid Dosage remains the volume backbone across generic portfolios in India and China.
CDSCO in India enforces Schedule M compliance for domestic manufacturing facilities, while China's NMPA implements data integrity requirements through revised GMP annexes. South Korea's MFDS maintains PIC/S-aligned inspection protocols that facilitate mutual recognition with European and North American regulators. Stakeholders must evaluate regulatory divergence across national pharmacopoeias when designing multi-site supply networks.
Market Dynamics
Continuous manufacturing platforms are compressing batch cycle times and reshaping capital deployment priorities across Asia-Pacific CDMOs, while India's PLI scheme for active pharmaceutical ingredients redirects local production incentives toward integrated supply chains.
Growth Catalysts
- Biologics capacity clustering:South Korea and China are aggregating mammalian cell culture infrastructure to serve monoclonal antibody pipelines. This concentration attracts originator outsourcing from mid-cap biotech firms.
- CDSCO Schedule M compliance:India's tightened domestic manufacturing standards elevate facility quality, enabling local CDMOs to qualify for regulated-market supply contracts previously reserved for Western suppliers.
- Continuous flow chemistry:Adoption of flow reactor systems for complex intermediate production reduces solvent waste and improves process control. Specialized Asia-Pacific laboratories are capturing high-margin synthetic routes.
Market Restraints
- Specialized equipment lead times:Stainless steel bioreactors and isolator lines for aseptic processing face procurement backlogs stretching eighteen to twenty-four months, constraining capacity expansion velocity.
- Single-use supply concentration:Bioprocessing films and connectors rely on a concentrated supplier base in East Asia, creating vulnerability to regional logistics disruptions or export licensing delays.
- NMPA data integrity enforcement:China's revised GMP annexes impose granular electronic record requirements that increase validation overhead for foreign-sponsored manufacturing.
Strategic Opportunities
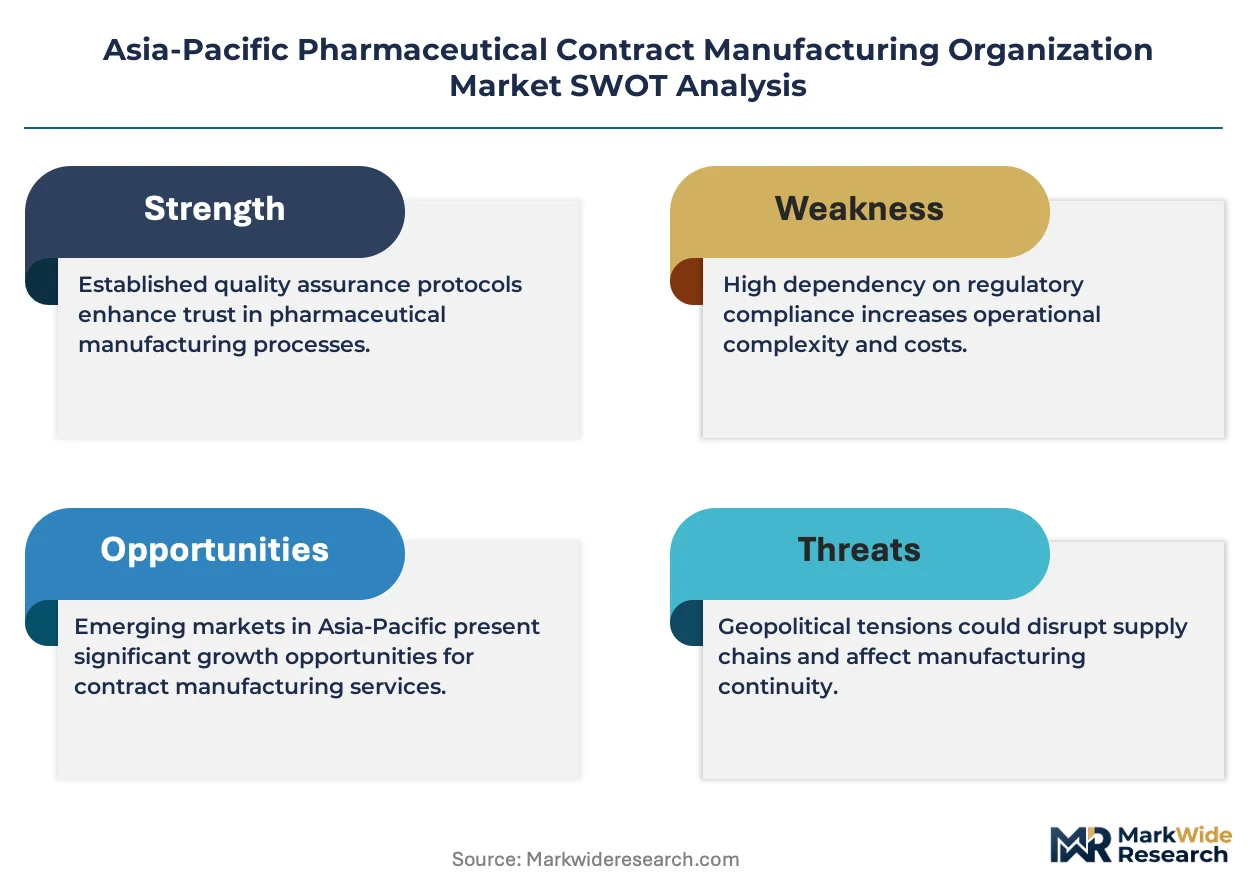
- Vietnam and Indonesia greenfield sites:Underpenetrated Southeast Asian markets offer cost-advantaged locations for oral solid dosage capacity serving domestic and regional generic demand.
- Cell therapy contract development:Viral vector production and patient-specific manufacturing workflows represent nascent service categories where first-mover CDMOs can establish proprietary platforms.
- MFDS PIC/S alignment:South Korea's mutual recognition protocols with European and North American regulators reduce duplicate inspection burdens, positioning local facilities as bridge manufacturing hubs.
Industry Challenges
- Bioprocess engineering talent scarcity:Asia-Pacific markets face acute shortages of professionals trained in scale-up cell culture and downstream purification, compressing project timelines.
- Multi-site quality system harmonization:CDMOs operating across India, China, and South Korea must reconcile divergent national pharmacopoeia requirements, complicating unified batch release protocols.
- Legacy equipment retrofit costs:Converting traditional batch facilities to continuous processing requires substantial capital redeployment and extended validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market |
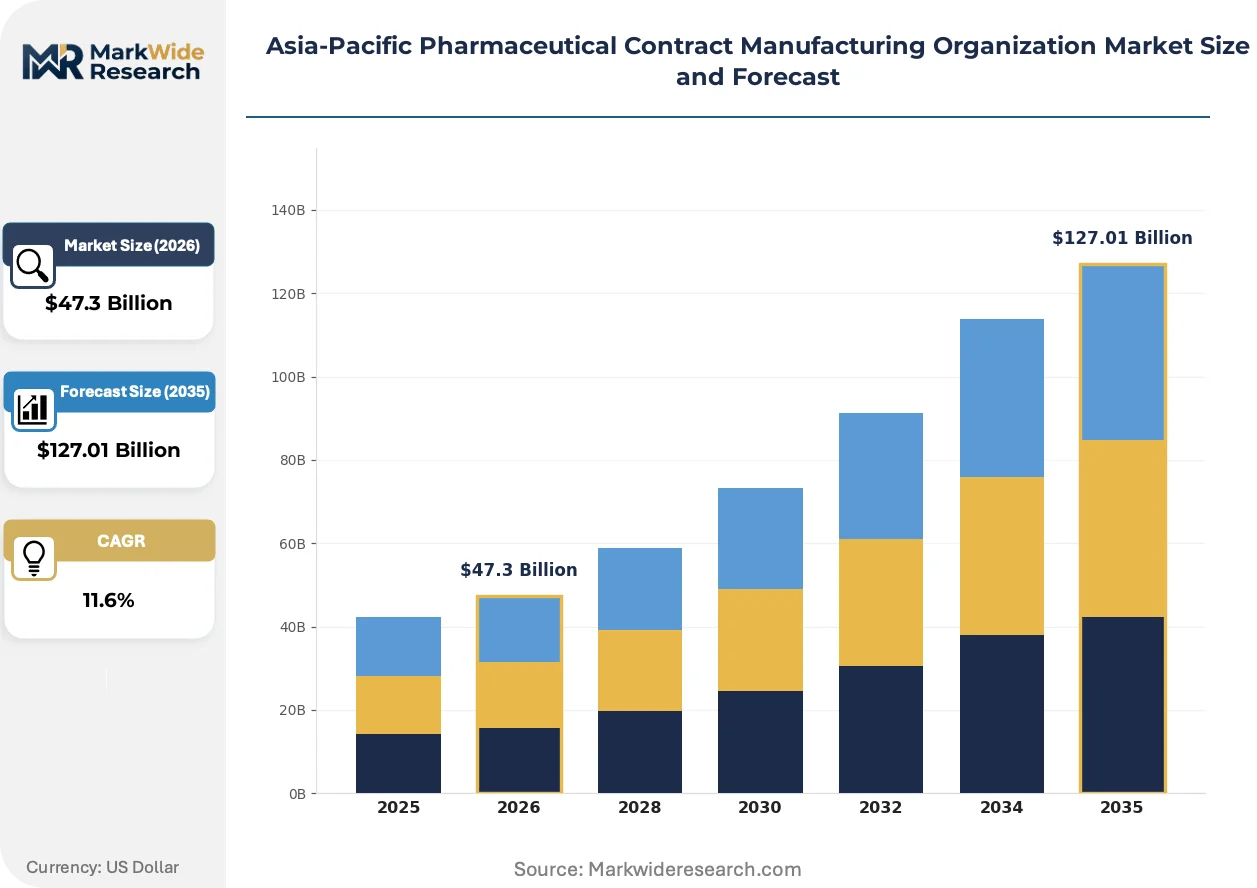
| Market Size in 2026 | $47.3 Billion |
| Market Size in 2035 | $127.01 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Oral Solid Dosage, Biotechnology, Topicals End User: Pharmaceutical Companies, Biotech Firms, Nutraceuticals, Research Institutions Service Type: Process Development, Manufacturing, Packaging, Quality Control Technology: Continuous Manufacturing, Isolators, Automation, Fluid Bed Granulation |
| Companies Covered | Boehringer Ingelheim Group, Samsung Biologics, Recipharm AB, Bushu Pharmaceuticals, Asymchem Laboratories, Jubilant Life Sciences Ltd, Pfizer CentreSource, WuXi STA, Thermo Fisher Scientific Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market Strategic Shifts
Technology convergence between small-molecule flow chemistry and large-molecule single-use bioprocessing is redefining facility design standards across Asia-Pacific pharmaceutical manufacturing services.
Single-use bioreactor systems are expanding into commercial-scale mammalian cell culture production, displacing traditional stainless steel infrastructure for multi-product facilities. Mid-cap biotech sponsors in South Korea and China are adopting these platforms to compress changeover downtime between antibody campaigns. This shift is expanding into capacity planning models that prioritize operational flexibility over nominal volume scale.
China's NMPA has implemented revised data integrity annexes requiring complete electronic batch records with audit trail functionality. This policy compresses documentation review cycles while elevating IT infrastructure requirements for domestic and foreign-sponsored sites. Injectable and biologics manufacturers face the steepest compliance adaptation costs.
Originator procurement patterns favor integrated development-to-manufacturing partnerships over transactional project contracting. Biotech sponsors in India and China are consolidating vendor relationships to reduce technology transfer friction and accelerate IND-to-NDA timelines. This concentration is most visible among venture-backed firms with compressed funding runways seeking to eliminate handoff delays between discovery chemistry and GMP supply.
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market Segmentation
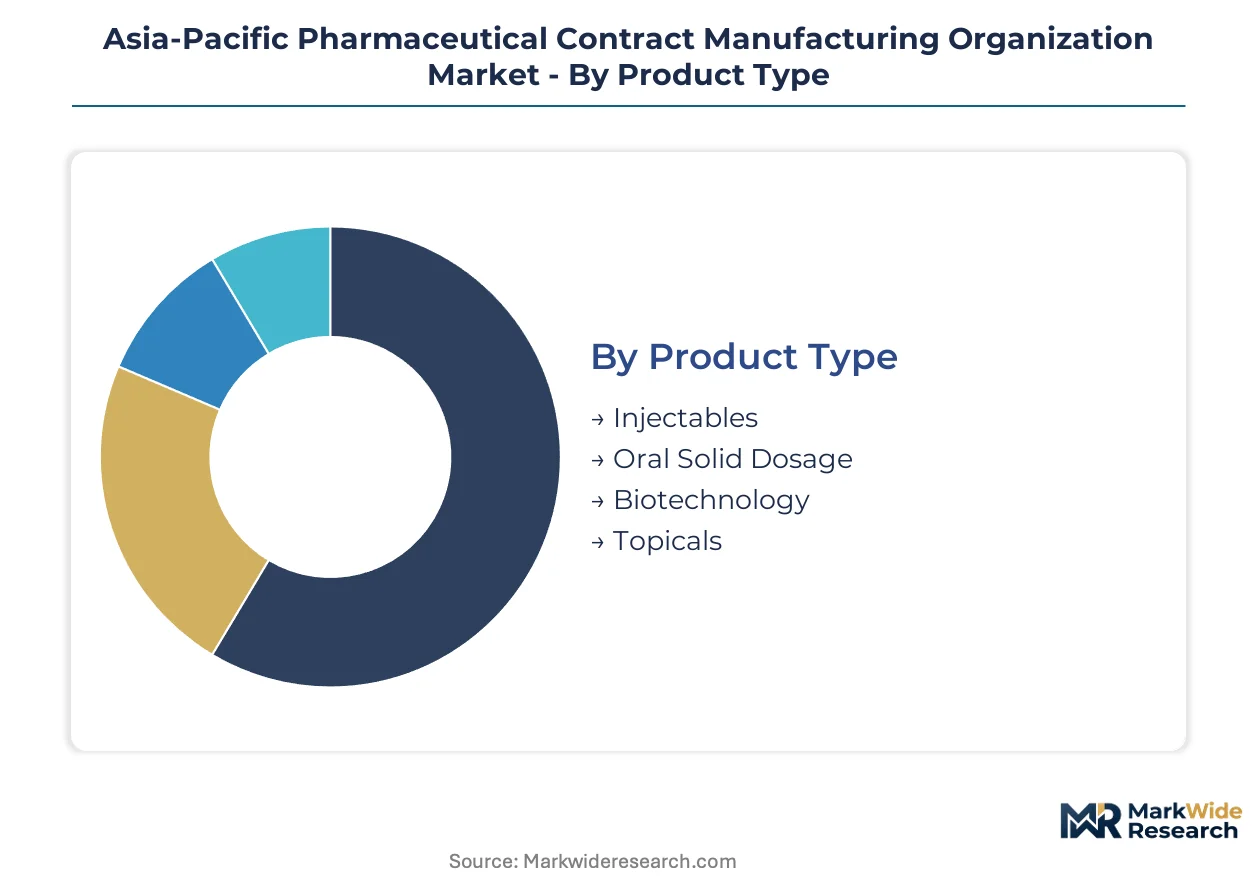
CDMO procurement decisions in Asia-Pacific increasingly hinge on matching service capabilities to specific molecule modalities and regulatory pathways. Segment-level specialization determines which providers capture high-margin biologics contracts versus commoditized generic volumes.
Product Type:
Standalone biologics manufacturing commands distinct facility investments compared to embedded small-molecule lines serving multiple oral dosage clients.
- Injectables:Aseptic fill-finish operations require isolator technology and dedicated cleanroom infrastructure. Demand concentrates in South Korea and China as local biotech sponsors advance biosimilar and novel biologic candidates toward commercialization. MFDS and NMPA inspection intensity elevates compliance costs for foreign-sponsored sites.
- Biotechnology:Mammalian cell culture and microbial fermentation platforms serve monoclonal antibody and recombinant protein production. Samsung Biologics anchors large-scale capacity in Songdo, while WuXi Biologics expands multi-modal bioprocessing across Shanghai and Wuxi sites. CDMOs with single-use bioreactor flexibility capture mid-cap sponsor campaigns with compressed development timelines.
- Oral Solid Dosage:High-volume tablet and capsule manufacturing dominates Indian and Chinese generic supply to regulated and emerging markets.
- Topicals:Semi-solid and transdermal formulations require specialized content uniformity and release testing protocols.
Oral Solid Dosage leads volumes today; Biotechnology is gaining share fastest.
End User:
Customer type dictates contract structure, with large pharma favoring multi-year capacity reservations and biotech startups preferring milestone-based development partnerships.
- Pharmaceutical Companies:Established originators and generics manufacturers outsource to de-risk capital deployment and access regional cost advantages. Indian facilities serve European and North American markets under mutual recognition agreements; Chinese sites increasingly supply domestic innovation pipelines under NMPA oversight.
- Biotech Firms:Venture-backed sponsors with limited manufacturing infrastructure drive demand for integrated development-to-commercial services. South Korean CDMOs capture regional antibody campaigns through proximity to Seoul and Pangyo biotech clusters.
- Nutraceuticals:Dietary supplement and functional food manufacturers seek GMP-adjacent production for export qualification.
- Research Institutions:Academic and government laboratories require small-batch GMP manufacturing for early-phase clinical material.
Pharmaceutical Companies anchor contract value today; Biotech Firms are expanding their share of development-stage engagements most rapidly.
Service Type:
Margin profiles diverge sharply between front-end process development and back-end commercial manufacturing.
- Manufacturing:Commercial-scale production of drug substance and drug product generates recurring revenue under multi-year supply agreements. Indian API manufacturers are repositioning toward finished dosage capabilities to capture higher value per kilogram of active ingredient. CDSCO Schedule M compliance investments enable participation in regulated-market contracts.
- Process Development:Route scouting, scale-up, and tech transfer services command premium pricing for complex synthetic and bioprocess challenges. Asymchem Laboratories and WuXi STA compete on continuous flow chemistry expertise for high-potency intermediates.
- Quality Control:Analytical method development, validation, and release testing support batch disposition across all product categories.
- Packaging:Secondary packaging, serialization, and cold-chain distribution complete the commercial supply chain.
Manufacturing dominates revenue today; Process Development carries the steepest expansion trajectory as sponsors seek earlier CDMO engagement.
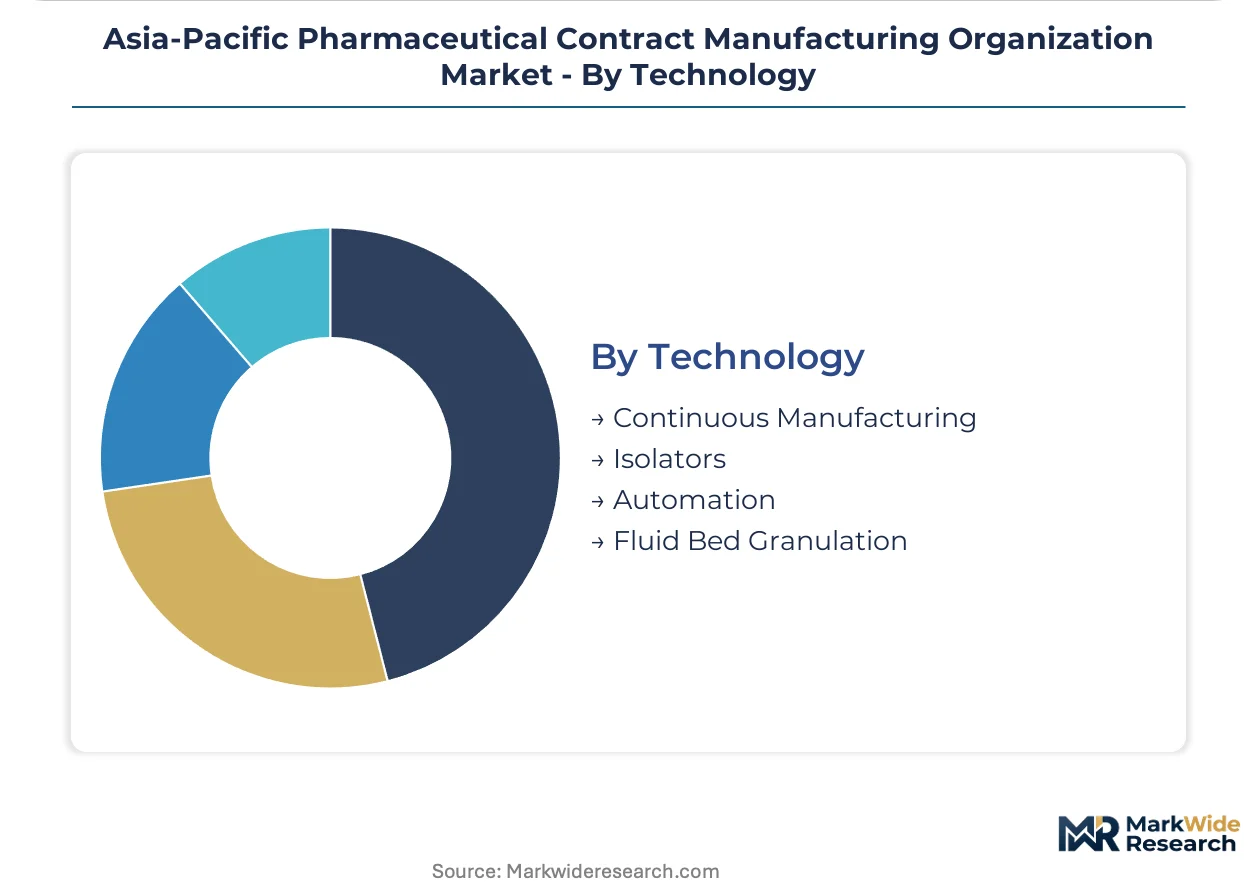
Technology:
Capital deployment priorities separate continuous processing adopters from batch-legacy facilities facing retrofit decisions.
- Continuous Manufacturing:Flow reactor systems and integrated direct compression lines reduce batch cycle times and improve quality consistency. Adoption concentrates in synthetic chemistry and solid dosage applications where process analytical technology enables real-time release. CDMOs with proven continuous platforms differentiate on speed-to-IND for small-molecule candidates.
- Isolators:Closed containment systems for potent compound handling and aseptic processing protect operators and products. Demand is climbing fastest in antibody-drug conjugate and high-potency API manufacturing where occupational exposure limits drive engineering controls.
- Automation:Robotic aseptic processing and automated guided vehicles reduce human intervention in critical manufacturing zones.
- Fluid Bed Granulation:Batch and continuous fluid bed systems remain standard for oral solid dosage particle engineering.
Fluid Bed Granulation retains installed base dominance today; Continuous Manufacturing is climbing the fastest among technology investment priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration across the Asia-Pacific region tracks divergent compliance costs and incentive structures. CDMOs relocate capacity toward jurisdictions where regulatory burden and capital subsidies optimize total cost of quality.
China
Domestic biotech sponsors drive demand for mammalian cell culture capacity in Shanghai and Suzhou industrial parks. NMPA data integrity annexes impose granular electronic record requirements that elevate IT infrastructure investments for foreign-sponsored sites. WuXi Biologics anchors multi-modal bioprocessing across Wuxi facilities serving regional antibody pipelines.
India
API manufacturers reposition toward finished dosage capabilities to capture higher value per kilogram of active ingredient. CDSCO Schedule M compliance investments enable local CDMOs to qualify for regulated-market supply contracts previously reserved for Western suppliers. Hyderabad and Ahmedabad clusters concentrate oral solid dosage capacity serving European and North American generic markets.
South Korea
Mid-cap biotech firms with compressed funding runways seek integrated development-to-manufacturing partnerships to eliminate handoff delays. MFDS maintains PIC/S-aligned inspection protocols that facilitate mutual recognition with European and North American regulators. Samsung Biologics anchors large-scale mammalian cell culture production in Songdo, attracting regional antibody campaigns through proximity to Seoul biotech clusters.
Japan
Originator companies outsource specialized bioprocessing to access regional cost advantages while maintaining PMDA quality standards. The country's national pharmaceutical regulator enforces GMP requirements that align with ICH guidelines, enabling streamlined batch release for export markets. Osaka and Tokyo metropolitan areas concentrate formulation and fill-finish capacity serving domestic innovation pipelines.
Vietnam
Underpenetrated Southeast Asian markets offer cost-advantaged locations for oral solid dosage capacity serving domestic and regional generic demand. The country's national pharmaceutical regulator is strengthening GMP enforcement to align with ASEAN harmonization initiatives. Ho Chi Minh City industrial zones attract greenfield investments from Indian and Chinese CDMOs seeking labor cost arbitrage.
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market Competitive Environment
Chinese producers anchor one tier; Indian specialists hold another in the Asia-Pacific CDMO structure. The vendor base separates into consolidated large-scale biologics operators, mid-cap integrated development-to-manufacturing providers, and commodity-focused generic dosage form specialists. Strategic archetypes include technology-differentiated flow chemistry laboratories, single-use bioprocessing adopters, and backward-integrated API-to-dosage manufacturers. Capacity expansion and portfolio diversification toward higher-margin biologics services represent dominant competitive moves.
Within the large-scale biologics tier, Samsung Biologics exemplifies mammalian cell culture infrastructure concentration. Among integrated development-to-manufacturing providers, WuXi STA and Asymchem Laboratories occupy positions spanning small-molecule process development and GMP supply. These entities represent archetypes of technology convergence between synthetic chemistry expertise and regulatory-compliant manufacturing scale.
| Leading Market Players |
|---|
| Boehringer Ingelheim Group |
| Samsung Biologics |
| Recipharm AB |
| Bushu Pharmaceuticals |
| Asymchem Laboratories |
| Jubilant Life Sciences Ltd |
| Pfizer CentreSource |
| WuXi STA |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
Stainless steel bioreactor procurement costs cascade through Asia-Pacific CDMO pricing tiers, with eighteen-to-twenty-four-month equipment lead times compressing margins for mammalian cell culture campaigns while amplifying premium capture for facilities with installed isolator capacity.
Pricing Analysis
Distributor margins for single-use bioprocessing consumables absorb significant downstream markup before reaching sponsor procurement teams. Project-based contracting dominates development-stage engagements, while multi-year capacity reservations anchor commercial manufacturing relationships. Price differentiation rests on MFDS and NMPA inspection history, with PIC/S-aligned facilities commanding tiered premiums over domestic-standard competitors. Cost compression in oral solid dosage runs through Indian and Chinese generic supply, where CDSCO Schedule M compliance investments are reshaping competitive positioning. Biotech sponsors with compressed funding runways exhibit highest price sensitivity; large pharma originators prioritize quality assurance over unit cost.
Supply Chain Analysis
Bioprocess engineering talent scarcity in South Korea and China constrains expansion velocity for mammalian cell culture capacity. Raw material dependencies center on East Asian suppliers for bioprocessing films, connectors, and chromatography resins. Single-source vulnerability in single-use component supply creates exposure to regional logistics disruptions or export licensing delays. Distribution runs through integrated development-to-manufacturing partnerships that eliminate handoff friction between discovery chemistry and GMP supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific pharmaceutical contract manufacturing has entered a late-cycle quality phase where CDSCO Schedule M compliance and NMPA data integrity enforcement are filtering commoditized providers from premium-positioned competitors.
For Market Incumbents: Extend continuous manufacturing platform investments to defend against emerging flow chemistry specialists capturing high-margin synthetic routes. Anchor capacity expansion in Songdo and Shanghai biotech clusters where mammalian cell culture demand concentrates. Prioritize MFDS PIC/S alignment investments to qualify for European and North American mutual recognition contracts.
For New Entrants and Emerging Players: Mid-cap biotech sponsors with compressed IND-to-NDA timelines represent the most penetrable buyer archetype in Vietnam and Indonesia greenfield markets. Capture oral solid dosage demand serving regional generic markets through cost-advantaged Ho Chi Minh City industrial zones. Lead with integrated analytical validation capabilities to differentiate from transactional API suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where bioprocess engineering talent scarcity intersects with legacy equipment retrofit requirements. Five-to-ten-year viability favors CDMOs with proven single-use bioreactor flexibility and continuous flow chemistry expertise. Monitor NMPA enforcement intensity as inflection signal for foreign-sponsored site compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Platform Deployment | Flow reactor adoption reduces solvent waste while accelerating IND timelines for small-molecule sponsors. |
| Single-Use Bioreactor Scale-Up | Commercial-scale mammalian cell culture flexibility captures mid-cap antibody campaigns with compressed timelines. |
| MFDS PIC/S Alignment Investment | Mutual recognition protocols reduce duplicate inspection burdens for bridge manufacturing hub positioning. |
| API-to-Dosage Integration | Backward integration into finished dosage capabilities elevates value per kilogram for Indian manufacturers. |
| Cell Therapy Viral Vector Capacity | Patient-specific manufacturing workflows represent nascent service categories with first-mover platform potential. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CDSCO regulatory affairs leads, MFDS inspection coordinators, biotech sponsor procurement directors, and mammalian cell culture facility operators with secondary validation against NMPA GMP annex revisions, CDSCO Schedule M compliance databases, ClinicalTrials.gov antibody pipeline filings, and Asia-Pacific customs trade data. Bottom-up facility capacity assessments and top-down sponsor outsourcing spend estimates were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baseline through post-regulatory-revision intervals informed projection anchor points across the analysis window. Segmentation modeling incorporated product type, service tier, technology platform, and regional regulatory cluster dimensions. CAGRs were derived from sponsor pipeline maturation curves and capacity expansion announcements. Forecast inputs included monoclonal antibody IND filing trajectories and PLI scheme incentive disbursement patterns.
Underlying measurement precision varies by segment; biologics capacity and continuous manufacturing adoption carry tighter precision than emerging cell therapy categories. Forecasts reflect assumptions regarding regulatory enforcement continuity and sponsor outsourcing preference stability. Material deviation in NMPA data integrity audit intensity or single-use supply chain disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
RNA-Targeted Small Molecules Market