
 Air Filters Market | 2026-2036
Air Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Air Filters Market Intelligence
The fragmented aftermarket distributor channel for HVAC systems is narrowing due to consolidation and the rise of e-commerce platforms. Camfil leverages its specialized focus on clean air solutions to command premium positioning in industrial applications. Donaldson Company sustains its market presence through a broad portfolio covering both engine and industrial filtration. This competitive dynamic pressures smaller, regional suppliers.
Air filters are devices composed of fibrous or porous materials that remove solid particulates, such as dust, pollen, mold, and bacteria, from the air. Their performance is often rated using standards like MERV, which quantifies the filter's ability to capture particles of specific sizes. HEPA filters command the highest value within the filter type segmentation due to their use in critical cleanroom and pharmaceutical applications. Demand from data centers represents a fast-growing application, requiring specialized filtration to protect sensitive electronics.
Regulatory frameworks from the US EPA and China's MEE governing industrial emissions directly mandate the use of high-efficiency filtration. In Europe, standards like the F-Gas Regulation indirectly influence HVAC system design and associated filter requirements to improve energy efficiency. Future market development will hinge on creating filters that achieve higher particle capture efficiency without increasing energy consumption in HVAC systems.
Market Dynamics
The central dynamic shaping the air filter market is the technical and economic tension between achieving higher particle capture efficiency and minimizing the associated energy penalty. Stricter air quality regulations and cleanroom standards demand finer filtration, which inherently increases airflow resistance and drives up HVAC energy consumption.
Growth Catalysts
- Regulatory Mandates:China's MEE regulations on industrial emissions and particulate matter directly compel factories and power plants to install and upgrade high-efficiency air filtration systems, creating a large, compliance-driven market segment.
- Pharmaceutical Manufacturing:The expansion of sterile drug production requires adherence to stringent cleanroom classifications, such as those defined by ISO 14644, propelling demand for certified HEPA and ULPA filters to prevent contamination.
- Standardization Adoption:The broader adoption of the ISO 29463 testing standard provides a globally recognized framework for filter performance, enabling buyers to specify and verify high-efficiency products and encouraging manufacturers to upgrade their offerings.
Market Restraints
- Input Material Volatility:The cost and availability of key raw materials for filter media, such as synthetic polymers and specialized glass fibers, are subject to fluctuations in global commodity markets, creating margin pressure for manufacturers.
- Energy Consumption Trade-Off:A fundamental physical restraint is that higher-efficiency filters (with higher MERV or HEPA ratings) create a greater pressure drop, forcing HVAC systems to work harder and consume more energy, a significant drawback for cost-sensitive end-users.
- Alternative Technology Competition:Non-filter-based air purification technologies, including ultraviolet germicidal irradiation (UV-C) and photocatalytic oxidation (PCO), compete for budget allocation in certain applications, particularly for controlling airborne pathogens and VOCs.
Strategic Opportunities
- Data Center Filtration:The rapid build-out of data centers presents a significant opportunity for specialized filters designed to protect sensitive servers from airborne contaminants and corrosive gases, which can cause equipment failure.
- Smart Filter Systems:Integrating IoT sensors into filters to monitor particulate loading and pressure drop in real-time enables a shift to condition-based maintenance, creating new service revenue streams and improving system efficiency.
- Southeast Asia Industrialization:Industrializing economies in Southeast Asia are experiencing worsening air pollution, opening opportunities for filter manufacturers to supply solutions for industrial emissions control and improved indoor air quality in commercial buildings.
Industry Challenges
- Navigating Global Standards:Manufacturers face the operational complexity and cost of designing and certifying products to meet disparate regional standards, such as EPA requirements in the US and CE marking directives in Europe.
- End-User Education on TCO:A persistent challenge is communicating the total cost of ownership (TCO) to customers, who may opt for lower-priced, less efficient filters without understanding the long-term impact on higher energy bills and maintenance costs.
- Aftermarket Channel Consolidation:Ongoing consolidation among HVAC parts distributors and the rise of large e-commerce platforms create challenges for smaller filter manufacturers seeking to secure market access and maintain brand visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Filters Market |
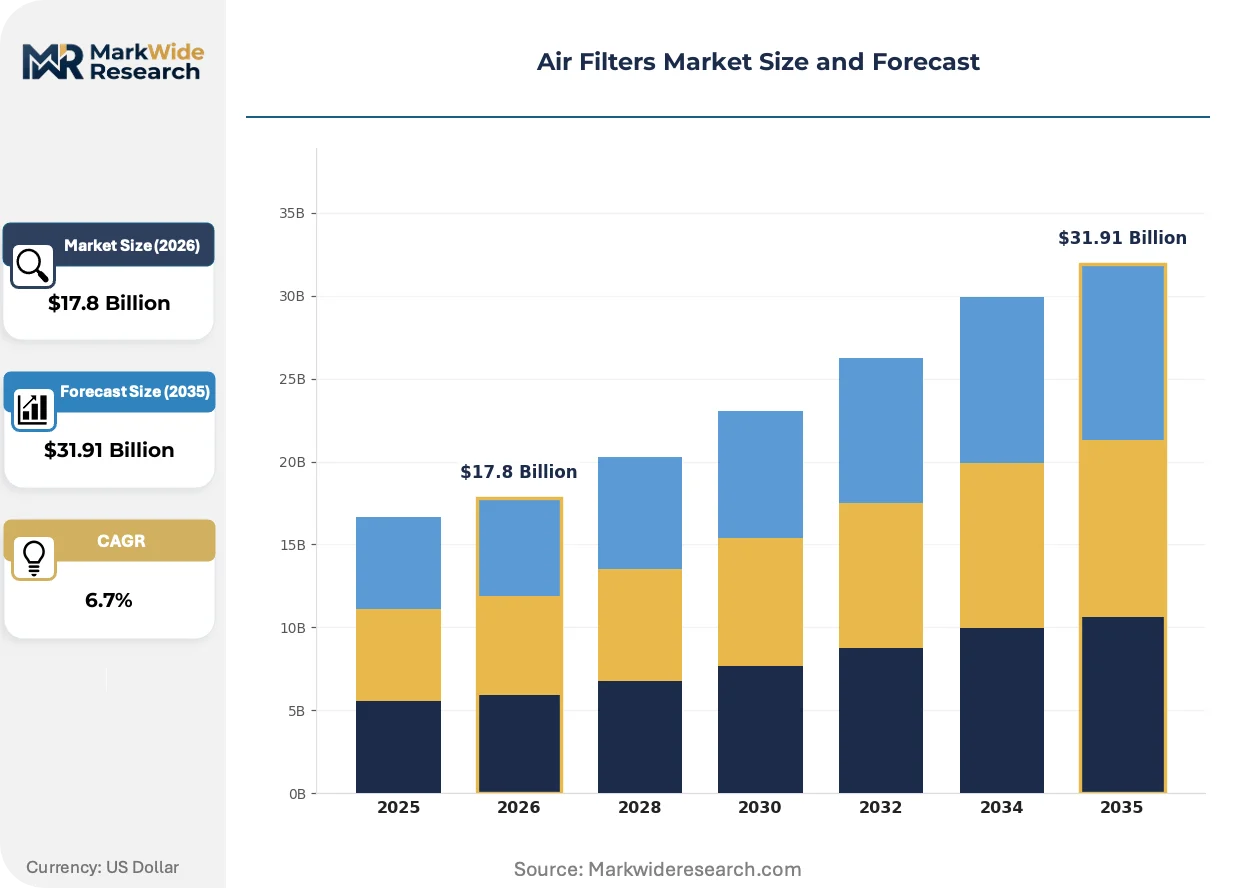
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.91 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: HEPA, Carbon, Electrostatic, UV, Panel, Pleated Application: HVAC Systems, Cleanrooms, Data Centers, Laboratories, Commercial Buildings, Transportation End User: Manufacturing Plants, Pharmaceutical Facilities, Research Institutes, Server Farms, Educational Facilities, Offices Technology: Mechanical, Electronic, Hybrid, Photocatalytic, Activated Carbon, Ionic |
| Companies Covered | Donaldson Company, Mann+Hummel, AAF International, Daikin Industries, Rensa Filtration, Honeywell International, 3M Company, Parker-Hannifin Corporation, Camfil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Filters Market Strategic Shifts & Innovations
Product development is pivoting from passive filtration media to intelligent, integrated systems that actively manage air quality and energy use. This evolution reflects a broader demand-side shift toward performance-based outcomes rather than simple component procurement. Filters are increasingly viewed as critical assets for operational efficiency and health compliance.
Advanced media using nanofiber coatings provide superior particle capture at a finer level than traditional meltblown fibers. Industrial and healthcare facilities are adopting these materials to meet stringent air purity requirements without incurring prohibitive energy costs. This technology is collapsing the long-standing compromise between high filtration efficiency and low airflow resistance, enabling new performance benchmarks.
Europe's F-Gas Regulation, while targeting refrigerants, has a significant ripple effect on the air filter market. The regulation incentivizes holistic HVAC system upgrades to improve energy efficiency, compelling building owners to consider the energy impact of all components. Consequently, commercial HVAC specifiers are increasingly selecting filters with certified low-pressure-drop characteristics to contribute to overall system compliance.
A notable change in purchasing behavior is the move from time-based to condition-based filter replacement cycles. This trend disrupts the traditional, schedule-driven aftermarket sales model and favors suppliers offering integrated monitoring solutions with sensors. The shift is most apparent in critical environments like data centers and hospitals in North America, where optimizing both air quality and energy expenditure is paramount.
Air Filters Market Segmentation
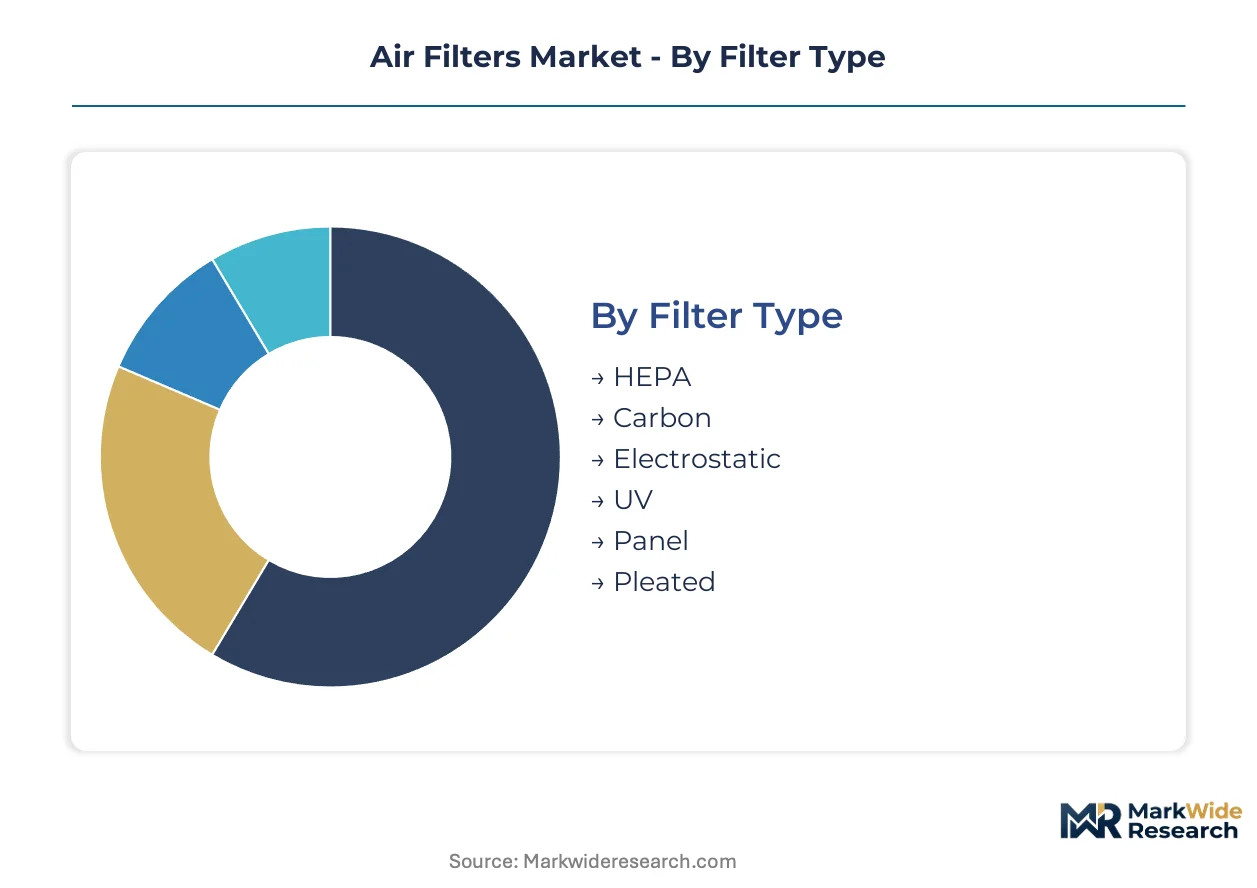
The air filters market is highly diversified, with segmentation critical for understanding specific demand drivers and technological advancements. Different filter types, applications, end-users, and underlying technologies each present unique performance requirements and market dynamics. This granular view clarifies where value accumulates and innovation focuses.
Filter Type:
The service intensity required for filter replacement and maintenance varies significantly across filter types, influencing procurement patterns and aftermarket revenue streams.
- HEPA:High-efficiency particulate air filters capture 99.97% of particles 0.3 microns in size, essential for maintaining sterile environments. Demand concentrates in pharmaceutical facilities and cleanrooms due to stringent contamination control needs.
- Pleated:These filters use a folded media design to increase surface area, offering a balance of efficiency and airflow. Commercial HVAC systems widely adopt pleated filters for general air quality, balancing cost-effectiveness with performance.
- Carbon:Activated carbon filters remove gaseous contaminants and odors through adsorption.
- Electrostatic:Electrostatic filters use an electrical charge to attract and capture airborne particles.
- UV:Ultraviolet filters employ UV-C light to inactivate airborne microorganisms and pathogens.
- Panel:Basic panel filters serve as pre-filters, capturing larger particles to extend the life of finer filters.
HEPA filters hold the largest value share; momentum sits with advanced pleated designs offering lower pressure drop.
Application:
Application segments demonstrate distinct volume concentrations, with some representing foundational demand and others emerging as specialized, high-growth niches.
- HVAC Systems:Heating, ventilation, and air conditioning systems are the largest application area, requiring filters to maintain indoor air quality and protect equipment. Energy efficiency regulations in Europe are driving demand for low-pressure-drop filters in these systems.
- Data Centers:These facilities deploy specialized filters to protect sensitive electronics from particulate matter and corrosive gases. The rapid build-out of data centers globally represents a fast-growing application.
- Cleanrooms:Cleanroom applications demand ultra-high-efficiency filters for controlled environments.
- Commercial Buildings:Filters in commercial buildings focus on occupant comfort and general air hygiene.
- Laboratories:Laboratories require precise air filtration to prevent cross-contamination and protect experiments.
- Transportation:Filters in transportation protect engine components and cabin occupants from airborne pollutants.
HVAC Systems represent the largest volume segment, while Data Centers are expanding most quickly.
End User:
Understanding end-user segments reveals diverse purchasing behaviors and regulatory compliance pressures that shape filter specifications and market demand.
- Pharmaceutical Facilities:These facilities mandate extremely high-efficiency filters to meet ISO 14644 cleanroom standards for sterile manufacturing. Strict regulatory oversight ensures consistent demand for certified HEPA and ULPA filters.
- Manufacturing Plants:Industrial manufacturing plants use filters for emissions control and process protection, driven by regulations like China's MEE mandates. Heavy industry requires robust filtration solutions to manage particulate output.
- Server Farms:Server farms prioritize filters that protect delicate IT equipment from dust and corrosive elements.
- Educational Facilities:Educational facilities focus on improving indoor air quality for student and staff well-being.
- Research Institutes:Research institutes require specialized filtration for sensitive experiments and controlled environments.
- Offices:Office environments use filters primarily for general comfort and air purification.
Pharmaceutical Facilities drive premium demand, while Manufacturing Plants face significant regulatory pressure.
Technology:
Technological advancements are a central theme, with innovation focusing on improving capture efficiency while simultaneously reducing energy consumption.
- Mechanical:These filters physically block particles using fibrous media, constituting the most traditional and widely adopted technology. Continuous material science improvements enhance mechanical filtration performance.
- Activated Carbon:Activated carbon technology adsorbs gaseous pollutants and volatile organic compounds (VOCs) onto its porous surface. This technology is critical for odor control and chemical purification.
- Electronic:Electronic filters use electrostatic principles to charge and collect particles from the air stream.
- Hybrid:Hybrid filters combine multiple filtration principles to achieve enhanced performance across various contaminant types.
- Photocatalytic:Photocatalytic oxidation (PCO) technology uses UV light and a catalyst to break down airborne contaminants.
- Ionic:Ionic filters generate ions to charge particles, causing them to clump together or adhere to surfaces.
Mechanical filtration remains foundational, but hybrid and photocatalytic technologies are gaining innovation focus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE regulations drive significant demand for air filtration systems, anchoring market growth in the Asia-Pacific region. Regulatory frameworks across Europe and North America also shape regional market dynamics, compelling industries and commercial sectors to adopt advanced filtration solutions. This global regulatory push ensures sustained market expansion for air filter manufacturers.
China
Industrial emissions control and public health initiatives are primary demand drivers in China. The MEE regulations directly mandate high-efficiency air filtration systems for factories and power plants. Major industrial zones, such as the Yangtze River Delta, are experiencing substantial upgrades in their air purification infrastructure.
United States
Data centers and pharmaceutical facilities generate robust demand for specialized air filters in the United States. US EPA regulations on industrial emissions and indoor air quality influence filter specifications across various sectors. California's stringent environmental standards further accelerate the adoption of advanced filtration technologies in commercial buildings.
Germany
Demand for energy-efficient HVAC systems and cleanroom applications is pronounced in Germany. The EU F-Gas Regulation indirectly influences HVAC system design, promoting filters with lower pressure drop characteristics. Bavaria's advanced manufacturing sector specifically requires high-performance filters for precision processes and controlled environments.
India
Manufacturing plant expansion and increasing concerns over urban air pollution fuel filter demand in India. The country's national environmental policies are gradually tightening, requiring industries to manage particulate emissions more effectively. Industrial corridors in Gujarat are installing new filtration units to comply with evolving environmental standards.
Vietnam
Industrialization and rapid urbanization are creating new demand for air filters in Vietnam. The National Environmental Protection Law encourages businesses to invest in air quality management solutions. Manufacturing hubs around Ho Chi Minh City are expanding, necessitating filtration systems for both process protection and worker safety.
Air Filters Market Key Industry Players
Specialized premium providers and broad-portfolio industrial suppliers split the market for air filtration solutions. The aftermarket distribution channel is experiencing consolidation, while e-commerce platforms gain prominence. Companies often pursue strategic partnerships and portfolio diversification to maintain their market positions.
Within the broad-portfolio industrial supplier archetype, Donaldson Company maintains a significant presence through its extensive product range covering engine and industrial filtration. Camfil exemplifies specialized premium providers, focusing on clean air solutions for critical applications. Mann+Hummel represents another large-scale player, offering a wide array of filtration products across various end-user segments.
| Leading Market Players |
|---|
| Donaldson Company |
| Mann+Hummel |
| AAF International |
| Daikin Industries |
| Rensa Filtration |
| Honeywell International |
| 3M Company |
| Parker-Hannifin Corporation |
| Camfil |
| Others |
Cost & Logistics Intelligence
Volatility in specialized glass fibers and synthetic polymers, critical raw materials for filter media, directly compresses manufacturer margins and influences pricing throughout the air filter value chain. This upstream cost pressure often transfers to end-user segments.
Pricing Analysis
Pricing for air filters exhibits a notable geographic spread, with premium HEPA filters in Western markets commanding higher values than standard pleated filters in emerging economies. The dominant pricing structure is per-unit transactional, often integrated into service contracts for HVAC systems. Certification levels, such as ISO 29463, and specialized after-sales support drive significant price differentiation. Commercial HVAC and residential end-users are most price-sensitive, whereas pharmaceutical facilities prioritize certified performance, leading to higher price tolerance.
Supply Chain Analysis
Restricted technology controls, particularly concerning advanced nanofiber coatings, could limit the global flow of high-performance filtration media. Raw material production for filter media concentrates in China, the United States, and specific European regions; the industry relies heavily on synthetic polymers, specialized glass fibers, and activated carbon. Commodity price volatility for these key inputs presents a significant supply chain risk, impacting manufacturing costs. Downstream distribution runs through a fragmented network of HVAC parts distributors and growing e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air filter market is undergoing a buyer-power shift, driven by ongoing consolidation among HVAC parts distributors. This shift alters procurement dynamics for manufacturers and redefines market access strategies.
For Market Incumbents: Harden supply chain resilience by securing long-term contracts for specialized glass fibers and synthetic polymers. Incumbents should invest in advanced nanofiber media R&D to counter the energy consumption trade-off. Acquiring specialized filter media producers can gain upstream control and mitigate input material volatility. This strategy defends against commoditization and competition from alternative purification technologies.
For New Entrants and Emerging Players: Build out niche capabilities in specialized data center filtration solutions, addressing sensitive electronics protection. Target the rapidly expanding data center application segment, particularly in North America. Focus on industrializing Southeast Asian economies for emissions control and improved indoor air quality. Offer integrated smart filter systems with IoT sensors as a differentiated go-to-market angle, providing condition-based maintenance benefits.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional distributors seeking market consolidation. The air filter market offers stable, long-term returns over the next decade due to persistent regulatory tailwinds and public health concerns. Acquisition targets include specialized filter media manufacturers with proprietary advanced media technology. A signal to watch is increased M&A activity among smaller, innovative technology providers as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Media | Increases production of nanofiber filters to meet stringent cleanroom standards. |
| IoT Integration for Smart Filters | Enables real-time monitoring of filter performance and predictive maintenance for HVAC systems. |
| Strategic Partnerships with HVAC OEMs | Ensures early integration of high-efficiency filters into new energy-efficient HVAC designs. |
| Acquisition of Regional Distributors | Strengthens aftermarket channel control and expands market access in fragmented geographies. |
| Certification to ISO 29463 Standards | Validates filter performance for global markets, especially in pharmaceutical applications. |
Research Approach
Cross-validation between primary interviews and secondary market reports anchors the qualitative findings of this study. Interviews were conducted with plant managers, R&D directors, procurement leads, and HVAC system integrators. Secondary data sources included SEC 10-K filings, US EPA regulatory documents, ISO standards publications, and industry trade association reports. Bottom-up and top-down triangulation ensured data consistency.
Calibration of historical market trends against current industry shifts formed the basis for future projections across the analysis window. The analytical framework modeled market dynamics by filter type, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from regression analysis of historical data and future demand drivers. Key forecast inputs included industrialization rates and cleanroom expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major industrial suppliers or new technology entrants would shift outcomes. Rapid shifts in global trade policies or breakthroughs in alternative purification technologies could revise projections. Continuous validation against operating reality remains the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Actuators Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market