
 South America Fans and Blowers Market | 2026-2036
South America Fans and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fans and Blowers Market Analytics
Buyer concentration among large-scale mining and HVAC contractors is hardening across the Andean ridge and Brazil's industrial corridor. Howden Group Ltd anchors its position through deep specialization in heavy-duty centrifugal systems for underground ventilation. Greenheck Fan Corp leverages broad manufacturing scale to compete across commercial and institutional HVAC channels. Ebm-Papst Group differentiates through precision motor technology leadership in energy-efficient axial fan architectures.
Fans and blowers are electromechanical devices engineered to generate airflow through rotational impeller action, with performance calibrated by parameters including static pressure, volumetric flow rate measured in cubic meters per second, and mechanical efficiency ratings. These systems serve essential functions across industrial ventilation, climate control, combustion air supply, and process cooling applications where controlled gas movement determines operational safety and energy consumption. Centrifugal fans capture the dominant share of industrial procurement budgets due to their pressure-generation advantages in ducted mining and manufacturing environments. Axial fans occupy faster-growing niches in HVAC retrofit markets where space constraints and energy efficiency targets favor compact inline configurations. Electric technology dominates installed capacity, though hybrid and solar alternatives are gaining traction in remote operations beyond grid reach.
Brazil's INMETRO energy labeling requirements and ANVISA industrial hygiene standards shape product certification pathways and filter performance mandates across the region. Argentina's IRAM safety standards and Chile's SEC electrical certifications create layered compliance obligations for cross-border suppliers. Peru's Ministry of Energy and Mines ventilation directives for underground operations drive specification rigor in the mining segment. Stakeholders must monitor evolving efficiency tier thresholds and localized content rules as governments tighten industrial policy alignment with decarbonization commitments.
Market Dynamics
Deepening extraction depths across Chilean and Peruvian copper belts are forcing ventilation infrastructure overhauls, while Brazil's INMETRO energy labeling program compresses equipment replacement cycles in manufacturing corridors.
Growth Catalysts
- Underground mining ventilation mandates:Peru's Ministry of Energy and Mines directives for deeper extraction operations require high-pressure centrifugal systems in copper and gold operations.
- Energy efficiency labeling acceleration:Brazil's INMETRO PBE program creates regulatory pull for premium-efficiency motor-fan combinations across São Paulo's manufacturing belt.
- Industrial hygiene enforcement:ANVISA standards for airborne contaminant control drive filter-integrated blower upgrades in food processing and pharmaceutical facilities.
Market Restraints
- Copper and rare-earth magnet cost volatility:Permanent magnet price swings in neodymium supply chains compress margin predictability for high-efficiency motor manufacturers.
- Import dependency for precision bearings:Concentrated supply from European and Asian specialist producers creates lead time vulnerability for maintenance-critical mining operations.
- Grid connectivity limitations:Remote Andean and Amazon basin extraction sites face diesel-electric hybrid cost premiums that slow electrification timelines.
Strategic Opportunities
- Argentine industrial corridor penetration:IRAM certification-aligned product lines can capture pent-up demand in Córdoba and Buenos Aires manufacturing zones currently served by aging equipment.
- Solar-hybrid ventilation for off-grid mining:Photovoltaic-diesel hybrid configurations address energy access gaps in Peruvian and Chilean high-altitude extraction sites beyond transmission infrastructure.
- Retrofit channel development:Energy-as-a-service financing models bypass capital-constrained Brazilian mid-tier manufacturers seeking INMETRO tier upgrades without balance sheet impact.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous INMETRO, SEC, and IRAM compliance requirements extend product validation timelines for cross-border suppliers.
- Legacy system integration friction:Variable frequency drive retrofits on existing ductwork networks demand specialized commissioning expertise scarce in regional service channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fans and Blowers Market |
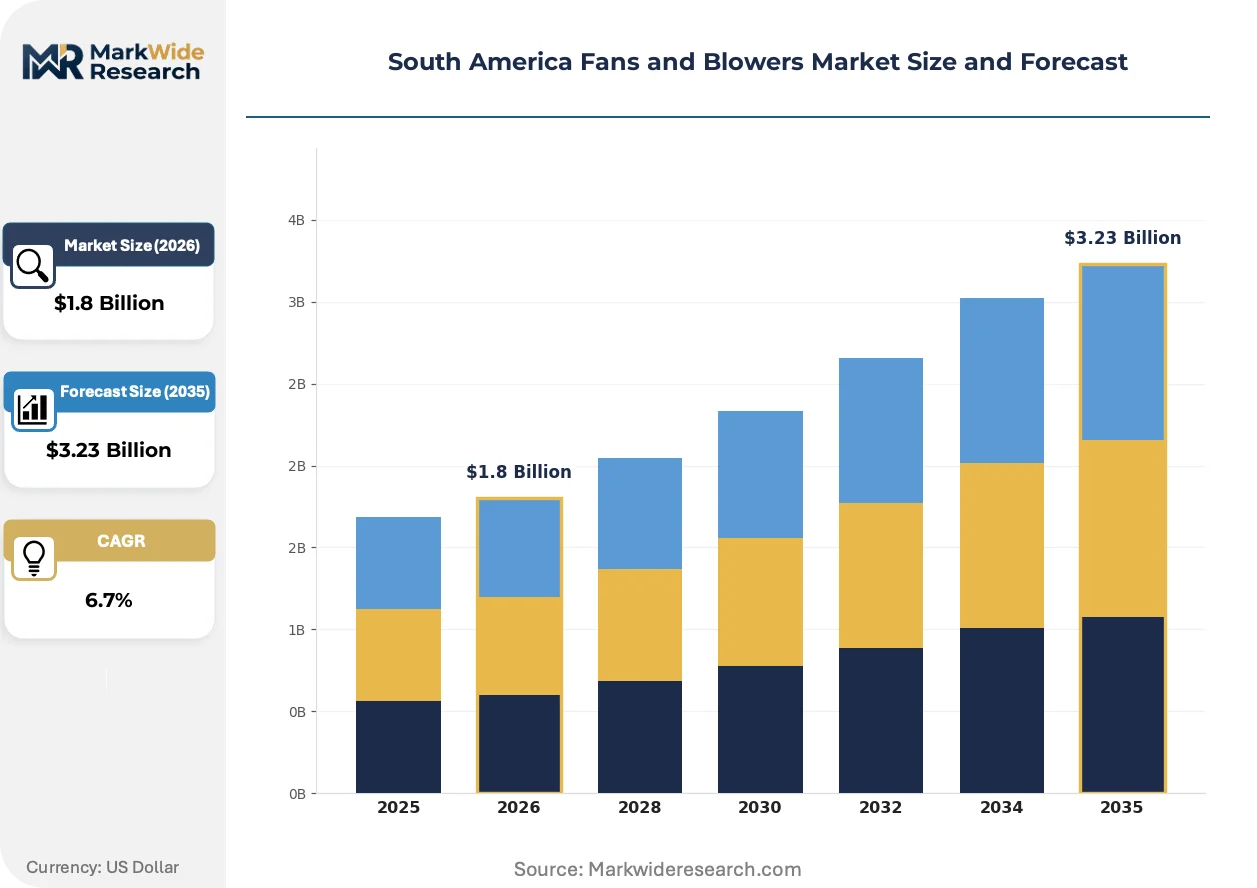
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Fans, Axial Fans, Blowers, Portable Fans End User: Manufacturing, HVAC, Automotive, Mining Application: Industrial Ventilation, Cooling Systems, Air Circulation, Exhaust Systems Technology: Electric, Hybrid, Gas-Powered, Solar |
| Companies Covered | Loren Cook Company, Howden Group Ltd, Trane Technologies plc, Cooltron Industrial Supply Inc, CG Power and Industrial Solutions Limited, Greenheck Fan Corp, Ebm-Papst Group, Acme Engineering And Manufacturing Corporation, Continental Blower LLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fans and Blowers Market Evolving Landscape
Permanent magnet synchronous motor architectures are compressing energy consumption benchmarks across South American industrial ventilation, while regulatory tier compression and procurement model fragmentation reshape competitive access patterns.
Direct-drive permanent magnet motor technology eliminates gearbox losses and maintenance points in heavy-duty centrifugal applications. Chilean state-owned mining enterprises and Brazilian pulp processors are specifying these configurations for 24/7 process ventilation. The technology is electrifying efficiency expectations in procurement specifications, compressing market space for conventional induction motor alternatives.
Brazil's INMETRO PBE labeling program tightens minimum efficiency thresholds for industrial fans on three-year revision cycles. The regulation forces equipment replacement decisions ahead of mechanical end-of-life in São Paulo and Minas Gerais manufacturing clusters. Suppliers must maintain parallel certification tracks as Argentina's IRAM and Chile's SEC adopt similar tier structures on staggered timelines.
Large-scale mining contractors are consolidating specification authority and unbundling aftermarket service from initial equipment procurement. Specialist ventilation engineering firms now control blower selection for major Peruvian and Chilean extraction projects, displacing direct OEM relationships. This concentration is most visible in the Andean copper belt, where three contracting groups manage ventilation infrastructure for over sixty percent of underground operations.
South America Fans and Blowers Market Segmentation
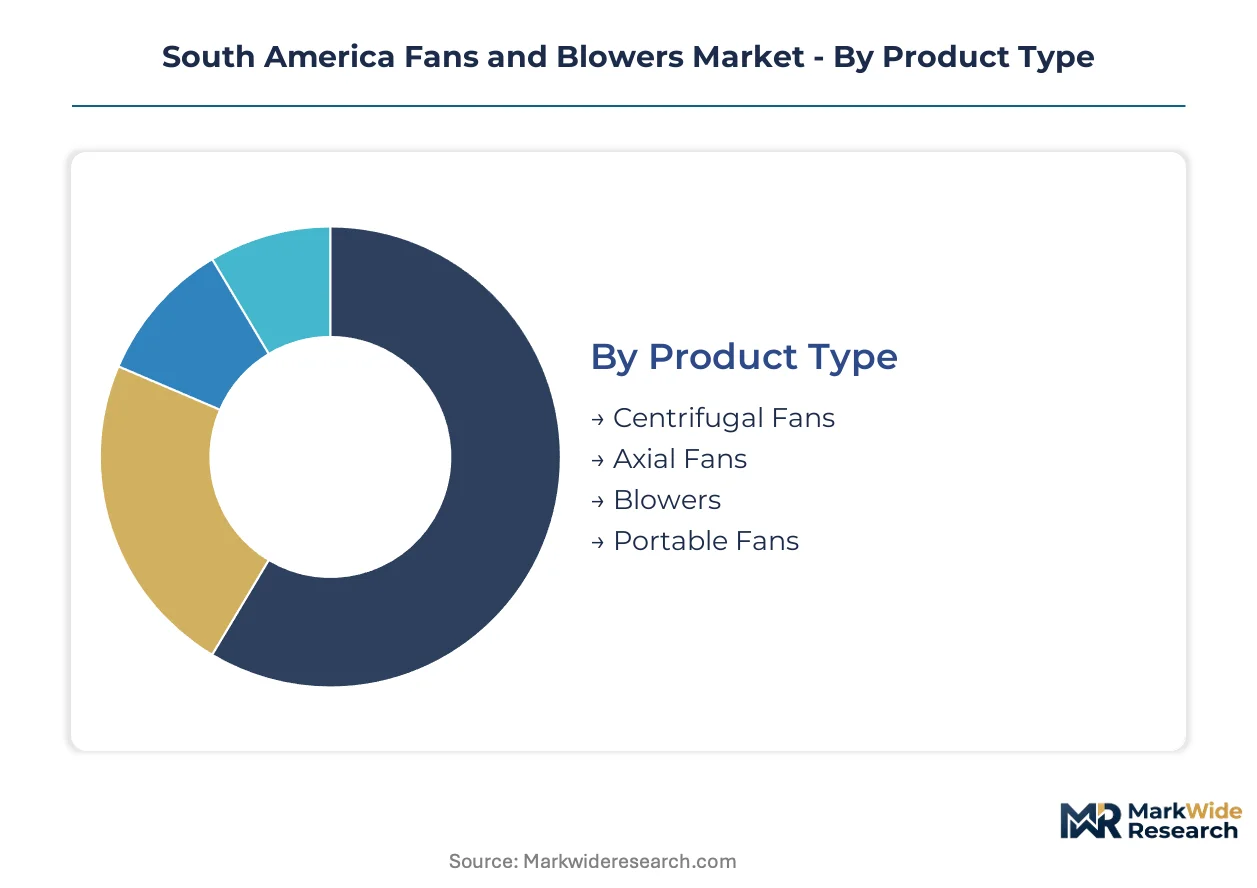
Segmentation in the South America fans and blowers market reveals how technology specifications, end-use requirements, and energy access constraints fragment procurement patterns across Brazil's manufacturing belt and the Andean mining corridor. Understanding these divides exposes where premium-efficiency upgrades concentrate versus where cost-minimized equipment prevails.
Product Type:
Pressure-generation requirements and ductwork configurations determine equipment selection across Chilean underground operations and Brazilian industrial facilities.
- Centrifugal Fans:Radial impeller designs generate high static pressure for ducted mining ventilation and heavy manufacturing exhaust. Chilean state-owned copper enterprises specify these for operations below 1,000 meters depth where atmospheric pressure demands exceed axial fan capabilities.
- Axial Fans:Inline configurations move large air volumes at lower pressure, dominating HVAC retrofit channels in São Paulo's commercial building stock where ceiling plenum space constraints favor compact footprints. Brazil's INMETRO labeling acceleration compresses replacement cycles for premium-efficiency axial units.
- Blowers:Positive-displacement mechanisms deliver precise airflow control for pneumatic conveying and combustion air supply in Argentine food processing clusters.
- Portable Fans:Mobile units serve temporary ventilation needs in Peruvian alluvial mining and Brazilian construction sites lacking permanent infrastructure.
Centrifugal fans lead on scale; axial fans lead on momentum.
End User:
Capital intensity and regulatory exposure create divergent procurement behaviors across customer categories.
- Manufacturing:Pulp processors and automotive parts suppliers in Minas Gerais drive demand for continuous-duty ventilation with integrated filtration. ANVISA industrial hygiene enforcement mandates upgrade schedules that outpace mechanical wear.
- HVAC:Commercial building operators across São Paulo prioritize energy efficiency tier compliance over initial cost. INMETRO PBE labeling creates regulatory pull for variable-speed motor-fan combinations in new construction and retrofit alike.
- Automotive:Paint booth ventilation and foundry exhaust systems in Córdoba and Buenos Aires manufacturing zones require spark-resistant construction and contaminant-specific filtration.
- Mining:Underground copper and gold extraction in Peru and Chile generates the region's most demanding ventilation specifications. The Ministry of Energy and Mines directives for deeper operations force high-pressure system deployment beyond conventional limits.
Manufacturing captures the largest installed base; mining generates the steepest specification escalation.
Application:
Functional requirements for air movement quality and contaminant control shape equipment architecture decisions.
- Industrial Ventilation:Process-specific contaminant removal demands customized ductwork and filtration integration. Brazilian pharmaceutical facilities combine HEPA filtration with blower systems to meet ANVISA airborne particulate standards.
- Cooling Systems:Heat rejection applications in Chilean data centers and Brazilian steel mills require corrosion-resistant materials for high-humidity environments.
- Air Circulation:General building comfort applications concentrate in Argentina's aging commercial stock where energy efficiency retrofits lag regional peers.
- Exhaust Systems:Fume and vapor extraction in Peruvian mining concentrators and Brazilian chemical processing demands spark-proof construction and emergency shutdown integration.
Industrial ventilation commands the premium tier; cooling systems are expanding most quickly.
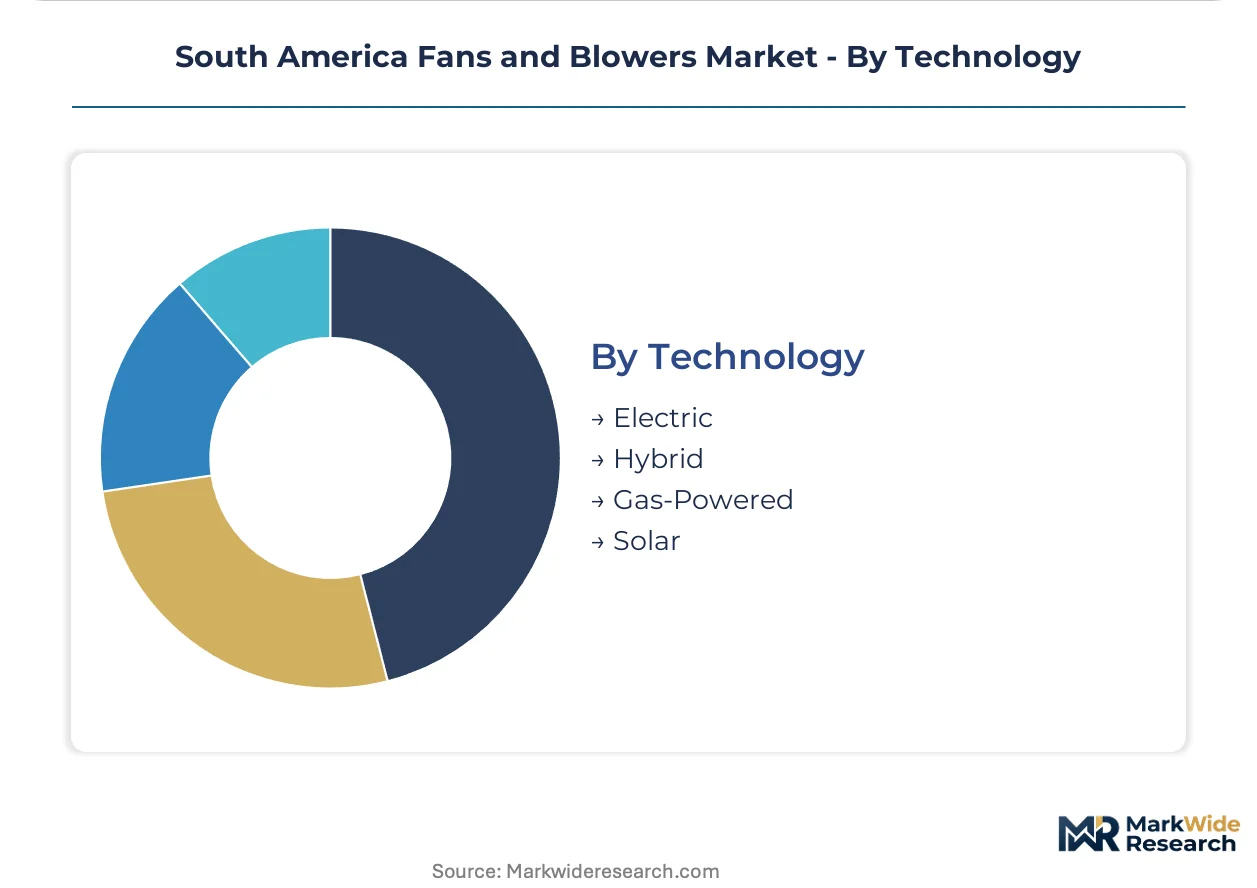
Technology:
Energy access infrastructure and operational continuity requirements fragment power source adoption across the region's geographic extremes.
- Electric:Grid-connected industrial facilities in São Paulo and Santiago specify permanent magnet synchronous motors for 24/7 process ventilation. Direct-drive architectures eliminate gearbox maintenance points in continuous-duty applications.
- Hybrid:Photovoltaic-diesel configurations address energy access gaps in Peruvian and Chilean high-altitude extraction sites beyond transmission infrastructure. Battery storage integration enables daytime solar capture for nighttime ventilation cycles.
- Gas-Powered:Natural gas and propane units serve remote Brazilian agroindustrial operations where grid extension costs exceed distributed generation economics.
- Solar:Standalone photovoltaic ventilation penetrates off-grid Amazon basin monitoring stations and small-scale alluvial mining camps with minimal capital deployment.
Electric technology dominates installed capacity; hybrid configurations gain share fastest in remote extraction frontiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest installed base of industrial ventilation equipment while Chile and Peru generate the steepest specification escalation through deep mining demands. Argentina's manufacturing corridor presents untapped retrofit potential amid aging infrastructure.
Brazil
INMETRO's PBE energy labeling program compresses replacement cycles across São Paulo and Minas Gerais manufacturing belts. ANVISA industrial hygiene standards mandate filter-integrated blower upgrades in food processing and pharmaceutical facilities. The southeastern industrial corridor spanning São Paulo state's automotive parts suppliers and Minas Gerais pulp processors drives continuous-duty ventilation procurement.
Chile
State-owned copper enterprises specify high-pressure centrifugal systems for operations below 1,000 meters depth where atmospheric pressure demands intensify. SEC electrical certifications create compliance obligations for cross-border equipment suppliers. The northern mining districts concentrate ventilation infrastructure investment as extraction depths extend beyond conventional limits.
Peru
The Ministry of Energy and Mines directives for deeper underground operations force ventilation infrastructure overhauls in copper and gold extraction. Remote high-altitude sites beyond transmission infrastructure accelerate photovoltaic-diesel hybrid adoption. The Andean mining belt generates the region's most demanding blower specifications through contractor-consolidated procurement.
Argentina
IRAM safety standards and certification-aligned product lines capture pent-up demand in Córdoba and Buenos Aires manufacturing zones. Aging commercial building stock lags regional peers in energy efficiency retrofits. The automotive paint booth and foundry exhaust segments in Córdoba require spark-resistant construction and contaminant-specific filtration.
Colombia
Grid connectivity limitations in remote extraction sites create diesel-electric hybrid cost premiums that slow electrification timelines. Emerging mining operations in the Andean foothills generate initial ventilation infrastructure demand. Bogotá's industrial periphery concentrates mid-tier manufacturing ventilation requirements with limited premium-efficiency penetration.
South America Fans and Blowers Market Competitive Landscape
European producers anchor the premium-efficiency tier; North American specialists hold scale advantages in commercial HVAC channels. The vendor base stratifies across three layers: global diversified industrials with full product portfolios, regional specialists concentrating on mining-grade heavy-duty systems, and niche motor-technology innovators. Market structure favors consolidation around specification authority as large-scale mining contractors unbundle aftermarket service from initial procurement. Dominant competitive moves include strategic partnerships with ventilation engineering firms and technology licensing for permanent magnet synchronous motor architectures.
Among diversified global industrials, Trane Technologies plc and Howden Group Ltd exemplify scale-driven positioning across multiple end-use segments. Greenheck Fan Corp occupies a fabrication-intensive tier serving commercial and institutional HVAC channels with broad manufacturing coverage. Ebm-Papst Group represents precision motor technology leadership in energy-efficient axial fan architectures. These anchors illustrate how competitive positioning fragments across technology specialization, geographic manufacturing footprint, and end-use concentration rather than consolidating around unified platform strategies.
| Leading Market Players |
|---|
| Loren Cook Company |
| Howden Group Ltd |
| Trane Technologies plc |
| Cooltron Industrial Supply Inc |
| CG Power and Industrial Solutions Limited |
| Greenheck Fan Corp |
| Ebm-Papst Group |
| Acme Engineering And Manufacturing Corporation |
| Continental Blower LLC |
| Others |
Value Network & Pricing Analysis
Permanent magnet synchronous motor architectures compress manufacturing costs for premium-efficiency centrifugal systems, with neodymium price volatility from Chinese rare-earth supply chains feeding through to tiered equipment pricing across Brazilian INMETRO-certified and uncertified product lines.
Pricing Analysis
Capacity additions in China's rare-earth processing facilities are reshaping price floors for high-efficiency motor components, with three-tier pricing structure across premium, standard, and economy levels separating INMETRO A-grade certified units from basic induction motor alternatives. Price differentiation centers on certification tier and after-sales service bundling, with Brazilian manufacturing belt buyers showing highest sensitivity to upfront capital outlay while Chilean state mining enterprises prioritize lifecycle cost. Pricing pressure stems from copper conductor cost swings, compressing margins for mid-tier suppliers serving Argentina's IRAM-aligned procurement channels.
Supply Chain Analysis
Brazil's ANVISA local-content mandates for industrial equipment procurement are reshaping sourcing patterns, with European precision bearing manufacturers and Chinese motor component suppliers anchoring upstream tiers. Raw material dependencies center on copper windings, neodymium permanent magnets, and specialized alloy housings. Supply chain risk concentrates in single-source vulnerability for high-pressure impeller castings from German and Italian specialist foundries. Distribution runs through ventilation engineering contractors in the Andean mining belt and direct OEM relationships with São Paulo manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in permanent magnet motor technology shifts and energy-as-a-service financing models that capture premium pricing without balance sheet burden on capital-constrained Brazilian mid-tier manufacturers.
For Market Incumbents: Anticipate contractor consolidation in Peruvian and Chilean mining ventilation procurement by deepening partnerships with specification-authority engineering firms. Defend against emerging Chinese motor-technology entrants by accelerating INMETRO A-grade certification coverage across axial fan product lines and capturing aftermarket service contracts unbundled from initial equipment sales. For New Entrants and Emerging Players: Solar-hybrid power architectures offer a technology-first wedge into off-grid Peruvian high-altitude extraction sites where diesel-electric premiums slow incumbent electrification timelines. Target Argentina's Córdoba automotive manufacturing corridor with IRAM-certified spark-resistant blower configurations, leveraging pent-up demand in aging paint booth infrastructure through equipment-leasing go-to-market structures. For Investors and Strategic Acquirers: Consolidation pressure builds where ventilation engineering firms control specification authority for over sixty percent of Andean underground operations. Long-term viability favors acquisition targets with permanent magnet synchronous motor technology portfolios and established INMETRO certification pathways. Watch for inflection where Brazilian mid-tier manufacturers accelerate INMETRO tier upgrades ahead of mechanical end-of-life, signaling financing model acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Technology Licensing | Direct-drive architectures eliminate gearbox maintenance points in Chilean state-owned copper enterprise specifications. |
| Energy-as-a-Service Financing Model | Equipment-leasing structures bypass capital constraints for INMETRO tier upgrades in São Paulo manufacturing belt. |
| IRAM Certification Investment | Alignment with Argentine safety standards captures pent-up demand in Córdoba and Buenos Aires manufacturing zones. |
| Ventilation Engineering Firm Partnership | Specification authority consolidation in Peruvian and Chilean mining channels displaces direct OEM relationships. |
| Solar-Hybrid Product Line Development | Photovoltaic-diesel configurations address energy access gaps beyond Andean transmission infrastructure. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and maintenance directors, customs and trade data reconciliation, SEC and local exchange filings — were reconciled across bottom-up equipment shipment analysis and top-down industrial ventilation spend estimates. Stakeholder consultations spanned OEM procurement teams at Brazilian pulp processors, aftermarket service heads at Chilean mining contractors, and ventilation engineering specialists in Lima and Santiago. Secondary validation drew from INMETRO certification databases, ANVISA industrial hygiene filings, and Peruvian Ministry of Energy and Mines ventilation directives.
Historical shipment patterns were cross-referenced against panel input from specification-authority contractors to build analytical framework projections across the analysis window. Segmentation dimensions modeled include product type, end-use industry, application function, and technology architecture. CAGRs were derived from trend extrapolation of equipment replacement cycles and regulatory tier compression schedules, with copper price trajectories and permanent magnet cost curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth supply chain disruptions and Brazilian electoral shifts affecting INMETRO enforcement intensity. Forecasts reflect documented assumptions on regulatory adoption timelines and mining investment cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Global Fans and Blowers Market