
 Digital Tachometer Market | 2026-2036
Digital Tachometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Tachometer Market Analysis
Silicon carbide sensor elements are consolidating as the preferred alternative to legacy Hall-effect components in high-temperature tachometer applications. OMEGA Engineering leverages captive semiconductor sourcing to stabilize component costs across its instrument portfolio. Emerson Electric sustains R&D intensity in optical sensing architectures for aerospace turbine monitoring. Dynapar anchors its competitive stance through backward integration into magnetic pickup manufacturing.
A digital tachometer measures rotational speed in revolutions per minute using electronic signal processing, typically employing inductive, optical, or magnetic sensing principles with resolution thresholds below 0.1 RPM for precision industrial applications. The device serves critical functions in predictive maintenance, quality assurance, and safety interlock systems across rotating machinery fleets. Panel-mount instruments dominate installed base volumes in factory automation settings where permanent machine integration is standard. Wireless connectivity represents the fastest-expanding technology segment as industrial IoT architectures demand untethered sensor networks for remote diagnostics. Handheld units retain margin concentration in field service and calibration workflows where portability commands pricing premiums.
FCC electromagnetic compatibility rules constrain transmitter design in wireless tachometer models sold into US industrial facilities. CE marking under the EU Machinery Directive mandates functional safety validation for instruments deployed in European manufacturing environments. IEC 61010-1 insulation and clearance requirements shape product architecture decisions for suppliers seeking multi-region market access. Stakeholders must weigh certification pathway costs against regional revenue concentration when prioritizing product development queues.
Market Dynamics
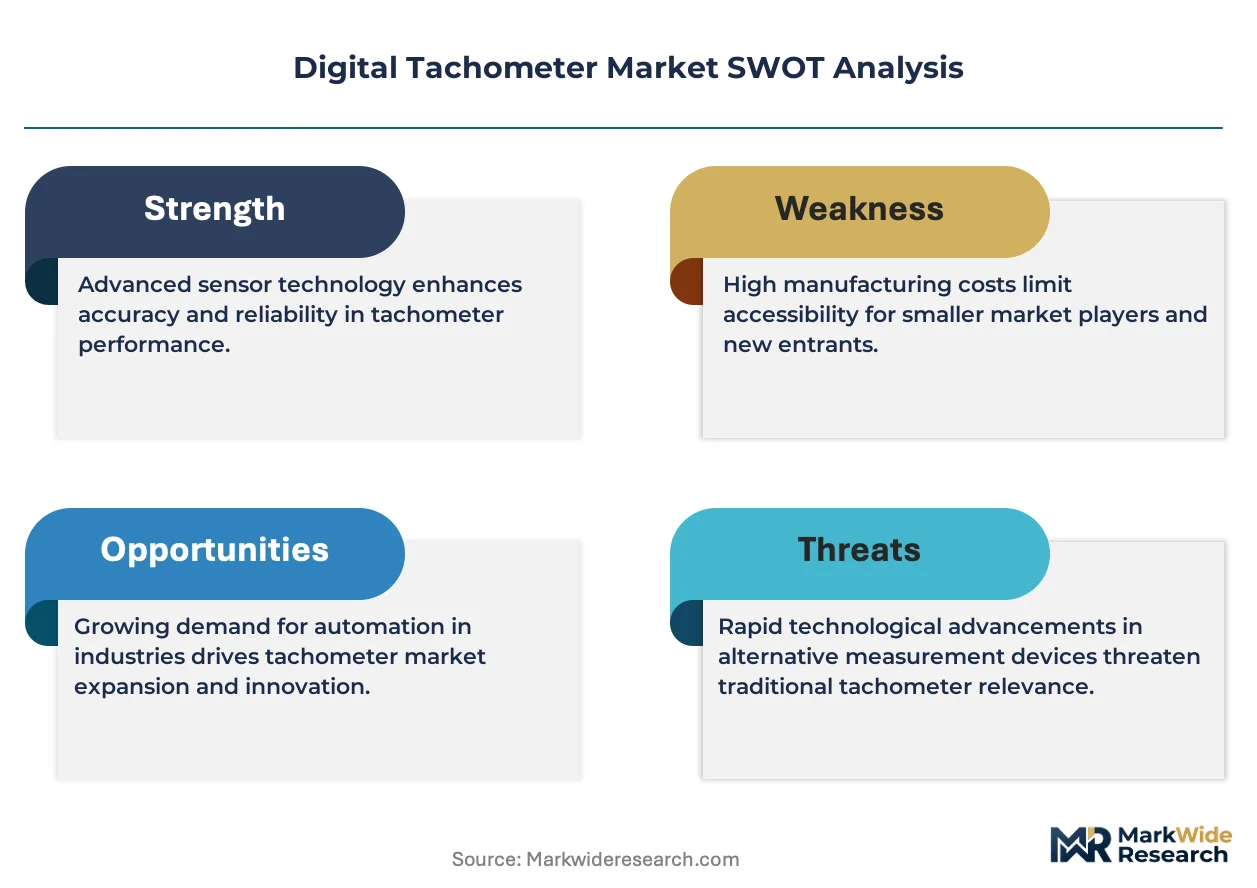
Industrial IoT architectures are forcing tachometer suppliers to reengineer product portfolios around wireless connectivity stacks, compressing development cycles and fragmenting certification requirements across multiple regulatory jurisdictions.
Growth Catalysts
- Automotive Test Facility Expansion:Precision speed-monitoring instrument procurement is accelerating across assembly line modernization programs in manufacturing economies with active industrial automation investment.
- IEC 61010-1 Standardization:Multi-region market access requirements are consolidating demand around suppliers with pre-certified insulation and clearance architectures.
- Silicon Carbide Sensor Migration:High-temperature application requirements are pulling replacement demand away from legacy Hall-effect component installations.
Market Restraints
- Rare Earth Magnet Supply Concentration:Magnetic pickup manufacturing faces input cost volatility tied to processing capacity limitations in dominant supplier geographies.
- FCC Electromagnetic Compliance Burden:Wireless transmitter design constraints add engineering overhead and extend validation timelines for US-bound product variants.
- Optical Sensing Cost Structure:Aerospace turbine monitoring applications require precision optical architectures that carry premium component costs and specialized calibration protocols.
Strategic Opportunities
- Predictive Maintenance Service Unbundling:Remote diagnostics capability is opening recurring revenue streams beyond hardware sales in rotating machinery fleet management.
- Handheld Unit Premium Positioning:Field service and calibration workflow requirements sustain margin concentration in portable instrument categories.
- CE Marking Functional Safety Pathway:EU Machinery Directive validation creates competitive differentiation for suppliers serving European manufacturing environments.
Industry Challenges
- Multi-Region Certification Timeline Compression:IEC 61010 safety standards, FCC electromagnetic rules, and CE marking requirements must be satisfied in parallel, straining quality assurance bandwidth.
- Legacy System Integration Complexity:Panel-mount instrument replacement cycles in factory automation settings demand backward compatibility with existing control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Tachometer Market |
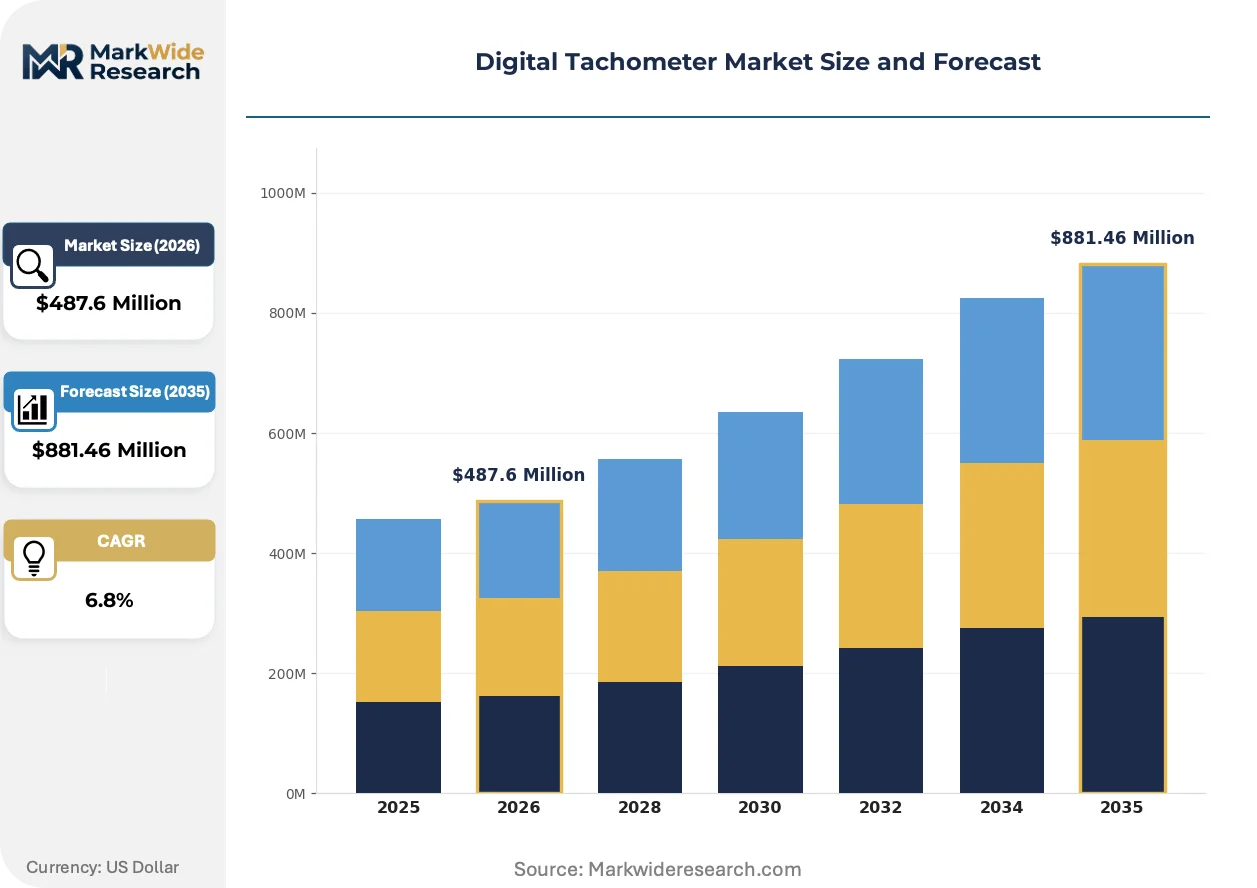
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Panel-Mount, Portable, Wireless Technology: Optical, Inductive, Magnetic, Contact End User: Automotive, Marine, Aerospace, Industrial Equipment Application: Monitoring, Calibration, Performance Testing, Diagnostics |
| Companies Covered | OMEGA Engineering, Emerson Electric, Dynapar, Fluke Corporation, Monarch Instrument, JTEKT Electronics Corporation, Rockwell Automation, Honeywell, OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Tachometer Market Emerging Trajectories
Wireless sensor networks are restructuring how rotational speed data flows from machine edge to enterprise systems, creating new competitive battlegrounds around connectivity protocol selection and cybersecurity architecture.
Silicon carbide sensor elements are decentralizing temperature-performance tradeoffs in industrial tachometer design. Automotive test facilities and aerospace turbine monitoring operations are adopting these components for applications exceeding legacy Hall-effect thermal limits. This material transition is decentralizing supplier power away from established magnetic sensing specialists toward semiconductor-capable instrument manufacturers.
CE marking under the EU Machinery Directive is tightening functional safety validation requirements for instruments deployed in European manufacturing environments. Suppliers must document hazard analysis and risk reduction measures to maintain market access. Panel-mount instrument categories face the most intensive scrutiny, driving consolidation toward vendors with dedicated compliance engineering resources.
Buyer concentration among industrial automation integrators is compressing sales cycle structures and reshaping channel economics. Direct procurement relationships with system integrators are displacing traditional distributor networks for volume factory automation deployments. China-based manufacturing investment programs exhibit the most pronounced shift toward consolidated supplier panels with integrated service capabilities.
Digital Tachometer Market Segmentation
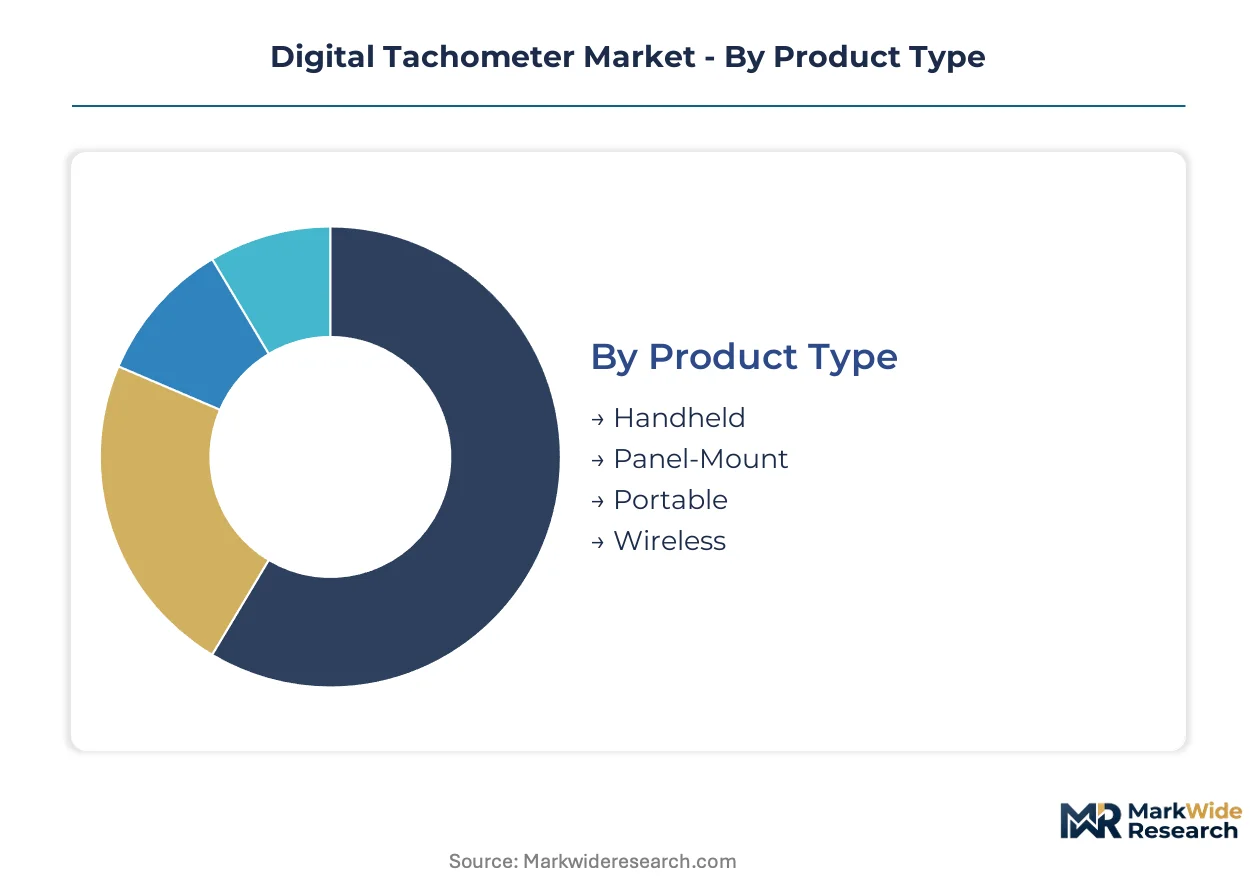
Digital tachometer procurement patterns diverge sharply across installation contexts, sensing architectures, and operational workflows. Manufacturers must align certification pathways and connectivity specifications to the dominant use case within each segment cluster.
Product Type:
Buyer differentiation hinges on mobility requirements versus permanent integration needs.
- Panel-Mount:Fixed-installation instruments dominate factory automation baselines with direct PLC integration and continuous monitoring capability. Demand concentrates in Germany and Japan where automotive test facility modernization programs require hardened enclosures meeting IEC 61010-1 insulation specifications.
- Wireless:Battery-powered units with industrial IoT connectivity stacks enable untethered sensor networks for remote diagnostics. Aerospace turbine monitoring operations in the United States drive FCC-compliant transmitter procurement under electromagnetic compatibility constraints.
- Handheld:Portable field service instruments command pricing premiums through calibration workflow portability.
- Portable:Semi-permanent units bridge fixed and mobile applications for temporary test bench configurations.
Panel-mount leads volumes today; wireless is gaining share fastest.
Technology:
Cost tier separation reflects component sourcing complexity and thermal performance boundaries.
- Magnetic:Inductive pickup architectures leverage rare earth magnet assemblies for high-reliability rotational detection in heavy industrial environments. Supply cost volatility from dominant processing geographies constrains margin stability for magnetic sensing specialists.
- Optical:Laser and infrared encoding systems deliver sub-0.1 RPM resolution for precision aerospace applications. Turbine manufacturers in France and the United Kingdom specify optical architectures despite premium calibration overhead.
- Inductive:Proximity-based detection suits contaminated environments where physical contact risks sensor damage.
- Contact:Mechanical probe instruments serve basic maintenance workflows with minimal electronics content.
Magnetic maintains installed base dominance; optical climbs the fastest on aerospace specification shifts.
End User:
Maturity gradients separate regulated safety-critical applications from commoditized industrial maintenance.
- Automotive:Assembly line and test facility procurement spans precision speed verification across powertrain validation cells. Chinese domestic automation investments expand instrument volumes for electric vehicle motor testing.
- Aerospace:Turbine monitoring demands functional safety documentation under EASA and FAA airworthiness pathways. Engine OEMs in the United States and Germany consolidate supplier panels around optical sensing certification.
- Industrial Equipment:Rotating machinery fleets drive replacement cycles for predictive maintenance instrumentation.
- Marine:Propulsion system monitoring in commercial shipping faces salt corrosion and vibration tolerance specifications.
Automotive leads volumes today; aerospace shows steepest expansion trajectory.
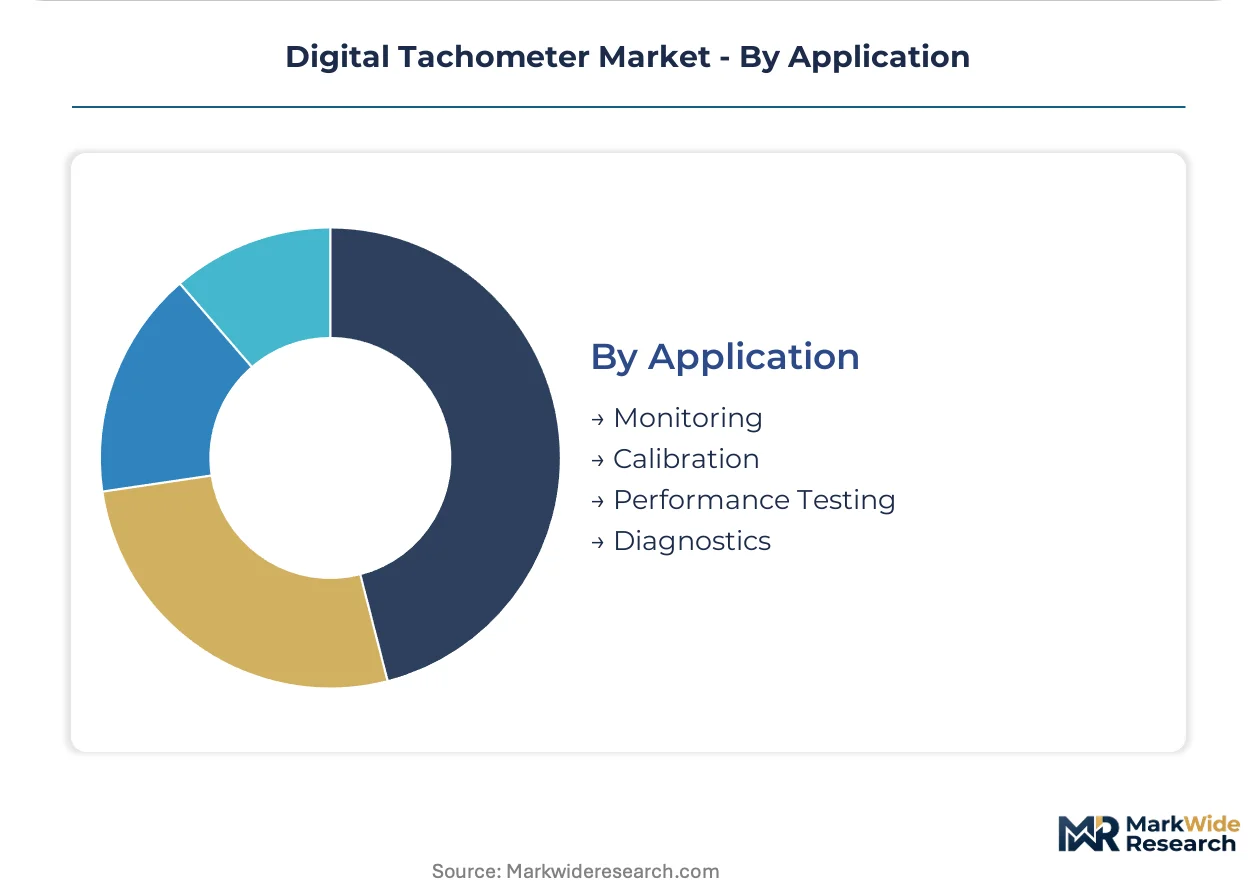
Application:
Customer type fragmentation separates capital equipment buyers from recurring service contract holders.
- Monitoring:Continuous rotational speed surveillance underpins safety interlock systems and process control loops. Factory automation integrators in China specify panel-mount instruments with integrated IoT gateways.
- Diagnostics:Condition-based maintenance workflows leverage wireless data streams for fleet-wide anomaly detection. Service providers unbundle hardware from predictive analytics subscriptions.
- Calibration:Traceable reference standards for field instrumentation require handheld portability and documented uncertainty budgets.
- Performance Testing:R&D and quality assurance protocols demand highest-resolution sensing for specification verification.
Monitoring leads volumes today; diagnostics expands most quickly on service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive test facility clusters in Stuttgart and Wolfsburg anchor instrument procurement volumes for precision speed-monitoring applications. Industrial automation integrators in these regions specify panel-mount tachometers with integrated IoT gateways for assembly line modernization.
United States
Aerospace turbine monitoring operations in Cincinnati and Hartford drive FCC-compliant wireless transmitter procurement under electromagnetic compatibility constraints. FAA airworthiness pathways mandate functional safety documentation for engine OEM supplier panels. Aerospace clusters in Arizona and Connecticut consolidate optical sensing certification requirements.
Germany
Automotive powertrain validation cells in Munich and Ingolstadt expand precision instrument volumes for electric vehicle motor testing. CE marking under the EU Machinery Directive tightens functional safety validation for panel-mount categories. Industrial automation investment programs in Baden-Württemberg concentrate demand around hardened enclosures.
China
Domestic industrial automation investments in Shanghai and Shenzhen expand instrument procurement volumes for rotating machinery fleets. GB standards and MIIT regulations shape product architecture decisions for multi-region market access. Manufacturing investment programs in Jiangsu and Zhejiang provinces shift toward consolidated supplier panels.
Japan
Precision industrial applications in Nagoya and Osaka demand resolution thresholds below 0.1 RPM for quality assurance protocols. METI industrial policy frameworks accelerate adoption of silicon carbide sensor elements in high-temperature environments. Automotive test facilities in Toyota City anchor magnetic pickup replacement cycles.
France
Aerospace turbine manufacturers in Toulouse and Bordeaux specify optical architectures despite premium calibration overhead. EASA functional safety documentation requirements consolidate supplier relationships around certified instrument vendors. Industrial equipment maintenance operations in Lyon drive handheld unit procurement for field service workflows.
Digital Tachometer Market Vendor Landscape
Global majors compete with regional champions across certification pathway breadth and sensing technology specialization. The vendor base stratifies between semiconductor-capable instrument manufacturers and legacy magnetic sensing specialists. Three archetypes dominate: diversified industrial conglomerates with captive semiconductor sourcing, precision instrumentation specialists with aerospace certification depth, and automation-focused suppliers with PLC integration expertise. Capacity expansion in silicon carbide sensor elements and strategic partnerships for wireless connectivity stacks represent the dominant competitive moves.
Among diversified industrial conglomerates, Emerson Electric and Honeywell exemplify scale-driven positions spanning multiple sensing architectures. OMEGA Engineering occupies a specialist tier focused on stabilized component costs through captive supply chains. Japanese manufacturers including OMRON Corporation and JTEKT Electronics Corporation anchor regional positions in precision industrial applications. Dynapar represents backward integration into magnetic pickup manufacturing. Fluke Corporation and Monarch Instrument sit within the handheld portability segment where field service workflows command pricing premiums.
| Leading Market Players |
|---|
| OMEGA Engineering |
| Emerson Electric |
| Dynapar |
| Fluke Corporation |
| Monarch Instrument |
| JTEKT Electronics Corporation |
| Rockwell Automation |
| Honeywell |
| OMRON Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into magnetic pickup manufacturing anchors Dynapar's supply position while stabilizing component cost pass-through to buyers. Captive semiconductor sourcing at OMEGA Engineering similarly insulates pricing power against rare earth magnet volatility concentrated in dominant processing geographies.
Pricing Analysis
Rare earth magnet cost pass-through dominates magnetic sensing tier pricing, with neodymium and dysprosium price swings flowing directly to panel-mount instrument quotations. Three-tier pricing structure across aerospace-certified optical, industrial-grade magnetic, and economy contact tiers separates buyers by resolution requirement and thermal specification. Cost compression in wireless connectivity modules is intensifying because silicon carbide sensor volumes are scaling through automotive test facility procurement. Field service workflows command least price sensitivity, while factory automation integrators in China exhibit highest volume-driven negotiation leverage.
Supply Chain Analysis
Specialized calibration technician availability in Germany, Japan, and the United States constrains optical sensing assembly expansion despite aerospace demand pull. Silicon carbide wafer fabrication draws from Taiwan and South Korea semiconductor foundries, while rare earth magnet processing rests on Chinese separation and refining capacity. Single-source vulnerability in Hall-effect legacy component supply chains threatens magnetic pickup manufacturers with forced architecture migrations. Distribution runs through industrial automation integrator panels in China and Germany, displacing traditional distributor networks for volume deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide sensor cost curves are compressing premium-tier entry thresholds, expanding margin capture for semiconductor-capable instrument manufacturers. This cost-down driver rewards suppliers with captive wafer sourcing and optical certification depth.
For Market Incumbents: Anticipate semiconductor-capable entrants eroding magnetic sensing margins by accelerating silicon carbide sensor roadmaps and securing captive foundry allocation. Defensive consolidation moves center on backward integration into magnetic pickup manufacturing and CE marking functional safety investment to lock European automotive test facility relationships. Certification bandwidth constraints threaten incumbents lacking dedicated compliance engineering resources. For New Entrants and Emerging Players: Capture handheld unit premium positioning in field service workflows where calibration portability commands pricing power and brand loyalty remains underdeveloped. White-space targets cluster around wireless IoT-enabled diagnostics for rotating machinery fleets in China's Jiangsu and Zhejiang manufacturing investment zones. Go-to-market execution should anchor on direct procurement relationships with industrial automation integrators rather than traditional distributor channels. For Investors and Strategic Acquirers: Roll-up economics work for precision instrumentation specialists with aerospace certification depth because FAA and EASA airworthiness pathways create defensible moats around turbine monitoring supplier panels. Long-term viability favors targets with integrated silicon carbide sensor capabilities and multi-region IEC 61010-1 pre-certification. Watch silicon carbide wafer pricing inflection as signal for margin expansion timing in semiconductor-capable instrument portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Sensor Migration | Automotive test facilities in Stuttgart and Wolfsburg specify high-temperature components exceeding Hall-effect thermal limits. |
| CE Marking Functional Safety Investment | EU Machinery Directive validation consolidates European manufacturing supplier relationships around certified instrument vendors. |
| Wireless Connectivity Stack Integration | Industrial IoT architectures in Chinese automation investment zones demand untethered sensor networks for remote diagnostics. |
| Backward Integration into Magnetic Pickup Manufacturing | Rare earth magnet supply concentration in dominant processing geographies threatens input cost stability for non-integrated suppliers. |
| Aerospace Optical Sensing Certification | FAA airworthiness pathways in Cincinnati and Hartford consolidate engine OEM supplier panels around precision resolution capabilities. |
Methodological Framework
Bottom-up automotive and aerospace end-use modeling reconciled against top-down semiconductor and magnet supply-side tracking forms the analytical core of this study. Primary interviews with maintenance directors at rotating machinery fleets, plant engineers in automotive test facilities, procurement leads at industrial automation integrators, and aftermarket service heads at precision instrumentation distributors combined with secondary validation from IEC certification databases, FCC equipment authorization filings, customs trade data for rare earth magnet flows, and SEC 10-K disclosures from diversified industrial conglomerates. Triangulation between stakeholder demand signals and component supply constraints calibrated volume and value estimates.
Historical trendline analysis across magnetic, optical, and inductive sensing technology adoption curves informed projection framework construction. Segmentation dimensions modeled include product type mobility requirements, sensing architecture thermal boundaries, end-use regulatory maturity gradients, and application workflow customer types. CAGRs derived from fitted trend extrapolation adjusted for silicon carbide sensor substitution elasticity and wireless connectivity module cost decay rates through the projection horizon. Aerospace turbine monitoring specification shifts and Chinese domestic automation investment program procurement volumes served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; aerospace optical sensing and automotive panel-mount categories carry tighter precision than economy contact instrument tiers due to certification documentation density and supplier panel consolidation. Forecasts reflect assumptions about IEC 61010-1 standardization timeline adherence, rare earth magnet processing capacity expansion, and silicon carbide wafer foundry allocation prioritization. Material deviation in FAA airworthiness pathway enforcement stringency or Chinese MIIT industrial automation subsidy levels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Actuators Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Contour Measuring Machines Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Above 300mm Cooling Fans Market