
 Air Bearing Spindle Market | 2026-2036
Air Bearing Spindle Market Size, Share, and Industry Trends Forecast 2026-2036
Air Bearing Spindle Market Analytics
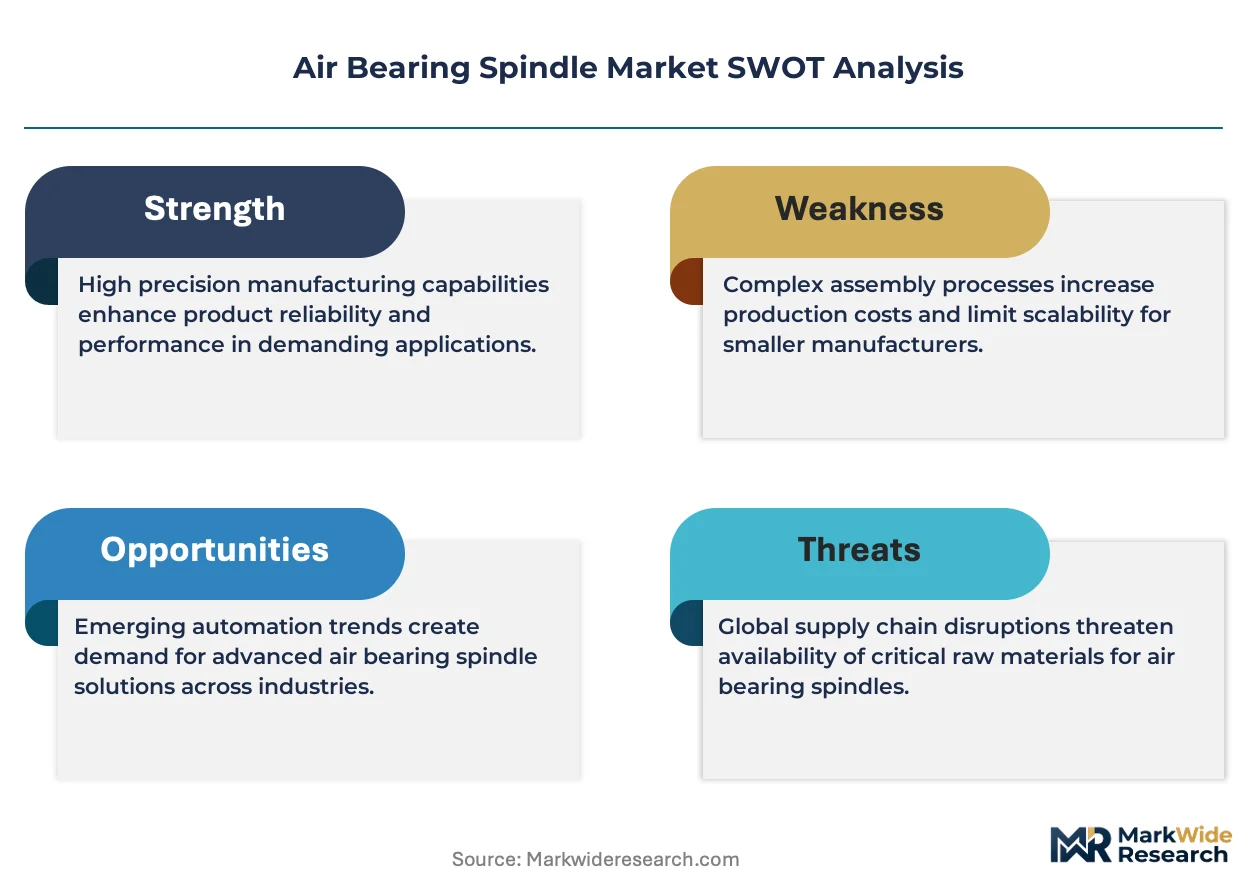
A capital-intensity divergence between integrated spindle builders and modular component suppliers is redrawing competitive boundaries in precision motion. Westwind Air Bearings leverages proprietary porous media technology to dominate aerospace turbine blade grinding installations. NSK Ltd. anchors its position through backward integration into ceramic ball manufacturing and in-house production of sensor-integrated bearing systems. NTN Corporation competes by extending its automotive precision heritage into medical imaging gantry applications.
An air bearing spindle suspends a rotating shaft on a thin film of pressurized gas, typically achieving rotational accuracies below 0.1 micrometer and speeds exceeding 100,000 RPM without mechanical contact. This non-contact architecture eliminates particulate generation, making the technology essential for semiconductor wafer dicing and optical lens polishing where contamination control dictates yield. High-speed spindle configurations command premium positioning in lithography and laser micromachining segments where thermal stability and nanometer-level runout determine process capability. Custom spindle builds represent the fastest-growing revenue pool as OEM equipment builders demand application-specific taper interfaces, integrated motor windings, and embedded condition monitoring. Standard spindle sales remain volume-heavy but margin-constrained by Asian competitor price pressure in general CNC machining.
FDA device quality system regulations and ISO 17025 calibration standards shape medical imaging and metrology spindle procurement, mandating traceable performance documentation and preventive maintenance protocols. EPA energy efficiency guidelines and OSHA workplace noise limits further filter supplier qualification in US manufacturing environments. Semiconductor equipment buyers must monitor REACH substance restrictions on perfluorinated lubricants and evolving EU AI Act conformity requirements for autonomous process control systems.
Market Dynamics
Semiconductor lithography equipment manufacturers are consolidating procurement around high-speed spindle architectures as EUV scanner complexity drives rotational accuracy requirements below 50 nanometers. This technical escalation is compressing supplier qualification timelines and fragmenting volume between integrated builders and modular specialists.
Growth Catalysts
- China's dual carbon goals:Industrial efficiency mandates under MEE regulations are accelerating replacement of conventional mechanical bearings in precision manufacturing clusters.
- EUV lithography expansion:Scanner OEMs are expanding spindle procurement for next-generation node production, with nanometer-level runout specifications becoming non-negotiable.
- REACH substance restrictions:Perfluorinated lubricant limitations are forcing contamination-sensitive industries toward gas-film suspension technologies.
Market Restraints
- Input cost volatility:Porous carbon and specialty ceramic feedstocks face supply concentration from Japanese and German precursor suppliers.
- Technical limitation:Load capacity constraints in aerostatic configurations restrict adoption in heavy-duty turbine blade grinding above 50 kilograms.
- Regulatory friction:FDA device quality system documentation requirements extend medical imaging spindle qualification cycles by 18-24 months.
Strategic Opportunities
- Underpenetrated medical robotics:Surgical tool sharpening and orthopedic implant polishing represent untapped demand in Swiss and German manufacturing corridors.
- Technology convergence:Embedded condition monitoring systems integrating vibration sensors and thermal mapping are opening predictive maintenance revenue streams.
- Regulatory tailwind:EU AI Act conformity requirements for autonomous process control are creating specification premiums for sensor-integrated spindle platforms.
Industry Challenges
- Skill gap in aerostatic design:The shortage of engineers capable of optimizing orifice and porous media geometries is constraining custom build capacity.
- Certification timeline compression:ISO 17025 calibration traceability requirements are colliding with compressed semiconductor equipment delivery schedules.
- Integration complexity:Legacy CNC machining centers require mechanical retrofitting to accommodate air bearing spindle interfaces, delaying adoption in installed base upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Bearing Spindle Market |
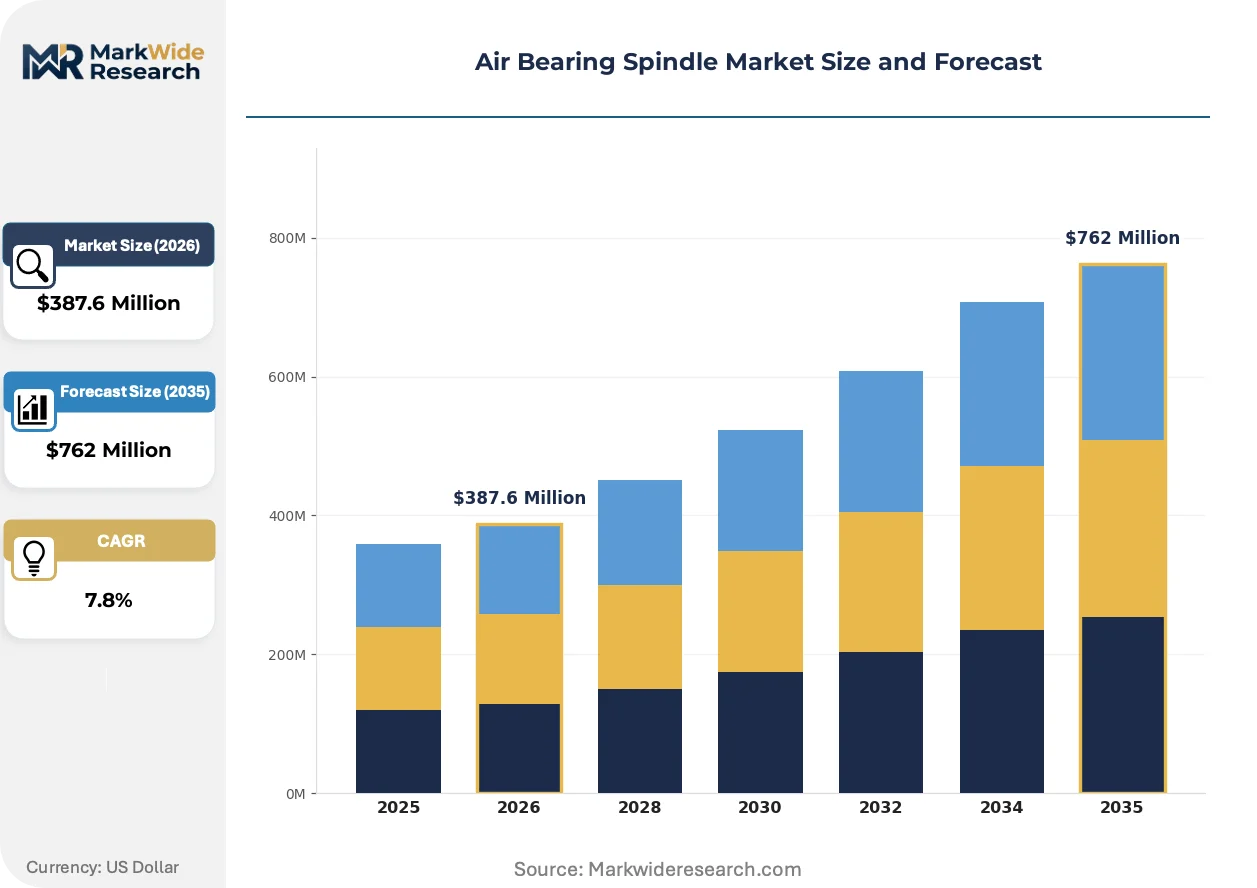
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $762 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Spindle, High-Speed Spindle, Custom Spindle, Vertical Spindle End User: Aerospace, Automotive, Electronics, Medical Application: CNC Machining, Grinding, Milling, Laser Cutting Installation: Built-in, Removable, Integrated, Standalone |
| Companies Covered | Westwind Air Bearings, Air Bearings Ltd., NSK Ltd., NTN Corporation, PI Nelson Air Corp, Cranfield Precision, Seagull Solutions, Inc., FME Corp, IBAG North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Bearing Spindle Market Evolving Landscape
Active magnetic bearing hybrids and sensor-integrated architectures are fragmenting traditional spindle procurement patterns. Equipment builders now demand application-specific configurations that bundle motion control, thermal management, and predictive diagnostics into single-source supply agreements.
Porous media aerostatic technology is decomposing conventional orifice-based designs in semiconductor wafer dicing applications. Lithography equipment manufacturers are specifying Westwind-style porous carbon inserts for sub-0.05 micrometer rotational accuracy. This materials shift is compressing the addressable market for drilled-orifice spindle specialists and elevating chemistry-controlled manufacturing capabilities as a competitive barrier.
REACH perfluorinated substance restrictions and evolving EU AI Act conformity requirements are reshaping supplier qualification protocols. Equipment buyers now mandate documented substance compliance and autonomous control system certifications before spindle approval. Semiconductor metrology and medical imaging segments are responding by consolidating procurement around vertically integrated builders with captive regulatory affairs capabilities.
Buyer concentration among lithography OEMs is forcing spindle vendors into co-development contracts with exclusive taper interfaces and embedded motor windings. The traditional catalog spindle model is yielding to application-specific engineering partnerships. This pattern is most visible in East Asian precision manufacturing clusters around Hsinchu Science Park and Seoul's Pangyo Techno Valley, where equipment builders specify proprietary interfaces to lock in supply security.
Air Bearing Spindle Market Segmentation
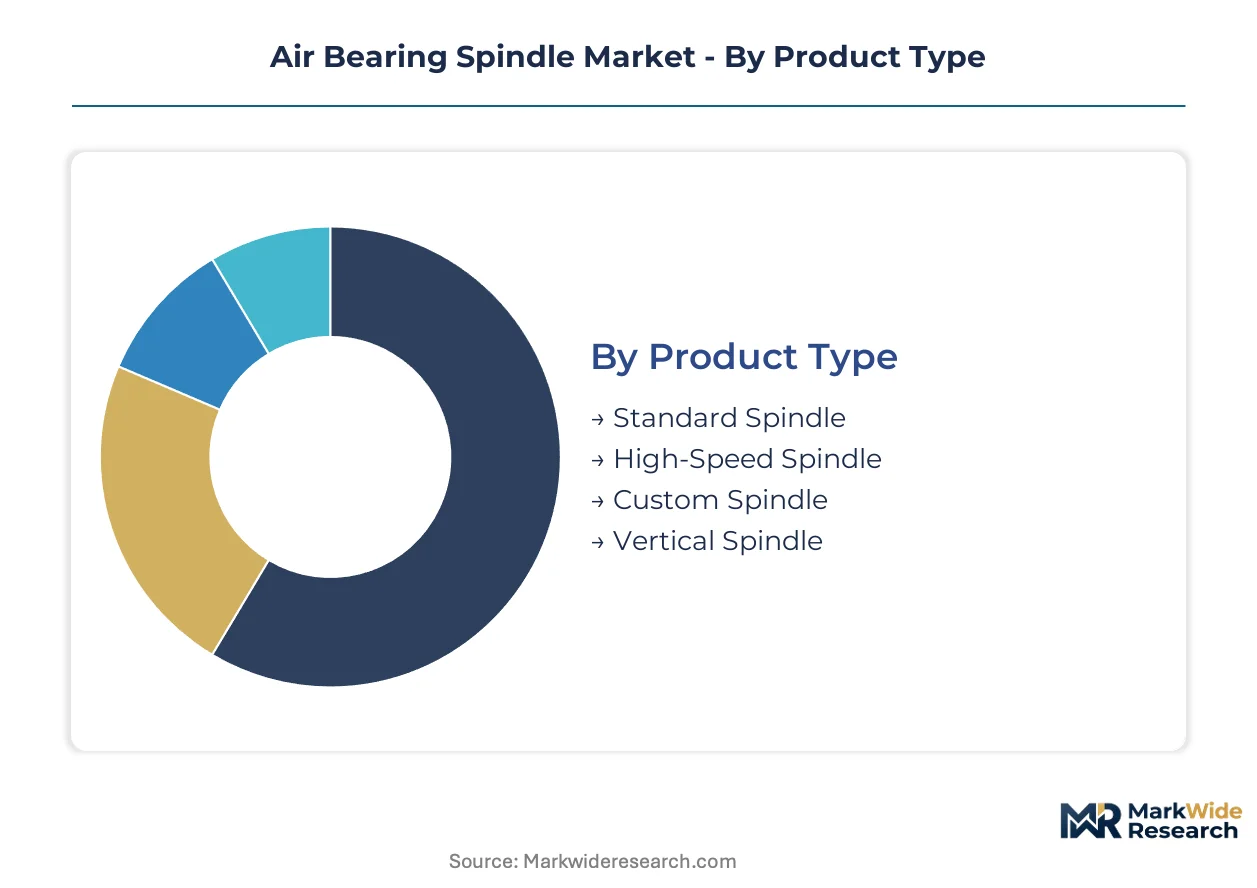
Air bearing spindle procurement patterns fragment sharply across product architectures and end-use specifications. Equipment builders demand application-specific configurations that bundle rotational accuracy, thermal stability, and contamination control into unified supply agreements.
Product Type:
High-speed and custom configurations face intensifying substitution pressure from active magnetic bearing hybrids in heavy-load turbine applications, while standard designs confront Asian price competition in general machining.
- Standard Spindle:Catalog configurations with fixed taper interfaces and pre-integrated motor windings serve volume CNC machining installations. Demand concentrates in Chinese precision manufacturing clusters where MEE efficiency mandates accelerate mechanical bearing replacement.
- High-Speed Spindle:Aerostatic architectures achieving rotational accuracies below 0.1 micrometer and speeds exceeding 100,000 RPM dominate semiconductor lithography equipment. EUV scanner OEMs in Hsinchu Science Park and Seoul's Pangyo Techno Valley specify nanometer-level runout as non-negotiable.
- Custom Spindle:Application-specific builds with proprietary taper interfaces and embedded condition monitoring command premium positioning.
- Vertical Spindle:Configurations optimized for gravitational load orientation in optical lens polishing and wafer dicing.
Standard spindles anchor the volume base while custom builds gain share at the steepest rate.
End User:
Electronics and medical segments concentrate procurement around contamination-sensitive architectures where REACH perfluorinated restrictions eliminate conventional lubricant options.
- Aerospace:Turbine blade grinding installations specify porous media aerostatic technology for sub-0.05 micrometer accuracy. Load capacity constraints above 50 kilograms restrict penetration in heavy-duty applications.
- Automotive:Precision heritage from powertrain machining extends into electric motor stator grinding and battery component finishing.
- Electronics:Semiconductor wafer dicing and lithography equipment demand gas-film suspension to eliminate particulate generation.
- Medical:FDA device quality system regulations and ISO 17025 calibration standards mandate traceable performance documentation and preventive maintenance protocols.
Electronics procurement anchors current volume while medical imaging applications expand most quickly.
Application:
Laser cutting and precision grinding command specification premiums over conventional CNC machining where mechanical bearings retain cost advantage.
- CNC Machining:General-purpose installations face margin compression from Asian competitor price pressure. Legacy equipment retrofit requirements delay air bearing adoption in installed base upgrades.
- Grinding:Optical lens polishing and orthopedic implant finishing require nanometer-level surface finish control. Swiss and German manufacturing corridors represent underpenetrated demand for surgical tool sharpening applications.
- Milling:High-material-removal-rate configurations stress aerostatic load capacity limits.
- Laser Cutting:Thermal stability requirements in micromachining drive specification of sensor-integrated spindle platforms with embedded vibration monitoring.
Grinding applications anchor revenue concentration while laser micromachining climbs the fastest.
Installation:
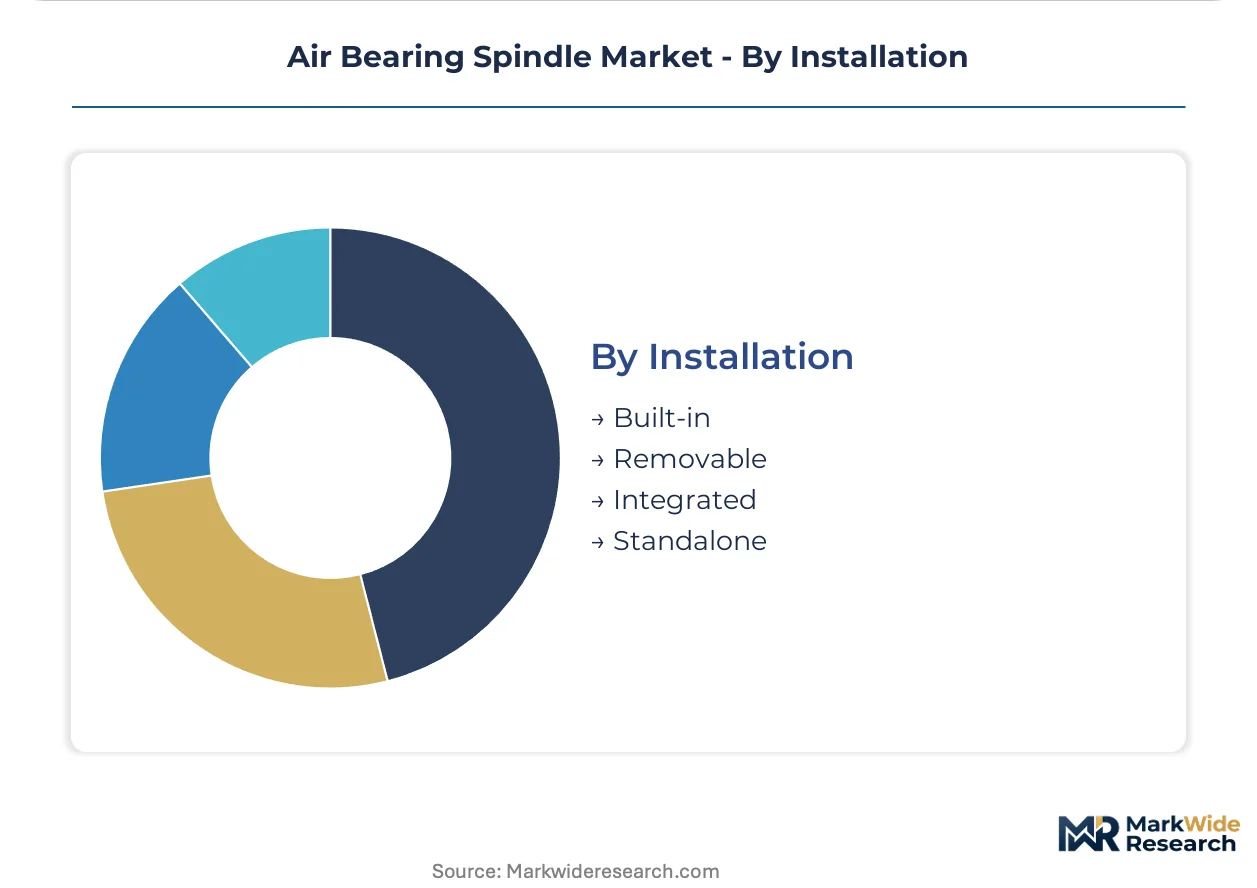
Built-in and integrated configurations capture specification premiums as OEM equipment builders consolidate procurement around single-source motion control systems.
- Built-in:Permanent integration into original equipment designs with proprietary interfaces locks in supply security. Lithography OEMs mandate exclusive taper specifications and embedded motor windings through co-development contracts.
- Removable:Field-replaceable modules support preventive maintenance protocols in medical imaging and metrology applications. ISO 17025 calibration traceability requirements extend qualification cycles.
- Integrated:Bundled architectures combining spindle, drive, and control electronics into unified subsystems.
- Standalone:Self-contained units for retrofit installations and laboratory metrology environments.
Built-in installations dominate OEM procurement while integrated configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Japanese precision component suppliers outpace import volumes in high-accuracy spindle architectures, while China narrows its trade deficit through domestic porous media manufacturing scale-up. Taiwan and South Korea maintain balanced trade in lithography-grade spindles. The United States runs a structural import dependency for semiconductor equipment subassemblies.
China
MEE industrial efficiency mandates accelerate mechanical bearing replacement in Yangtze River Delta precision clusters. Dual carbon goals tighten energy consumption benchmarks for manufacturing equipment. Hsinchu Science Park equipment builders source spindle subassemblies from Suzhou and Shenzhen fabrication corridors.
United States
FDA device quality system regulations extend medical imaging spindle qualification timelines by 18-24 months. EPA energy efficiency guidelines filter supplier access in precision manufacturing environments. Greater Boston and Silicon Valley concentrate metrology and semiconductor equipment procurement around traceable calibration protocols.
Germany
REACH perfluorinated substance restrictions eliminate conventional lubricant options in contamination-sensitive applications. ECHA substance compliance documentation becomes mandatory for spindle approval in EU equipment supply chains. Bavaria and Baden-Württemberg anchor precision grinding demand from automotive and medical technology OEMs.
Japan
METI industrial technology roadmaps prioritize nanometer-level motion control for next-generation lithography. JIS standards govern rotational accuracy certification for domestic equipment procurement. Nagoya and Osaka manufacturing corridors supply porous carbon feedstocks and ceramic precursor materials to global spindle builders.
South Korea
MFDS medical device regulations align with FDA quality system requirements for imaging equipment imports. Pangyo Techno Valley equipment builders specify proprietary spindle interfaces through exclusive co-development contracts. Seoul Capital Area lithography OEMs consolidate procurement around vertically integrated motion control suppliers.
Air Bearing Spindle Market Competitive Landscape
Concentration sits with integrated spindle builders possessing captive porous media manufacturing and in-house regulatory affairs capabilities. Modular component suppliers compete on application-specific engineering velocity but face margin compression from Asian price competition in standard configurations. Three archetypes dominate: vertically integrated precision motion specialists, porous media technology licensors, and catalog spindle distributors with regional service networks. Competitive moves center on backward integration into ceramic feedstock production and exclusive co-development contracts with lithography OEMs.
Among integrated precision motion specialists, Westwind Air Bearings and NSK Ltd. exemplify the premium-tier archetype through proprietary manufacturing capabilities. NTN Corporation occupies a position bridging automotive precision heritage and medical imaging applications. Air Bearings Ltd. and PI Nelson Air Corp represent the modular engineering tier focused on custom build velocity. Seagull Solutions, Inc. and IBAG North America anchor North American distribution and service capabilities.
| Leading Market Players |
|---|
| Westwind Air Bearings |
| Air Bearings Ltd. |
| NSK Ltd. |
| NTN Corporation |
| PI Nelson Air Corp |
| Cranfield Precision |
| Seagull Solutions, Inc. |
| FME Corp |
| IBAG North America |
| Others |
Value Network & Pricing Analysis
Ninety-day ceramic precursor lead times from Nagoya suppliers compress pricing power for modular spindle builders while amplifying margin capture for integrated manufacturers with captive feedstock production. This inventory-to-pricing dynamic rewards backward integration into porous carbon manufacturing and punishes catalog distributors dependent on spot-market ceramic sourcing.
Pricing Analysis
The customization-premium spread between configured-to-order and standard spindle pricing widens as lithography OEMs demand proprietary taper interfaces and embedded motor windings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard configurations intensifies because Asian competitors flood general CNC machining with price-competitive mechanical bearing alternatives. Medical imaging buyers show least price sensitivity due to FDA-mandated qualification investments, while Chinese precision manufacturing clusters exhibit highest sensitivity to upfront equipment costs.
Supply Chain Analysis
Inbound logistics costs on the Yokohama-Hamburg trade lane strain just-in-time delivery of porous carbon feedstocks to European spindle assemblers. Supply concentrates in Japan, Germany, and China for ceramic precursor materials, specialty coatings, and precision-machined housings. Raw material dependencies draw from porous carbon substrates, silicon nitride ceramic balls, and rare-earth motor magnets. Single-source vulnerability from Japanese carbon precursor suppliers threatens production continuity. Distribution runs through direct OEM partnerships for built-in configurations and regional service networks for removable spindle modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power shifts toward lithography OEMs as equipment procurement consolidates around co-development contracts with exclusive supply terms. This concentration fragments volume between integrated builders and modular specialists.
For Market Incumbents: Secure captive porous media manufacturing capabilities to defend margin position against substitute magnetic bearing hybrids encroaching on heavy-load applications. Anchor regulatory affairs capacity in-house to compress FDA and EU AI Act qualification timelines that modular competitors cannot match. Prioritize exclusive taper interface development with Hsinchu Science Park and Pangyo Techno Valley equipment builders to lock in supply security. For New Entrants and Emerging Players: Anchor in Swiss and German surgical tool sharpening corridors where orthopedic implant polishing demand outpaces established service coverage. Target medical robotics white space with compact aerostatic spindles optimized for gravitational load orientation in automated polishing cells. Pursue embedded condition monitoring integration as the go-to-market angle, bundling vibration sensors and thermal mapping into predictive maintenance revenue streams. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because REACH substance restrictions and FDA quality system mandates continuously elevate compliance barriers. Acquisition candidates center on vertically integrated precision motion specialists with captive ceramic feedstock production and documented ISO 17025 calibration protocols. Watch EU AI Act conformity requirement enforcement as the inflection signal for sensor-integrated spindle specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Feedstock | Captive porous carbon production insulates margin from Japanese precursor supply volatility. |
| Exclusive Co-Development Contracts | Proprietary taper interfaces with ASML and Tokyo Electron lock in lithography-grade volume. |
| Embedded Condition Monitoring Launch | Sensor-integrated platforms capture EU AI Act specification premiums in semiconductor metrology. |
| Regulatory Affairs Capacity Expansion | In-house FDA and ECHA documentation teams compress medical imaging qualification cycles. |
| Medical Robotics Application Engineering | Surgical tool sharpening specialization penetrates Swiss orthopedic manufacturing corridors. |
Research Methodology
Initial hypotheses were tested against primary input from spindle design engineers, OEM procurement managers, aftermarket service heads, and precision manufacturing plant managers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary triangulation against METI industrial technology roadmaps, ECHA substance restriction databases, FDA 510(k) filing records, and customs trade flow data. Bottom-up build from application-level demand and top-down validation from equipment shipment data converged on segment-specific estimates.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in high-speed, standard, and custom spindle configurations. The analytical framework models product architecture, end-use industry, installation type, and regional manufacturing cluster as core segmentation dimensions. CAGRs derive from equipment procurement cycle analysis and replacement rate assumptions tied to MEE efficiency mandates and EUV lithography expansion trajectories. Forecast inputs incorporate REACH substance restriction phase-out schedules and semiconductor node transition timelines.
Material uncertainties — tariff exposure on ceramic imports, REACH perfluorinated lubricant prohibition enforcement, and EUV scanner deployment delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and buyer consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Dust Collector Systems Market