
 Gypsum-Based Products Market | 2026-2036
Gypsum-Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum-Based Products Market Outlook
Building-material distribution is tilting toward direct contractor relationships and digital procurement platforms. Saint-Gobain leverages its vertically integrated plasterboard network across Western Europe. Knauf Group anchors its position through captive gypsum reserves and regional manufacturing density. Yoshino Gypsum Co., Ltd. specializes in high-performance moisture-resistant boards for Japan's humid coastal zones.
Gypsum-based products consist primarily of calcium sulfate dihydrate or hemihydrate, formulated with additives such as glass fibers, starch, and foaming agents to achieve controlled density, fire resistance, and surface hardness for interior wall and ceiling systems. Board products lead volume due to standardized drywall installation in commercial and residential builds, while plaster segments retain margin strength in heritage restoration and artisanal finishing. Pre-mixed formulations represent the fastest-growing form category as jobsite labor costs push contractors toward ready-to-apply compounds that reduce mixing time and waste.
EPA emissions standards for synthetic gypsum sourcing shape supply availability in the United States, while REACH compliance in Europe restricts certain flame-retardant additives used in board facings. China's GB standards mandate formaldehyde limits in gypsum board adhesives, affecting import eligibility for non-compliant producers. Stakeholders must monitor regulatory divergence between synthetic and natural gypsum certification pathways as carbon-accounting rules tighten across major construction markets.
Market Dynamics
Synthetic gypsum from coal-plant flue-gas desulfurization is displacing natural ore across board manufacturing, compressing raw-material costs while tightening supply-chain dependency on power-utility partnerships.
Growth Catalysts
- India's fire-safety code tightening:Stricter enforcement of National Building Code provisions drives specification of fire-rated gypsum board in residential high-rises across Mumbai and Bangalore.
- Prefabricated wall systems:China's tier-one cities mandate modular construction targets that accelerate gypsum board integration into factory-built panels.
- Flue-gas desulfurization output:Rising synthetic gypsum availability from coal-plant scrubbers in the United States expands feedstock options for domestic manufacturers.
Market Restraints
- Natural gypsum ore volatility:Concentrated reserves in Spain and Thailand expose processors to shipping-cost spikes and geopolitical disruption.
- EPA emissions compliance:Mercury and heavy-metal testing requirements for synthetic gypsum create certification bottlenecks at U.S. import terminals.
- Light-gauge steel framing substitution:Cold-formed steel systems in commercial builds reduce gypsum board thickness specifications in seismic zones.
Strategic Opportunities
- Pre-mixed compound penetration:Ready-to-apply formulations capture share from site-mixed plaster in India's contractor market where labor costs surge.
- Moisture-resistant board specialization:Coastal construction in Japan's humid prefectures creates demand for enhanced-performance products with silicone additives.
- EU Green Deal carbon accounting:Embodied-carbon disclosure rules favor synthetic gypsum with documented lower extraction emissions versus natural ore.
Industry Challenges
- Skilled installer scarcity:Drywall finishing trades face attrition in Germany and France, delaying project timelines and elevating rework rates.
- Legacy inventory compatibility:New low-formaldehyde adhesive formulations from China's GB standard updates conflict with existing board stocks in distributor warehouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum-Based Products Market |
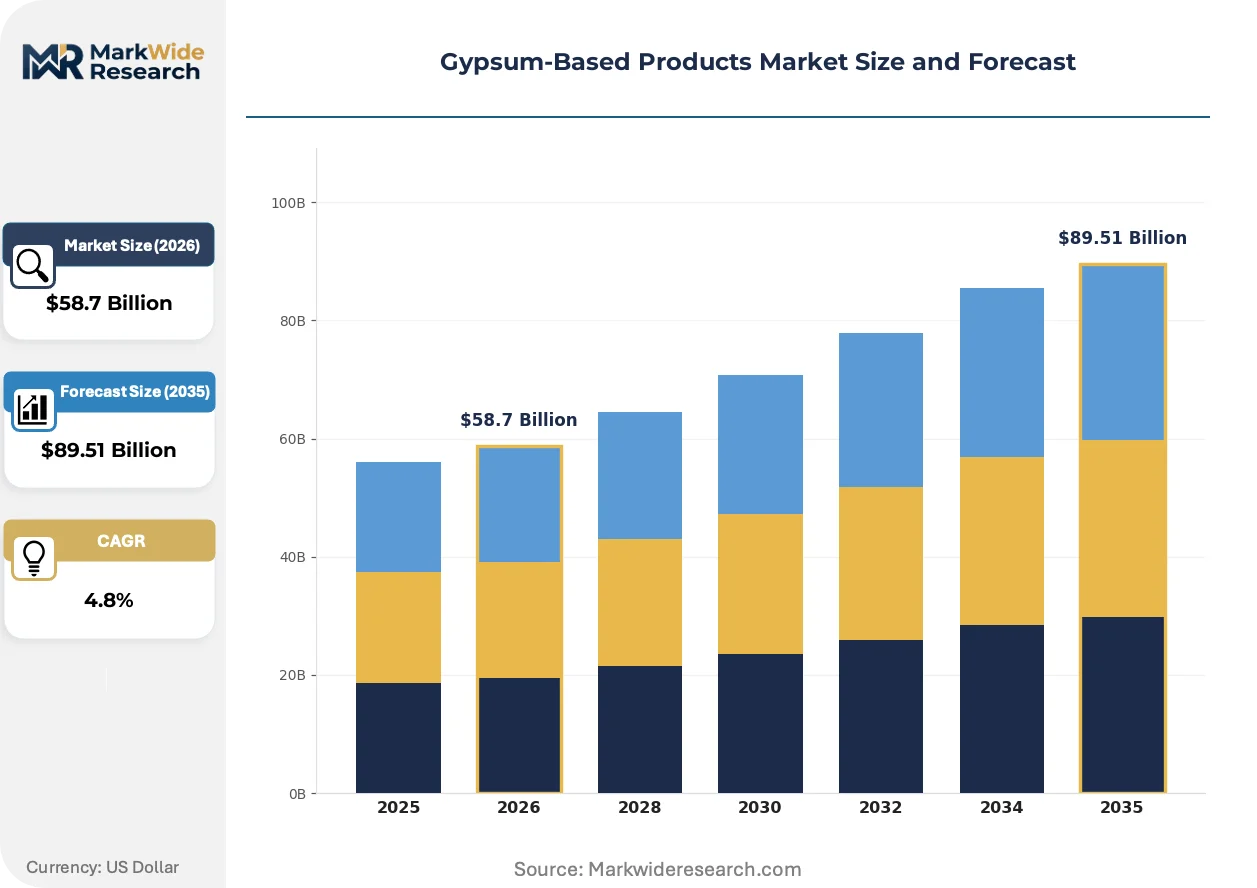
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plaster, Board, Powder, Blocks End Use Industry: Construction, Agriculture, Manufacturing, Decoration Form: Dry Mix, Pre-Mixed, Liquid, Granular Application: Wall Construction, Ceiling, Flooring, Insulation |
| Companies Covered | Knauf Group, Saint-Gobain, USG Corporation, National Gypsum Company, Georgia-Pacific LLC, Etex Group, Beijing New Building Materials Public Limited Company, American Gypsum Company LLC, Yoshino Gypsum Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum-Based Products Market Strategic Shifts
Digital procurement platforms and factory automation are compressing traditional distribution layers while material science advances unlock performance tiers previously unattainable with standard formulations.
Glass-fiber reinforced gypsum panels with enhanced flexural strength are rendering obsolete conventional paper-faced board in high-impact commercial corridors. Hospital and airport operators in the United States specify these composites for durability, accepting 15-20% material premiums to reduce lifecycle replacement cycles. The shift compresses margins for commodity board producers unable to retool extrusion lines.
REACH restrictions on halogenated flame retardants in Europe force reformulation of board facings and core additives. Manufacturers substitute intumescent mineral coatings, raising R&D spend but preserving access to German and French public construction tenders. Smaller exporters from Turkey and North Africa face exclusion until compliance certification completes.
Contractor purchasing through specialized B2B platforms now captures 30% of volume in China's tier-one cities, disintermediating traditional building-material distributors. These platforms bundle logistics, credit terms, and specification tools that small contractors previously accessed through regional wholesalers. The channel shift concentrates buyer power and pressures distributor margins in Shanghai and Beijing metropolitan zones.
Gypsum-Based Products Market Segmentation
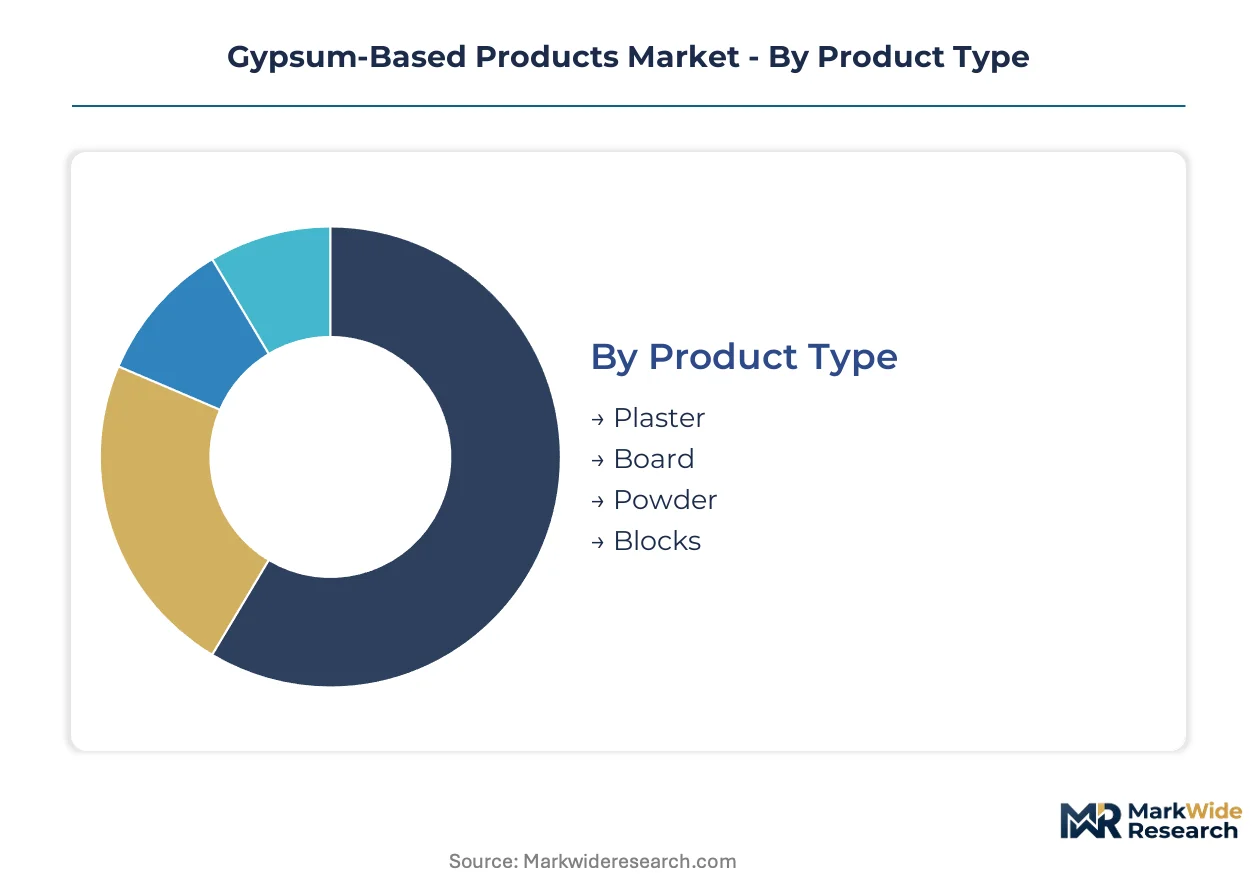
Segmentation in gypsum-based products reveals how formulation chemistry and application requirements split purchasing decisions across contractor workflows. Distinct technical specifications govern whether a project specifies board systems or wet-applied plaster, while form factors determine logistics costs and jobsite labor allocation.
Product Type:
Cost tier separates commodity board from specialized plaster and precision powder grades, with price sensitivity clustering around installation labor trade-offs.
- Board:Paper-faced or glass-fiber reinforced panels dominate residential and commercial drywall installation. Demand concentrates in China's tier-one cities where prefabricated wall systems integrate standardized board dimensions into factory-built modules.
- Plaster:Wet-applied calcium sulfate hemihydrate formulations serve heritage restoration and artisanal finishing where surface customization exceeds board capabilities. Heritage contractors in France and Italy specify lime-compatible gypsum plaster for monument conservation, accepting premium material costs to meet UNESCO-compatible restoration standards.
- Powder:Bagged hemihydrate serves site-mixed applications where contractors control set time through water addition ratios.
- Blocks:Pre-cast gypsum masonry units deliver rapid wall assembly in low-rise construction across India's residential high-rises.
Board commands the established base. The steepest expansion runs through Plaster.
End Use Industry:
Application maturity varies sharply, with construction absorbing volume while agriculture and manufacturing pursue niche performance specifications.
- Construction:Interior wall, ceiling, and flooring systems represent the core demand pool. Residential construction across India drives adoption amid stricter fire-safety codes in Mumbai and Bangalore high-rises.
- Agriculture:Soil amendment and livestock bedding applications leverage gypsum's calcium and sulfur content. Large-scale grain operations in the United States Midwest specify synthetic gypsum for sodic soil reclamation, responding to USDA conservation program incentives that offset material transport costs.
- Manufacturing:Ceramic mold making and industrial casting require high-purity gypsum with controlled porosity.
- Decoration:Ornamental cornices, ceiling roses, and architectural details serve premium residential and hospitality interiors.
Construction absorbs the volume base. The fastest volume gains emerge in Agriculture.
Form:
Customer type and jobsite labor economics determine whether contractors accept premium pricing for ready-to-apply convenience versus traditional site mixing.
- Pre-Mixed:Factory-blended compounds with controlled rheology eliminate on-site mixing variability. India's contractor market where labor costs surge captures the steepest uptake, as ready-to-apply formulations reduce mixing time and waste on compressed project schedules.
- Dry Mix:Bagged powder requiring water addition retains cost advantage in price-sensitive developing markets.
- Liquid:Pumpable slurries for specialized spray application in industrial coatings.
- Granular:Coarse particle sizing for agricultural soil amendment and specific industrial processes.
Dry Mix holds the established volume position. The steepest expansion trajectory belongs to Pre-Mixed.
Application:
Volume concentration and performance requirements diverge across building envelope positions, with wall systems dominating procurement spend.
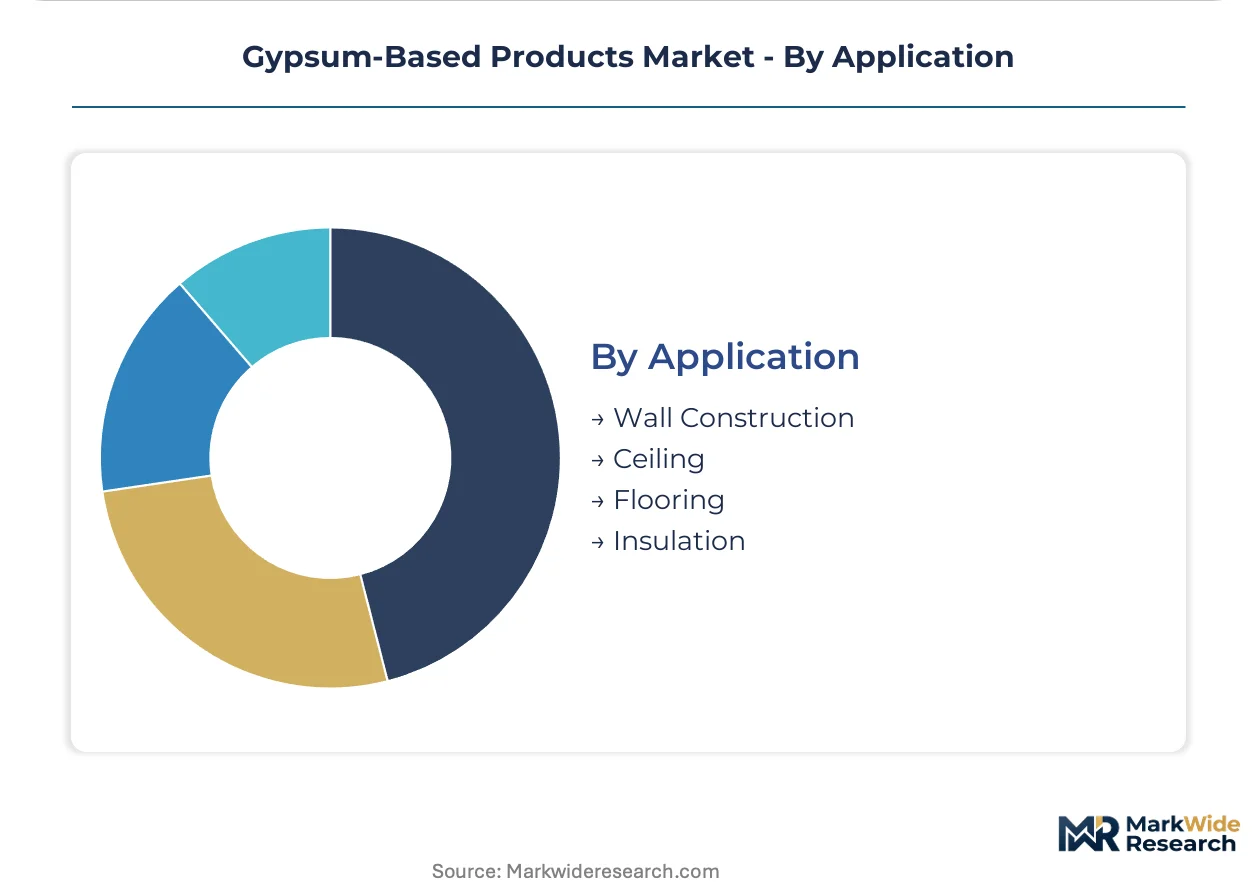
- Wall Construction:Vertical surface cladding in drywall or wet plaster represents the largest application category. Fire-rated board specifications in India's residential high-rises tighten compliance requirements under National Building Code enforcement.
- Ceiling:Suspended grid systems and direct-applied plaster finishes demand lightweight formulations with sag resistance. Hospital and airport operators in the United States specify glass-fiber reinforced gypsum panels for durability in high-impact commercial corridors.
- Flooring:Self-leveling underlayments and screed systems prepare substrates for finished floor coverings.
- Insulation:Foamed gypsum boards and cavity fill provide thermal and acoustic performance.
Wall Construction anchors procurement volume. The steepest expansion runs through Ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing power through captive synthetic gypsum supply, while Indian importers absorb volatility from Thai natural ore shipments. This asymmetry shapes procurement strategies across Asia-Pacific construction markets. European producers leverage REACH-compliant formulations to sustain premium positioning against lower-cost imports.
China
Prefabricated wall mandates in tier-one cities accelerate gypsum board integration into factory-built modules. GB standards enforce formaldehyde limits in board adhesives, filtering import eligibility for non-compliant producers. Shanghai and Beijing metropolitan zones concentrate demand through contractor purchasing platforms that bundle logistics and credit terms.
India
Residential high-rises in Mumbai and Bangalore drive fire-rated board specifications under National Building Code enforcement. BIS certification requirements tighten quality benchmarks for imported board products. Western Maharashtra and Karnataka states anchor manufacturing clusters where domestic producers scale capacity to meet coastal urban demand.
United States
Synthetic gypsum from coal-plant flue-gas desulfurization expands feedstock options for domestic board manufacturers. EPA mercury and heavy-metal testing requirements create certification bottlenecks at import terminals. Texas and southeastern states concentrate manufacturing capacity near utility partnerships and population growth corridors.
Germany
EU Green Deal embodied-carbon disclosure rules favor synthetic gypsum with documented lower extraction emissions versus natural ore. REACH restrictions on halogenated flame retardants force reformulation of board facings and core additives. North Rhine-Westphalia hosts dense plasterboard manufacturing networks serving Benelux and French export markets.
Japan
Moisture-resistant board demand surges in humid coastal prefectures where silicone-enhanced formulations command material premiums. METI energy-efficiency standards for building materials shape product development priorities. Kanto and Kansai regions concentrate specification activity among hospital and hospitality developers prioritizing durability.
Gypsum-Based Products Market Competitive Environment
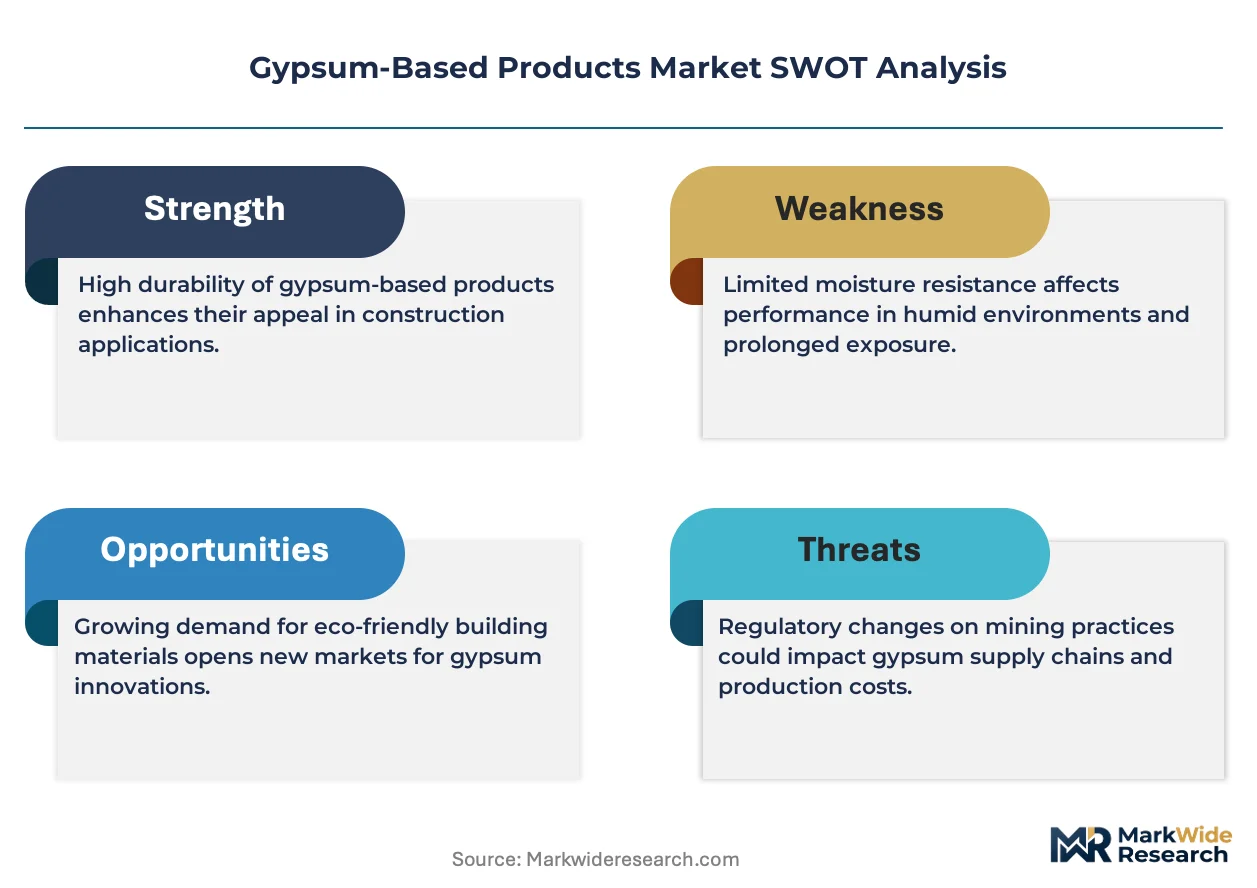
Vertically integrated multinationals and regional specialists split the market between scale economies and application-specific formulations. Three archetypes dominate: captive-reserve holders controlling upstream gypsum supply, technology licensors exporting process expertise, and moisture-performance specialists serving humid-climate niches. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure synthetic gypsum offtake agreements with power utilities.
Among European-based building-material conglomerates, Saint-Gobain and Knauf Group exemplify the integrated-reserve archetype through in-house production of plasterboard feedstock. Yoshino Gypsum Co., Ltd. occupies a position representing the performance-specialist tier with its focus on high-performance formulations. These three anchors illustrate how geographic origin and corporate structure map to distinct strategic positioning within the competitive set.
| Leading Market Players |
|---|
| Knauf Group |
| Saint-Gobain |
| USG Corporation |
| National Gypsum Company |
| Georgia-Pacific LLC |
| Etex Group |
| Beijing New Building Materials Public Limited Company |
| American Gypsum Company LLC |
| Yoshino Gypsum Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's dense plasterboard manufacturing networks concentrate synthetic gypsum processing capacity, translating captive feedstock access into pricing leverage over Benelux and French export markets dependent on spot natural ore purchases.
Pricing Analysis
The customization-premium spread separates commodity paper-faced board from glass-fiber reinforced panels and moisture-resistant formulations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and silicone additive content. Cost compression in standard board runs through synthetic gypsum oversupply from U.S. coal-plant scrubbers. Small contractors in India's tier-two cities exhibit highest price sensitivity, while hospital operators in Japan accept material premiums for durability specifications.
Supply Chain Analysis
Tariff exposure between China and select ASEAN markets dominates supply chain risk calculus for board adhesive formulations. Manufacturing draws from captive synthetic gypsum in the United States, natural ore reserves in Spain and Thailand, and flue-gas desulfurization partnerships with utilities. Single-source vulnerability concentrates in Thai natural ore shipments to Indian importers. Distribution runs through contractor purchasing platforms in Shanghai and Beijing that bundle logistics and credit terms, disintermediating traditional building-material wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contractor purchasing platforms in China's tier-one cities function as platform-economics inflection points, where bundled logistics and specification tools create interoperability standards that reshape downstream procurement workflows.
For Market Incumbents: Build captive synthetic gypsum offtake moats through long-term utility partnerships that lock in feedstock cost advantage against natural ore volatility. Secure BIS certification ahead of India's National Building Code enforcement tightening to filter import competition. Channel control through direct contractor platform relationships in Shanghai and Beijing metropolitan zones protects margin position from distributor disintermediation. For New Entrants and Emerging Players: India's western Maharashtra and Karnataka states present underpenetrated white-space for pre-mixed compound penetration as labor costs surge on compressed project schedules. Coastal prefectures in Japan offer specification entry through silicone-enhanced moisture-resistant formulations commanding material premiums. Partner with regional distributors holding legacy inventory relationships to bypass platform concentration in tier-one Chinese cities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors performance-specialist producers with documented REACH-compliant formulations and carbon-accounting transparency under EU Green Deal rules. Long-term viability rests on synthetic gypsum processing capabilities and regulatory certification depth rather than commodity scale. Watch for EPA mercury testing requirement expansions as inflection signal for U.S. import terminal bottlenecks reshaping competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Gypsum Offtake Agreement | Captive feedstock from coal-plant scrubbers compresses raw-material cost exposure versus natural ore spot markets. |
| Pre-Mixed Compound Manufacturing Scale-Up | Ready-to-apply formulations capture contractor share in India where labor cost inflation accelerates adoption. |
| Moisture-Resistant Board Specialization | Silicone-enhanced products command premiums in Japan's humid coastal prefectures with limited domestic competition. |
| REACH-Compliant Formulation Investment | Intumescent mineral coating substitution preserves access to German and French public construction tenders. |
| Contractor Platform Partnership | Direct relationships with Shanghai and Beijing purchasing platforms bypass distributor margin compression. |
Study Parameters
A spread of perspectives from plant managers at synthetic gypsum processing facilities, procurement leads at downstream board manufacturers, distribution channel partners, and technical R&D directors converged on the working assumptions. Secondary validation drew from EPA emissions filings, REACH compliance databases, Chinese customs trade data, and SEC 10-K disclosures from building-material conglomerates. Bottom-up capacity modeling and top-down construction spend allocation were triangulated against operating metrics.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry concentration, form factor convenience premium, and application performance requirements. CAGRs were derived from installed base replacement cycles and new construction penetration curves. Synthetic gypsum availability from coal-plant scrubber retrofits and prefabricated wall system integration rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-affiliated producers or sudden EPA mercury standard tightening would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Mining Explosives Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Pelletized Activated Carbon Market