
 Fatty Alcohol Market | 2026-2036
Fatty Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Alcohol Market Intelligence
Palm kernel oil is broadening its share of C12-C14 alcohol feedstock economics, displacing traditional petrochemical routes in surfactant manufacturing. BASF SE leverages integrated oleochemical complexes in Germany and Asia to sustain cost-advantaged supply positions. Kao Corporation anchors its competitive stance through captive fatty alcohol production for premium personal care lines. Emery Oleochemicals specializes in certified-sustainable grades that command preferential placement with European cosmetic producers.
Fatty alcohols are long-chain aliphatic alcohols with carbon chain lengths ranging from C6 to C22, typically produced via high-pressure hydrogenation of fatty acid methyl esters or natural oils, serving primarily as surfactant precursors and emulsion stabilizers across consumer and industrial formulations. Primary alcohols dominate volume throughput due to their direct use in sulfate and ethoxylate derivatives for detergent applications. Personal care products represent the fastest-expanding application segment as formulators replace petrochemical surfactants with plant-derived alternatives. Liquid form maintains the largest share of commercial transactions, though flake and powder grades gain traction in concentrated detergent powders and solid cosmetic bars.
REACH in Europe and EPA regulations in the United States govern biodegradability thresholds and volatile organic compound limits for surfactant-containing products, directly influencing fatty alcohol specifications and market access conditions. BIS standards in India and China's GB standards for detergent raw materials impose additional compositional requirements on imported alcohol fractions. Stakeholders must monitor feedstock certification schemes and regional bio-based content mandates to secure long-term contract positions.
Market Dynamics
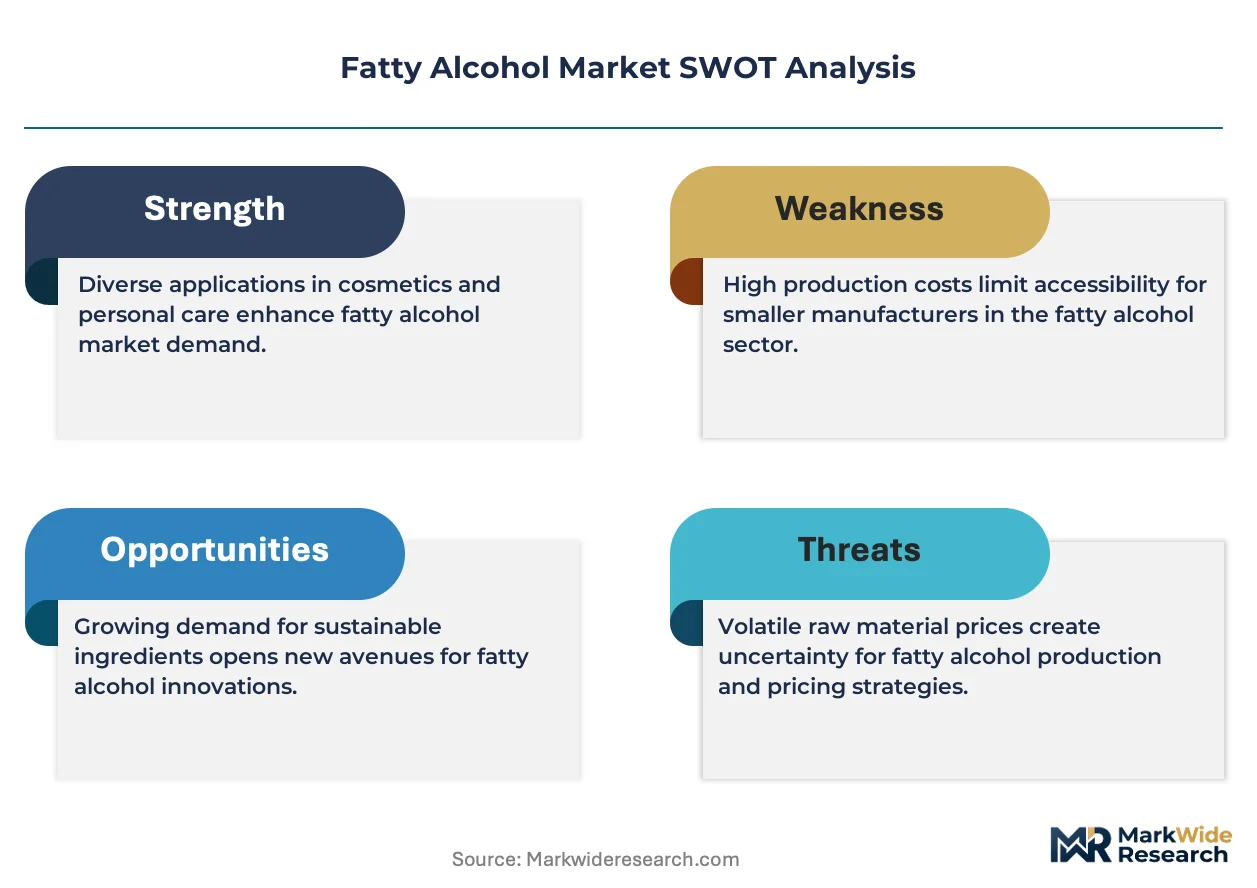
Palm kernel oil feedstock economics are compressing petrochemical routes in surfactant manufacturing, while REACH compliance in Europe tightens certification requirements for cosmetic-grade alcohols entering premium supply chains.
Growth Catalysts
- REACH biodegradability mandates:European formulators accelerate substitution of synthetic surfactants with plant-derived C12-C14 alcohols to meet ECHA thresholds for aquatic toxicity and biodegradation kinetics.
- Personal care clean-label pivot:Cosmetic brands specify RSPO-certified and mass-balance segregated fatty alcohols to satisfy consumer preference for traceable, naturally derived emulsifiers and conditioning agents.
- Southeast Asian oleochemical clustering:Malaysian and Indonesian integrated complexes capture export demand for detergent-grade alcohols through backward integration into palm kernel oil refining and methyl ester production.
Market Restraints
- Feedstock price volatility:Crude palm oil and palm kernel oil price swings on Bursa Malaysia Derivatives exchange transmit directly to fatty alcohol contract pricing, compressing blender margins.
- Supply concentration risk:Over half of global C12-C14 capacity sits within integrated Southeast Asian oleochemical complexes, creating geographic single-point vulnerability for European and North American buyers.
- Petrochemical route persistence:Shell higher olefins process and Sasol Fischer-Tropsch synthesis retain cost competitiveness for C16-C18 detergent alcohols in markets without bio-based procurement mandates.
Strategic Opportunities
- Indian personal care expansion:BIS standards for detergent raw materials and rising disposable incomes in tier-two cities create unmet demand for mid-tier sulfate and ethoxylate derivatives.
- EU Green Deal bio-content mandates:Corporate sustainability reporting directive and product environmental footprint rules reward suppliers with certified-sustainable supply chains and verified carbon intensity data.
- Solid cosmetic bar formulation:Flake and powder fatty alcohol grades penetrate concentrated detergent powders and waterless shampoo bars through modified crystallization and spray-drying investments.
Industry Challenges
- RSPO mass-balance certification timelines:Segregated supply chain documentation and third-party audit cycles delay contract eligibility for European cosmetic producers with 2025 sustainability targets.
- Hydrogenation catalyst replacement cycles:Copper-chromium and zinc oxide catalyst systems for fatty acid methyl ester reduction require scheduled turnaround maintenance that disrupts continuous production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Alcohol Market |
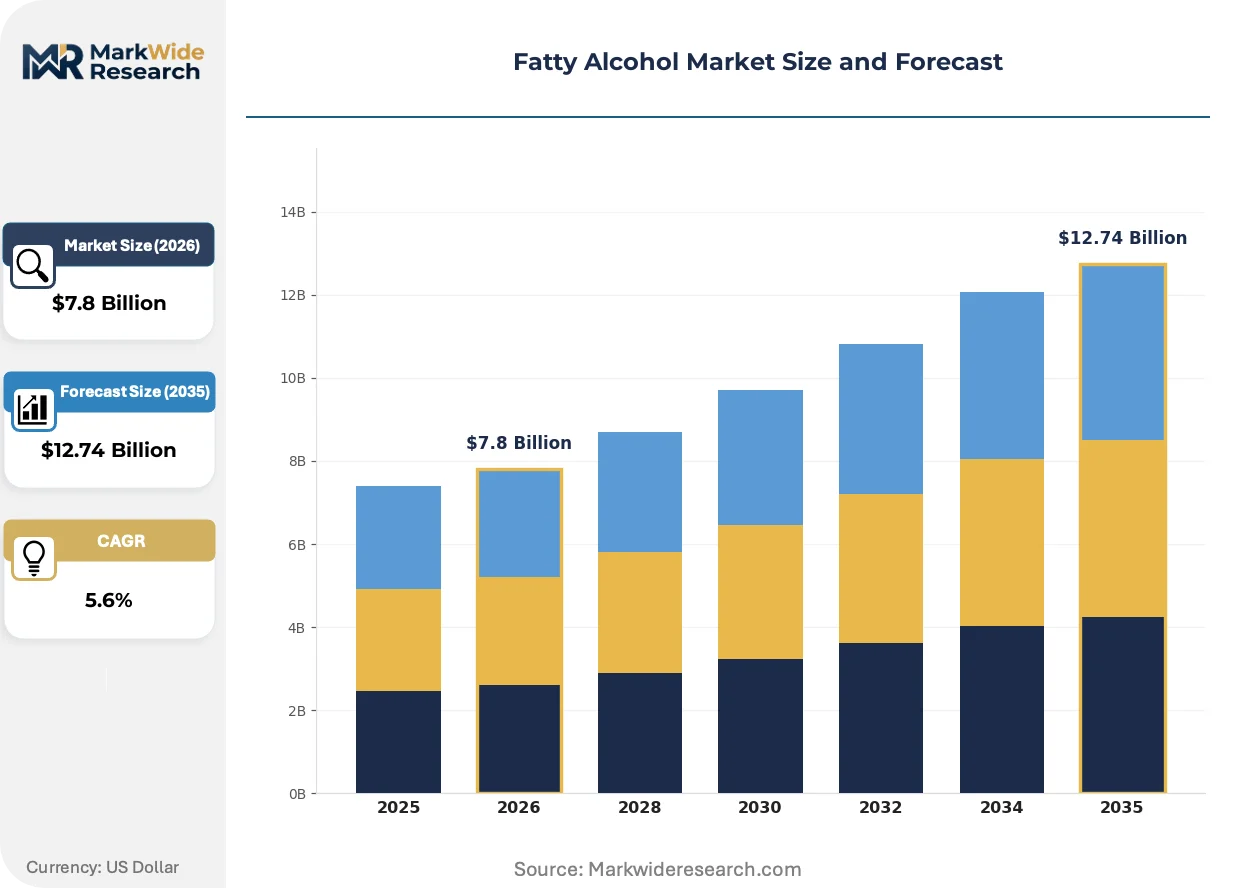
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Alcohols, Secondary Alcohols, Tertiary Alcohols, Polyalcohols Application: Detergents, Personal Care Products, Lubricants, Emulsifiers, Paints & Coatings End User: Manufacturing Plants, Cosmetic Producers, Chemical Companies, Textile Industries Form: Liquid, Powder, Flake, Granule, Paste |
| Companies Covered | Musim Mas Holdings, BASF SE, Wilmar International Ltd, Kao Corporation, Emery Oleochemicals, KLK OLEO, Godrej Industries, Evonik Industries, Sasol Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Alcohol Market Strategic Shifts & Innovations
Enzymatic transesterification and advanced hydrogenation catalysts are compressing carbon intensity metrics while REACH and EPA rules harden specifications for surfactant precursors.
Membrane filtration coupled with enzymatic interesterification is rewriting process economics for high-purity C12-C14 alcohol fractions. Specialty surfactant producers in Germany and the Netherlands adopt these systems to reduce energy inputs and eliminate solvent-based purification steps. The technology is enabling smaller-batch, certificate-of-origin-linked production for cosmetic-grade supply chains.
REACH Annex XVII restrictions on microplastics and EPA Safer Choice program criteria are tightening biodegradability windows for surfactant-containing products. Formulators must demonstrate 28-day biodegradation thresholds for fatty alcohol sulfates and ethoxylates to maintain shelf placement in European retail channels. Personal care brands with EU distribution are reformulating around shorter-chain alcohol derivatives that clear aquatic toxicity protocols.
Buyers are consolidating procurement around suppliers with integrated sustainability data platforms. Large personal care manufacturers in France and Germany now require blockchain-traceable feedstock documentation and Scope 3 carbon accounting for fatty alcohol contracts. This behavior concentrates contract volumes with oleochemical producers who have invested in digital supply chain infrastructure and third-party certification systems.
Fatty Alcohol Market Segmentation
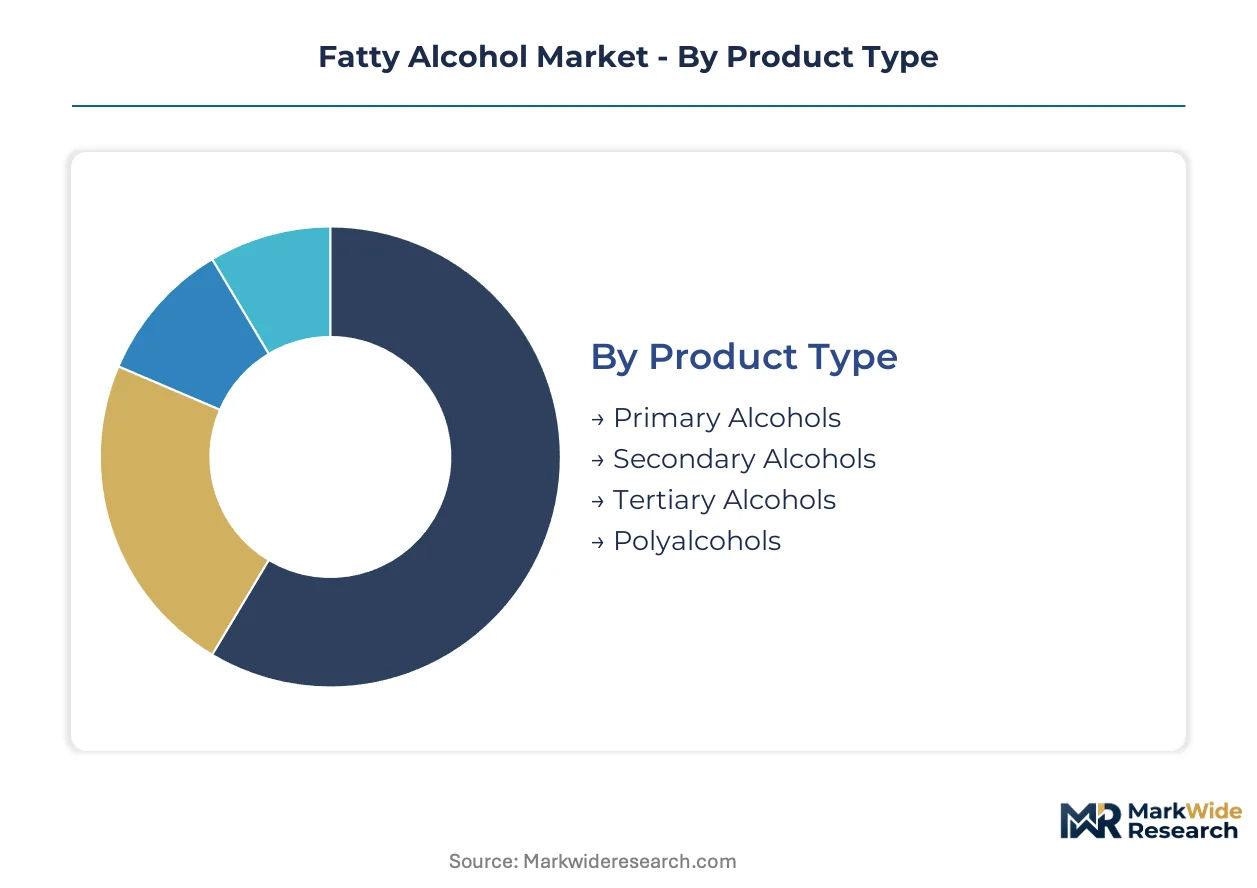
Certification requirements fragment the fatty alcohol landscape, with REACH-mandated biodegradability thresholds and RSPO chain-of-custody rules creating divergent compliance burdens across product grades. Segmentation strategy must align feedstock sourcing, hydrogenation intensity, and end-use specifications to capture premium contract positions.
Product Type:
REACH Annex XVII and EPA Safer Choice criteria impose distinct biodegradability windows on each alcohol class, with C12-C14 primary grades facing the strictest aquatic toxicity protocols for European cosmetic placement.
- Primary Alcohols:Straight-chain aliphatic alcohols produced via high-pressure hydrogenation of fatty acid methyl esters serve as direct precursors for sulfate and ethoxylate surfactants. Detergent manufacturers in Germany and the Netherlands concentrate procurement here to satisfy ECHA 28-day biodegradation mandates for household cleaning products.
- Secondary Alcohols:Branched structures derived from olefin hydroformylation offer superior wetting properties and lower foam profiles for industrial metalworking fluids. Japanese lubricant formulators specify these grades for precision machining applications where residue control is critical.
- Tertiary Alcohols:Highly branched C16-C18 variants command niche positions in specialty emulsion polymerization.
- Polyalcohols:Multi-hydroxyl compounds including fatty alcohol ethoxylates enable viscosity modification in personal care formulations.
Primary alcohols sit at the top of the volume ranking, with secondary alcohols climbing the fastest on industrial lubricant demand.
Application:
Cost tier stratification separates commodity detergent feedstocks from certificate-of-origin-linked cosmetic grades, with margin spreads widening on digital traceability investments.
- Detergents:C12-C14 alcohol sulfates and ethoxylates constitute the baseline surfactant workhorse for household and industrial cleaning formulations. Malaysian integrated producers capture volume contracts through backward integration into palm kernel oil refining, compressing delivered costs to European blender networks.
- Personal Care Products:RSPO-certified and mass-balance segregated alcohols serve as emulsifiers, conditioning agents, and viscosity modifiers in premium skincare and haircare lines. French and German cosmetic houses now require blockchain-traceable documentation and Scope 3 carbon accounting for contract eligibility.
- Lubricants:C16-C18 fractions provide boundary lubrication and corrosion inhibition in metalworking and automotive applications.
- Emulsifiers:Fatty alcohol-based systems stabilize oil-water interfaces in food processing and agrochemical formulations.
- Paints & Coatings:Coalescing agents and dispersant aids derived from C8-C10 alcohols modify film formation properties.
Detergents anchor the volume base, though personal care products expand most quickly on clean-label procurement pivots.
End User:
Customer type determines specification intensity, with cosmetic producers imposing the most stringent certification requirements and chemical companies optimizing for scale and feedstock flexibility.
- Manufacturing Plants:Integrated oleochemical complexes in Malaysia and Indonesia consume captive fatty alcohol output for downstream surfactant and ester production, capturing margin through continuous hydrogenation economics and methyl ester self-supply.
- Cosmetic Producers:Premium personal care manufacturers in France, Germany, and Switzerland specify segregated supply chains with third-party audit documentation, concentrating contract volumes with producers who have invested in digital traceability infrastructure.
- Chemical Companies:Merchant surfactant and specialty ester producers source standard-grade alcohols on spot and contract mechanisms indexed to Bursa Malaysia palm kernel oil futures.
- Textile Industries:Fiber lubricant and softener compounders in India and Bangladesh purchase C16-C18 derivatives for yarn processing and fabric finishing applications.
Manufacturing plants dominate throughput, with cosmetic producers gaining share fastest on sustainability-linked procurement mandates.
Form:
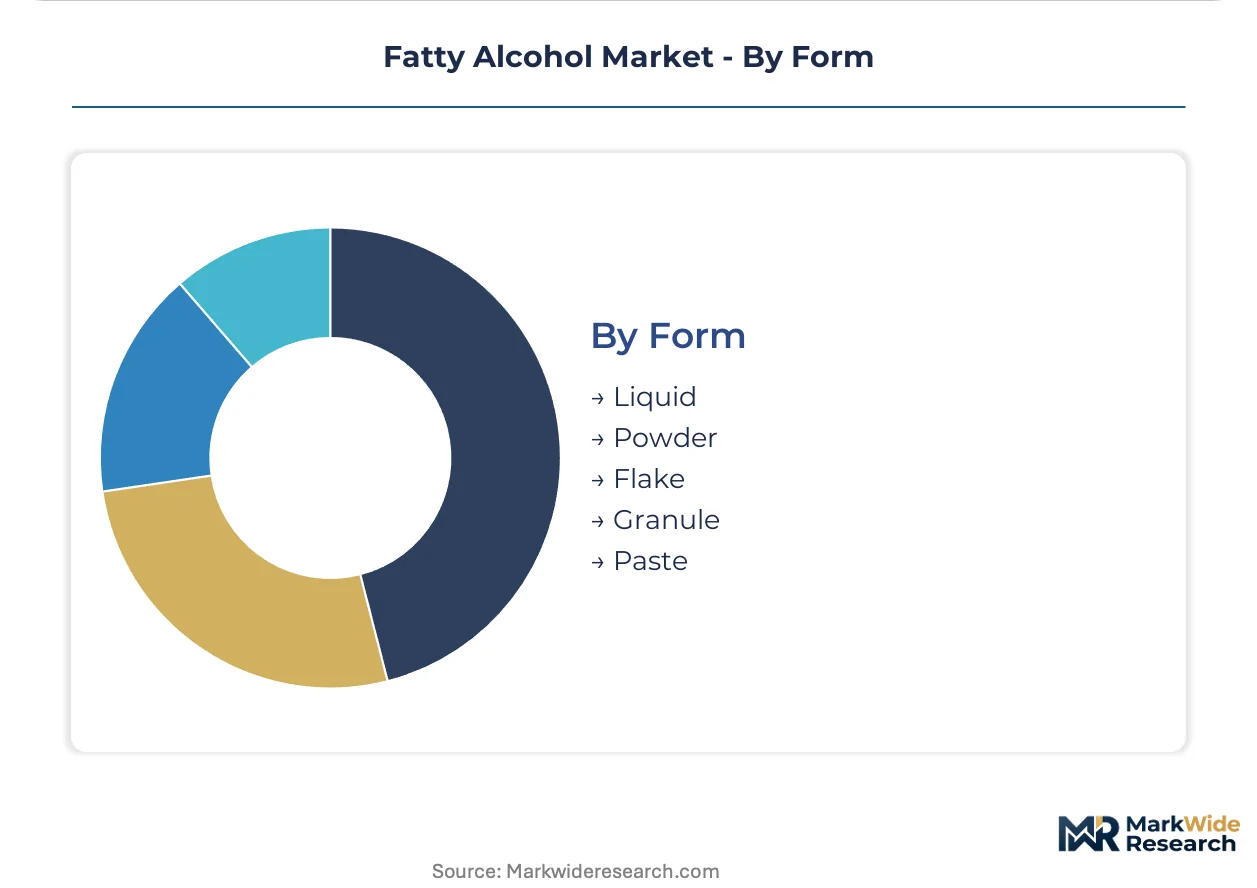
Supply concentration in Southeast Asian oleochemical corridors favors liquid bulk shipments, while solid forms require downstream crystallization and spray-drying investments closer to end-use markets.
- Liquid:Bulk tanker and drum shipments of molten or solvent-cut alcohols constitute the predominant commercial transaction format, enabling efficient handling through integrated oleochemical port terminals in Johor and Rotterdam.
- Powder:Spray-dried and micronized grades serve concentrated detergent formulations and waterless cosmetic bars where transportation economics favor reduced water content.
- Flake:Solidified and flaked products facilitate metering in solid bar manufacturing and powder blending operations.
- Granule:Agglomerated forms improve flow properties for automated handling in large-scale detergent powder plants.
- Paste:Semi-solid preparations combine fatty alcohols with emollients for direct cosmetic compounding.
Liquid form maintains the volume leadership position, with powder grades ascending fastest on concentrated and waterless formulation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian oleochemical corridors in Malaysia and Indonesia anchor global fatty alcohol production capacity through integrated palm kernel oil refining complexes. European formulators in Germany and the Netherlands drive premium-grade demand via REACH-mandated biodegradability thresholds. North American blenders balance petrochemical and bio-based sourcing under EPA Safer Choice criteria.
Malaysia
Johor Port integrated complexes process palm kernel oil into methyl esters for C12-C14 alcohol hydrogenation serving European detergent manufacturers. The Malaysian Palm Oil Board enforces MSPO certification standards that align with EU deforestation regulation compliance timelines. Pasir Gudang industrial zones concentrate backward-integrated surfactant production for export to Indian and Bangladeshi textile processors.
Indonesia
Medan and Surabaya oleochemical clusters absorb rising regional feedstock supply for detergent-grade alcohol export contracts. The Indonesian Sustainable Palm Oil (ISPO) mandate tightens traceability documentation for shipments entering EU Green Deal supply chains. Dumai refining corridors expand methyl ester capacity to capture displaced European demand from less certified origins.
Germany
Rhine-Ruhr chemical producers specify RSPO-segregated C12-C14 grades for sulfate derivatives in household cleaning formulations. ECHA REACH Annex XVII restrictions on aquatic toxicity drive substitution of synthetic surfactants with plant-derived alternatives. Ludwigshafen and Marl industrial sites maintain hydrogenation infrastructure for high-purity cosmetic-grade alcohol batches.
United States
Gulf Coast petrochemical complexes sustain Shell higher olefins process output for C16-C18 detergent alcohols in markets without bio-based procurement mandates. EPA Safer Choice program criteria influence surfactant precursor specifications for institutional cleaning product lines. Houston and Port Arthur terminals handle bulk liquid shipments to Midwest detergent powder plants.
India
Mumbai and Gujarat surfactant compounders expand sulfate and ethoxylate derivative capacity for tier-two city personal care demand. BIS detergent raw material standards impose compositional requirements on imported C12-C14 alcohol fractions. Ankleshwar chemical zones develop downstream emulsifier production for domestic cosmetic manufacturers.
Fatty Alcohol Market Key Industry Players
Global majors compete with regional champions across feedstock integration depth and certification infrastructure. The vendor base stratifies into three tiers: Southeast Asian palm oil-integrated producers, European specialty chemical houses with hydrogenation expertise, and Indian conglomerates with captive surfactant demand. Strategic moves center on RSPO mass-balance certification investments and flake/powder form capacity additions for solid cosmetic formulations.
Within the integrated oleochemical tier, Musim Mas Holdings and Wilmar International exemplify Southeast Asian producers with backward integration into palm kernel oil refining. BASF SE anchors the European specialty chemical archetype through Ludwigshafen-based hydrogenation assets. Kao Corporation occupies a position linking captive fatty alcohol production to premium personal care formulation expertise.
| Leading Market Players |
|---|
| Musim Mas Holdings |
| BASF SE |
| Wilmar International Ltd |
| Kao Corporation |
| Emery Oleochemicals |
| KLK OLEO |
| Godrej Industries |
| Evonik Industries |
| Sasol Ltd |
| Others |
Cost & Logistics Intelligence
Specialized hydrogenation engineers concentrated in Germany's Rhine-Ruhr chemical corridor command wage premiums that widen spreads between cosmetic-grade and detergent-grade fatty alcohol pricing tiers. Labor-cost differentials between European technical specialists and Southeast Asian plant operators reinforce three-tier pricing stratification across premium certified, standard industrial, and economy spot-market segments.
Pricing Analysis
Input-cost pass-through from Bursa Malaysia palm kernel oil futures directly governs contract pricing for C12-C14 alcohols, with integrated producers capturing margin through captive methyl ester supply. Pricing stratifies across RSPO-segregated cosmetic grades, mass-balance industrial grades, and uncertified spot volumes based on certification depth and carbon-accounting documentation. Cost compression in standard detergent grades is intensifying as Malaysian capacity expansions outpace European demand growth. Chemical companies purchasing on spot indices exhibit highest price sensitivity, while cosmetic producers accepting long-term contracts with sustainability premiums show lowest sensitivity.
Supply Chain Analysis
Certification gating through RSPO mass-balance and ISPO documentation requirements concentrates eligible supply among Malaysian and Indonesian integrated oleochemical complexes with audit infrastructure. Feedstock dependencies rest on crude palm oil, palm kernel oil, and hydrogen supply from regional petrochemical corridors. Single-source vulnerability emerges from geographic concentration of C12-C14 hydrogenation capacity within Johor and Pasir Gudang industrial zones. Distribution runs through bulk liquid terminals at Rotterdam and Houston, with flake and powder forms requiring downstream crystallization investments closer to European and North American formulation plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fatty alcohol market represents a late-cycle quality story as REACH-mandated biodegradability thresholds and EU Green Deal bio-content rules pivot procurement toward certified-sustainable supply chains with verified carbon intensity data.
For Market Incumbents: Extend certification infrastructure investments to capture EU Corporate Sustainability Reporting Directive contract eligibility before 2025 compliance deadlines. Deepen backward integration into palm kernel oil refining through Malaysian joint ventures to defend margin position against feedstock price volatility. Prioritize flake and powder capacity additions for solid cosmetic bar formulations where formulation trends concentrate growth. For New Entrants and Emerging Players: EU Green Deal bio-content mandates in Europe open a window for specialty producers with blockchain-traceable supply chains and Scope 3 carbon accounting platforms. Target Indian personal care expansion in tier-two cities where BIS standards create compliance barriers for uncertified imports but demand outpaces domestic supply. Pursue partnership routes with European cosmetic houses seeking segregated supply chain alternatives to concentrated Southeast Asian sourcing. For Investors and Strategic Acquirers: Integrated personal care conglomerates are the most active acquirer in this space, seeking captive fatty alcohol production to secure formulation supply and sustainability credentials. Five-to-ten-year viability hinges on certification infrastructure depth and geographic diversification beyond Malaysian supply concentration. Monitor RSPO mass-balance audit completion rates as inflection indicator for contract eligibility and premium pricing capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive palm kernel oil refining secures margin through methyl ester self-supply at Johor complexes. |
| RSPO Segregated Certification Investment | Third-party audit infrastructure unlocks European cosmetic contracts with blockchain-traceable documentation requirements. |
| Flake and Powder Capacity Expansion | Spray-drying investments capture solid cosmetic bar formulation demand from waterless shampoo trends. |
| Joint Venture in Indian Downstream | Gujarat surfactant compounding partnerships access tier-two city personal care demand under BIS standards. |
| Carbon Intensity Data Platform | Scope 3 accounting systems satisfy EU Corporate Sustainability Reporting Directive procurement preconditions. |
Research Approach
Coverage spans Southeast Asia, Europe, North America, and South Asia, with primary inputs from each region combined with secondary validation. Interviews with oleochemical plant managers, procurement leads at detergent and cosmetic manufacturers, RSPO certification auditors, and hydrogenation technology suppliers informed capacity and pricing assessments. Secondary sources include customs and trade flow data, ECHA REACH registration dossiers, BIS standard documentation, and SEC filings from listed oleochemical producers. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Granularity-level modeling operated at product type, application, end user, form, and regional production hub dimensions across the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by base-year value shares. Forecast inputs incorporated palm kernel oil price elasticity assumptions, REACH compliance timeline probabilities, and RSPO certification adoption curves by buyer archetype.
Revisions become necessary when feedstock price volatility exceeds historical bands, regulatory enforcement timelines shift, or hydrogenation catalyst technology disrupts production economics. Forecasts reflect documented assumptions about certification infrastructure buildout rates and bio-based procurement mandate expansion. A model refresh is warranted upon material change in EU deforestation regulation enforcement or Malaysian export policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
6 Hexanediol Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Acetic Ether Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Lime Sulfur Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Trimethylamine Market
Chemicals
5 Dinitroaniline Market
Chemicals
Diphosphate Market
Chemicals
Zinc Chemicals Market
Chemicals
Immunochemicals Market
Chemicals
Hydrophobing Agents Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Isopropanolamine Market