
 Alcohol Ethoxylates Market | 2026-2036
Alcohol Ethoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Ethoxylates Market Intelligence
REACH is recalibrating the cost-of-entry calculus for nonylphenol-based formulations across European manufacturing chains. BASF SE leverages backward integration into fatty alcohol feedstocks to secure margin stability under tightening ECHA substance restrictions. Croda International Plc specializes in bio-based ethoxylation pathways that navigate evolving EFSA safety thresholds for household applications. Shell Chemicals anchors its position through large-scale ethylene oxide infrastructure that sustains supply reliability for industrial cleaning compounders.
Alcohol ethoxylates are non-ionic surfactants produced by ethoxylation of fatty alcohols with ethylene oxide, yielding products with hydrophilic-lipophilic balance values typically between 10 and 16 for detergent-grade applications. These compounds function primarily as wetting agents, emulsifiers, and detergents across aqueous formulation systems. Linear Alcohol Ethoxylates dominate volume flows due to their superior biodegradability profile and compliance with stringent aquatic toxicity standards in Western formulations. Industrial Cleaning as an end-use channel represents the fastest-growing demand pool, driven by concentrated institutional sanitation protocols and food-processing hygiene mandates.
EPA toxicity assessments and OSHA workplace exposure limits jointly determine permissible ethoxylate concentrations in US industrial cleaner formulations. BIS certification requirements and CDSCO cosmetic ingredient standards in India are creating parallel compliance architectures for exporters and domestic producers alike. Stakeholders must monitor regulatory divergence between REACH-aligned jurisdictions and emerging economy standards to optimize regional product registration strategies.
Market Dynamics
REACH restrictions on Nonylphenol Ethoxylates are forcing European formulators to rebuild supply chains around Linear Alcohol Ethoxylates, redistributing competitive advantage toward feedstock-integrated producers and bio-based pathway specialists.
Growth Catalysts
- Industrial cleaning protocols:Institutional sanitation mandates in food processing and healthcare facilities are expanding concentrated surfactant consumption for hard-surface disinfection and degreasing applications.
- PLI scheme incentives:India's Production Linked Incentive program for specialty chemicals is accelerating domestic ethoxylation capacity expansion and import substitution for detergent-grade feedstocks.
- ECHA substance restrictions:REACH Annex XVII limitations on alkylphenol ethoxylates are redirecting formulation R&D investment toward biodegradable Linear Alcohol Ethoxylate alternatives with superior aquatic toxicity profiles.
Market Restraints
- Ethylene oxide supply concentration:Feedstock availability depends on a limited number of large-scale petrochemical complexes, creating vulnerability to unplanned outages and price volatility in key producing regions.
- Fatty alcohol cost structure:Natural oil and fat price fluctuations directly compress margins for ethoxylate producers lacking backward integration into oleochemical feedstocks.
- Substitution by sugar-based surfactants:Alkyl polyglucosides and other carbohydrate-derived alternatives are capturing share in personal care and household applications where mildness claims command premium positioning.
Strategic Opportunities
- Bio-based ethoxylation pathways:Renewable carbon feedstocks and enzymatic processing methods are opening differentiation channels for producers targeting EFSA safety thresholds and EU Green Deal compliance.
- Indian domestic market expansion:BIS certification requirements and CDSCO cosmetic standards are creating captive demand for locally manufactured pharmaceutical-grade and personal-care ethoxylates.
- Food-processing hygiene mandates:HACCP-aligned sanitation protocols in meat, dairy, and beverage processing are institutionalizing recurring demand for high-purity industrial cleaning surfactants with documented residue profiles.
Industry Challenges
- Multi-jurisdiction registration complexity:Divergent data requirements between REACH-aligned systems, EPA toxicity assessments, and emerging economy standards extend product launch timelines and inflate compliance overhead.
- Ethoxylation reactor capex intensity:Pressure-rated ethylene oxide handling infrastructure and explosion-proof processing environments demand substantial capital deployment for capacity expansion or greenfield projects.
- Specialized process engineering talent:Scarce expertise in alkoxylation kinetics, narrow-range ethoxylation control, and batch consistency optimization constrains operational scaling for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Ethoxylates Market |
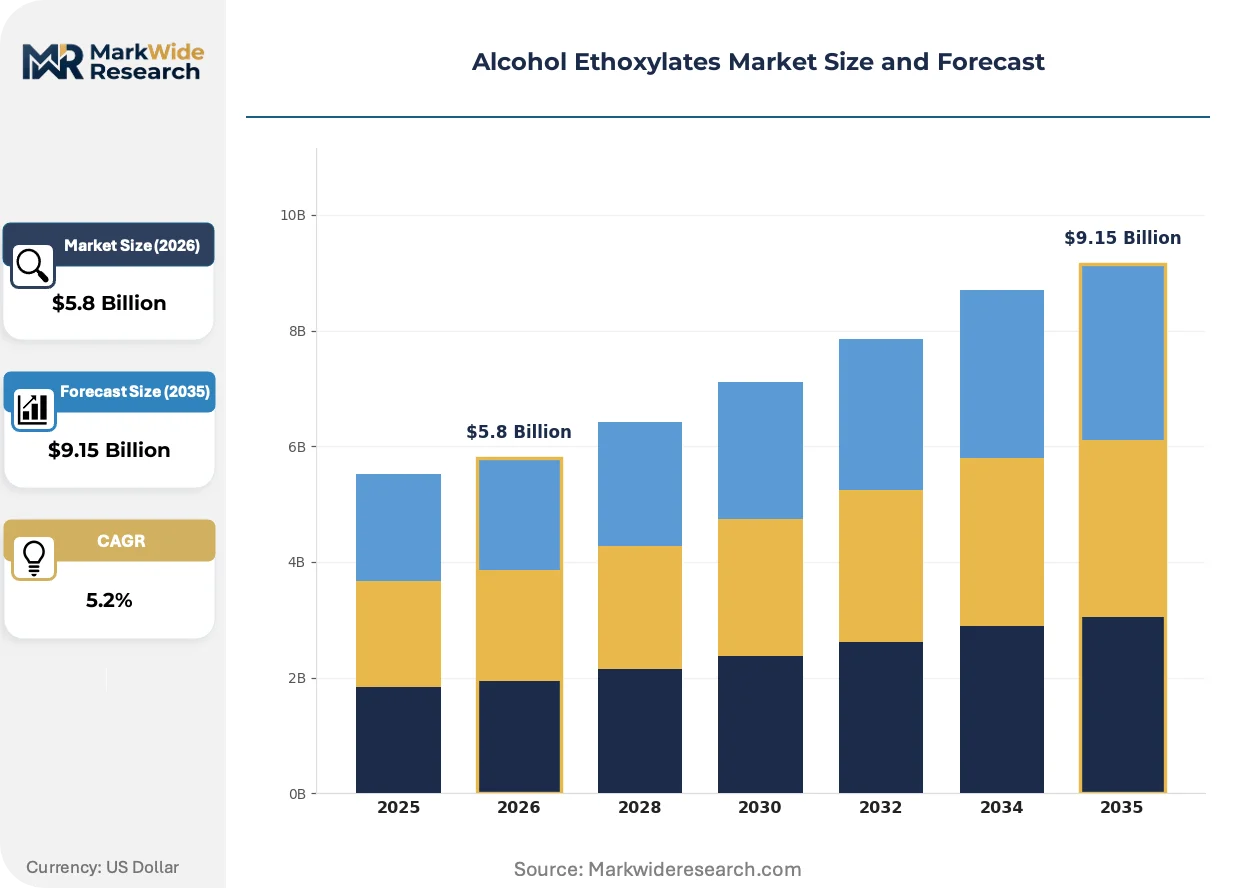
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.15 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Alcohol Ethoxylates, Branched Alcohol Ethoxylates, Nonylphenol Ethoxylates, Tridecyl Ethoxylates End User: Household Cleaning, Personal Care, Industrial Cleaning, Textile Manufacturing Application: Surfactants, Emulsifiers, Solubilizers, Dispersants Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | BASF SE, Clariant, Dow, Huntsman Corporation, Sasol Ltd, Stepan Company, Croda International Plc, Shell Chemicals, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Ethoxylates Market Strategic Shifts & Innovations
Formulation science is pivoting toward bio-derived and precision-ethoxylated architectures as regulatory toxicity thresholds tighten and end-users demand documented environmental fate data alongside functional performance.
Narrow-range ethoxylation technology is overtaking conventional broad-range processes in premium detergent and personal care segments. This controlled-addition method yields tighter ethylene oxide distribution curves, improving surfactant performance consistency and reducing unreacted alcohol residuals. Multinational household product manufacturers are adopting these grades for concentrated liquid formulations, compressing the competitive position of standard-range producers in Western European and North American markets.
EU Green Deal chemical sustainability criteria are accelerating substance-level transparency requirements across formulation supply chains. ECHA SCIP database obligations and impending digital product passport mandates are forcing ethoxylate suppliers to invest in chain-of-custody documentation and lifecycle assessment capabilities. Industrial cleaning compounders serving automotive and electronics manufacturing are prioritizing suppliers with verified renewable carbon content and third-party biodegradability certifications.
Buyer consolidation among institutional cleaning service providers and food-processing contractors is compressing procurement cycles and unbundling technical service components from material supply contracts. Large facility management groups are centralizing surfactant purchasing through preferred supplier frameworks with mandated ESG disclosure requirements, displacing traditional distributor networks in Germany, France, and the United Kingdom. This concentration is most visible in hospital and airport sanitation contracts where multi-year framework agreements now specify minimum bio-based content thresholds.
Alcohol Ethoxylates Market Segmentation
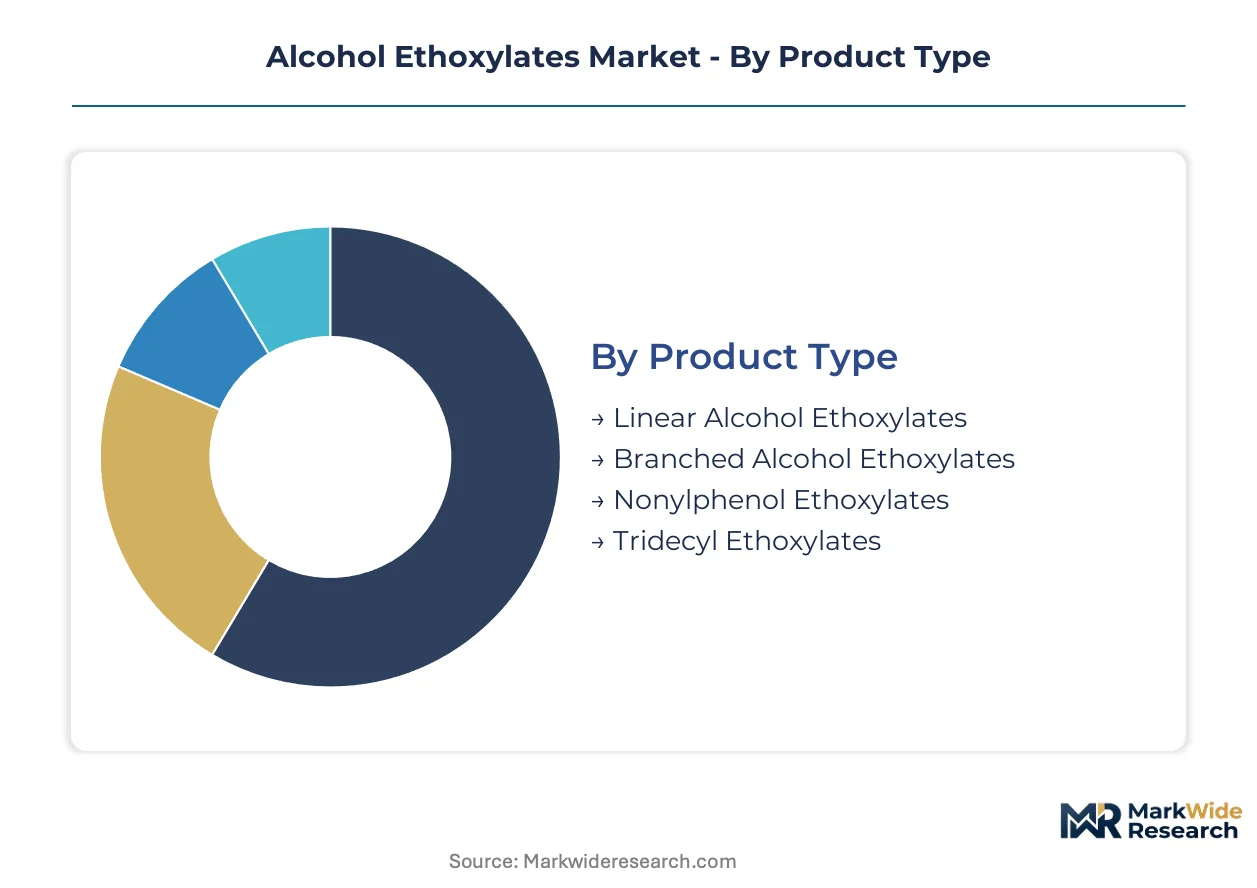
Segmentation in alcohol ethoxylates reveals how formulation requirements diverge across regulatory environments and end-use performance thresholds. Product architecture, application intensity, and channel economics each reshape procurement patterns for compounders and institutional buyers.
Product Type:
Integration depth varies sharply: Linear Alcohol Ethoxylates function as standalone surfactants in detergent formulations, while Nonylphenol Ethoxylates persist primarily as embedded intermediates in legacy industrial systems requiring reformulation investment to displace.
- Linear Alcohol Ethoxylates:These C12-C18 fatty alcohol derivatives with 3-12 moles ethylene oxide deliver HLB values between 10-16 for broad detergent compatibility. REACH Annex XVII restrictions on alkylphenol alternatives are concentrating demand in German and French household cleaning compounders seeking documented aquatic biodegradability.
- Branched Alcohol Ethoxylates:Guerbet alcohol structures with methyl branching provide superior wetting kinetics and low-temperature solubility. Personal care formulators in the United States leverage these grades for premium facial cleanser applications where rapid rinse-off commands formulation priority.
- Nonylphenol Ethoxylates:Legacy alkylphenol structures face phased withdrawal across ECHA-regulated jurisdictions.
- Tridecyl Ethoxylates:C13 iso-alcohol bases serve defoaming and metalworking fluid segments.
Linear Alcohol Ethoxylates lead volumes today; Branched Alcohol Ethoxylates are gaining share fastest.
End User:
Cost tier stratification separates commodity surfactant buyers from specialty formulation houses: institutional sanitation contracts run on specification-grade volumes, while personal care channels absorb premium-priced narrow-range ethoxylates with certified residue profiles.
- Industrial Cleaning:Concentrated hard-surface degreasers and food-processing sanitizers consume high-active ethoxylate blends. HACCP-aligned meat and dairy processors in India are institutionalizing recurring procurement through BIS-certified domestic suppliers under PLI scheme incentives.
- Household Cleaning:Liquid laundry detergents and all-purpose sprays represent volume anchors. EPA Safer Choice program requirements and state-level disclosure mandates in California and New York are filtering supplier qualification toward producers with verified ethoxylate chain-of-custody documentation.
- Personal Care:Mildness-critical applications absorb premium narrow-range grades with tight unreacted alcohol specifications.
- Textile Manufacturing:Scouring and wet-processing auxiliaries demand emulsifier stability across variable water hardness.
Industrial Cleaning commands the steepest expansion trajectory; Personal Care sustains the highest margin realization per kilogram.
Application:
Volume concentration clusters in surfactant functions, while margin capture shifts toward emulsifier and solubilizer segments where technical service bundling persists.
- Surfactants:Wetting, detergency, and foaming functions dominate tonnage flows. Institutional cleaning service providers in the United Kingdom and Germany are consolidating procurement through framework agreements specifying minimum bio-based content thresholds.
- Emulsifiers:Oil-in-water stabilization for agrochemical and cosmetic formulations requires narrow-range ethoxylation control. Croda International and BASF SE compete on verified renewable carbon content for EU Green Deal compliance.
- Solubilizers:Fragrance and active ingredient solubilization in aqueous systems.
- Dispersants:Pigment and filler stabilization in coatings and construction.
Surfactant applications anchor current volumes; Emulsifier functions are expanding most quickly in agrochemical and cosmetic compounding.
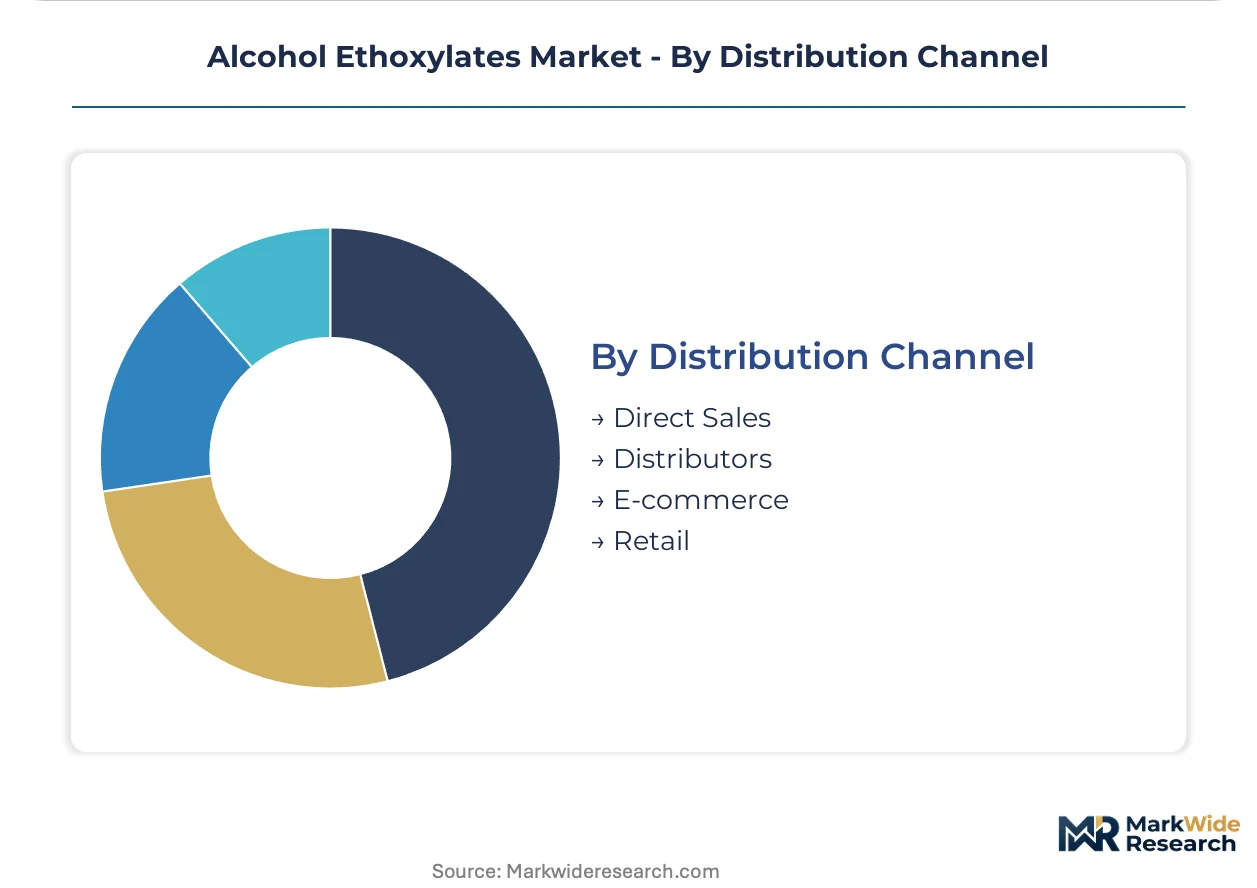
Distribution Channel:
Customer type fragmentation separates bulk institutional buyers from fragmented small-lot purchasers: direct sales capture specification-intensive accounts, while distributor networks and digital platforms serve spot buyers with standardized grades.
- Direct Sales:Multi-year supply agreements with industrial compounders and household product manufacturers anchor capacity planning. Large facility management groups in France and Germany now mandate ESG disclosure requirements that distributor intermediaries cannot satisfy.
- Distributors:Regional chemical distributors maintain inventory positions for mid-tier formulators lacking tank farm infrastructure.
- E-commerce:Digital platforms serve small-batch personal care startups and research-scale purchasers.
- Retail:Consumer-facing channels for DIY and specialty cleaning segments.
Direct Sales channels dominate value capture; E-commerce is climbing the fastest among emerging personal care formulators and regional compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent concentrates in Germany's Ruhr industrial corridor and India's Gujarat chemical belt, anchoring ethoxylation capacity expansion in both mature and emerging manufacturing ecosystems.
Germany
Industrial cleaning compounders in North Rhine-Westphalia drive specification-grade Linear Alcohol Ethoxylate consumption for food-processing sanitation. REACH Annex XVII restrictions on alkylphenol alternatives redirect formulation R&D toward biodegradable surfactant architectures. BASF SE's Ludwigshafen complex maintains backward integration into fatty alcohol feedstocks, securing margin stability under tightening ECHA substance evaluations.
United States
Institutional facility management groups consolidate surfactant procurement through multi-year framework agreements with mandated ESG disclosure requirements. EPA Safer Choice program requirements and California state-level disclosure mandates filter supplier qualification toward producers with verified chain-of-custody documentation. Gulf Coast petrochemical infrastructure sustains ethylene oxide supply reliability for industrial cleaning compounders serving automotive and electronics manufacturing clusters.
India
HACCP-aligned meat and dairy processors in Maharashtra and Gujarat institutionalize recurring procurement of BIS-certified domestic ethoxylates. The PLI scheme for specialty chemicals accelerates greenfield ethoxylation capacity and import substitution for detergent-grade feedstocks. CDSCO cosmetic ingredient standards create parallel compliance architectures for pharmaceutical-grade and personal-care surfactant manufacturers in the Delhi-Mumbai industrial corridor.
China
Yangtze River Delta detergent manufacturers absorb volume flows of standard-range ethoxylates for liquid laundry and all-purpose cleaning formulations. GB standards on industrial chemical safety and environmental discharge protocols reshape production cost structures for surfactant compounders. Zhejiang and Jiangsu province chemical parks concentrate narrow-range ethoxylation investments targeting premium personal care export markets.
France
Large hospital and airport sanitation contractors in Île-de-France centralize purchasing through preferred supplier frameworks specifying minimum bio-based content thresholds. EU Green Deal chemical sustainability criteria force ethoxylate suppliers to invest in chain-of-custody documentation and lifecycle assessment capabilities. ECHA SCIP database obligations drive substance-level transparency investments across formulation supply chains serving automotive manufacturing in the Grand Est region.
Alcohol Ethoxylates Market Key Industry Players
The competitive structure tilts toward feedstock-integrated petrochemical majors and bio-based pathway specialists. Tier-one positions concentrate among producers with captive ethylene oxide infrastructure or backward integration into oleochemical feedstocks. Mid-tier compounders compete on regional certification expertise and narrow-range ethoxylation technical service. Dominant competitive moves include capacity expansion in India under PLI incentives and portfolio diversification toward renewable carbon content verification for EU Green Deal compliance.
Within the integrated petrochemical tier, BASF SE and Shell Chemicals anchor positions through large-scale ethylene oxide infrastructure and fatty alcohol supply chain control. Croda International Plc exemplifies the bio-based specialization archetype, occupying a position defined by enzymatic processing methods and renewable carbon feedstock pathways. These three entities collectively represent the strategic spectrum spanning conventional petrochemical scale, oleochemical integration depth, and biotechnological differentiation.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| Dow |
| Huntsman Corporation |
| Sasol Ltd |
| Stepan Company |
| Croda International Plc |
| Shell Chemicals |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
EU Green Deal chemical sustainability criteria gate qualified supply access and premium-tier pricing power for ethoxylate producers serving Western European institutional cleaning compounders. Large facility management groups in France and Germany now mandate ESG disclosure thresholds that distributor intermediaries cannot satisfy, compressing procurement into direct supplier relationships with documented renewable carbon content.
Pricing Analysis
The bundled-vs-unbundled service split separates specification-grade Linear Alcohol Ethoxylate contracts from commodity spot transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with narrow-range ethoxylates commanding formulation service premiums. Cost compression in standard-range grades is intensifying because buyer consolidation among institutional cleaning service providers unbundles technical support from material supply. Mid-tier compounders exhibit highest price sensitivity, while personal care formulators absorbing certified residue profiles show least.
Supply Chain Analysis
Dual-sourcing requirements from large facility management groups mandate multi-supplier qualification for ethylene oxide and fatty alcohol inputs. Supply concentrates in Germany, India, and the United States for ethoxylation capacity, with feedstock sourcing drawing from Malaysian and Indonesian oleochemical complexes. Raw material dependencies rest on ethylene oxide, natural oil and fat derivatives, and specialized catalyst systems. Single-source vulnerability persists around large-scale petrochemical complexes. Distribution runs through direct sales for institutional accounts and regional chemical distributors for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI scheme subsidies and BIS certification requirements create 15-20% cost advantages versus REACH-aligned European production for detergent-grade ethoxylates.
For Market Incumbents: Deploy backward integration into fatty alcohol feedstocks to secure margin stability under tightening ECHA substance evaluations. BASF SE's Ludwigshafen complex exemplifies this lever, capturing cost advantages as natural oil price fluctuations compress margins for non-integrated competitors. Capacity addition in Gujarat's chemical belt under India's PLI incentives defends position against emerging domestic producers. For New Entrants and Emerging Players: REACH Annex XVII restrictions in Europe open a window for bio-based ethoxylation pathway specialists targeting EFSA safety thresholds and EU Green Deal compliance. White-space targets cluster in pharmaceutical-grade ethoxylates under CDSCO standards and narrow-range grades for premium personal care. A technical service bundling go-to-market angle penetrates mid-tier compounders displaced by buyer consolidation. For Investors and Strategic Acquirers: Roll-up economics work for regional certification specialists because multi-jurisdiction registration complexity extends product launch timelines and inflates compliance overhead for fragmented mid-tier producers. Long-term viability centers on five-to-ten year windows for producers with verified renewable carbon content and chain-of-custody documentation capabilities. The signal to watch is BIS certification acceleration under India's PLI scheme as inflection indicator for import substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohols | BASF SE's captive supply of oleochemical feedstocks secures margin stability against natural oil volatility. |
| Greenfield Ethoxylation Capacity in India | PLI scheme incentives accelerate domestic production substitution for detergent-grade surfactant imports. |
| Narrow-Range Ethoxylation Technology Investment | Croda International's precision processing captures premium personal care demand with tight unreacted alcohol specifications. |
| Long-Term Supply Agreement with Institutional Cleaners | Multi-year frameworks with French hospital contractors lock in volume through mandated bio-based content thresholds. |
| Joint Venture for Bio-Based Feedstock Pathways | Enzymatic processing partnerships navigate evolving EFSA safety thresholds for EU Green Deal compliance. |
Research Approach
Bottom-up industrial cleaning consumption modeling reconciled against top-down ethoxylation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at European and Indian ethoxylation facilities, procurement leads at institutional cleaning service providers, distribution channel partners in Germany and France, and technical R&D directors at specialty chemical compounders were cross-validated against secondary sources including customs and trade data from Indian DGFT and European Eurostat, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical producers.
Input-output matrix framing connects ethylene oxide and fatty alcohol feedstock availability to end-use demand across detergent-grade, personal care, and industrial cleaning segments. Segmentation dimensions modeled include product architecture (Linear Alcohol Ethoxylates, Branched Alcohol Ethoxylates, Nonylphenol Ethoxylates), end-use intensity (Industrial Cleaning, Household Cleaning, Personal Care), and regional production hub clustering. CAGRs were derived through regression analysis of historical consumption patterns and projected formulation substitution rates across the analysis window, with ethoxylation reactor utilization rates and REACH regulatory phase-out timelines as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ethylene oxide supply disruption scenarios or accelerated ECHA substance restrictions. Deviation in India's PLI scheme implementation pace or BIS certification enforcement would shift the outlook materially for import substitution trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Cetyl Esters Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Squalane Market
Oleochemicals
Esters Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Mexico Glycerine Market