
 Phenoxycycloposphazene Market | 2026-2036
Phenoxycycloposphazene Market Size, Share, and Industry Trends Forecast 2026-2036
Phenoxycycloposphazene Market Outlook
Electronics end-use demand is shifting toward higher-specification flame-retardant formulations in PCB laminates and semiconductor encapsulants. Ozeki CO leverages its Japanese manufacturing base to supply precision-grade phenoxycycloposphazene for electronics clients requiring low-ion-content material. Jiangsu Yoke Technology anchors domestic Chinese supply through integrated phosphorus chemistry operations in Jiangsu Province. DuPont competes on technology leadership in halogen-free flame-retardant systems for aerospace and automotive wire coatings.
Phenoxycycloposphazene is a cyclic phosphazene compound bearing phenoxy substituents, typically synthesized through nucleophilic substitution of hexachlorocyclotriphosphazene with sodium phenoxide, yielding a white crystalline solid with thermal decomposition thresholds above 300°C that functions as a halogen-free flame retardant and thermal stabilizer in polymers. Powder formulations dominate volume throughput due to easier compounding integration with epoxy resins and polyolefins, while liquid grades command margin premiums in electronics potting applications where viscosity control proves critical. The flame-retardant application segment leads absolute consumption, though adhesives and sealants represent the fastest-growing outlet as construction and automotive OEMs adopt phosphorus-based systems to meet evolving fire codes.
China's Ministry of Emergency Management enforces GB 8624 building material fire classification standards that restrict halogenated retardants in public infrastructure, directly expanding addressable demand for phenoxycycloposphazene alternatives. Japan's METI maintains JIS standards for electronic equipment flame resistance that OEMs such as Mitsubishi Chemical must satisfy for domestic and export sales. REACH registration requirements in Europe impose data and testing burdens on importers, shaping market access economics for Chinese producers like Zhangjiagang Xinyi Chemical and Zibo Lanyan Chemical. Stakeholders must monitor regulatory divergence between China's GB standard evolution, Japan's electronics-specific JIS updates, and potential EU restriction proposals under the CLP regulation to anticipate product formulation investments and geographic sourcing shifts.
Market Dynamics
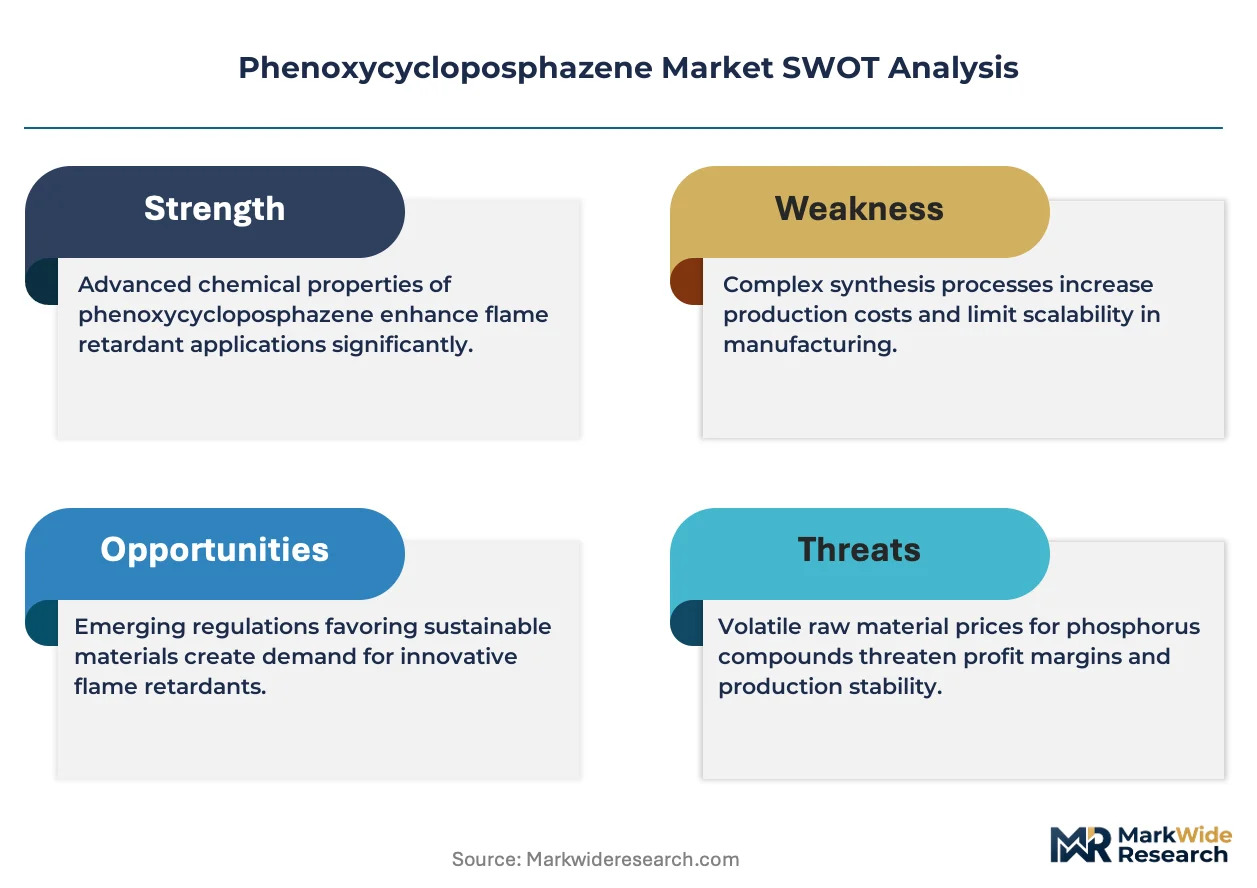
Electronics OEM procurement of halogen-free flame retardants is compressing qualification timelines from 18 months to 8 months, forcing suppliers to front-load toxicology dossiers and thermal performance data ahead of formal engagement.
Growth Catalysts
- GB 8624 Building Material Classification:China's Ministry of Emergency Management restricts halogenated retardants in public infrastructure, expanding specification windows for phosphorus-based alternatives in curtain walls and electrical conduit.
- Semiconductor Encapsulant Demand:Advanced packaging architectures for automotive power modules require thermal stability above 280°C, positioning phenoxycycloposphazene as a drop-in replacement for brominated epoxy hardeners.
- Jiangsu Specialty Chemical Cluster:Concentrated phosphorus derivative capacity around Zhangjiagang and Taizhou reduces inland logistics costs for electronics manufacturers in the Yangtze River Delta.
Market Restraints
- Hexachlorocyclotriphosphazene Feedstock Volatility:Chlorinated phosphazene precursor supply concentrates with three Chinese producers, exposing compounders to 40-60 day order-to-delivery cycles during Q4 maintenance turnarounds.
- REACH Data Cost Burden:ECHA registration requirements for substances above 100 tonnes annually impose €300,000-500,000 toxicology and ecotoxicology testing costs, filtering out sub-scale exporters from European market access.
- Magnesium Hydroxide Substitution:Mining and processing scale economies in Qinghai Province position mineral flame retardants as cost-competitive alternatives in polyolefin wire and cable applications below 200°C service temperature.
Strategic Opportunities
- India Electronics Manufacturing Incentive Scheme:PLI scheme disbursements for semiconductor and component assembly create first-mover advantage for halogen-free retardant qualification with Dixon Technologies and Aequs.
- Two-Component Polyurethane Adhesives:Construction OEMs in Germany specify phosphorus-based systems for curtain wall bonding to satisfy DIN 4102-4 fire resistance ratings without halogen content.
- AI-Driven Formulation Optimization:Machine learning platforms trained on thermal decomposition kinetics are compressing R&D cycles for customized phosphazene-epoxy blends by 30-40%.
Industry Challenges
- Phosphorus Chemistry Talent Scarcity:Specialized expertise in P-Cl bond substitution kinetics and cyclic phosphazene ring stability concentrates with retiring cohorts at Japanese and German specialty chemical firms.
- UL 94 V-0 Certification Timeline:Third-party flame testing protocols require 12-16 weeks for iterative formulation adjustments, delaying commercial launch schedules for electronics adhesive developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenoxycycloposphazene Market |
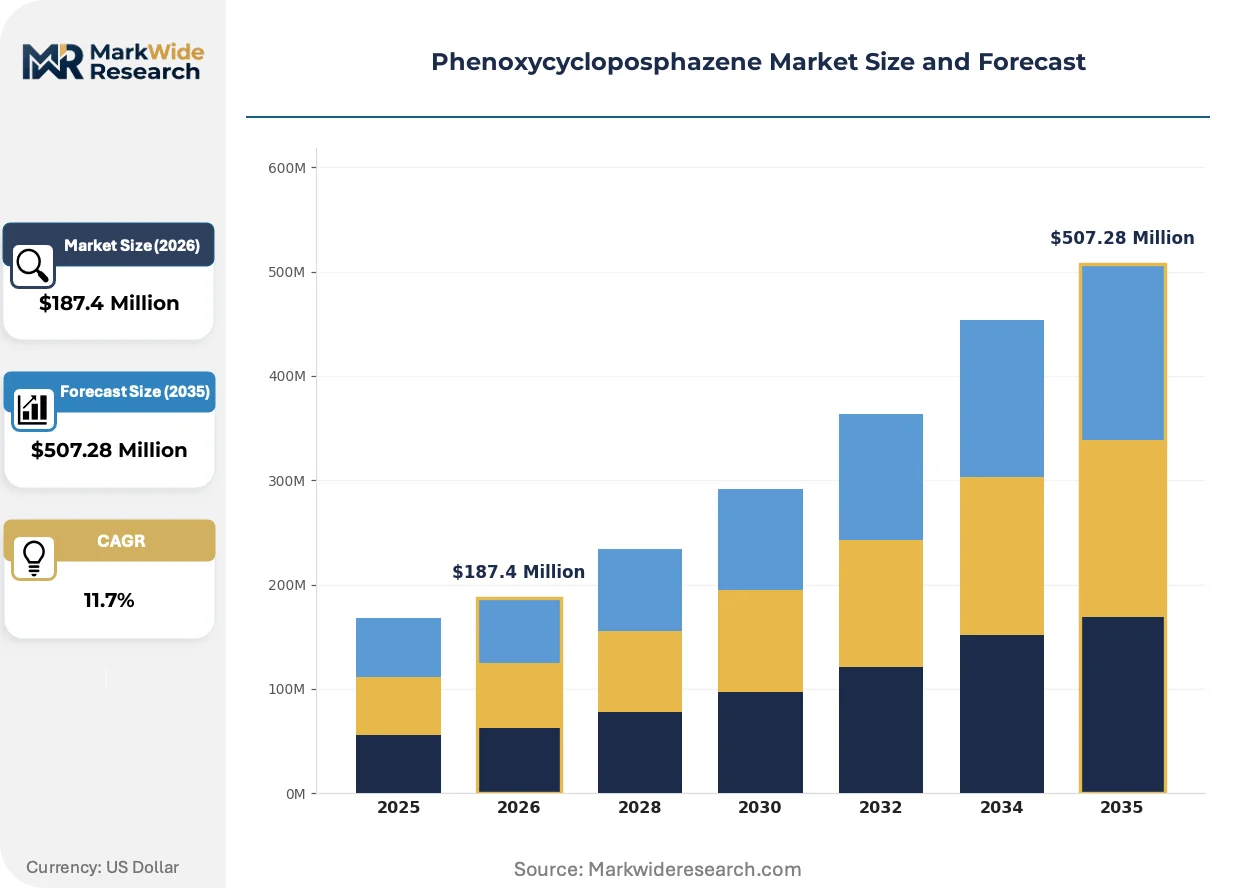
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Emulsion End User: Chemical Industry, Electronics, Construction, Coatings Application: Flame Retardants, Adhesives, Sealants, Textiles Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Ozeki CO, Jiangsu Yoke Technology, Zhangjiagang Xinyi Chemical, Weihai Jinwei ChemIndustry, Zibo Lanyan Chemical, Qingdao Scienoc Chemical, DuPont, Mitsubishi Chemical, Tianjin Zhongxin Chemtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenoxycycloposphazene Market Strategic Shifts
Formulation science is converging with digital chemistry platforms to accelerate phosphazene derivative development, while regulatory stringency in fire safety and chemical management compresses commercialization windows.
Microencapsulated phenoxycycloposphazene particles are absorbing processing shear forces in twin-screw extrusion without premature thermal degradation. Automotive wire harness manufacturers in Stuttgart and Detroit are adopting these grades for continuous compounding lines. This innovation is absorbing margin pressure from mineral filler competition by enabling higher loadings in thin-wall insulation.
China's GB standards evolution on electronic equipment fire safety is tightening halogen content thresholds in server rack enclosures and power distribution units. MIIT certification requirements now mandate third-party testing for phosphorus-based alternatives in data center infrastructure. Domestic OEMs including Inspur and Huawei are accelerating supplier qualification for Jiangsu-sourced phosphazene formulations to secure domestic compliance ahead of 2025 enforcement milestones.
Electronics distributors are consolidating flame-retardant additive procurement under technical service agreements rather than spot purchasing. Arrow Electronics and Avnet are embedding formulation support into supply contracts, displacing traditional chemical trader channels. This restructuring concentrates specification influence with compounders holding in-house thermal analysis capabilities, particularly visible in Shenzhen and Singapore procurement offices serving Southeast Asian contract manufacturers.
Phenoxycycloposphazene Market Segmentation
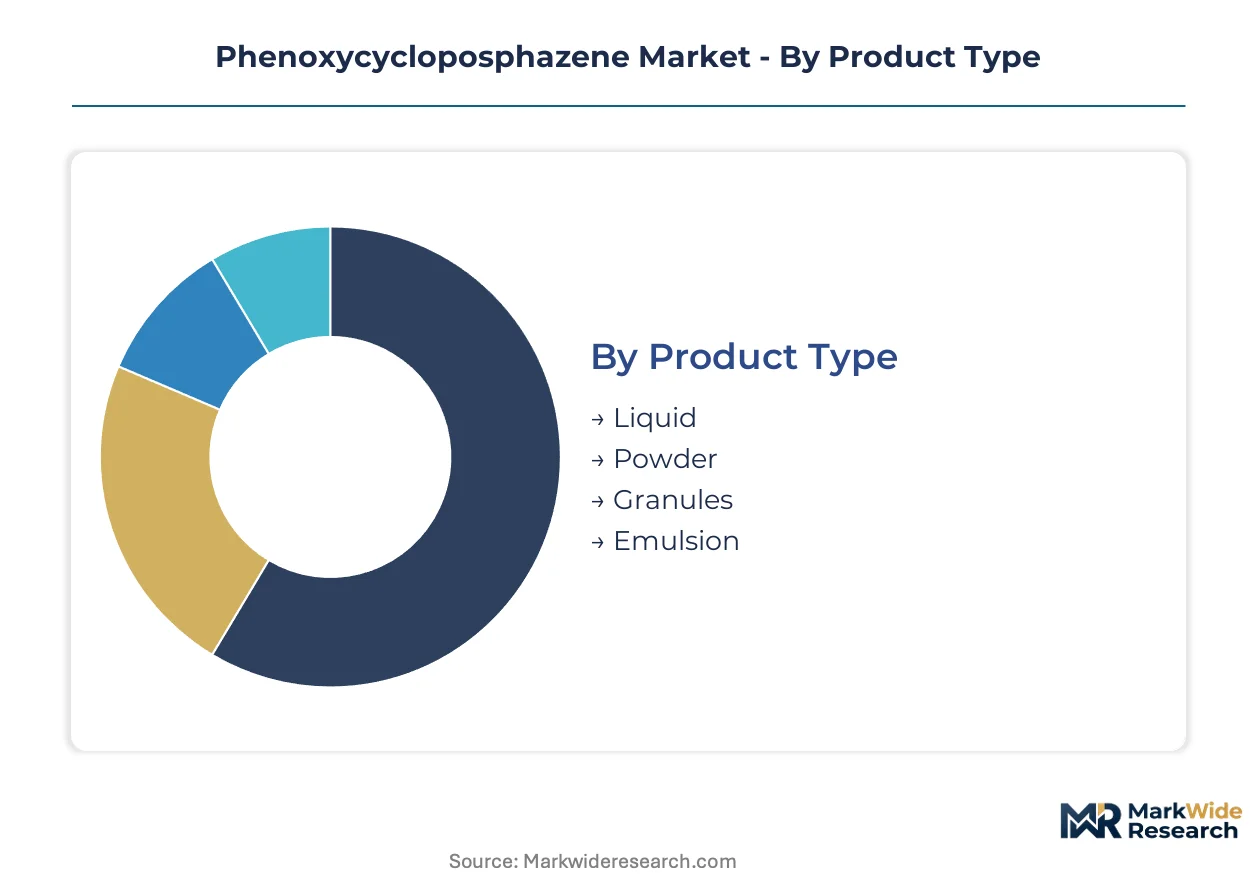
Phenoxycycloposphazene procurement patterns diverge sharply across product forms and end-use specifications. Electronics OEMs demand ion-controlled liquid grades while construction compounders prioritize cost-optimized powder throughput.
Product Type:
Capital intensity peaks with liquid-grade purification infrastructure requiring stainless-steel reactor trains and sub-micron filtration systems.
- Liquid:Low-viscosity formulations enable precision dosing in semiconductor encapsulant potting operations. Demand concentrates with automotive power module manufacturers in Stuttgart requiring thermal stability above 280°C.
- Powder:Crystalline solid morphology facilitates dry-blending with epoxy resins and polyolefins at elevated loadings. Electronics laminators in Jiangsu Province specify this grade for PCB substrate integration where dispersion uniformity governs flame-retardant efficiency.
- Granules:Dust-free handling properties suit automated feeding systems in continuous extrusion lines.
- Emulsion:Aqueous dispersion format serves textile back-coating applications with direct padding compatibility.
Most installed capacity flows through Powder. Expansion is steepest in Liquid.
End User:
Application complexity varies from standardized construction additive formulations to electronics-grade purity protocols with ion-content thresholds below 10 ppm.
- Electronics:Semiconductor encapsulant and PCB laminate applications dominate value capture. Japanese OEMs through METI-certified supply chains specify low-halogen liquid grades for automotive power electronics.
- Construction:Curtain wall adhesives and electrical conduit compounds absorb volume under China's GB 8624 fire classification enforcement. German construction OEMs specify phosphorus-based systems for DIN 4102-4 compliance.
- Chemical Industry:Intermediate synthesis and custom phosphazene derivative production.
- Coatings:Intumescent fire-protection systems for steel infrastructure.
Electronics commands the steepest expansion trajectory. Construction maintains the largest volume base.
Application:
Performance certification requirements create tiered qualification barriers across end-use categories.
- Flame Retardants:Halogen-free epoxy hardener replacement in wire insulation and electronic housings. UL 94 V-0 certification timelines of 12-16 weeks govern commercial access.
- Adhesives:Two-component polyurethane systems for structural bonding. Construction OEMs in Germany specify these for curtain wall applications to satisfy DIN 4102-4 ratings.
- Sealants:Fire-resistant joint compounds for building expansion joints.
- Textiles:Back-coating treatments for technical fabrics in transportation seating.
Flame Retardants anchor current capacity utilization. Adhesives are climbing the fastest.
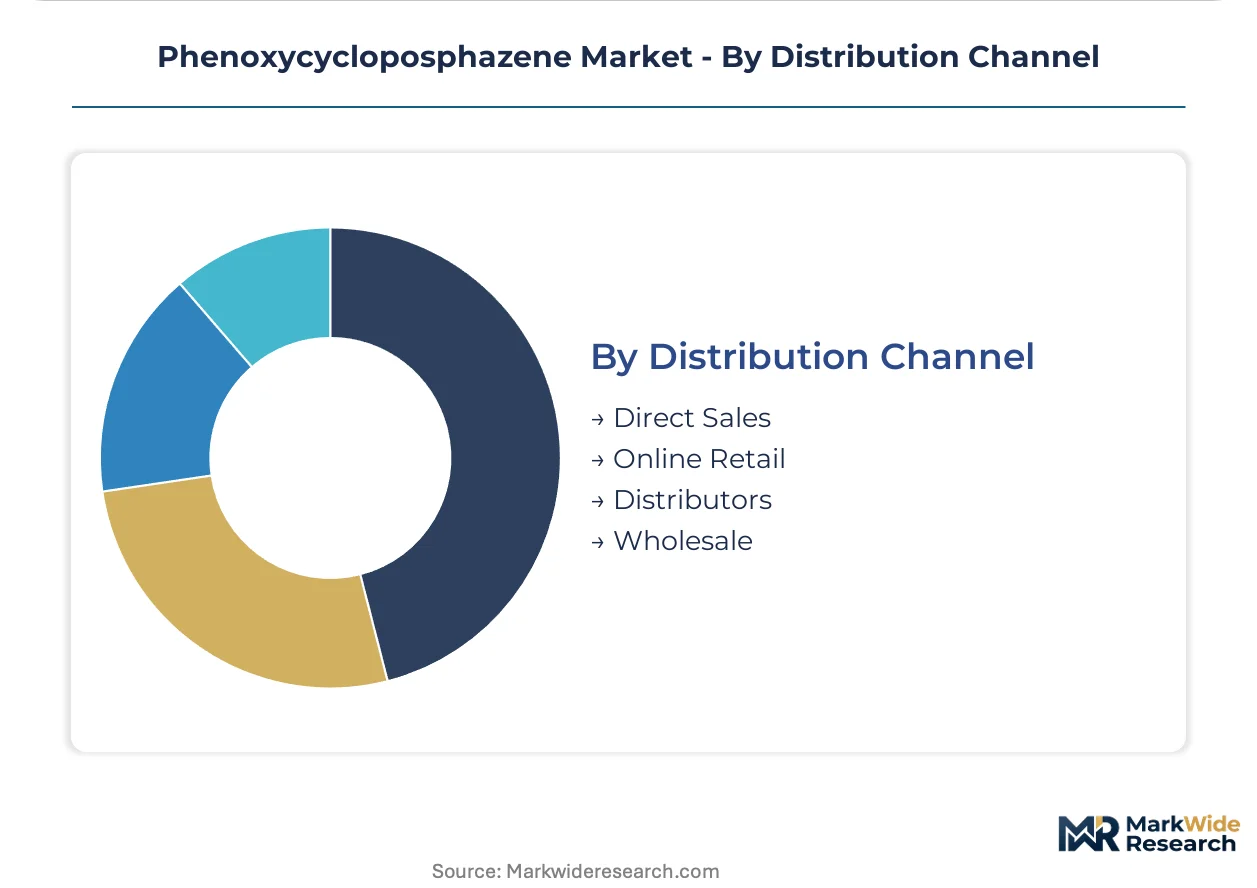
Distribution Channel:
Channel economics reflect technical service intensity versus transaction efficiency tradeoffs.
- Direct Sales:Technical service agreements with formulation support dominate electronics procurement. Arrow Electronics and Avnet embed thermal analysis capabilities into supply contracts for Southeast Asian contract manufacturers.
- Distributors:Regional chemical distributors serve construction compounders with standardized powder grades.
- Online Retail:Small-volume specialty chemical portals for R&D sampling.
- Wholesale:Bulk commodity transactions for standardized industrial grades.
Direct Sales captures the highest margin pool. Distributors maintain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors phenoxycycloposphazene procurement intensity, with Jiangsu Province specialty chemical clusters supplying domestic electronics laminators and automotive wire manufacturers. Regional demand patterns diverge sharply across regulatory jurisdictions and end-use specifications.
China
Electronics OEMs in Shanghai and Suzhou are accelerating halogen-free flame-retardant qualification for PCB substrates and semiconductor encapsulants. MIIT certification requirements under evolving GB standards mandate third-party testing for phosphorus-based alternatives in data center infrastructure. Zhangjiagang and Taizhou chemical parks concentrate domestic phosphazene derivative capacity, reducing logistics costs for Yangtze River Delta manufacturers.
Japan
Automotive power module producers in Nagoya and Osaka require thermal stability above 280°C for advanced packaging architectures. METI maintains JIS standards for electronic equipment flame resistance that OEMs must satisfy for domestic and export sales. Japanese manufacturing bases supply precision-grade material with low-ion-content specifications for semiconductor clients.
Germany
Construction OEMs specify phosphorus-based adhesive systems for curtain wall bonding to satisfy DIN 4102-4 fire resistance ratings. Automotive wire harness manufacturers in Stuttgart adopt microencapsulated grades for continuous compounding lines in thin-wall insulation. REACH registration requirements impose data and testing burdens on importers, shaping market access economics.
United States
Electronics distributors in Silicon Valley and Austin consolidate flame-retardant additive procurement under technical service agreements with embedded formulation support. EPA and OSHA frameworks govern workplace exposure limits for phosphorus compound handling. Southeast Asian contract manufacturers served by US-based procurement offices drive specification influence toward compounders with in-house thermal analysis capabilities.
India
Electronics Manufacturing Incentive Scheme disbursements for semiconductor and component assembly create qualification opportunities with domestic contract manufacturers. BIS fire safety standards for building materials and electronic equipment are tightening compliance requirements for imported flame-retardant additives. Maharashtra and Karnataka industrial corridors attract specialty chemical investments to serve emerging domestic electronics assembly capacity.
Phenoxycycloposphazene Market Competitive Environment
Capacity expansion dominates the current landscape, with Chinese producers adding phosphazene derivative output to capture electronics supply chain localization. The vendor base concentrates around integrated phosphorus chemistry operations and specialty flame-retardant compounders. Three strategic archetypes emerge: Japanese precision-grade suppliers, Chinese integrated producers with captive feedstock access, and Western technology leaders in aerospace and automotive systems. M&A activity and strategic partnerships represent the dominant competitive vectors as qualification timelines compress.
Within the integrated Chinese producer tier, Jiangsu Yoke Technology and Zhangjiagang Xinyi Chemical exemplify operations anchored in Jiangsu Province chemical clusters. Ozeki CO occupies a position representing Japanese precision-grade supply for electronics clients with stringent ion-content requirements. DuPont sits within the technology leadership archetype, competing on halogen-free system expertise for aerospace and automotive wire coating applications.
| Leading Market Players |
|---|
| Ozeki CO |
| Jiangsu Yoke Technology |
| Zhangjiagang Xinyi Chemical |
| Weihai Jinwei ChemIndustry |
| Zibo Lanyan Chemical |
| Qingdao Scienoc Chemical |
| DuPont |
| Mitsubishi Chemical |
| Tianjin Zhongxin Chemtech |
| Others |
Value Chain & Pricing Dynamics
China's GB 8624 fire safety mandates on halogen-free building materials gate qualified supply access for phenoxycycloposphazene producers, restricting premium-tier pricing power to compounders with certified phosphorus chemistry operations and MIIT-compliant testing infrastructure.
Pricing Analysis
Distributor margin layers absorb 15-25 points between Jiangsu chemical park production and Yangtze River Delta electronics laminators. Three-tier pricing structure across electronics-grade liquid, industrial powder, and construction granule tiers separates ion-controlled semiconductor formulations from commodity flame-retardant blends. Cost compression in powder grades intensifies because magnesium hydroxide mining scale economies in Qinghai Province erode polyolefin wire and cable positioning below 200°C service thresholds. Construction compounders exhibit highest price sensitivity, while automotive power module manufacturers in Stuttgart tolerate premium liquid-grade positioning for thermal stability above 280°C.
Supply Chain Analysis
Inland freight costs from Zhangjiagang and Taizhou chemical parks to Shanghai-Suzhou electronics corridors run 40-60% below interprovincial logistics from inland phosphorus derivative sources. Supply concentrates in China, Japan, and Germany, with hexachlorocyclotriphosphazene feedstock anchored in three Chinese producers exposing compounders to Q4 maintenance turnaround vulnerabilities. Raw material dependencies rest on chlorinated phosphazene precursors, sodium phenoxide, and specialized stainless-steel reactor infrastructure. Single-source feedstock concentration presents structural risk during seasonal maintenance windows. Distribution runs through direct technical service agreements with Arrow Electronics and Avnet displacing spot chemical trader channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phenoxycycloposphazene margin expansion rests on electronics-grade liquid formulation premiums and captive hexachlorocyclotriphosphazene feedstock integration compressing input cost volatility.
For Market Incumbents: Extend certification coverage under evolving GB standards and JIS updates to lock out mineral filler substitution threats from Qinghai-sourced magnesium hydroxide. Deepen captive supply of chlorinated phosphazene precursors through Jiangsu Province chemical park capacity additions. Prioritize UL 94 V-0 pre-certification investments to compress 12-16 week qualification timelines for electronics adhesive developers. For New Entrants and Emerging Players: Indian contract manufacturers under PLI scheme disbursements represent the most penetrable buyer archetype for first-mover halogen-free retardant qualification with Dixon Technologies and Aequs. Construction OEMs in Germany specifying DIN 4102-4 compliant curtain wall adhesives offer white-space positioning away from saturated electronics procurement channels. Lead with AI-driven formulation optimization platforms trained on thermal decomposition kinetics to compress R&D cycles by 30-40% against incumbent development timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among integrated Chinese phosphorus chemistry specialists with captive feedstock access and MIIT certification infrastructure already deployed. Long-term viability over the next decade hinges on regulatory divergence between China's GB standard evolution, Japan's JIS electronics updates, and potential EU CLP restriction proposals. Monitor phosphorus chemistry talent scarcity signals—retiring cohort expertise in P-Cl bond substitution kinetics at Japanese and German specialty chemical firms—as inflection indicator for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hexachlorocyclotriphosphazene Feedstock | Captive precursor supply insulates compounders from 40-60 day order-to-delivery cycles during Q4 maintenance turnarounds. |
| MIIT Certification Pre-Investment | Early compliance with evolving GB standards secures supplier qualification with Inspur and Huawei ahead of enforcement milestones. |
| AI-Driven Formulation Optimization Platform | Machine learning on thermal decomposition kinetics compresses customized phosphazene-epoxy blend development cycles by 30-40%. |
| Long-Term Technical Service Agreement with Electronics Distributors | Arrow Electronics and Avnet embedding thermal analysis capabilities displace spot chemical trader channels in Southeast Asian procurement. |
| Microencapsulated Grade Capacity Addition | Shear-resistant particles enable automotive wire harness manufacturers in Stuttgart and Detroit to adopt continuous compounding lines. |
Study Parameters
Direct dialogue with specialty chemical plant managers, electronics OEM procurement leads at PCB laminators and semiconductor encapsulant compounders, distribution channel partners serving construction adhesives markets, and phosphorus chemistry R&D directors grounded qualitative intelligence. Secondary validation drew from China customs and trade data, Ministry of Emergency Management GB standard evolution filings, Jiangsu Province chemical park capacity announcements, and ECHA REACH registration disclosures. Bottom-up and top-down triangulation cross-checked producer capacity announcements against downstream demand modeling.
Bottom-up volume modeling segmented by product form tier, end-use industry vertical, and regional production hub concentration anchored forecast construction. Electronics-grade liquid, industrial powder, and construction granule tiers combined with flame-retardant, adhesive, and sealant applications plus China, Japan, Germany, and India regional clusters structured the analytical framework. CAGRs derived from segmented growth rate assumptions weighted by base-year consumption shares across the projection horizon. Industry-specific inputs included MIIT certification timeline acceleration, UL 94 V-0 testing protocol durations, and hexachlorocyclotriphosphazene feedstock maintenance cycle patterns.
Underlying measurement precision varies by segment; electronics-grade liquid formulations with ion-content thresholds below 10 ppm carry tighter precision than commodity construction powder grades where dispersion uniformity assumptions introduce wider bands. Forecasts reflect documented assumptions on regulatory enforcement timing, feedstock capacity expansion schedules, and mineral filler substitution elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Special Boiling Point Solvents Market