
 Acesulfame K Market | 2026-2036
Acesulfame K Market Size, Share, and Industry Trends Forecast 2026-2036
Acesulfame K Market Analysis
China is fragmenting acesulfame K capacity across multiple provincial production zones, with Shandong Minghui Food extending its fermentation-to-crystallization pipeline while Jiangsu Vitasweet anchors downstream blending operations for export markets. Anhui Jinhe Industrial leverages captive sucrose supply chains to sustain cost positions in powdered grades. Changzhou Niutang Chemical Plant competes on pharmaceutical-grade purity certifications, differentiating from commodity bulk suppliers.
Acesulfame K is a high-intensity non-nutritive sweetener, chemically designated as potassium salt of 6-methyl-1,2,3-oxathiazine-4(3H)-one 2,2-dioxide, exhibiting approximately 200 times the sweetness intensity of sucrose with thermal stability up to 225°C that enables pasteurization and baking applications. The compound functions primarily as a flavor enhancer and sugar substitute in processed foods and beverages where caloric reduction or glycemic control is targeted. Powdered grades dominate volume throughput due to handling efficiency in industrial batching, while liquid formulations are gaining traction in beverage premix operations where dissolution speed determines line productivity. The nutraceutical end-user channel represents the fastest-expanding margin pool as protein supplement and sports nutrition brands reformulate with acesulfame K blends to mask bitter notes from functional ingredients.
China's SAMR enforces GB 25540 standards for acesulfame K purity and maximum usage levels in food categories, while the EU's EFSA maintains ongoing re-evaluations of acceptable daily intake thresholds that directly determine formulation ceilings for products entering European markets. The FDA's food additive regulations under 21 CFR 172.800 govern US market access, with periodic toxicology reviews influencing brand-owner risk assessments. Stakeholders must monitor regulatory divergence between jurisdictions on cumulative sweetener exposure limits, as tightening standards in one major market cascade through multinational reformulation decisions.
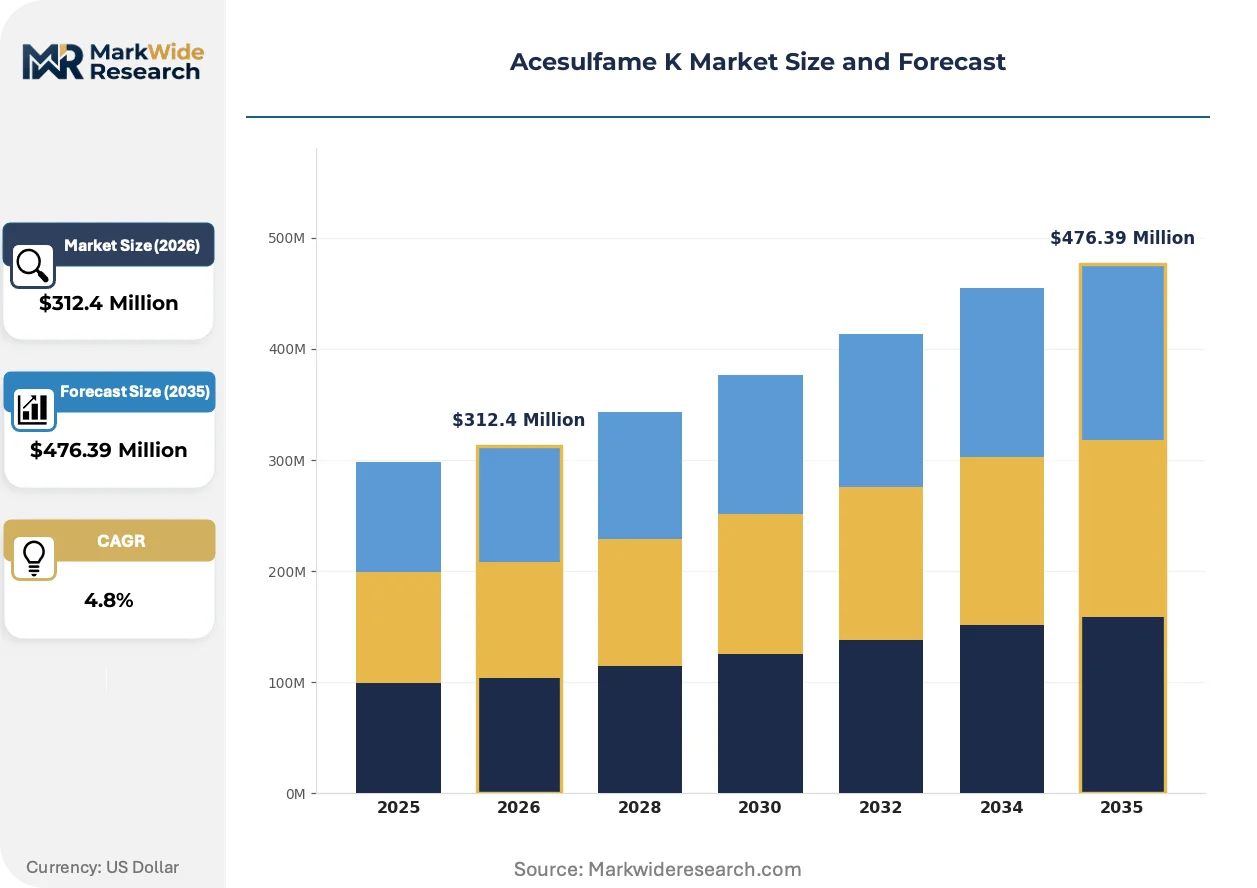
Market Dynamics
China's SAMR enforcement of GB 25540 purity standards is compressing supplier margins while accelerating consolidation among Shandong and Jiangsu fermentation-to-crystallization operators. This regulatory tightening is reshaping qualification requirements for export-bound material.
Growth Catalysts
- Beverage reformulation mandates:Reduced-sugar carbonated drink specifications in the EU and North America are pulling high-intensity sweetener volumes into flavored water and functional beverage premix operations.
- Sports nutrition protein masking:Bitter-note suppression requirements in whey and plant-based protein supplements are expanding acesulfame K blend adoption across nutraceutical contract manufacturers.
- EFSA re-evaluation timelines:Pending acceptable daily intake reviews are prompting European brand owners to secure qualified supply chains ahead of potential formulation ceiling adjustments.
Market Restraints
- Sucrose feedstock volatility:Anhui province's captive sugar supply chains face input cost pressure from climate-impacted beet and cane harvests, compressing powdered grade margins.
- Shandong-Jiangsu supply concentration:Over two-thirds of crystallization capacity sits within 400 kilometers of Qingdao, creating geographic risk exposure to regional environmental enforcement actions.
- Thermal stability ceiling:The 225°C decomposition threshold limits ultra-high-temperature processing applications where sucralose maintains performance advantages.
Strategic Opportunities
- Pharmaceutical-grade certification:Changzhou Niutang's USP-grade positioning demonstrates margin expansion potential for suppliers achieving excipient purity standards above food-grade baselines.
- Liquid formulation premix channels:Beverage line productivity demands are opening dissolution-optimized supply contracts with multinational bottling operations seeking batch-time reductions.
- India FSSAI sweetener approvals:Pending regulatory harmonization with Codex standards is creating first-mover positioning for qualified exporters into processed food and dairy applications.
Industry Challenges
- Fermentation scale-up expertise:Shandong Minghui's extended pipeline demonstrates that 6-methyl-1,2,3-oxathiazine biocatalysis requires specialized biochemical engineering talent scarce outside established chemical clusters.
- Cross-jurisdiction compliance synchronization:Suppliers must maintain parallel certification tracks for FDA 21 CFR 172.800, EFSA additive evaluations, and China's GB 25540 amendments without unified testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acesulfame K Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated, Liquid, Powdered, Tablets Application: Beverages, Confectionery, Dairy Products, Bakery End User: Food Manufacturers, Nutraceuticals, Personal Care, Pharmaceuticals Sales Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Anhui Jinhe Industrial Co. Ltd, Changzhou Niutang Chemical Plant Co. Ltd, Suzhou Hope Technology Co. Ltd, Nutrinova (Celanese), HYET Sweet, Hermes Sweeteners, Jiangsu Vitasweet, Shandong Minghui Food, Jiangxi BEIYANG Food Additive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acesulfame K Market Emerging Trajectories
Continuous crystallization automation is collapsing batch-to-batch variation in sweetness potency while regulatory divergence between FDA and EFSA timelines is forcing dual-track toxicology investments. These pressures are compressing supplier economics and accelerating technology substitution decisions.
Continuous flow crystallization systems are collapsing residence time requirements from 12-hour batch cycles to sub-4-hour processing windows. Jiangsu Vitasweet and comparable operators are retrofitting fermentation downstream units to capture yield improvements and energy cost reductions. This equipment transition is collapsing the cost gap between commodity powdered grades and higher-purity pharmaceutical certifications.
EFSA's systematic re-evaluation of artificial sweetener acceptable daily intakes is compressing formulation ceilings for products entering European markets. Brand owners are pre-emptively reducing acesulfame K loadings in reformulated SKUs to maintain compliance headroom against potential threshold reductions. The beverage segment is responding with blend diversification strategies incorporating stevia and monk fruit extracts.
Sports nutrition brands are unbundling sweetener procurement from flavor house contracts to secure direct supply relationships with crystallization specialists. This disintermediation is shifting volume commitments from beverage-centric distributors to nutraceutical-focused chemical traders. The pattern is most visible in North American protein supplement manufacturing where batch customization requirements exceed standardized beverage specifications.
Acesulfame K Market Segmentation
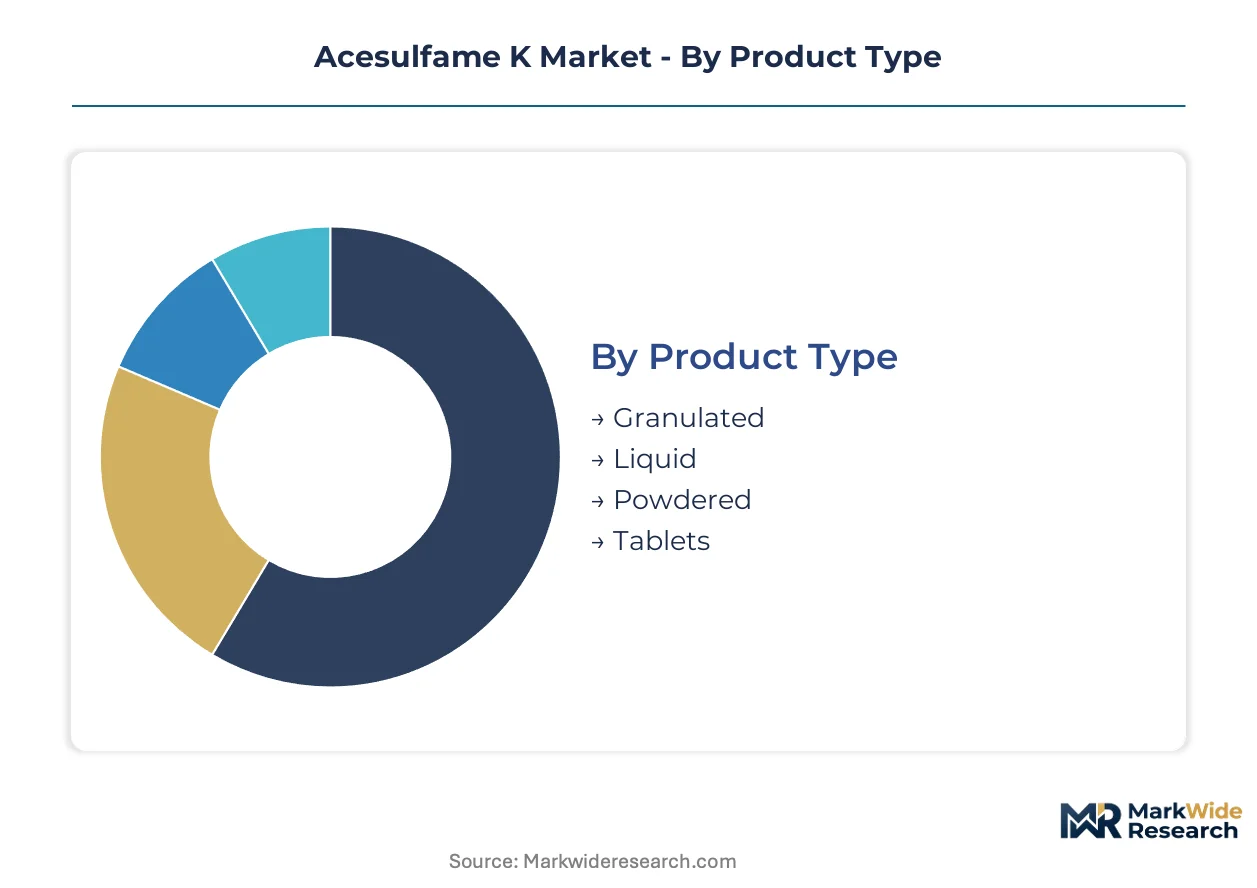
Acesulfame K's technical versatility—thermal stability, high solubility, and synergistic blending—creates distinct demand profiles across physical forms and end-use channels. Suppliers must align crystallization output with precise formulation requirements in beverage premix operations versus pharmaceutical excipient specifications.
Product Type:
Use-case spectrum spans industrial batching efficiency through pharmaceutical precision, with physical form dictating dissolution kinetics and handling economics.
- Powdered:Fine crystalline grades dominate industrial throughput due to metering accuracy in high-speed blending lines and bulk packaging economics. Food manufacturers in China's Shandong province anchor demand for standardized particle distribution that ensures homogeneous sweetness delivery in carbonated beverage concentrates.
- Liquid:Pre-dissolved formulations eliminate hydration delays in continuous beverage processing, with dissolution-optimized concentrates gaining share among multinational bottling operations seeking batch-time compression. EFSA formulation ceiling pressures are accelerating blend diversification into liquid stevia-acesulfame K hybrids.
- Granulated:Free-flowing agglomerated particles reduce dust exposure in manual handling environments, serving smaller confectionery and bakery operations without pneumatic transfer systems.
- Tablets:Compressed unit-dose formats address pharmaceutical excipient and tabletop sweetener applications where precise individual dosing supersedes bulk efficiency.
Established volume favors Powdered; emerging adoption favors Liquid.
Application:
Cost tier stratification separates commodity beverage formulations from premium-positioned functional food applications, with thermal processing requirements filtering supplier qualification.
- Beverages:Reduced-sugar carbonated drinks and flavored waters pull the majority of high-intensity sweetener volumes, with pasteurization compatibility at 225°C enabling hot-fill operations. EU and North American reformulation mandates are restructuring procurement toward qualified crystallization specialists capable of EFSA-compliant purity documentation.
- Confectionery:Hard candy and chewing gum applications exploit acesulfame K's heat stability and non-cariogenic profile, though sucralose maintains share in ultra-high-temperature depositing processes exceeding thermal ceilings.
- Dairy Products:Yogurt and flavored milk applications require acid-stable sweetness systems that survive fermentation pH shifts, with powdered grades preferred for dry mix-in operations.
- Bakery:Maillard reaction incompatibility limits standalone use in browning-dependent applications, relegating acesulfame K to blend components in reduced-sugar cake and cookie formulations.
Volume concentration sits with Beverages; margin expansion concentrates in Confectionery.
End User:
Customer type segmentation reveals diverging procurement patterns between specification-tolerant food manufacturers and certification-intensive pharmaceutical buyers.
- Food Manufacturers:Beverage and processed food producers drive baseline demand through commodity-grade powdered and liquid contracts, with Shandong-Jiangsu supply clusters serving formulation flexibility requirements across carbonated and still drink portfolios.
- Nutraceuticals:Protein supplement and sports nutrition brands represent the steepest expansion trajectory, with bitter-note masking requirements in whey and plant-based formulations pulling direct supply relationships away from flavor house intermediaries.
- Pharmaceuticals:USP-grade excipient specifications command premium positioning for tablet binders and liquid medication sweetening, with Changzhou Niutang's certification track demonstrating margin potential above food-grade baselines.
- Personal Care:Toothpaste and oral care applications leverage non-cariogenic claims in premium positioning, though volumes remain fractional against ingestible categories.
Procurement scale favors Food Manufacturers; specification intensity favors Pharmaceuticals.
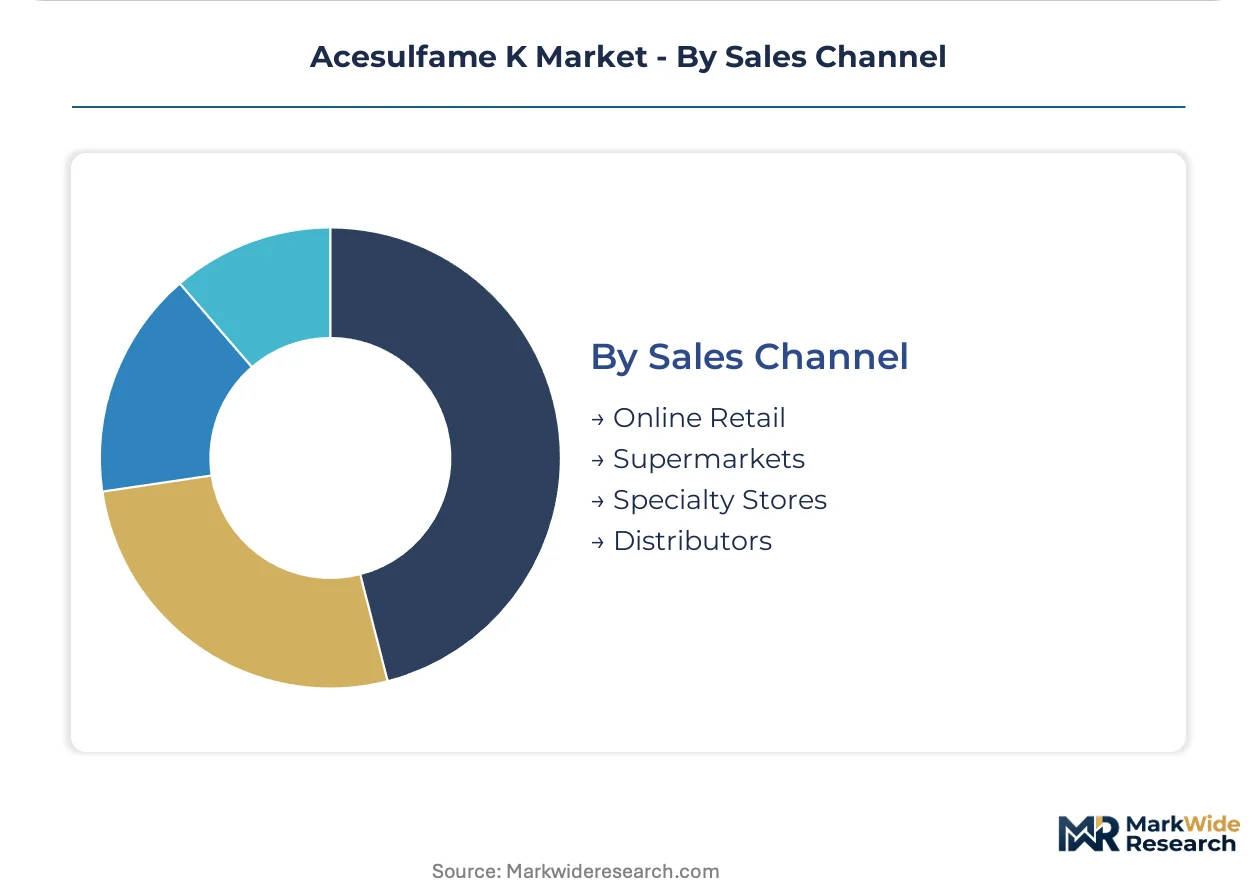
Sales Channel:
Supply concentration in chemical manufacturing clusters shapes distribution economics, with bulk industrial procurement diverging sharply from fragmented retail accessibility.
- Distributors:Chemical trading houses and ingredient distributors consolidate procurement for mid-scale food manufacturers lacking direct supplier qualification resources, with Shandong and Jiangsu warehouse networks serving regional batching operations.
- Online Retail:E-commerce platforms address small-scale nutraceutical startups and specialty food producers seeking sample quantities and flexible order minimums outside traditional distributor thresholds.
- Supermarkets:Consumer-packaged tabletop sweeteners represent a marginal channel, with private-label positioning dependent on brand recognition rather than industrial specification.
- Specialty Stores:Health food and organic retail channels show limited acesulfame K penetration due to clean-label positioning favoring natural alternatives.
Industrial throughput flows through Distributors; market access experimentation channels through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces concentrate over two-thirds of crystallization capacity within a 400-kilometer radius of Qingdao. This geographic clustering shapes trade flows and regulatory compliance requirements across export destinations.
United States
Beverage reformulation mandates from FDA 21 CFR 172.800 drive demand for qualified acesulfame K supply chains in reduced-sugar carbonated drinks. The agency's periodic toxicology reviews prompt brand owners to maintain formulation headroom against potential threshold adjustments. New Jersey and California distribution hubs consolidate procurement for multinational bottling operations seeking EFSA-aligned purity documentation.
Germany
EFSA's systematic re-evaluation of acceptable daily intake thresholds compresses formulation ceilings for products entering European markets. The Federal Office of Consumer Protection and Food Safety enforces additive purity standards that cascade through multinational supply chain decisions. Cologne and Hamburg chemical trading houses anchor distribution networks serving reformulated confectionery and dairy applications across the EU.
China
SAMR enforcement of GB 25540 standards accelerates consolidation among Shandong and Jiangsu fermentation-to-crystallization operators. The Ministry of Ecology and Environment's regional enforcement actions create supply disruption risks for export-bound material. Qingdao and Changzhou manufacturing clusters dominate global output capacity through integrated fermentation-to-crystallization pipelines.
India
FSSAI's pending harmonization with Codex standards creates first-mover positioning opportunities for qualified exporters into processed food and dairy applications. The Bureau of Indian Standards maintains additive safety evaluations that determine import clearance protocols. Maharashtra and Gujarat food manufacturing corridors drive domestic demand for high-intensity sweetener formulations in traditional dairy and beverage categories.
Brazil
ANVISA's food additive regulations govern market access for imported acesulfame K in reduced-sugar beverage and confectionery applications. The agency's alignment with Mercosur standards shapes regional trade dynamics for crystallization specialists. São Paulo state concentrates formulation and blending operations serving Latin American processed food manufacturers.
Acesulfame K Market Vendor Landscape
Integrated fermentation specialists and downstream blending operators split the market between upstream crystallization and formulation flexibility. The supplier base concentrates geographically around Shandong-Jiangsu chemical corridors where biochemical engineering talent scarcity limits new entrant viability. Three archetypes dominate: captive sucrose-integrated producers, pharmaceutical-grade purity specialists, and export-focused blending operations. Competitive moves center on continuous crystallization automation investments and dual-track regulatory certification maintenance.
Among Chinese fermentation-to-crystallization operators, Anhui Jinhe Industrial Co. Ltd and Shandong Minghui Food occupy positions within the integrated production archetype, leveraging provincial supply chain proximity. Changzhou Niutang Chemical Plant Co. Ltd exemplifies the pharmaceutical-grade certification tier, representing margin expansion potential through excipient purity standards. Jiangsu Vitasweet sits within the export-oriented blending specialist category, serving multinational beverage premix requirements. Suzhou Hope Technology Co. Ltd anchors a position among technology-integrated operators in the Yangtze River Delta manufacturing corridor.
| Leading Market Players |
|---|
| Anhui Jinhe Industrial Co. Ltd |
| Changzhou Niutang Chemical Plant Co. Ltd |
| Suzhou Hope Technology Co. Ltd |
| Nutrinova (Celanese) |
| HYET Sweet |
| Hermes Sweeteners |
| Jiangsu Vitasweet |
| Shandong Minghui Food |
| Jiangxi BEIYANG Food Additive |
| Others |
Supply Flow & Price Mechanics
The Qingdao-Shanghai freight corridor's container cost dynamics amplify pricing power for Shandong-Jiangsu crystallization clusters while forcing downstream differentiation between pharmaceutical-grade and commodity-grade buyers. GB 25540 compliance investments compress margins at the fermentation-to-crystallization interface, with purity certification tiers separating export-bound material from domestic food-grade throughput.
Pricing Analysis
China's GB 25540 standards dictate the pricing tier structure across food-grade, pharmaceutical-grade, and reagent-grade certifications. Three-tier pricing separates USP-grade excipients from standard food-additive powders and economy-grade industrial blends. Price differentiation rests on EFSA-aligned purity documentation and thermal stability batch testing. Cost compression in commodity powdered grades is intensifying because Anhui province's captive sucrose supply chains face climate-impacted harvest volatility. Nutraceutical contract manufacturers show highest price sensitivity due to reformulation frequency, while pharmaceutical excipient buyers accept premium positioning for USP certification.
Supply Chain Analysis
Shandong Minghui Food and Jiangsu Vitasweet anchor contract-manufacturing concentration for crystallization and downstream blending operations. Geographic supply concentrates in China, with secondary fermentation capacity in India and specialty blending operations in Germany. Raw material dependencies draw from sucrose feedstocks, biocatalytic enzymes for 6-methyl-1,2,3-oxathiazine conversion, and potassium salt for final salt formation. Single-source vulnerability runs through Shandong-Jiangsu environmental enforcement exposure within the 400-kilometer Qingdao radius. Distribution runs through chemical trading houses consolidating procurement for mid-scale food manufacturers lacking direct supplier qualification resources.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
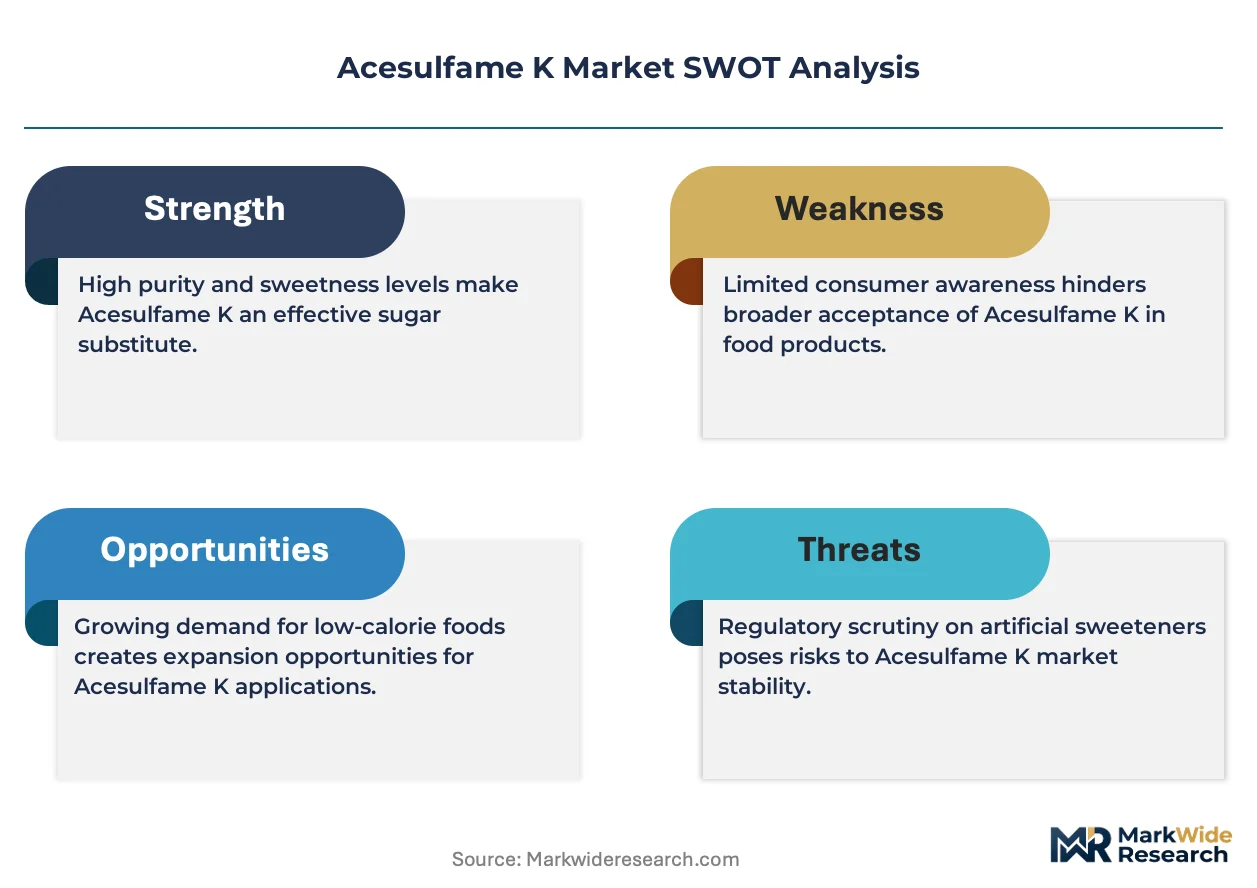
Fragmentation opportunity emerges as EFSA re-evaluation timelines force brand owners to diversify sweetener blends, creating niche positioning for crystallization specialists capable of rapid formulation customization.
For Market Incumbents: Entrench through backward integration into captive sucrose supply chains and continuous crystallization automation investments that collapse batch-to-batch variation. Shandong-Jiangsu operators must defend against pharmaceutical-grade purity specialists like Changzhou Niutang by securing dual-track FDA-EFSA certification maintenance ahead of potential ADI threshold adjustments. Capacity addition in pharmaceutical-grade lines represents the critical lever for margin expansion above commodity-grade baselines. For New Entrants and Emerging Players: India's FSSAI regulatory harmonization with Codex standards offers underpenetrated positioning for qualified exporters into processed food and dairy applications. Target Maharashtra and Gujarat food manufacturing corridors with direct supply relationships bypassing chemical trading house intermediaries. Sports nutrition protein masking applications provide the most penetrable segment given disintermediation trends unbundling sweetener procurement from flavor house contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized fermentation-to-crystallization assets in China's coastal provinces. Long-term viability favors operators with integrated biochemical engineering talent pools and dual-jurisdiction compliance infrastructure. The signal to watch is EFSA ADI re-evaluation outcomes triggering multinational reformulation cascades and qualified supply chain scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Crystallization Automation | Jiangsu Vitasweet's retrofit investments collapse residence times from 12-hour batches to sub-4-hour windows. |
| Pharmaceutical-Grade Certification | Changzhou Niutang's USP-grade positioning demonstrates margin expansion above food-grade baselines. |
| Backward Integration into Sucrose | Anhui Jinhe's captive supply chains sustain cost positions against climate-impacted beet and cane volatility. |
| Dual-Track Regulatory Certification | Parallel FDA 21 CFR 172.800 and EFSA compliance tracks secure European market access ahead of ADI reviews. |
| Liquid Formulation Premix Development | Dissolution-optimized concentrates address multinational bottling operations seeking batch-time compression. |
Methodological Framework
Operator-level perspectives from fermentation plant managers, downstream beverage formulation chemists, nutraceutical contract manufacturing procurement leads, and pharmaceutical excipient quality directors anchored the qualitative base. Primary interviews combined with secondary validation from SAMR GB 25540 amendment filings, EFSA additive re-evaluation reports, FDA 21 CFR 172.800 regulatory dockets, and customs/trade data for high-intensity sweetener flows. Bottom-up crystallization capacity assessments and top-down end-use demand modeling provided triangulation across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning physical form, application category, end-user type, and sales channel. Grade tier, end-use industry, and regional production hub stratification shaped the analytical framework. CAGRs derived from installed fermentation capacity expansion timelines and reformulation-driven demand elasticity for reduced-sugar applications. Forecast inputs incorporated EFSA ADI re-evaluation timelines and FSSAI regulatory harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by pharmaceutical-grade purity specialists or sudden SAMR environmental enforcement actions would shift outcomes. Quarterly review of EFSA additive safety opinions, Anhui province sucrose harvest yields, and Shandong-Jiangsu environmental compliance actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Zinc Eugenol Market