
 RFID Locks Market | 2026-2036
RFID Locks Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Locks Market Intelligence
Shortages of certified electronic security technicians is unwinding installation capacity across major metropolitan corridors. ASSA ABLOY leverages its captive hardware ecosystem to control supply continuity for large hospitality rollouts. dormakaba Group anchors European commercial retrofit demand through its narrow-body electronic mortise platforms. SALTO Systems specializes in wireless online access control for educational campuses where IT infrastructure constraints favor battery-operated locks.
RFID locks are electromechanical locking devices that authenticate credentials through radio-frequency identification protocols operating at 125 kHz to 13.56 MHz or 860–960 MHz bands, with credential validation triggering a solenoid or motorized bolt mechanism. Their primary commercial purpose is to eliminate mechanical key distribution while generating time-stamped audit logs for security compliance. Networked locks command premium positioning in new commercial construction where structured cabling or mesh networks support real-time credential updates, while standalone locks retain cost advantages in residential and small-facility retrofits. Passive RFID credentials dominate volume shipments due to their absence of onboard power requirements, though ultra-high frequency RFID is gaining traction in vehicle access and logistics yard applications.
The EU AI Act and GDPR impose algorithmic transparency and biometric data handling requirements on smart lock systems deployed in European facilities, while the FCC governs radio emission profiles for RFID readers operating in unlicensed spectrum across the United States. ETSI EN standards for radio equipment and ISO/IEC 14443 proximity card specifications shape interoperability mandates that manufacturers must satisfy for market access. Stakeholders must weigh credential migration paths against emerging mobile wallet and smartphone-based access protocols before committing to long-term infrastructure cycles.
Market Dynamics
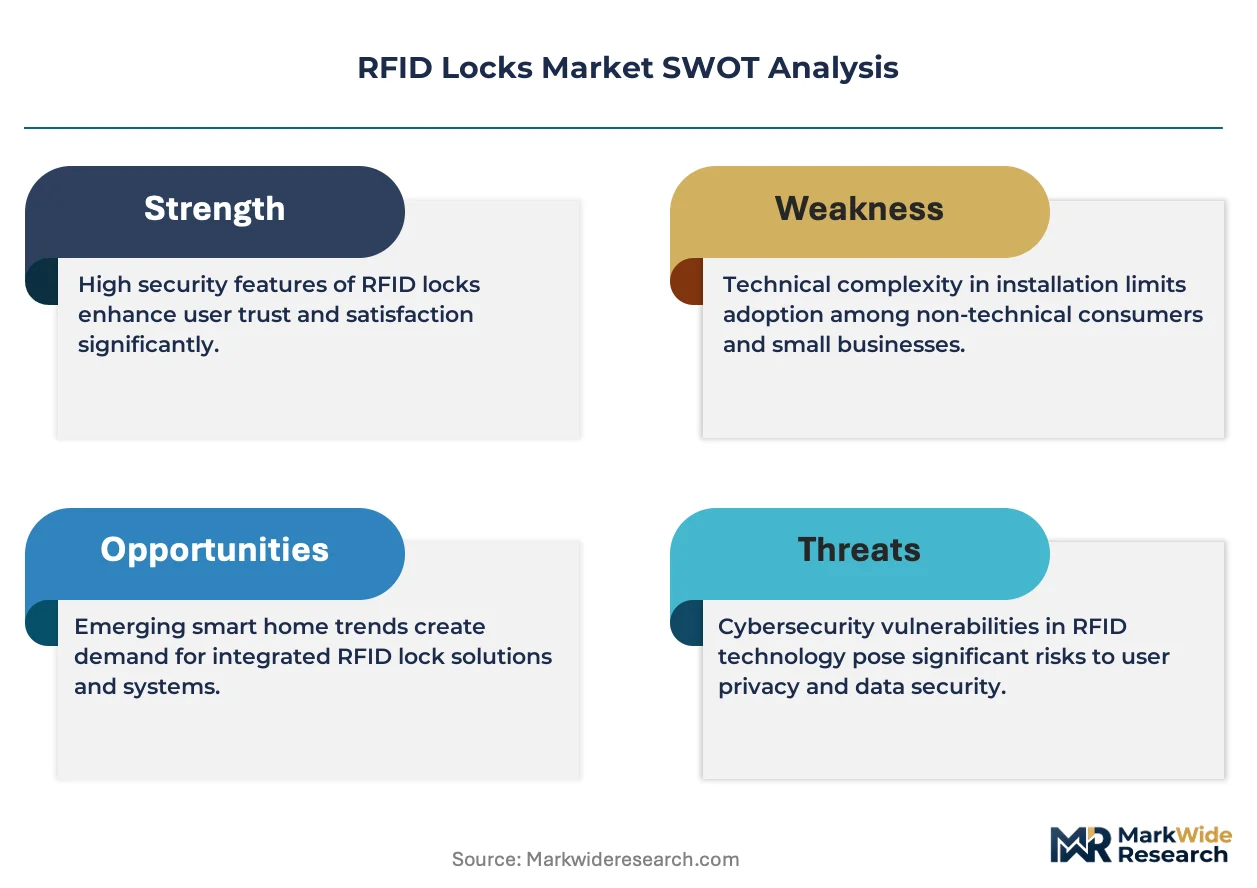
Contactless credential migration is compressing replacement cycles across commercial real estate portfolios as building operators reconcile legacy mechanical infrastructure with audit-compliant electronic access systems.
Growth Catalysts
- Hospitality contactless mandates:Hotel chains in the United States and Germany are retrofitting guest room entry systems to eliminate physical key handoffs and satisfy post-pandemic hygiene protocols.
- GDPR audit trail requirements:European facility managers must deploy time-stamped access logging for compliance, directly favoring RFID over mechanical master key systems.
- Passive 13.56 MHz credential standardization:ISO/IEC 14443 proximity specifications enable interoperability across multi-vendor campus deployments, reducing lock-in risk for institutional buyers.
Market Restraints
- Semiconductor supply concentration:Microcontroller shortages from East Asian foundries delay lock production schedules for retrofit contractors.
- Copper and rare earth magnet costs:Solenoid actuator materials face price volatility that compresses hardware margins on economy-tier standalone units.
- Mobile wallet substitution:Smartphone-based BLE and NFC access protocols threaten dedicated RFID credential volumes in premium commercial segments.
Strategic Opportunities
- India educational campus buildout:Government-funded smart city initiatives create greenfield demand for networked battery-operated locks where IT cabling remains absent.
- Vehicle access convergence:Ultra-high frequency RFID at 860-960 MHz enables seamless parking-to-building entry sequences for corporate campuses.
- EU AI Act compliance services:Algorithmic transparency mandates for biometric-enabled smart locks create recurring revenue streams for system integrators.
Industry Challenges
- Certified electronic security technician scarcity:Labor shortages across metropolitan installation corridors extend project timelines and inflate deployment costs.
- Legacy mechanical hardware interoperability:Retrofit installations must accommodate non-standard door prep dimensions without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Locks Market |
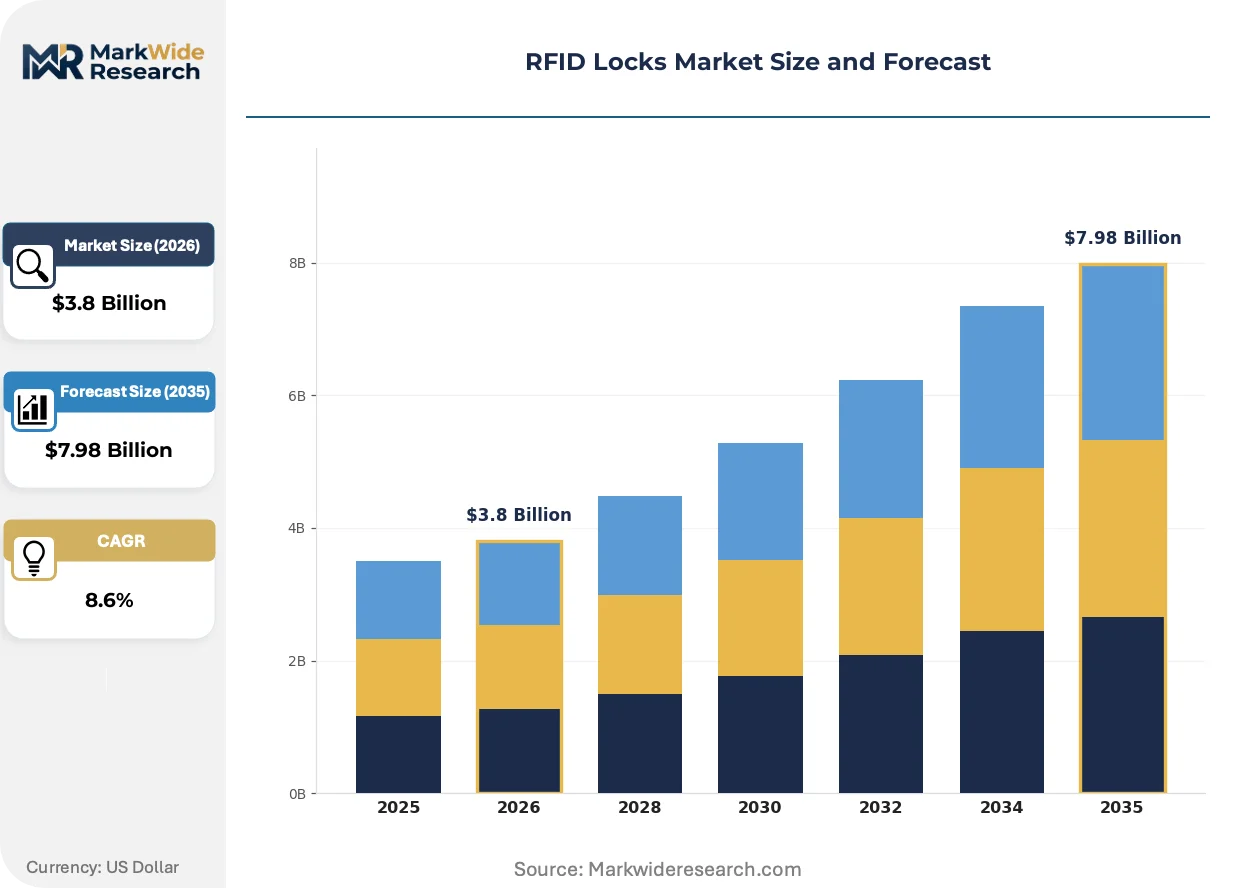
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Locks, Networked Locks, Mortise Locks, Padlocks, Cabinet Locks Technology: Passive RFID, Active RFID, Semi-Passive RFID, High-Frequency RFID, Ultra-High Frequency RFID Application: Access Control, Asset Management, Time & Attendance, Vehicle Tracking, Event Management End User: Commercial Buildings, Hospitality Facilities, Educational Institutions, Government Facilities, Residential Complexes |
| Companies Covered | ASSA ABLOY, Allegion, dormakaba Group, SALTO Systems, Honeywell International, Schlage, Spectrum Brands Holdings, Onity Inc., Stanley Black & Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Locks Market Strategic Shifts & Innovations
RFID lock architecture is bifurcating between ultra-low-power standalone units for residential retrofits and mesh-networked platforms that support real-time credential revocation in enterprise environments.
Bluetooth Low Energy radio modules are miniaturizing to single-chip implementations that fit within standard cylindrical lock form factors. Student housing operators in the United Kingdom are deploying these compact units at scale across aging dormitory stock. The technology is miniaturizing hardware footprints sufficiently to eliminate separate control boxes, collapsing installation labor to under thirty minutes per door.
The EU AI Act imposes algorithmic transparency requirements on biometric authentication subsystems embedded in smart locks. Manufacturers must document decision logic for facial recognition or fingerprint matching modules sold into European facilities. Hospitality chains operating across France and Spain are accelerating procurement of non-biometric RFID-only configurations to sidestep compliance complexity.
Facility managers are unbundling hardware procurement from installation and maintenance contracts. Large commercial real estate investment trusts now source locks directly from manufacturers while contracting regional security integrators for deployment only. This disintermediation is most pronounced in Germany and the Netherlands, where standardized DIN door preparations reduce installation variability and enable direct volume purchasing.
RFID Locks Market Segmentation
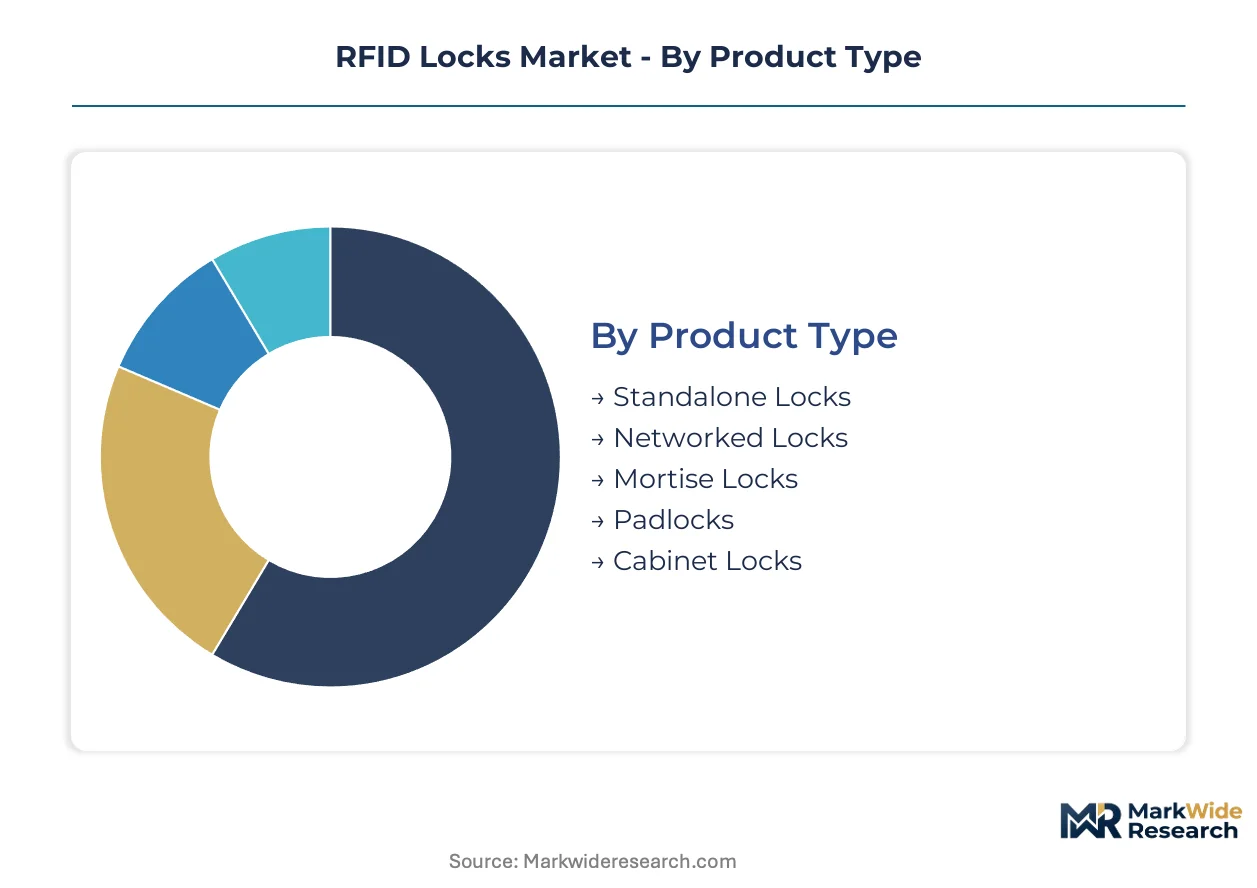
RFID lock procurement patterns diverge sharply between retrofit contractors seeking drop-in mechanical replacements and new construction developers specifying networked infrastructure. Understanding these segment boundaries clarifies where mobile credential substitution poses immediate threat versus where hardware-software integration creates stickier demand.
Product Type:
Standalone locks face the most acute substitution pressure from smartphone-based BLE credentials, while networked platforms defend position through real-time revocation capabilities that mobile wallets cannot replicate.
- Standalone Locks:Battery-powered units with offline credential validation store access permissions locally without network dependency. Hospitality retrofits across Germany and Spain favor these for rapid guest room deployment where IT infrastructure remains absent. Mobile wallet substitution threatens volumes in premium segments as BLE modules miniaturize.
- Networked Locks:Mesh-connected or hardwired platforms enable instantaneous credential updates and centralized audit logging. New commercial construction in the United States and Netherlands specifies these for compliance with tightening building codes around access traceability. Installation complexity limits retrofit applicability.
- Mortise Locks:Narrow-body electronic platforms accommodate legacy door preparations without structural modification. European commercial retrofit demand concentrates here.
- Padlocks:Weather-resistant housings protect RFID readers in outdoor logistics and utility applications. Construction site asset security drives replacement cycles.
- Cabinet Locks:Compact form factors secure server racks, medical storage, and retail fixtures. Healthcare compliance requirements favor audit-capable electronic units over mechanical alternatives.
Standalone locks anchor the volume base while networked locks gain share at the steepest rate.
Technology:
Cost tier stratification separates credential technologies, with passive RFID dominating shipment volumes through minimal per-unit cost while ultra-high frequency commands premium positioning in vehicle and yard logistics.
- Passive RFID:Credentials harvest operating power from reader electromagnetic fields, eliminating onboard batteries. ISO/IEC 14443 proximity specifications at 13.56 MHz enable interoperability across multi-vendor campus deployments in the United Kingdom and France. Standardization reduces institutional buyer lock-in risk.
- Ultra-High Frequency RFID:860–960 MHz protocols deliver extended read ranges for vehicle access and logistics yard applications. Corporate campuses in the United States deploy these for seamless parking-to-building entry sequences. FCC emission profiles govern reader deployment in unlicensed spectrum.
- Active RFID:Battery-powered tags broadcast signals without reader proximity. Cold chain monitoring and high-value asset tracking consume limited volumes.
- Semi-Passive RFID:Onboard sensors supplement passive backscatter with environmental data logging. Pharmaceutical storage compliance applications favor these for temperature monitoring integration.
- High-Frequency RFID:13.56 MHz protocols distinct from proximity standards support NFC smartphone interoperability. Mobile wallet convergence threatens dedicated credential demand.
Passive RFID anchors the volume base while ultra-high frequency RFID climbs the fastest on vehicle access convergence.
Application:
Application maturity varies by compliance intensity, with access control representing the most penetrated use case while event management remains experimental.
- Access Control:Door entry authentication generates the majority of installed base revenue. GDPR audit trail requirements in European facilities directly favor RFID over mechanical master key systems. Hospitality chains in Germany eliminate physical key handoffs to satisfy post-pandemic hygiene protocols.
- Asset Management:Real-time location systems track high-value equipment through facility zones. Healthcare and manufacturing verticals deploy these for capital expenditure protection.
- Time & Attendance:Credential validation timestamps record worker entry and exit for payroll integration. Construction and logistics sites favor ruggedized readers.
- Vehicle Tracking:UHF readers authenticate fleet entry at gates and loading docks. Corporate campus parking integration drives specification.
- Event Management:Temporary credential issuance controls attendee movement through venue zones. Music festivals and conference centers pilot disposable wristband formats.
Access control anchors the volume base while asset management expands most quickly on healthcare compliance investment.
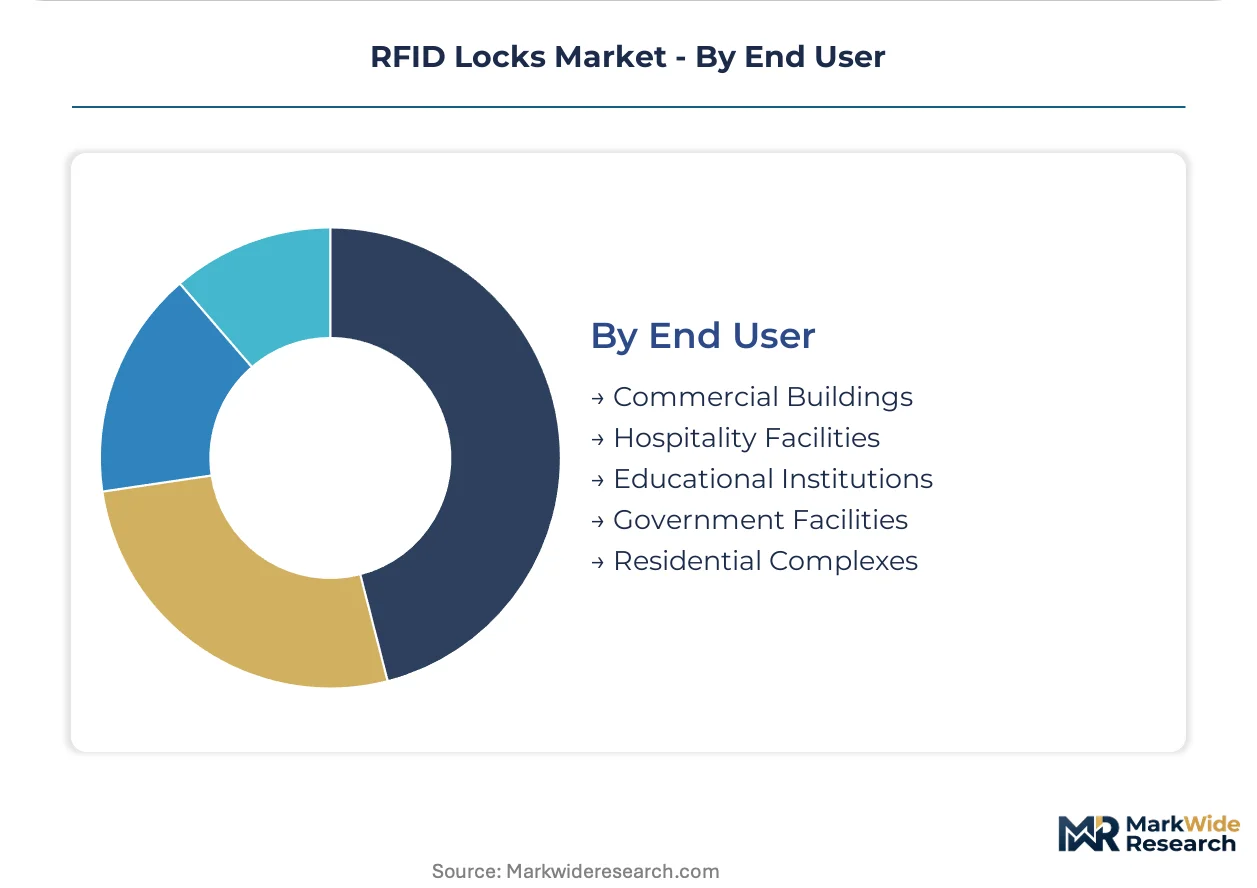
End User:
Customer type segmentation reveals diverging procurement sophistication, with commercial real estate investment trusts disintermediating distributors while educational institutions remain captive to integrator relationships.
- Commercial Buildings:Office and retail facilities specify networked locks for tenant turnover flexibility. Large REITs in Germany and the Netherlands source hardware directly from manufacturers while contracting regional integrators for installation only.
- Hospitality Facilities:Hotels and resorts retrofit guest room entry systems to eliminate physical key handoffs. United States and German chains lead contactless mandate compliance.
- Educational Institutions:Campuses favor battery-operated wireless locks where IT cabling remains absent. SALTO Systems specializes in this segment across European and Indian markets.
- Government Facilities:Federal and municipal buildings require FICAM-compliant credential interoperability. Procurement cycles extend on security clearance requirements.
- Residential Complexes:Multi-family housing deploys standalone locks for amenity access and unit entry. Cost sensitivity limits specification to economy-tier hardware.
Commercial buildings anchor the volume base while educational institutions gain share fastest on India smart city campus buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC emission standards govern RFID reader deployment across the United States, creating the regulatory baseline that shapes product certification cycles for North American market entry. Facility managers in Germany and the Netherlands source hardware directly from manufacturers while contracting regional integrators for installation only.
United States
Hospitality chains retrofit guest room entry systems to eliminate physical key handoffs and satisfy post-pandemic hygiene protocols. FCC regulations govern radio emission profiles for RFID readers operating in unlicensed spectrum. Major metropolitan corridors face certified electronic security technician shortages that extend project timelines.
Germany
Commercial real estate investment trusts disintermediate distributors through standardized DIN door preparations that reduce installation variability. GDPR audit trail requirements mandate time-stamped access logging for facility compliance. The Rhine-Ruhr industrial cluster anchors European demand for narrow-body electronic mortise platforms.
India
Government-funded smart city initiatives create greenfield demand for networked battery-operated locks where IT cabling remains absent. BIS standards shape interoperability mandates for radio equipment specifications. Educational campuses in Maharashtra and Karnataka deploy wireless online access control systems at scale.
United Kingdom
Student housing operators deploy compact BLE-enabled units across aging dormitory stock, collapsing installation labor to under thirty minutes per door. ISO/IEC 14443 proximity specifications enable interoperability across multi-vendor campus deployments. London and Southeast England concentrate institutional buyer procurement sophistication.
Netherlands
Facility managers unbundle hardware procurement from installation and maintenance contracts, sourcing locks directly from manufacturers. ETSI EN standards for radio equipment shape market access requirements. The Randstad metropolitan region leads European adoption of real-time credential revocation capabilities in networked platforms.
RFID Locks Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hardware-software integration creating stickier demand in enterprise segments while standalone units face acute substitution pressure. The competitive terrain stratifies across captive hardware ecosystems, narrow-body retrofit specialists, and wireless battery-operated platforms. Two dominant competitive moves are reshaping positioning: direct volume purchasing by large real estate investment trusts and geographic expansion into India educational campus buildouts.
Among integrated hardware-software providers, ASSA ABLOY and dormakaba Group exemplify the captive ecosystem archetype that controls supply continuity for large hospitality rollouts. SALTO Systems occupies a specialist position within the wireless online access control segment. These three anchors represent divergent strategic postures across retrofit versus new construction, networked versus standalone, and European versus emerging market penetration vectors.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion |
| dormakaba Group |
| SALTO Systems |
| Honeywell International |
| Schlage |
| Spectrum Brands Holdings |
| Onity Inc. |
| Stanley Black & Decker |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day microcontroller lead times from East Asian foundries concentrate procurement leverage among integrated hardware providers while compressing margins for standalone lock assemblers dependent on spot-market component sourcing. This inventory compression directly shapes tiered pricing power, with captive supply ecosystems commanding premium positioning against price-sensitive retrofit contractors.
Pricing Analysis
German and Dutch commercial real estate investment trusts pay fifteen to twenty percent premiums over United States hospitality chains for identical networked lock hardware due to bundled EU AI Act compliance documentation and DIN-standardized installation protocols. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in economy-tier standalone units is intensifying because copper and rare earth magnet volatility erodes solenoid actuator margins. Small-facility retrofit contractors exhibit highest price sensitivity, while government facilities demonstrate lowest sensitivity due to FICAM compliance mandates.
Supply Chain Analysis
China and Taiwan anchor RFID reader module fabrication and microcontroller wafer supply, while Germany and the United States concentrate precision solenoid and motorized bolt manufacturing. Raw material dependencies center on copper windings, neodymium rare earth magnets, and FR-4 printed circuit board substrates. Single-source vulnerability in 13.56 MHz proximity chipsets from concentrated East Asian foundries threatens production continuity. Distribution runs through manufacturer-direct channels for large REITs and tier-one security integrators, with regional distributors serving fragmented retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID lock market fragmentation creates multiple specialization niches as contactless credential migration splits demand between offline standalone retrofits and real-time networked infrastructure. Building operators unbundling procurement from installation generates openings for component specialists and compliance service providers.
For Market Incumbents: Compound hardware-software integration advantages by embedding EU AI Act algorithmic transparency documentation into standard product bundles, neutralizing compliance complexity as a competitive wedge. Deepen backward integration into solenoid actuator manufacturing to insulate margins from copper and rare earth price volatility. Prioritize certification pre-qualification with BIS for India smart city campus buildouts before local competitors establish reference installations. For New Entrants and Emerging Players: FCC Part 15 pre-certification fast-tracks unlock United States hospitality retrofit opportunities where incumbent lead times extend project timelines. Target educational institutions in Maharashtra and Karnataka with battery-operated wireless platforms that bypass absent IT infrastructure. Position through direct contracting with government smart city authorities, bypassing established integrator relationships that dominate commercial building segments. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial hardware parents seeking to divest non-core electronic security divisions with stranded technology portfolios. Five-to-ten-year viability hinges on credential protocol diversification beyond passive RFID toward mobile wallet interoperability. Monitor BLE module miniaturization cost curves as inflection indicator for standalone lock substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Bundling | Algorithmic transparency documentation creates recurring revenue streams for system integrators serving French and Spanish hospitality chains. |
| India BIS Certification Fast-Track | Pre-qualified hardware captures government-funded smart city campus buildouts in Maharashtra and Karnataka before local competition. |
| Solenoid Actuator Backward Integration | In-house copper winding and magnet sourcing insulates margins from commodity volatility compressing economy-tier standalone producers. |
| Mobile Wallet Protocol Integration | BLE-NFC hybrid modules defend against smartphone credential substitution threatening premium commercial segment volumes. |
| Direct REIT Procurement Channel | Bypassing distributor markups captures volume from German and Dutch commercial real estate investment trusts unbundling installation contracts. |
Research Approach
Operator-level perspectives from facility managers at commercial real estate investment trusts, hospitality security directors, educational campus IT administrators, certified electronic security technicians, and regional security integrators anchored the qualitative base. Primary interview insights combined with secondary validation from FCC equipment authorization databases, ETSI EN radio equipment standards filings, BIS certification registries, and customs trade data for RFID reader module imports. Bottom-up shipment estimates by product type and technology tier triangulated against top-down construction spending and hospitality capex projections.
Sensitivity analysis tested forecast robustness across semiconductor supply disruption scenarios and copper price volatility bands over the projection horizon. Segmentation modeling spanned product architecture, credential technology frequency band, application use case, and end-user procurement sophistication. CAGRs derived from logistic diffusion curves fitted to replacement cycle compression observations and greenfield deployment rates. Industry-specific inputs included certified technician labor availability indices and DIN door preparation standardization penetration by country.
Decision-makers should treat outputs as directional under stable regulatory enforcement of GDPR audit trail mandates and continued East Asian foundry supply continuity; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in mobile wallet adoption curves and EU AI Act implementation guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Access Control Readers Market
Access Control Systems
South Korea Access Control Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
North America Access Control Market
Access Control Systems
Germany Access Control Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Port Security Systems Market