
 Acousto-Magnetic (AM) Security Systems Market | 2026-2036
Acousto-Magnetic (AM) Security Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Acousto-Magnetic (AM) Security Systems Market Insights
Modular hardware-software bundling is decoupling across the AM security landscape, letting retailers mix tags from one vendor with detection gates from another. Checkpoint Systems leverages its manufacturing scale to dominate integrated system deployments in big-box retail. Sensormatic Solutions anchors its position through deep channel control over North American pharmacy and grocery chains. Nedap differentiates by specializing in open-protocol controllers that interoperate with third-party alarm and video systems.
Acousto-magnetic security systems detect ferromagnetic strips or tags using tuned resonant circuits operating at 58 kHz, triggering alarms when unpaid merchandise passes through detection pedestals at store exits. The technology serves primarily as an electronic article surveillance layer against shoplifting and internal theft in commercial environments. Tags and detectors together capture the bulk of component value, with passive tag volumes running far ahead of active and hybrid alternatives. Retail application leads absolute demand, though logistics and healthcare segments are expanding fastest as warehouses and hospitals adopt AM for inventory protection and pharmaceutical diversion control.
FCC certification requirements in the United States govern electromagnetic emissions from detection pedestals, while CE marking and RoHS compliance shape product access across European Union member states. Retailers in Germany face additional KBA-equivalent electromagnetic compatibility scrutiny for high-throughput gateway installations. Stakeholders must monitor how convergence between AM detection and AI-powered video analytics reshapes procurement criteria and vendor selection timelines.
Market Dynamics
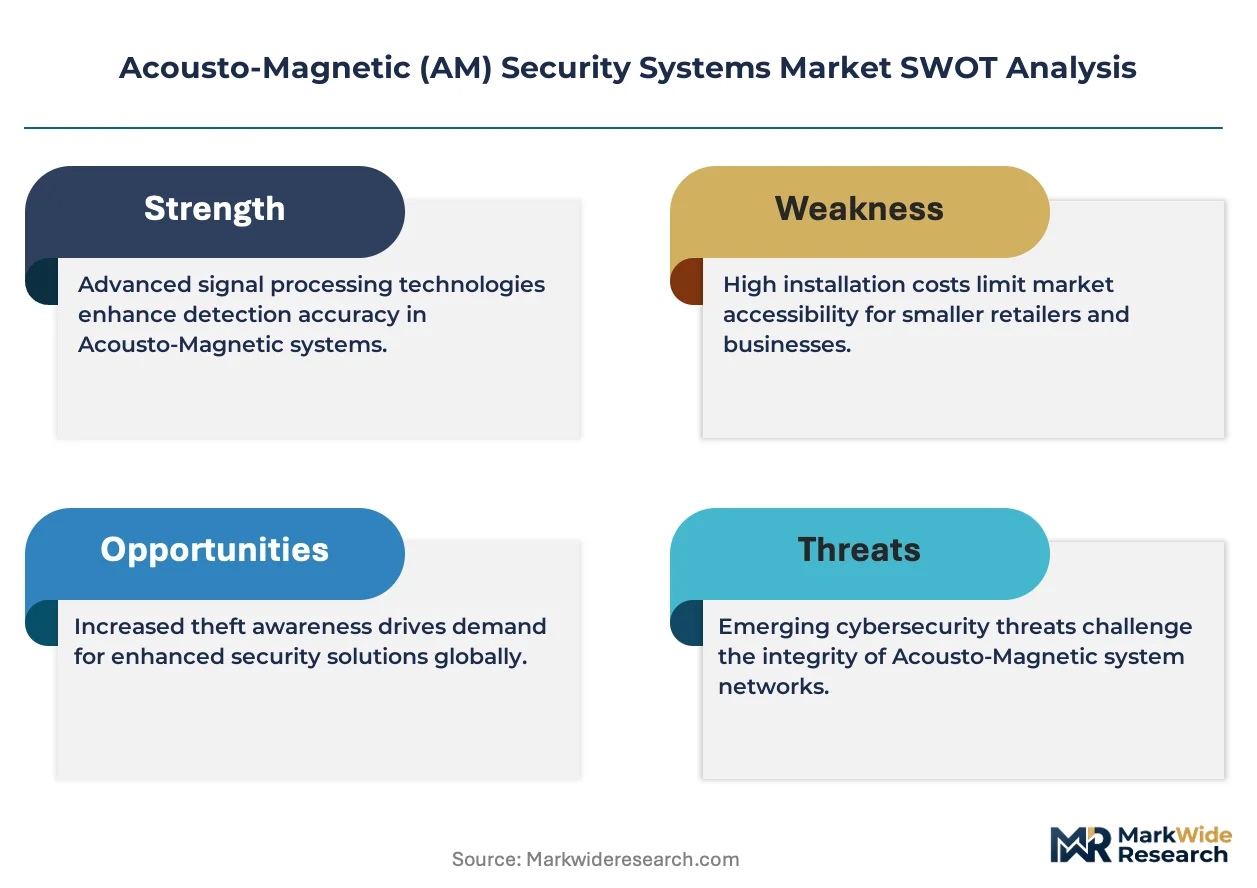
Modular interoperability between AM detection gates and third-party tag vendors is fragmenting procurement decisions across retail chains, forcing incumbent suppliers to unbundle hardware-software stacks and compete on component-level specifications rather than integrated system lock-in.
Growth Catalysts
- Organized Retail Crime Escalation:United States big-box retailers are expanding loss-prevention capital expenditure to counter coordinated theft rings targeting high-value electronics and pharmaceuticals.
- RFID Convergence:Dual-frequency AM-RFID hybrid tags enable unified inventory tracking and theft detection, reducing infrastructure duplication for warehouse operators.
- REACH and RoHS Compliance:European Union environmental mandates are accelerating replacement cycles for legacy electromagnetic systems containing restricted heavy metals.
Market Restraints
- Copper and Ferrite Price Volatility:Resonant circuit components in AM tags face input cost pressure from commodity metal markets, compressing tag manufacturer margins.
- Electromagnetic Interference Limitations:Detection accuracy degrades near high-powered RF equipment, restricting deployment in airports and industrial facilities with dense wireless infrastructure.
- RFID Substitution Threat:Item-level RFID tracking offers superior inventory visibility, diverting capital from pure-play AM installations in apparel retail.
Strategic Opportunities
- Healthcare Pharmaceutical Diversion Control:Hospital pharmacies and drug distribution centers represent underpenetrated demand for tamper-evident AM tagging of controlled substances.
- India Retail Modernization:Organized retail expansion in tier-2 Indian cities creates first-mover advantage for AM infrastructure deployment ahead of indigenous loss-prevention supply chains.
- AI-Powered Video Analytics Integration:Convergence between AM alarm triggers and computer-vision verification reduces false positives, creating premium pricing tiers for integrated solutions.
Industry Challenges
- FCC Certification Timeline Compression:United States retailers demand faster pedestal approval cycles for store remodels, straining testing laboratory capacity and delaying rollout schedules.
- Legacy Electromagnetic System Migration:Pharmacy chains face integration complexity when retrofitting existing store footprints with AM detection zones without disrupting 24-hour operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acousto-Magnetic (AM) Security Systems Market |
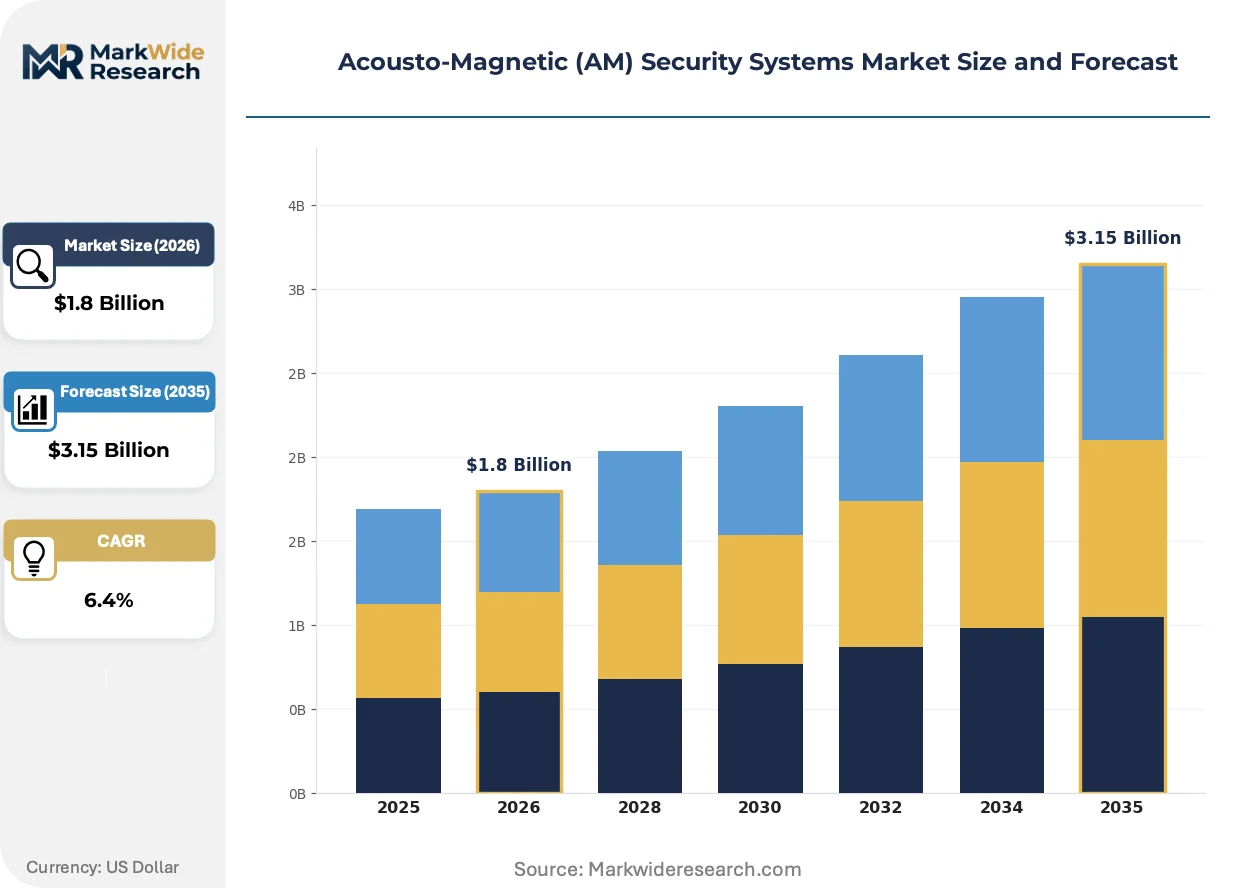
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active, Passive, Hybrid, Integrated Component: Tags, Detectors, Controllers, Alarms Application: Retail, Logistics, Manufacturing, Healthcare End User: Business, Government, Home, Education |
| Companies Covered | Checkpoint Systems, Sensormatic Solutions, Nedap, Tyco Retail Solutions, Gunnebo Gateway, Ketec, All-Tag Corporation, Sentry Technology Corporation, WG Security Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acousto-Magnetic (AM) Security Systems Market Trends and Innovations
AM security infrastructure is converging with adjacent detection and analytics layers, transforming standalone anti-theft gates into data-collection nodes that feed broader retail operations intelligence.
Cloud-connected AM pedestals are integrating real-time alarm telemetry with store traffic analytics, enabling loss-prevention teams to correlate theft events with customer flow patterns. United States pharmacy chains are piloting these systems to optimize staffing during high-risk periods. The technology is integrating previously siloed security and operations functions, compressing vendor margins on standalone hardware.
CE marking revisions under the EU Radio Equipment Directive are tightening electromagnetic emission testing protocols for detection gates deployed in high-throughput retail environments. German retailers face additional KBA-equivalent scrutiny for gateway installations exceeding specified transaction volumes. European pharmacy and grocery chains are responding by consolidating procurement around suppliers with pre-certified modular platforms.
Buyer concentration among national retail banners is compressing vendor negotiation cycles and unbundling service contracts from hardware purchases. Large United States big-box operators now separately procure tags, gates, and maintenance services, fragmenting historical single-source relationships. This pattern is most visible in apparel retail, where private-label tag manufacturing is migrating in-house to capture component margin.
Acousto-Magnetic (AM) Security Systems Market Segmentation
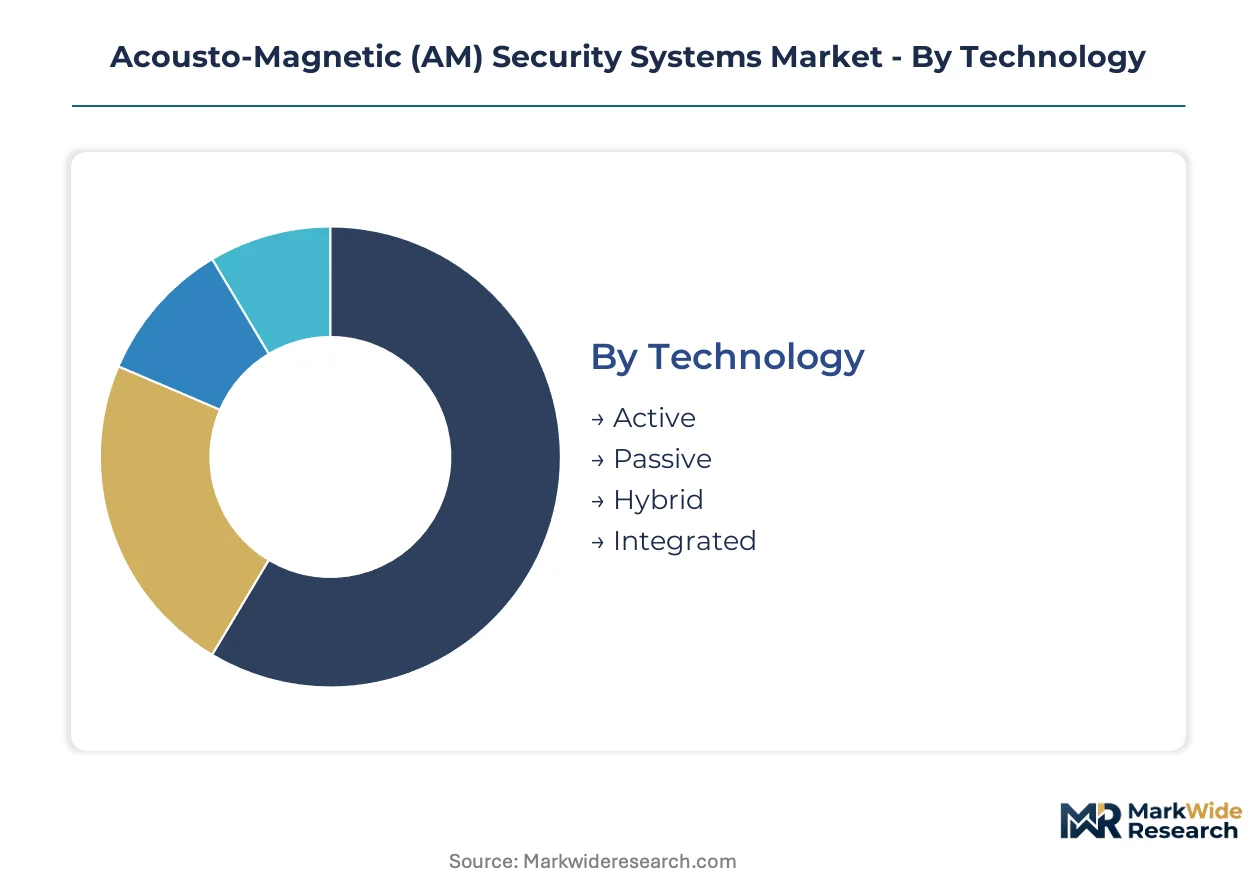
AM security procurement patterns diverge sharply by operational scale and compliance burden. Large retail banners prioritize integrated detection stacks, while smaller operators optimize for component modularity and tag interchangeability.
Technology:
Cost tier separates adopters in this dimension, with capital intensity and maintenance burden driving distinct buyer profiles.
- Passive:Tuned resonant circuits at 58 kHz require no onboard power, minimizing per-unit cost. United States pharmacy chains deploy these at scale for high-volume pharmaceutical tagging, constrained by copper and ferrite commodity price swings.
- Integrated:Unified AM-RFID hybrid architectures collapse theft detection and inventory tracking into single infrastructure. Warehouse operators in Germany favor these under REACH-mandated replacement cycles for legacy electromagnetic systems.
- Active:Battery-powered transmitters enable extended detection ranges for high-value asset protection.
- Hybrid:Dual-mode configurations combine passive resonant elements with active verification layers.
Volume sits with Passive; growth tilts toward Integrated.
Component:
Supply concentration determines margin capture, with tag manufacturing fragmenting fastest as retailers bring label production in-house.
- Tags:Ferromagnetic strips and labels constitute the highest-volume component category. Apparel retailers in the United States increasingly source private-label tags directly, bypassing traditional system integrators to capture component margin.
- Detectors:Pedestal-mounted resonant detection gates anchor system value. FCC certification timelines in the United States constrain deployment velocity for store remodels, compressing vendor delivery schedules.
- Controllers:Signal processing units manage alarm logic and system diagnostics.
- Alarms:Audio-visual alert mechanisms complete the detection chain.
Procurement concentrates in Tags; margin pressure hits Detectors hardest.
Application:
Maturity gaps between verticals create divergent pricing power, with established retail segments facing steeper discount pressure than emerging healthcare deployments.
- Retail:Electronic article surveillance against shoplifting dominates absolute demand. Big-box operators across North America and Europe are expanding loss-prevention budgets as organized retail crime escalates, though RFID substitution diverts some apparel sector capital.
- Healthcare:Pharmaceutical diversion control and tamper-evident tagging of controlled substances represent the steepest expansion trajectory. Hospital pharmacies in the United States pilot AM tagging for high-value medications under FDA-tracked distribution requirements.
- Logistics:Warehouse inventory protection applications are expanding fastest among third-party fulfillment operators.
- Manufacturing:Component theft prevention on production floors drives specialized detection zone configurations.
Revenue weight rests with Retail; Healthcare climbs the fastest.
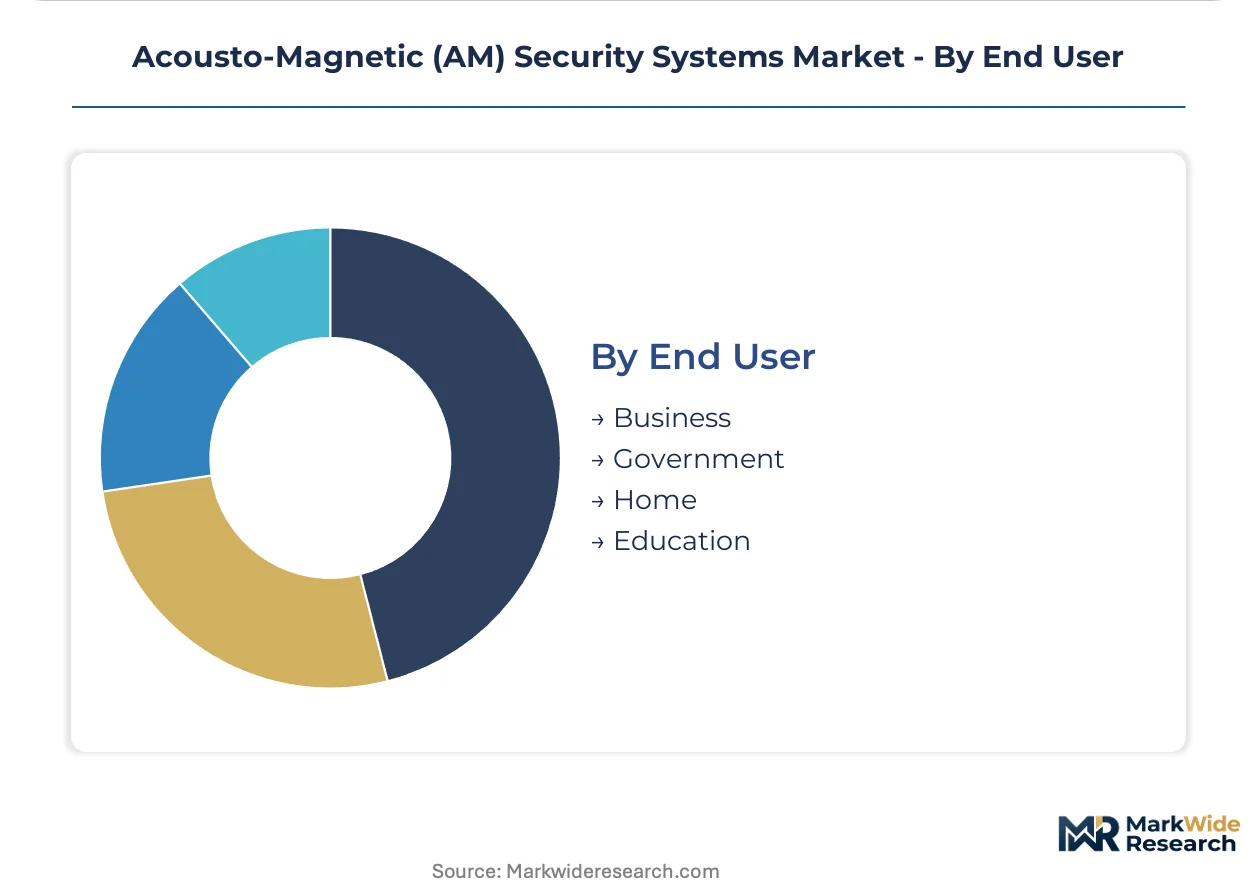
End User:
Customer type dictates contract structure, with government and education procurement favoring multi-year maintenance bundles over transactional hardware purchases.
- Business:Commercial retail, logistics, and healthcare entities constitute the core demand base. Pharmacy chains require 24-hour operational continuity during AM retrofits, complicating installation scheduling and integration timelines.
- Government:Public-sector procurement for municipal facilities and state-operated retail follows formalized bidding protocols with extended vendor qualification periods.
- Education:Campus bookstores and library systems deploy scaled-down detection infrastructure.
- Home:Residential applications remain minimal, limited to high-net-worth private collections.
Deployment scale favors Business; contract duration extends longest for Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of AM detection hardware concentrates in Germany and China, while consumption gravity sits with United States pharmacy chains and Western European retail banners upgrading legacy electromagnetic infrastructure.
United States
Big-box retailers and pharmacy chains are replacing legacy electromagnetic systems with next-generation AM platforms as organized retail crime escalates. FCC certification requirements govern electromagnetic emissions from detection pedestals, compressing vendor delivery schedules for store remodels. Loss-prevention capital expenditure expansion concentrates in the Midwest and Southeast retail corridors.
Germany
High-throughput retail environments drive demand for pre-certified modular platforms under tightened CE marking protocols. KBA-equivalent electromagnetic compatibility scrutiny applies to gateway installations exceeding specified transaction volumes. Industrial manufacturing clusters in Baden-Württemberg and Bavaria anchor European production of resonant circuit components.
China
Component manufacturing for ferromagnetic strips and detection pedestals supplies global AM system integrators. MIIT standards and GB certification frameworks shape product specifications for domestic and export markets. Yangtze River Delta electronics manufacturing hubs export tuned resonant circuits to North American and European system assemblers.
India
Organized retail expansion in tier-2 cities creates first-mover opportunity for AM infrastructure deployment ahead of indigenous loss-prevention supply chain maturation. BIS certification requirements govern electromagnetic equipment imports, favoring early entrants with tested product portfolios. Maharashtra and Karnataka retail corridors pilot AM tagging for apparel and pharmaceutical distribution.
United Kingdom
Pharmacy and grocery chains consolidate procurement around suppliers with pre-certified modular platforms following post-Brexit regulatory realignment. CE marking continuity agreements and UKCA marking transitions create dual-compliance burdens for detection gate deployments. London and Southeast England retail density drives concentrated demand for integrated AM-RFID hybrid architectures.
Acousto-Magnetic (AM) Security Systems Market Competitive Landscape
The competitive structure tilts toward integrated system providers with manufacturing scale advantages. Checkpoint Systems leverages its production footprint to dominate big-box retail deployments, while Sensormatic Solutions anchors position through channel control over pharmacy and grocery chains. Three archetypes define the field: vertically integrated hardware-software bundlers, open-protocol specialists enabling third-party interoperability, and component-focused tag manufacturers. Consolidation pressure is forcing unbundling of historical single-source relationships, while procurement fragmentation is compressing service contract margins.
Within the integrated-system tier, Checkpoint Systems and Sensormatic Solutions exemplify scale-driven market presence, occupying positions that reflect manufacturing depth and channel density respectively. Nedap represents the open-protocol specialist archetype, differentiating through controller interoperability with third-party alarm and video systems. These three anchors illustrate how vendor strategies are diverging between bundled platform dominance and modular component specialization.
| Leading Market Players |
|---|
| Checkpoint Systems |
| Sensormatic Solutions |
| Nedap |
| Tyco Retail Solutions |
| Gunnebo Gateway |
| Ketec |
| All-Tag Corporation |
| Sentry Technology Corporation |
| WG Security Products |
| Others |
Pricing and Supply Chain Analysis
Buyer unbundling of hardware-software procurement across United States pharmacy chains is forcing AM tag manufacturers to absorb copper and ferrite commodity volatility while competing on component-level specifications rather than integrated system margins.
Pricing Analysis
Margin tightening in passive tag tiers reflects apparel retailers' migration toward private-label sourcing and direct component procurement. Three-tier pricing structure across FCC-certified, CE-marked, and uncertified economy levels separates pharmacy chains willing to pay certification premiums from cost-optimized logistics operators. Cost-down pressure on detection pedestals accelerates because big-box retailers now separately negotiate gate hardware, installation, and maintenance services. Warehouse operators exhibit highest price sensitivity; healthcare pharmaceutical buyers show lowest due to diversion-control compliance requirements.
Supply Chain Analysis
FCC and CE certification gating concentrates resonant circuit manufacturing in Germany, China, and select United States facilities with pre-approved testing laboratory relationships. Ferromagnetic strip production draws from copper wire, ferrite ceramic cores, and polymer substrate inputs. Single-source vulnerability sits with Yangtze River Delta component suppliers subject to MIIT export protocol shifts. Distribution runs through system integrators serving retail banners, direct OEM procurement by pharmacy chains, and third-party logistics providers retrofitting warehouse infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AM security market sits in a technology-transition phase as integrated AM-RFID hybrid architectures displace standalone electromagnetic systems across retail and logistics verticals.
For Market Incumbents: Extend cloud-connected pedestal telemetry capabilities to capture recurring software revenue streams as hardware margins compress. Deepen backward integration into ferrite core production to offset copper price volatility threatening tag manufacturing economics. Anchor channel control over pharmacy chains through 24-hour retrofit installation capabilities that emerging competitors cannot replicate.
For New Entrants and Emerging Players: Capture healthcare pharmaceutical diversion control deployments where FDA-tracked distribution requirements create compliance-driven demand less sensitive to price competition. Target tier-2 Indian cities ahead of indigenous loss-prevention supply chain maturation under BIS certification frameworks. Lead with open-protocol controller interoperability as a wedge against integrated incumbents' hardware-software bundling.
For Investors and Strategic Acquirers: The window for entry favors component-specialist tag manufacturers with captive ferrite sourcing and pre-certified modular platforms. Long-term viability hinges on convergence with AI-powered video analytics rather than standalone detection hardware. Monitor FCC certification timeline compression as the inflection signal indicating whether testing laboratory capacity constraints will consolidate procurement around incumbents or fragment toward agile specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| AM-RFID Hybrid Platform Development | Unified infrastructure collapses theft detection and inventory tracking for warehouse operators under REACH mandates. |
| Cloud Telemetry Integration | Real-time alarm data feeds loss-prevention analytics correlating theft events with customer flow patterns. |
| Healthcare Certification Investment | FDA-tracked pharmaceutical distribution requirements create premium pricing tiers for diversion-control tagging. |
| India Market Entry | Tier-2 retail expansion ahead of indigenous supply chain maturation offers first-mover positioning under BIS rules. |
| Open-Protocol Controller Specialization | Interoperability with third-party alarm and video systems fragments historical single-source vendor relationships. |
Research Methodology
Multi-period observation of loss-prevention capital expenditure flows, FCC certification timeline data, and copper-ferrite commodity price movements anchored the trend analysis, supplemented by interviews with loss-prevention executives at pharmacy chains, retail category buyers, AM system integration specialists, and resonant circuit manufacturing engineers. Secondary validation drew from SEC filings of public retail banners, FCC equipment authorization databases, ECHA REACH substance restriction updates, and trade customs records for ferrite component flows. Bottom-up tag volume estimates and top-down retail infrastructure spending projections were triangulated to constrain forecast variance.
Input-output matrices mapped technology adoption (passive, integrated, active, hybrid), component category (tags, detectors, controllers, alarms), application vertical (retail, healthcare, logistics, manufacturing), and end-user type (business, government, education) across the projection horizon. CAGRs were derived from segment-level growth rate differentials applied to base-year market sizing. Forecast inputs included pharmacy chain retrofit schedules under organized retail crime response budgets and warehouse operator AM-RFID hybrid adoption curves under inventory visibility investment programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to RFID substitution rates in apparel retail and copper price volatility in resonant circuit manufacturing. Forecasts reflect documented assumptions regarding pharmacy chain loss-prevention budget expansion and European electromagnetic system replacement cycles. A model refresh is warranted upon material change in FCC certification processing timelines or REACH substance restriction amendments affecting ferrite core compositions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
China Access Control Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Locks Market
Access Control Systems
Asia-Pacific Proximity Access Control Market