
 Southeast Asia Surface Treatment Chemicals Market | 2026-2036
Southeast Asia Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Surface Treatment Chemicals Market Analytics
Indonesian specialty chemical producers is realigning capacity toward phosphate conversion coatings for automotive pretreatment. Henkel AG & Co KGaA leverages its Bangkok technical center to anchor regional formulation support. Nihon Parkerizing Co Ltd dominates Japanese OEM supply chains across Thailand and Indonesia. PPG Industries Inc competes through waterborne pretreatment systems tailored to tropical corrosion environments.
Surface treatment chemicals comprise formulated acids, alkalis, solvents, and surfactants engineered to modify substrate properties through cleaning, coating, passivation, or corrosion protection processes. These formulations typically operate at controlled pH ranges and temperatures to ensure adhesion, durability, and environmental compliance across metal, plastic, and composite surfaces. Alkalis and acids command the largest product volumes due to their foundational role in degreasing and pickling operations across automotive and electronics sectors. Corrosion protection applications attract premium margins as tropical humidity accelerates substrate degradation rates across Southeast Asian manufacturing hubs.
Thailand's Ministry of Industry enforces wastewater discharge limits that constrain chromate-based formulations, while Indonesia's environmental regulations under MEE alignment pressure suppliers toward trivalent chromium and zirconium-based alternatives. REACH-equivalent substance restrictions from EU trade partners indirectly shape export-oriented facility chemistries across Malaysian and Vietnamese plants. Stakeholders must monitor regulatory divergence between ASEAN member states when standardizing product portfolios across multi-country manufacturing networks.
Market Dynamics
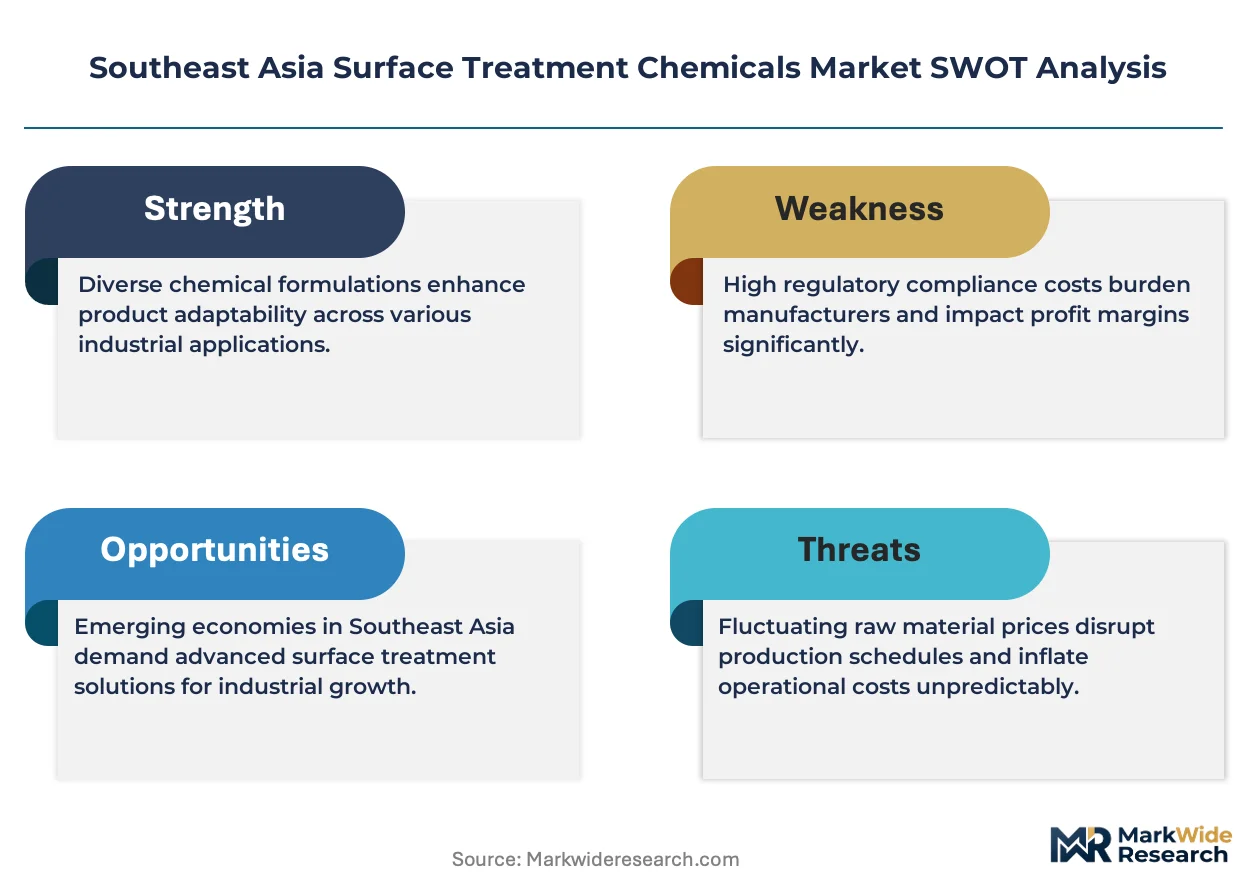
Indonesia's Ministry of Environment and Forestry (MEE) alignment is forcing trivalent chromium and zirconium-based formulations to displace legacy hexavalent chemistries across automotive pretreatment lines. Thai and Vietnamese regulators are tightening discharge limits in parallel, compressing formulation windows for regional suppliers.
Growth Catalysts
- Electronics manufacturing clustering:Vietnam's northern industrial zones are drawing printed circuit board fabricators requiring precision cleaning and plating chemistries at scale.
- Automotive OEM expansion:Thailand's Board of Investment incentives for electric vehicle assembly are triggering new pretreatment line installations.
- REACH-equivalent substance restrictions:EU trade partner compliance requirements are reshaping export-oriented facility chemistries across Malaysian plants.
Market Restraints
- Feedstock volatility:Phosphate and fluoride compound prices fluctuate with Chinese export quotas, squeezing margin stability for Indonesian formulators.
- Supplier concentration:Japanese specialty chemical producers control 70% of automotive pretreatment intellectual property across Thailand.
- Substitution pressure:Dry ice blasting and laser surface preparation are capturing niche applications in precision electronics cleaning.
Strategic Opportunities
- Myanmar industrial corridor development:Yangon-Pathein manufacturing zones lack established chemical supply infrastructure, creating first-mover positioning for pretreatment specialists.
- Waterborne system convergence:Combination of zirconium-based thin-film technologies with electrocoating primers is opening integrated process sales.
- Circular chemistry mandates:Singapore's Resource Sustainability Act is accelerating demand for closed-loop regeneration services.
Industry Challenges
- Process engineering talent scarcity:Surface treatment line optimization requires chemists fluent in both formulation science and automated conveyor controls.
- Legacy system integration:Retrofitting hexavalent chromium lines for trivalent operation demands simultaneous heating, rinsing, and drying modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Surface Treatment Chemicals Market |
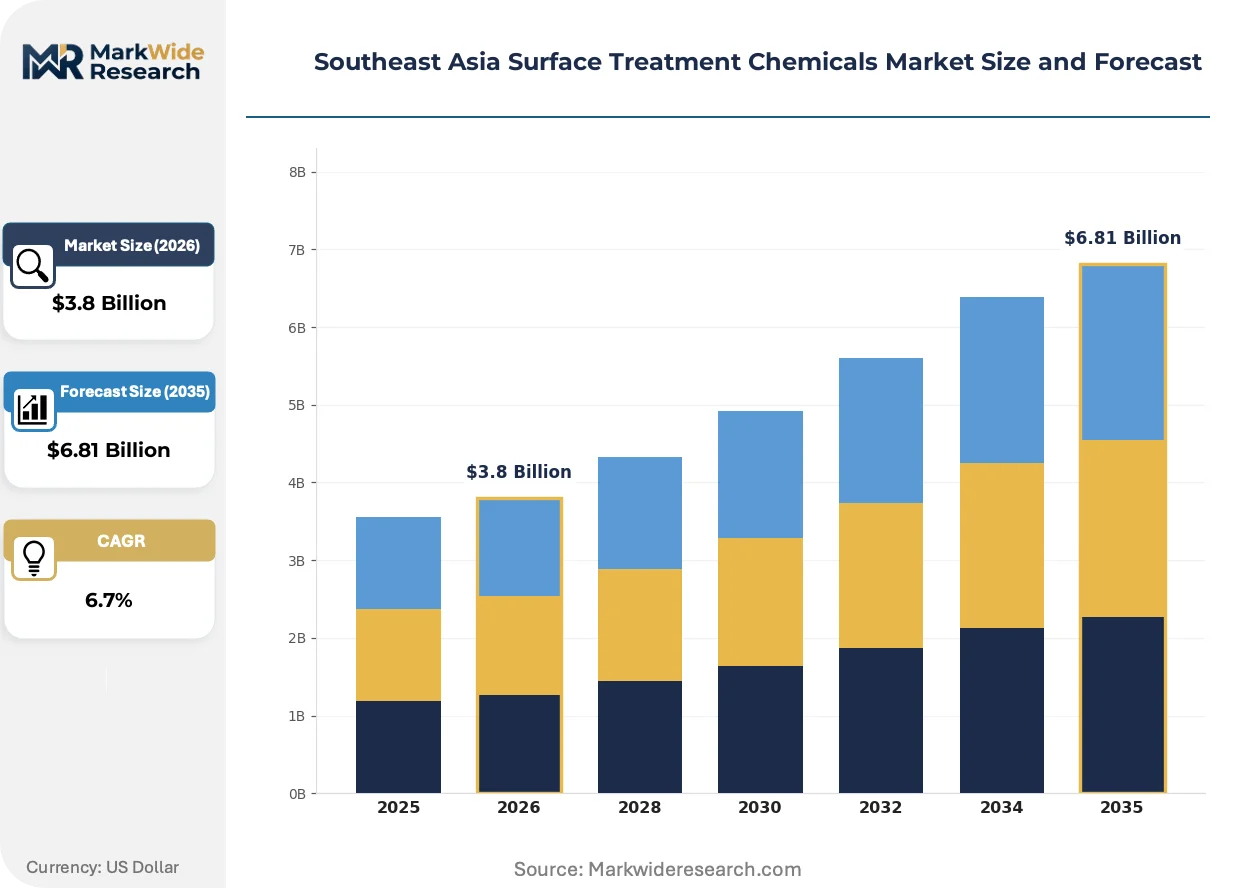
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acids, Alkalis, Solvents, Surfactants End Use Industry: Aerospace, Automotive, Construction, Electronics Application: Coating, Cleaning, Corrosion Protection, Passivation Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | Nihon Parkerizing Co Ltd, Nippon Paint Holdings Co Ltd, Chemetall GmbH, NOF CORPORATION, PPG Industries Inc, Henkel AG & Co KGaA, Siam YUKEN Co., Ltd., Kansai Paint Co., Ltd., JCU CORPORATION, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Surface Treatment Chemicals Market Evolving Landscape
Formulation chemistry is pivoting toward multi-metal compatibility and ambient-temperature operation to reduce energy intensity. Three interconnected developments are compressing traditional process boundaries.
Silane-based thin-film conversion coatings are expanding into automotive body-in-white pretreatment as a phosphate replacement. Thai OEMs are piloting these systems at 15% faster line speeds. The technology is expanding into tropical corrosion protection applications where humidity cycling exceeds 85% annually.
Indonesia's MEE wastewater discharge rules are mandating real-time effluent monitoring for heavy metal content. Metal finishing facilities must install automated sampling systems tied to treatment plant controls. Electronics manufacturers in Batam are responding by consolidating surface treatment to centralized job shops with captive zero-liquid-discharge capability.
Specification-driven procurement is consolidating vendor relationships around full-process chemical management contracts. Tier-1 automotive suppliers are replacing spot chemical purchases with multi-year total-fluid-cost agreements. This pattern is most visible in Thailand's Eastern Economic Corridor where Japanese OEMs enforce supplier reduction programs.
Southeast Asia Surface Treatment Chemicals Market Segmentation
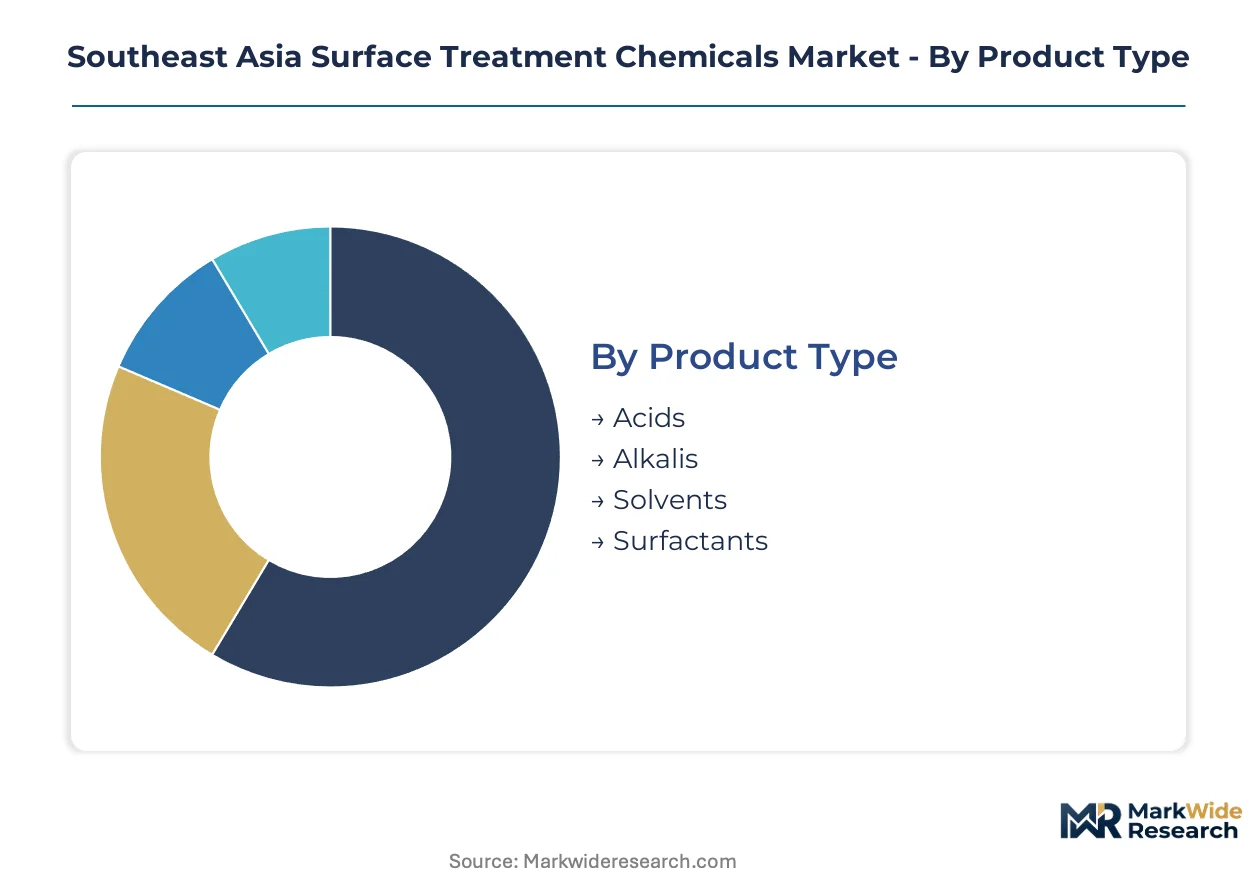
Surface treatment chemicals serve heterogeneous industrial processes requiring distinct formulation chemistries, application temperatures, and regulatory compliance profiles. Segment-level analysis reveals where capital deployment concentrates and which chemistries command premium positioning across Southeast Asian manufacturing hubs.
Product Type:
Acid and alkali formulations demand the heaviest upfront investment in corrosion-resistant storage infrastructure, automated dosing systems, and effluent neutralization capacity across Indonesian and Thai facilities.
- Acids:Sulfuric, hydrochloric, and phosphoric blends enable pickling, etching, and conversion coating activation at controlled concentrations. Automotive OEM pretreatment lines in Thailand's Eastern Economic Corridor consume bulk volumes for phosphate conversion coating preparation. MEE wastewater discharge monitoring is forcing closed-loop acid regeneration investments at Indonesian metal finishing plants.
- Alkalis:Caustic soda and silicated alkaline cleaners remove organic soils and metalworking fluids through saponification and emulsification chemistry. Electronics manufacturers in Vietnam's Bac Ninh province specify low-foam formulations for automated conveyor washing systems. These formulations absorb the largest product volumes due to universal deployment across degreasing operations.
- Solvents:Chlorinated and oxygenated solvents target precision cleaning of electronic substrates where aqueous systems risk moisture damage.
- Surfactants:Non-ionic and anionic wetting agents reduce surface tension in multi-stage cleaning processes.
Alkalis absorb the bulk of installed capacity; acids are expanding most quickly as automotive pretreatment lines scale across Indonesia and Thailand.
End Use Industry:
Automotive and electronics manufacturing concentrate the highest formulation specification requirements and longest supplier qualification cycles.
- Automotive:Body-in-white pretreatment, powertrain component cleaning, and corrosion protection specifications from Japanese OEMs drive phosphate, zirconium, and silane-based chemistry demand. Thai Board of Investment EV incentives are triggering new line installations requiring process chemical management contracts.
- Electronics:Printed circuit board fabrication and semiconductor packaging demand ultra-high-purity cleaning and plating chemistries with metallic impurity controls below parts-per-billion thresholds. Vietnam's northern industrial zones are drawing fabricators requiring precision chemistry supply chains.
- Aerospace:MRO facilities and tier suppliers specify Nadcap-accredited chemistries for airframe and engine component processing.
- Construction:Structural steel surface preparation for protective coating systems consumes bulk alkaline cleaners and conversion coatings.
Automotive anchors current volume demand; electronics is gaining share fastest as Vietnam's PCB clustering accelerates.
Application:
Corrosion protection applications command the widest formulation-to-performance spreads and longest technical service engagements.
- Corrosion Protection:Conversion coatings, sealers, and temporary protectants combat tropical humidity exceeding 85% annual cycling across Southeast Asian manufacturing hubs. Zirconium-based thin-film technologies are displacing legacy phosphate systems in Indonesian automotive lines.
- Cleaning:Alkaline degreasing, acid pickling, and solvent precision cleaning remove soils prior to downstream processing. Real-time effluent monitoring under Indonesia's MEE rules is consolidating cleaning operations to centralized job shops with captive treatment capacity.
- Coating:Surface activation and adhesion promotion chemistries prepare substrates for paint, powder, and electrocoat deposition.
- Passivation:Nitric and citric acid treatments restore chromium oxide layers on stainless steel surfaces.
Cleaning operations absorb the bulk of installed capacity; corrosion protection is climbing the fastest as humidity-driven substrate degradation accelerates specification upgrades.
Distribution Channel:
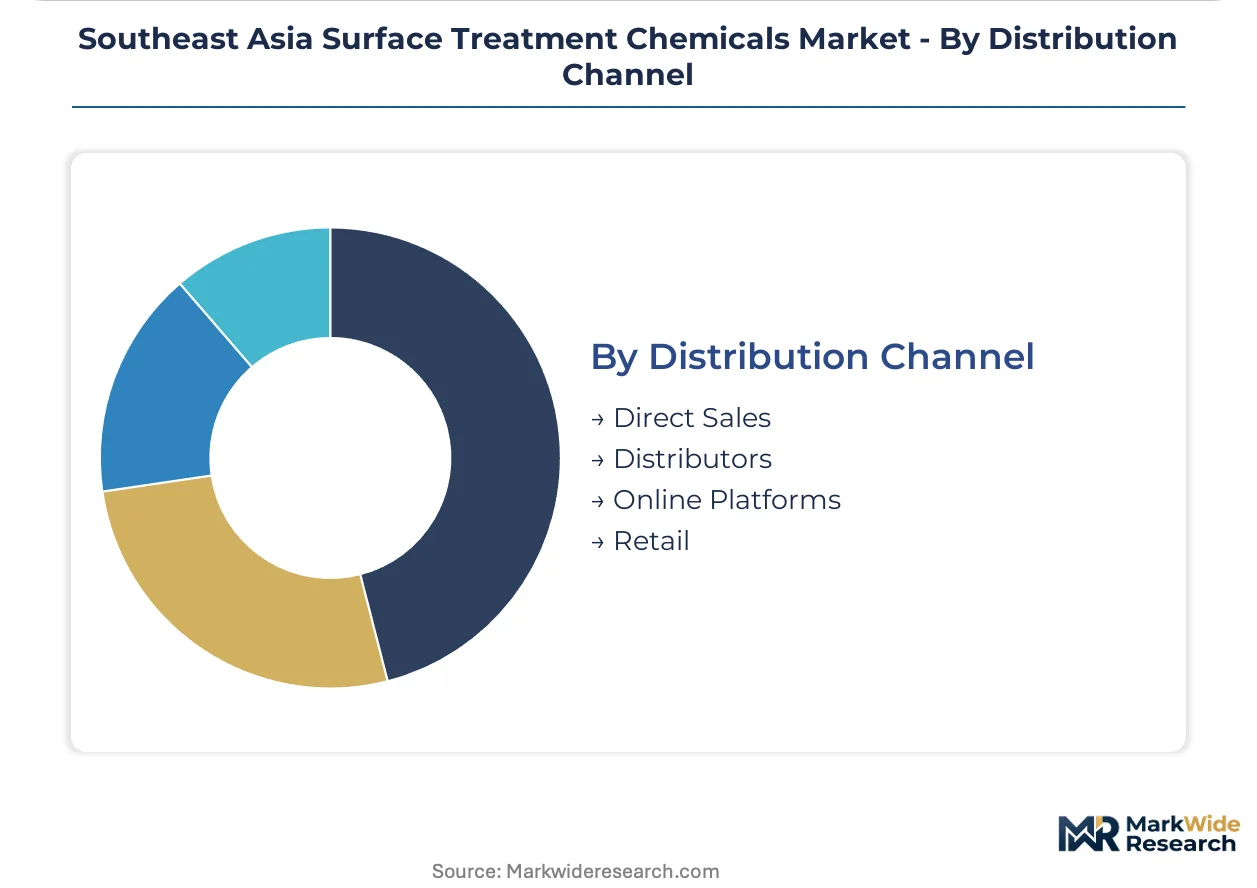
Direct sales relationships capture the highest lifetime value through integrated chemical management and technical service bundling.
- Direct Sales:Formulators deploy technical service engineers for process optimization, inventory management, and waste minimization programs. Tier-1 automotive suppliers in Thailand's Eastern Economic Corridor are consolidating around multi-year total-fluid-cost agreements.
- Distributors:Regional chemical distributors serve fragmented metal finishing and MRO accounts with stocked inventory and local delivery.
- Online Platforms:E-procurement channels are emerging for standardized commodity chemicals and consumables.
- Retail:Small-format packaging reaches maintenance workshops and job shops with intermittent demand patterns.
Direct sales channels anchor the bulk of revenue concentration; distributor networks are expanding most quickly as supplier reduction programs push volume through consolidated intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate rock deposits in Vietnam's northern highlands and Indonesia's central Java anchor regional feedstock supply for conversion coating chemistry. Chinese export quotas on fluoride compounds ripple through Thai and Indonesian formulator margins. Tropical humidity corrosion cycles exceeding 85% annually drive specification premiums across all five markets.
Thailand
Automotive OEM pretreatment lines in Thailand's Eastern Economic Corridor absorb bulk acid and alkali volumes as EV assembly incentives trigger new installations. The Ministry of Industry enforces wastewater discharge limits that constrain chromate-based formulations and accelerate trivalent chromium adoption. Rayong and Chonburi industrial zones concentrate Japanese-tier supplier chemical management contracts.
Indonesia
Phosphate conversion coating demand from automotive body-in-white operations is realigning specialty chemical capacity toward pretreatment chemistry. Ministry of Environment and Forestry alignment is forcing real-time effluent monitoring and zero-liquid-discharge investments at metal finishing plants. Batam electronics manufacturers are consolidating surface treatment to centralized job shops with captive treatment capability.
Vietnam
Printed circuit board fabricators in northern industrial zones are drawing precision cleaning and plating chemistries at scale. Tightening industrial discharge rules under Ministry of Environment guidance are forcing cleaner chemistries and closed-loop regeneration. Bac Ninh province specifies low-foam alkaline formulations for automated conveyor washing systems.
Singapore
Resource Sustainability Act mandates are accelerating demand for closed-loop regeneration services and circular chemistry models. The city-state's position as regional headquarters concentrates technical service engineering talent for multi-country formulation support. Jurong Island chemical hub hosts captive treatment infrastructure serving electronics and precision manufacturing.
Malaysia
Export-oriented facility chemistries are reshaping around REACH-equivalent substance restrictions from EU trade partners. Penang's electronics manufacturing corridor requires ultra-high-purity cleaning chemistries with metallic impurity controls below parts-per-billion thresholds. Port Klang logistics infrastructure supports just-in-time chemical delivery to automotive tier suppliers.
Southeast Asia Surface Treatment Chemicals Market Competitive Landscape
Global majors compete with regional champions across formulation technical service and regulatory compliance capabilities. Japanese specialty chemical producers control dominant positions in automotive pretreatment intellectual property across Thai and Indonesian supply chains. Three archetypes define competitive positioning: integrated coatings-chemicals conglomerates, standalone pretreatment specialists, and regional distributors with captive blending capacity. M&A activity targets captive regeneration service capabilities, while strategic partnerships secure feedstock supply against Chinese export quota volatility.
Among Japanese-origin pretreatment specialists, Nihon Parkerizing Co Ltd and NOF CORPORATION exemplify the intellectual-property-heavy archetype serving OEM supply chains. Henkel AG & Co KGaA anchors the integrated conglomerate tier with regional technical center infrastructure. Siam YUKEN Co., Ltd. occupies a position representing Thai-Japanese joint venture structures that blend local market access with foreign formulation expertise.
| Leading Market Players |
|---|
| Nihon Parkerizing Co Ltd |
| Nippon Paint Holdings Co Ltd |
| Chemetall GmbH |
| NOF CORPORATION |
| PPG Industries Inc |
| Henkel AG & Co KGaA |
| Siam YUKEN Co., Ltd. |
| Kansai Paint Co., Ltd. |
| JCU CORPORATION |
| Others |
Value Network & Pricing Analysis
Zirconium-based thin-film conversion coatings are compressing pretreatment line footprints while simultaneously raising formulation complexity premiums and consolidating supplier tiers around technical service capabilities. Thai automotive OEMs piloting silane-based systems at accelerated line speeds are accepting 15-20% chemical cost premiums for reduced sludge generation and ambient-temperature operation.
Pricing Analysis
Technical service bundling separates premium pretreatment suppliers from commodity alkali and acid vendors across Indonesian and Thai automotive lines. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, OEM qualification status, and waste minimization service inclusion. Cost compression in standard-grade alkalis is intensifying because Chinese phosphate export quotas feed raw material volatility. Tier-2 automotive suppliers exhibit highest price sensitivity; Japanese OEM supply chains show lowest, prioritizing process stability over unit chemistry costs.
Supply Chain Analysis
Nadcap and IATF 16949 qualification gating restricts pretreatment chemical supply to a narrow tier of formulators with documented OEM approvals across Thailand, Indonesia, and Vietnam. Phosphate rock from Vietnam's northern highlands and fluorides subject to Chinese export quotas anchor raw material dependencies. Single-source vulnerability concentrates in Japanese-origin automotive pretreatment intellectual property controlling 70% of Thai supply. Distribution runs through direct sales with embedded technical service engineers rather than arm's-length distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface treatment chemical supply is tightening around qualified formulators with captive regeneration capabilities, propping pricing power for incumbents holding OEM approvals. Capacity bottlenecks in process engineering talent fluent in both formulation science and automated conveyor controls constrain new line commissioning speeds.
For Market Incumbents: Anchor market position through backward integration into captive acid regeneration services at Indonesian metal finishing clusters facing MEE zero-liquid-discharge mandates. Deepen technical service staffing in Vietnam's Bac Ninh electronics corridor before PCB fabricator demand peaks. Defend against silane-based substitution by quantifying total-process-cost advantages in phosphate-zirconium hybrid systems. For New Entrants and Emerging Players: Myanmar's Yangon-Pathein industrial corridor lacks established chemical supply infrastructure and presents first-mover positioning for pretreatment specialists willing to build local technical service presence. Target centralized job shops consolidating surface treatment for Batam electronics manufacturers under real-time effluent monitoring requirements. Lead with waterborne system convergence combining zirconium thin-film technologies with electrocoating primer integration. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated coatings-chemicals conglomerates seeking regional pretreatment capabilities. Long-term viability hinges on circular chemistry service models aligned with Singapore's Resource Sustainability Act mandates. Watch for inflection in Japanese OEM supplier reduction programs accelerating consolidation around multi-year total-fluid-cost agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Regeneration | Captures margin from Indonesian MEE-mandated zero-liquid-discharge investments at metal finishing plants. |
| Technical Center Expansion | Henkel's Bangkok model demonstrates how regional formulation support anchors multi-country OEM supply contracts. |
| Silane-Based Coating Pilot Programs | Thai OEM line speed gains validate phosphate replacement economics in tropical corrosion environments. |
| Long-term Chemical Management Contracts | Tier-1 automotive supplier consolidation in Thailand's Eastern Economic Corridor locks in revenue visibility. |
| Joint Venture with Japanese Pretreatment Specialist | Siam YUKEN structure blends local market access with foreign formulation expertise for automotive OEM qualification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at Thai and Indonesian automotive pretreatment facilities, procurement leads at Vietnamese PCB fabricators, distribution channel partners serving Malaysian electronics corridors, and technical R&D directors at specialty chemical formulators. Secondary validation drew from Indonesian MEE discharge monitoring reports, Thai Board of Investment EV incentive disclosures, Vietnam customs chemical import records, and SEC 10-K filings of listed coatings-chemicals conglomerates. Bottom-up demand modeling across end-use industries triangulated against top-down market sizing from production capacity and consumption intensity benchmarks.
Data-stream reconciliation integrated shipment volumes from regional chemical distributors, OEM pretreatment line installation announcements, and formulation patent filings across the analysis window. Segmentation dimensions modeled include product chemistry family, end-use industry concentration, application process type, and regional regulatory compliance tier. CAGRs were derived from slope-log modeling of annual demand trajectories, with industry-specific inputs incorporating automotive production forecasts from Thai Board of Investment projections and electronics manufacturing FDI flows into Vietnam's northern industrial zones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese phosphate and fluoride export quota volatility, Japanese OEM supplier consolidation pacing, and substitution acceleration from dry ice blasting in precision electronics cleaning. A model refresh is warranted upon material change in Indonesian MEE enforcement intensity or Thai EV assembly incentive program structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
US Institutional Cleaning Detergents Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Concentrated Laundry Powder Market