
 Dust Control Systems and Suppression Chemicals Market | 2026-2036
Dust Control Systems and Suppression Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Control Systems and Suppression Chemicals Market Intelligence
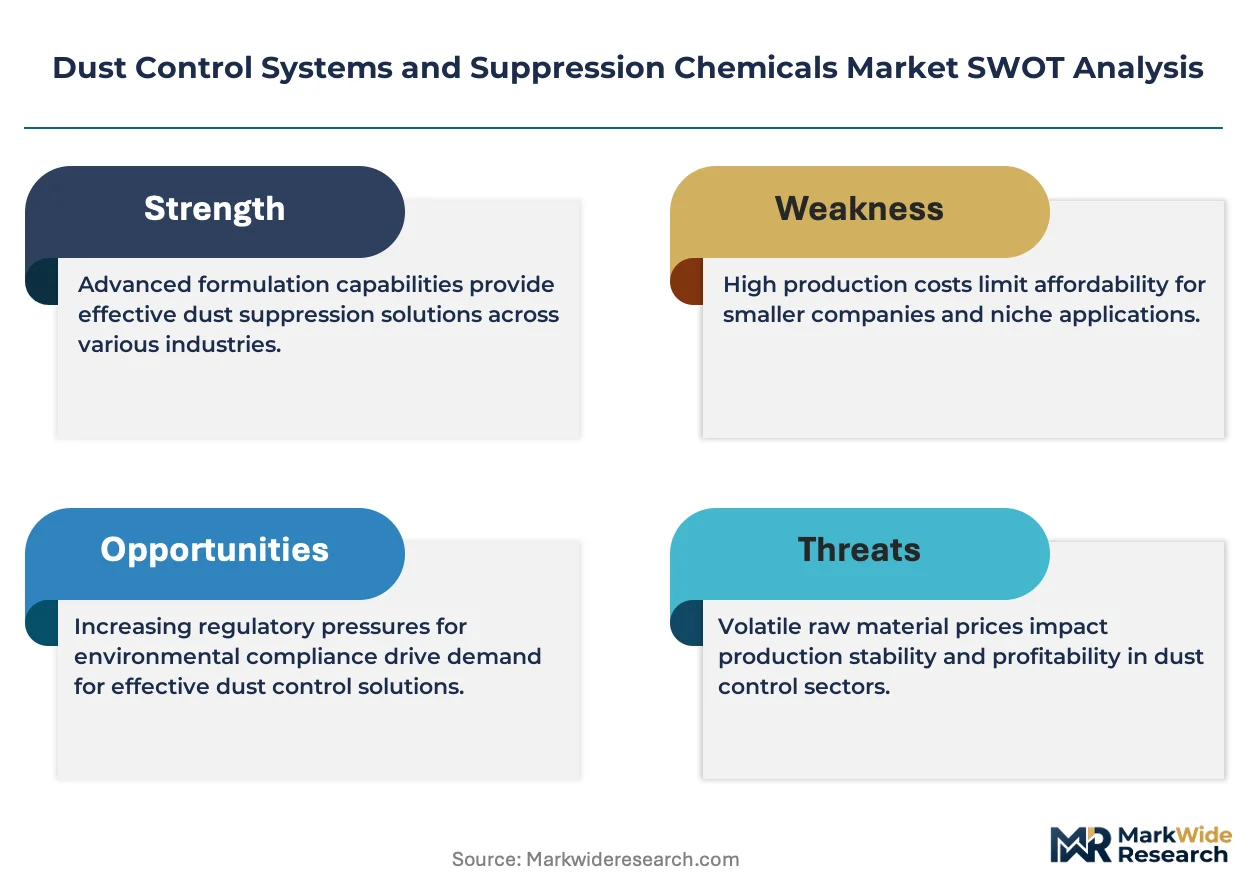
Remote monitoring and predictive maintenance subscriptions is broadening recurring revenue streams beyond equipment sales. Donaldson Company leverages its filtration sensor networks to sustain long-term service contracts with mining clients. Nederman Holding anchors its European installed base through aftermarket parts and digital fleet management platforms. Ecolab differentiates by bundling chemical suppressant replenishment with automated dosing system oversight.
Dust control systems and suppression chemicals encompass engineered equipment and formulated compounds designed to capture, settle, or bind airborne particulate matter across industrial environments. Polymer-based solutions form durable crusts on stockpiles through long-chain molecular cross-linking, while mechanical control employs cyclonic separation and fabric filtration to extract respirable dust from airstreams. Liquid suppressants dominate current procurement volumes due to lower per-tonne application costs in mining haul roads, though polymer-based solutions represent the fastest-expanding technology category as durability requirements intensify. Chemical control methods command premium pricing in arid climates where water scarcity constrains traditional wet suppression.
The US Mine Safety and Health Administration and Australia's Department of Mines, Industry Regulation and Safety enforce progressively lower respirable crystalline silica thresholds, compelling capital expenditure on engineered dust controls. EPA National Ambient Air Quality Standards and state-level air quality districts in California and Texas mandate continuous particulate monitoring at construction and demolition sites. Stakeholders must evaluate chemical suppressant biodegradability credentials against emerging environmental discharge restrictions while scaling mechanical system capacity to match extraction depth expansion.
Market Dynamics
Deepening open-pit mining operations in Australia and Chile are forcing a step-change in dust suppression durability requirements, accelerating polymer-based chemical adoption over conventional wet methods.
Growth Catalysts
- Respirable crystalline silica limits:The US Mine Safety and Health Administration's tightened exposure thresholds compel surface and underground extraction sites to deploy engineered mechanical controls and automated monitoring systems.
- Iron ore expansion:Western Australia's Pilbara region concentrates procurement activity as producers confront intensifying airborne particulate regulations from the Department of Mines, Industry Regulation and Safety.
- Polymer cross-linking advances:Long-chain molecular binding technologies form durable crusts on deepening stockpiles, extending reapplication intervals beyond traditional liquid suppressants.
Market Restraints
- Petrochemical feedstock volatility:Polymer-based suppressant formulations remain exposed to acrylic and vinyl acetate monomer price swings, compressing margin stability for chemical suppliers.
- Water infrastructure lock-in:Established mine sites face stranded asset risk from capital-intensive spray system networks that resist retrofit to low-water chemical alternatives.
- Biodegradability compliance friction:Emerging environmental discharge restrictions in multiple jurisdictions force dual-track formulation development, extending R&D timelines.
Strategic Opportunities
- Underground automation:Autonomous haulage expansion in Chilean copper operations creates demand for integrated dust suppression tied to fleet management platforms.
- Remote monitoring convergence:Filtration sensor networks combined with predictive algorithms enable subscription-based maintenance contracts that decouple vendor revenue from equipment sales cycles.
- Arid climate premium positioning:Water scarcity across Saudi Arabia and South Africa's Northern Cape justifies chemical suppressant pricing premiums unavailable in temperate mining regions.
Industry Challenges
- Cross-disciplinary integration:Chemical suppressant vendors lack embedded software expertise to deliver unified dosing-automation systems, forcing partnership dependencies.
- Legacy equipment interoperability:Mechanical filtration retrofits must interface with decades-old ventilation infrastructure without triggering production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Control Systems and Suppression Chemicals Market |
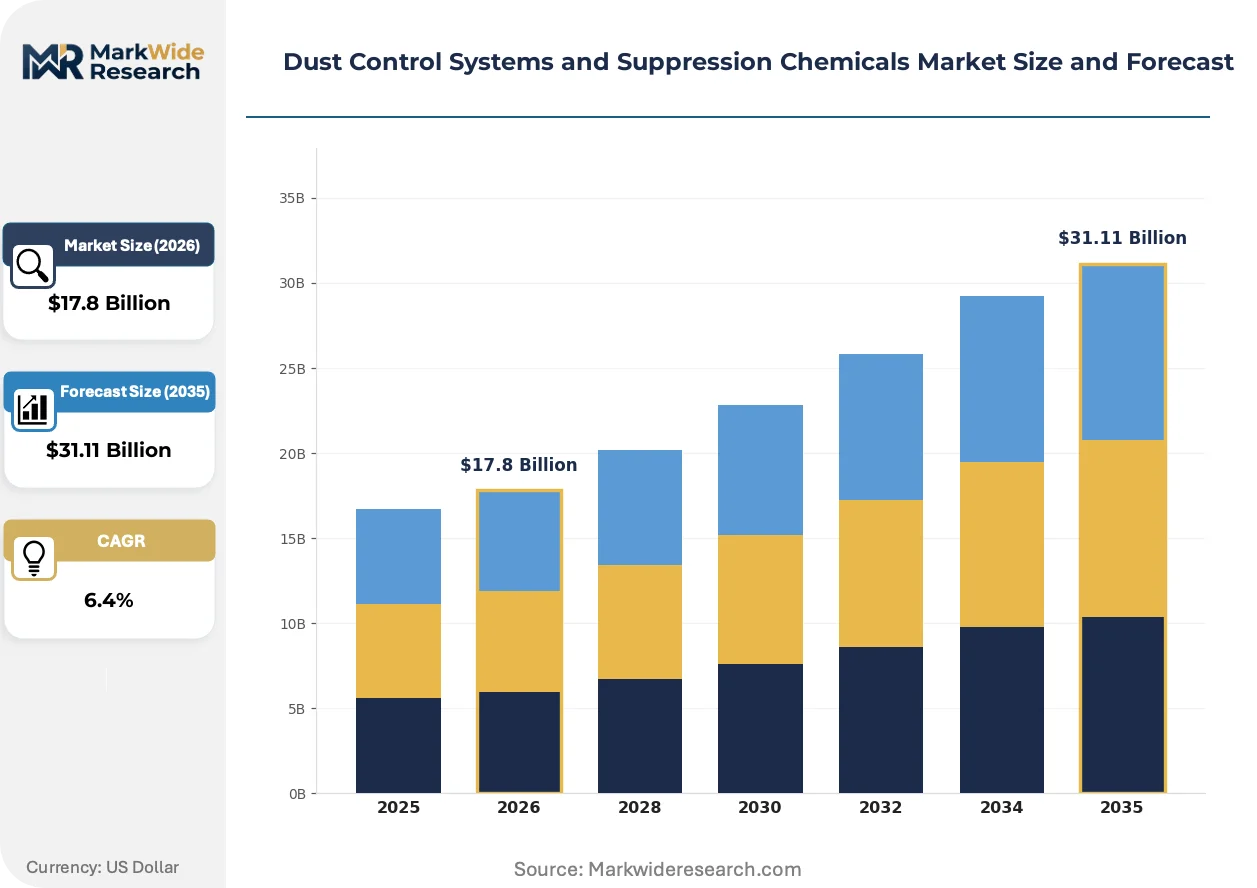
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Suppressants, Solid Suppressants, Coatings, Granular Materials Application: Construction, Mining, Agriculture, Industrial Operations Technology: Mechanical Control, Chemical Control, Water-Based Solutions, Polymer-Based Solutions End User: Construction Firms, Mining Companies, Agricultural Producers, Industrial Manufacturers |
| Companies Covered | Donaldson Company Inc., Ecolab Inc., Nederman Holding AB, Cargill Incorporated, Camfil AB, Quaker Houghton Corporation, Borregaard AS, Dust Control Technologies Inc., Hexion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Control Systems and Suppression Chemicals Market Strategic Shifts & Innovations
Digital integration is dissolving traditional boundaries between chemical application and mechanical filtration, creating unified particulate management platforms that bundle hardware, consumables, and data services.
Electrostatic precipitation enhancements paired with advanced fabric media are absorbing fine particulate fractions that bypass conventional cyclonic separation. Underground metal mining operations in Canada and Sweden are piloting these hybrid systems to address sub-micron silica fractions. The technology is absorbing service revenue from standalone chemical suppressant vendors by embedding dosing controls within filtration infrastructure.
REACH authorization requirements for persistent organic pollutants are restricting legacy binder chemistries in European mining jurisdictions. Industrial operators must reformulate dust suppressants to exclude restricted substances while maintaining crust durability equivalent to prohibited compounds. German and Finnish open-pit limestone producers face accelerated compliance timelines that favor suppliers with pre-validated biodegradable alternatives.
Subscription-based fleet management is displacing transactional chemical procurement in large-scale surface mining. Western Australian iron ore producers now specify multi-year service agreements bundling suppressant replenishment with automated application oversight. This model concentrates vendor selection authority with procurement functions rather than site engineering teams, favoring suppliers with integrated digital platforms over specialty chemical pure-plays.
Dust Control Systems and Suppression Chemicals Market Segmentation
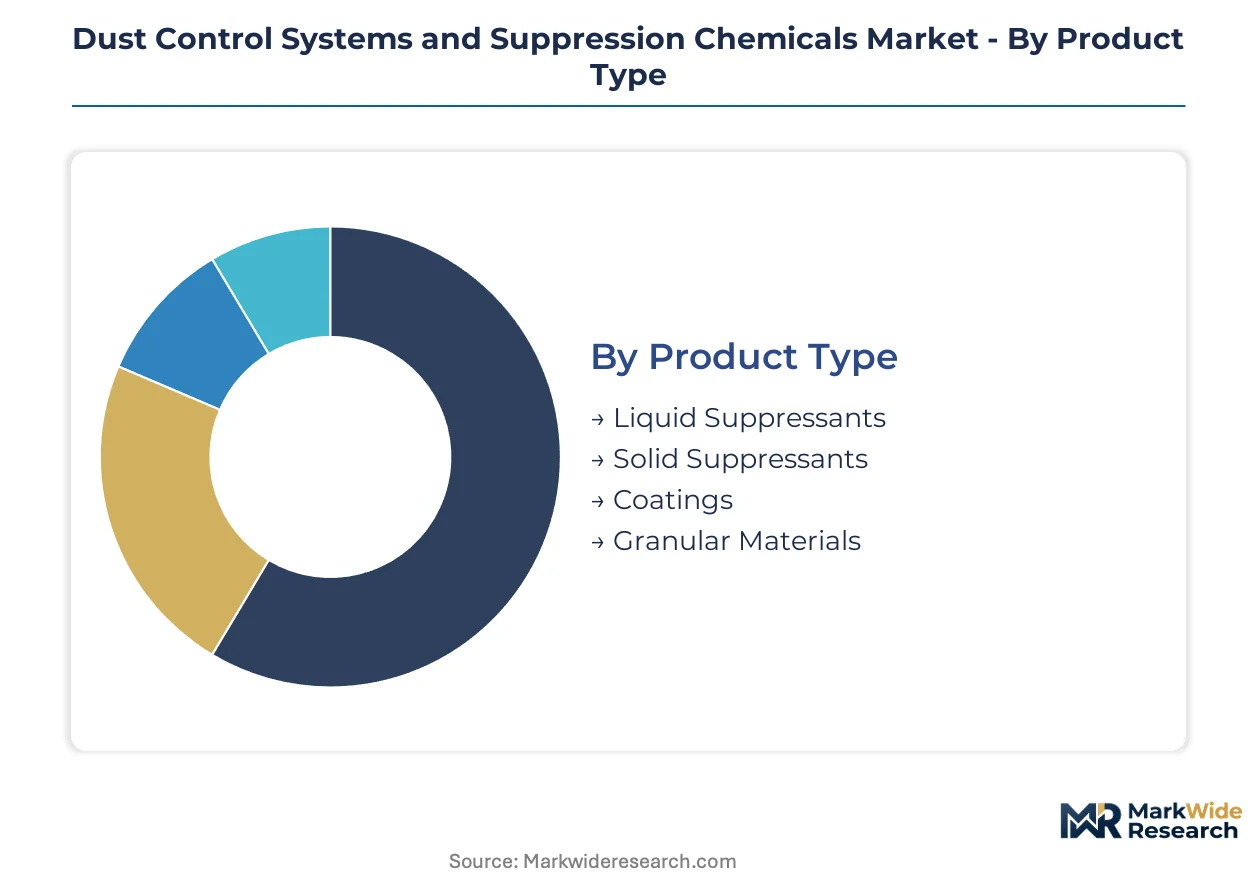
Dust control procurement splits between standalone chemical applications and integrated mechanical-chemical systems, with technology choices determining total cost of ownership across mining depths and climatic conditions. Segmentation reveals where bundled service models displace transactional chemical sales.
Product Type:
Liquid suppressants dominate standalone applications on haul roads, while solid and polymer formulations embed within automated dosing infrastructure for deeper integration.
- Liquid Suppressants:Water-based formulations with surfactant additives penetrate surface particulate layers for immediate dust settlement. Procurement concentrates in Western Australia's Pilbara iron ore operations where high-volume spray infrastructure already exists, though water scarcity is forcing evaluation of lower-volume alternatives.
- Solid Suppressants:Powdered binding agents including lignosulfonates and calcium chloride absorb atmospheric moisture to agglomerate fine particles. Chilean copper mines in the Atacama Desert specify these for stockpile management where liquid logistics prove prohibitive, driving premium pricing in arid geographies.
- Coatings:Surface-applied films form semi-permanent barriers on inactive storage areas. These find niche deployment in limestone quarries with extended material residence times.
- Granular Materials:Crushed aggregate blends with hygroscopic properties stabilize unpaved access roads. Agricultural producers in Australia's grain belt favor these for seasonal road maintenance.
Volume placements concentrate in liquid suppressants; the faster expansion belongs to solid suppressants.
Application:
Surface extraction depth and regulatory scrutiny intensity determine whether chemical suppression suffices or mechanical filtration becomes mandatory.
- Construction:Demolition and earthmoving operations in California and Texas face EPA National Ambient Air Quality Standards compliance deadlines. Continuous particulate monitoring mandates are accelerating procurement of both wet suppression and portable filtration units.
- Mining:Open-pit iron ore and copper extraction generates the largest absolute dust volumes. Underground automation in Chilean operations is creating demand for dust suppression integrated with autonomous haulage fleet management.
- Agriculture:Grain handling and livestock confinement operations require seasonal suppression during harvest and dry periods. These applications prioritize low-cost solutions over durability.
- Industrial Operations:Cement manufacturing and bulk material processing facilities deploy fixed mechanical filtration with chemical suppression for fugitive emissions. REACH authorization constraints in Europe are restricting legacy binder chemistries in these settings.
Revenue concentration sits with mining applications; construction is climbing the fastest as regulatory deadlines approach.
Technology:
Mechanical and chemical approaches increasingly converge in unified platforms, though pure-play vendors still dominate discrete procurement categories.
- Mechanical Control:Cyclonic separation, fabric filtration, and electrostatic precipitation extract respirable dust from airstreams. Canadian and Swedish underground metal mining operations are piloting hybrid electrostatic-fabric systems for sub-micron silica fractions.
- Chemical Control:Formulated binding agents agglomerate or crust particulate matter without mechanical extraction. These command premium pricing in water-scarce regions where mechanical alternatives require unsustainable liquid volumes.
- Water-Based Solutions:Conventional wet suppression using untreated or surfactant-modified water remains the lowest-cost approach. Established mine sites face stranded asset risk from capital-intensive spray networks that resist retrofit.
- Polymer-Based Solutions:Long-chain molecular cross-linking forms durable crusts extending reapplication intervals. These are gaining share fastest as deepening open-pit operations in Australia and Chile demand extended durability.
Installed base tilts toward water-based solutions; polymer-based alternatives show the steepest expansion trajectory.
End User:
Procurement authority is shifting from site engineering teams to centralized procurement functions as subscription-based service models displace transactional chemical purchasing.
- Construction Firms:Project-based contractors prioritize portable, rapidly deployable suppression for compliance with state-level air quality districts. These users show lowest loyalty and highest price sensitivity.
- Mining Companies:Large-scale surface and underground operators specify multi-year service agreements bundling suppressant replenishment with automated application oversight. Western Australian iron ore producers concentrate procurement activity for the sector.
- Agricultural Producers:Seasonal operations with variable dust generation favor low-capital solutions. Volume concentration is modest relative to mining and construction.
- Industrial Manufacturers:Cement and bulk processing facilities require continuous operation reliability. These end users drive demand for predictive maintenance subscriptions tied to filtration sensor networks.
Contract value concentrates with mining companies; construction firms are expanding their share fastest as infrastructure spending accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of dust control equipment concentrates in Germany and the United States, while consumption gravitates toward mining-intensive economies in Australia, Chile, and Canada where extraction depths intensify particulate management requirements.
Australia
Western Australia's Pilbara region drives continental procurement as iron ore producers confront tightening airborne particulate regulations from the Department of Mines, Industry Regulation and Safety. The state's mining code amendments mandate continuous respirable dust monitoring at all open-pit operations exceeding 50 meters depth. BHP and Rio Tinto operations near Port Hedland anchor chemical suppressant volume, with polymer-based solutions displacing conventional wet methods as stockpile heights increase.
Chile
Atacama Desert copper mining generates extreme aridity-driven demand for solid and polymer suppressants where liquid logistics prove economically prohibitive. The National Geology and Mining Service enforces progressive dust management plans for operations above 3,000 meters elevation. Codelco's Chuquicamata and Escondida clusters near Antofagasta specify automated dosing systems integrated with autonomous haulage fleet management platforms.
United States
Surface and underground mining across Appalachia and the Mountain West faces tightened respirable crystalline silica thresholds from the Mine Safety and Health Administration. EPA National Ambient Air Quality Standards compliance deadlines in California and Texas construction markets accelerate portable filtration procurement. Arizona's copper belt and Wyoming's Powder River Basin coal operations concentrate mechanical system deployment.
Germany
REACH authorization requirements for persistent organic pollutants compel reformulation of legacy dust suppressant binders in open-pit limestone extraction. The Federal Institute for Occupational Safety and Health mandates engineered controls for respirable silica in cement manufacturing. Bavarian and North Rhine-Westphalian industrial corridors drive predictive maintenance subscription adoption for filtration sensor networks.
Canada
Underground metal mining in Ontario and Quebec pilots hybrid electrostatic-fabric filtration systems targeting sub-micron silica fractions. Provincial occupational health regulators align exposure limits with ACGIH threshold value reductions. Sudbury Basin nickel operations and Red Lake gold camps anchor demand for integrated mechanical-chemical suppression platforms.
Dust Control Systems and Suppression Chemicals Market Key Industry Players
Top-tier vendors anchor integrated service models, while mid-tier chemical specialists and regional equipment fabricators occupy discrete technology niches. The vendor base stratifies across three functional tiers: filtration infrastructure providers bundling predictive maintenance subscriptions, chemical formulators pivoting toward biodegradable polymer development, and automation-software hybrids converging dosing controls with fleet management platforms. Dominant competitive moves include backward integration into sensor hardware and strategic partnerships bridging chemical application with mechanical extraction.
Within the integrated service tier, Donaldson Company and Ecolab exemplify divergent convergence strategies. Donaldson leverages filtration sensor networks to sustain recurring revenue through long-term maintenance contracts. Ecolab occupies a position binding chemical suppressant replenishment with automated dosing system oversight. Nederman Holding anchors the European installed base through aftermarket parts and digital fleet management platforms, representing the regional-specialist archetype against North American scale players.
| Leading Market Players |
|---|
| Donaldson Company Inc. |
| Ecolab Inc. |
| Nederman Holding AB |
| Cargill Incorporated |
| Camfil AB |
| Quaker Houghton Corporation |
| Borregaard AS |
| Dust Control Technologies Inc. |
| Hexion Inc. |
| Others |
Cost & Logistics Intelligence
Performance-grade divergence between polymer-based suppressants and commodity wet solutions shapes both margin structures and sourcing footprints across the value chain. Premium formulations command pricing multiples unavailable to water-based alternatives, while supply networks for acrylic and vinyl acetate monomers concentrate procurement leverage with specialized chemical producers.
Pricing Analysis
Margin tightening in liquid suppressant tiers reflects water infrastructure lock-in at established mine sites that resist retrofit to chemical alternatives. Three-tier pricing structure across premium polymer, standard solid binder, and economy water-based levels differentiates procurement based on durability requirements and reapplication frequency. Price differentiation centers on biodegradability certification status and automated dosing integration rather than raw formulation chemistry alone. Construction contractors in California and Texas exhibit highest price sensitivity due to project-based procurement cycles, while Australian iron ore producers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Specialized polymer chemist workforce availability in Germany and the United States anchors equipment manufacturing, while Chile and Australia concentrate field service deployment for mining-intensive consumption. Acrylic monomer supply draws from petrochemical complexes in the US Gulf Coast and Northwestern Europe, with lignosulfonate binders sourcing from Scandinavian pulp processing byproducts. Single-source vulnerability in vinyl acetate monomer supply creates exposure to feedstock price volatility. Distribution runs through regional chemical distributors for standalone suppressants and direct OEM channels for integrated mechanical-chemical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH authorization timelines and MSHA silica enforcement is eliminating formulation-only vendors lacking digital integration capabilities.
For Market Incumbents: To counter subscription-based displacement by integrated platform vendors, chemical specialists must backward integrate into sensor hardware or partner with automation providers. Incumbents should anchor capacity expansion in Western Australia's Pilbara region where procurement authority centralizes around multi-year service agreements. Certification investment in biodegradable polymer validation separates surviving suppliers from compliance-lagged competitors. For New Entrants and Emerging Players: Direct-to-mine digital sales channels bypass established distributor relationships that lock out formulation-only vendors. White-space opportunity concentrates in Chilean copper automation integration and Saudi Arabian arid-climate premium positioning. Target construction firms in EPA non-attainment zones with portable filtration-as-a-service models that sidestep capital-intensive chemical infrastructure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier mechanical filtration vendors possessing installed base density but lacking chemical formulation depth, given convergence toward unified particulate management platforms. Long-term viability favors targets with predictive maintenance subscription revenue exceeding transactional equipment exposure. Watch MSHA enforcement action frequency as inflection indicator for capital expenditure acceleration in US mining jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captures recurring revenue streams that Donaldson and Nederman currently dominate in filtration monitoring. |
| Biodegradable Polymer Certification Program | Secures market access as REACH restrictions eliminate legacy binder chemistries in European limestone extraction. |
| Long-term Service Agreement with Pilbara Iron Ore Producers | Locks out specialty chemical pure-plays by bundling suppressant replenishment with automated dosing oversight. |
| Joint Venture with Autonomous Haulage Platform Providers | Integrates dust suppression controls with Codelco and Escondida fleet management systems in Chilean copper. |
| Capacity Expansion in Arid Climate Mining Regions | Captures premium pricing justified by water scarcity constraints across Saudi Arabia and South Africa's Northern Cape. |
Research Approach
Multi-period observation of procurement contract structures, regulatory enforcement patterns, and polymer formulation patent filings anchored the trend analysis, supplemented by interviews with plant engineers at Australian iron ore operations, procurement leads at Chilean copper mines, aftermarket service heads at filtration OEMs, and technical R&D directors at chemical formulators. Secondary validation drew from MSHA enforcement databases, Australian Department of Mines compliance records, REACH authorization timelines, and SEC 10-K disclosures from listed vendors. Bottom-up segment sizing triangulated against top-down mining production volume and dust control intensity factors.
Segment-weighting across product type, application depth, technology convergence, and end-user procurement authority determined value distribution throughout the projection horizon. CAGRs derived from elasticity modeling of regulatory compliance cost absorption and substitution patterns between wet suppression and polymer alternatives. Industry-specific inputs included open-pit deepening rates in Pilbara and Atacama operations, plus autonomous haulage deployment timelines in Chilean copper.
The model holds under steady regulatory enforcement intensification; deviation in MSHA silica threshold timing or REACH authorization acceleration would shift chemical suppressant penetration trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Metal Polish Products Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market