
 Cleaning Fluids Market | 2026-2036
Cleaning Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Cleaning Fluids Market Analytics
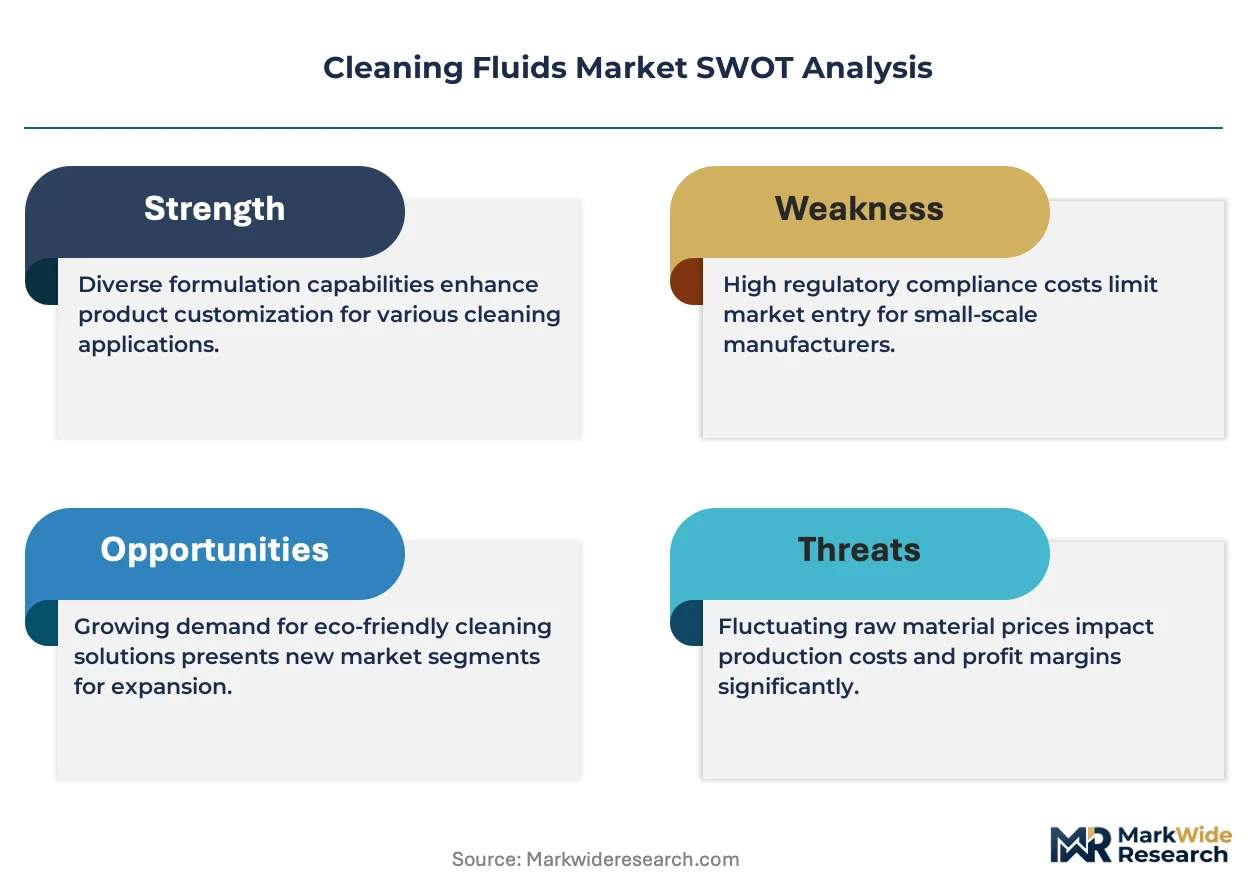
REACH restrictions on volatile organic compounds is shifting the cost-of-entry calculus for new entrants across European and export-oriented manufacturing bases. Ecolab Inc. leverages its institutional service infrastructure to embed recurring chemical supply contracts within healthcare and foodservice operations. Henkel AG & Co. KGaA anchors its position through specialized industrial degreaser formulations targeting automotive OEM specifications. BASF SE competes on backward integration into surfactant raw materials, securing feedstock cost advantages for high-volume disinfectant production.
Cleaning fluids encompass formulated aqueous and solvent-based solutions designed to remove contaminants, residues, and microbial loads from surfaces, typically specified by pH range, active ingredient concentration, and substrate compatibility parameters. Their primary industrial purpose centers on maintaining operational efficiency, regulatory compliance, and hygiene standards across manufacturing, healthcare, and commercial environments. The disinfectants category leads value generation due to healthcare-associated infection protocols and post-pandemic institutional retention of elevated sanitization frequencies. Industrial application demand outpaces household growth as precision manufacturing in electronics and aerospace intensifies solvent purity requirements. Liquid form factors dominate volume shipments, though spray formats capture premium positioning in automotive detailing and commercial glass maintenance segments.
The EPA governs antimicrobial claims and VOC thresholds in the United States, while ECHA administers REACH substance restrictions across European formulations, collectively elevating compliance investment for cross-border suppliers. FDA oversight of medical device cleaning validation and OSHA exposure limits for industrial solvents further constrain product design freedom and documentation burdens. Stakeholders must monitor evolving state-level ingredient disclosure mandates and biobased procurement preferences that threaten to fragment previously standardized national product portfolios.
Market Dynamics
Semiconductor wafer cleaning protocols in Taiwan and South Korea are driving solvent-intensive formulation demand, while REACH and EPA Safer Choice mandates simultaneously force surfactant chemistry transitions. This dual pressure—electronics manufacturing scale-up against regulatory reformulation—is restructuring supplier capabilities and regional production footprints.
Growth Catalysts
- Electronics Manufacturing Clusters:Taiwan Semiconductor Manufacturing Company and Samsung Foundry expansion in Hsinchu and Pyeongtaek intensifies ultra-pure solvent consumption for sub-3nm node wafer cleaning protocols.
- REACH Substance Restrictions:ECHA's 2024 VOC thresholds and bio-based surfactant mandates open substitution windows for European formulators with green chemistry capabilities.
- Healthcare Institutional Retention:Post-pandemic infection control protocols in US and German hospital systems sustain elevated disinfectant application frequencies above 2019 baselines.
Market Restraints
- Petrochemical Feedstock Volatility:Naphtha and ethylene oxide price swings compress margin predictability for surfactant-dependent disinfectant producers.
- Taiwan Strait Concentration Risk:70% of advanced semiconductor solvent demand concentrates in facilities vulnerable to geopolitical supply disruption.
- Technical Purity Limitations:Current bio-based surfactants fail to achieve parts-per-trillion metal ion specifications required for EUV lithography mask cleaning.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO's tightening GMP cleaning validation standards create demand for documented residue removal chemistries in Active Pharmaceutical Ingredient synthesis facilities.
- Automotive EV Battery Production:Cell electrode cleaning and dry room maintenance protocols represent unaddressed formulation white space as gigafactory construction accelerates in Nevada and Saxony.
- US Federal Biobased Procurement:USDA BioPreferred program mandates in federal healthcare contracts advantage domestic suppliers with certified renewable content above 34% thresholds.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in surfactant-polymer compatibility and regulatory submission documentation concentrates among aging specialists in Basel and Ludwigshafen clusters.
- Multi-Jurisdiction Certification Timelines:Parallel EPA antimicrobial registration, ECHA REACH dossier preparation, and FDA medical device cleaning validation extend product launch cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleaning Fluids Market |
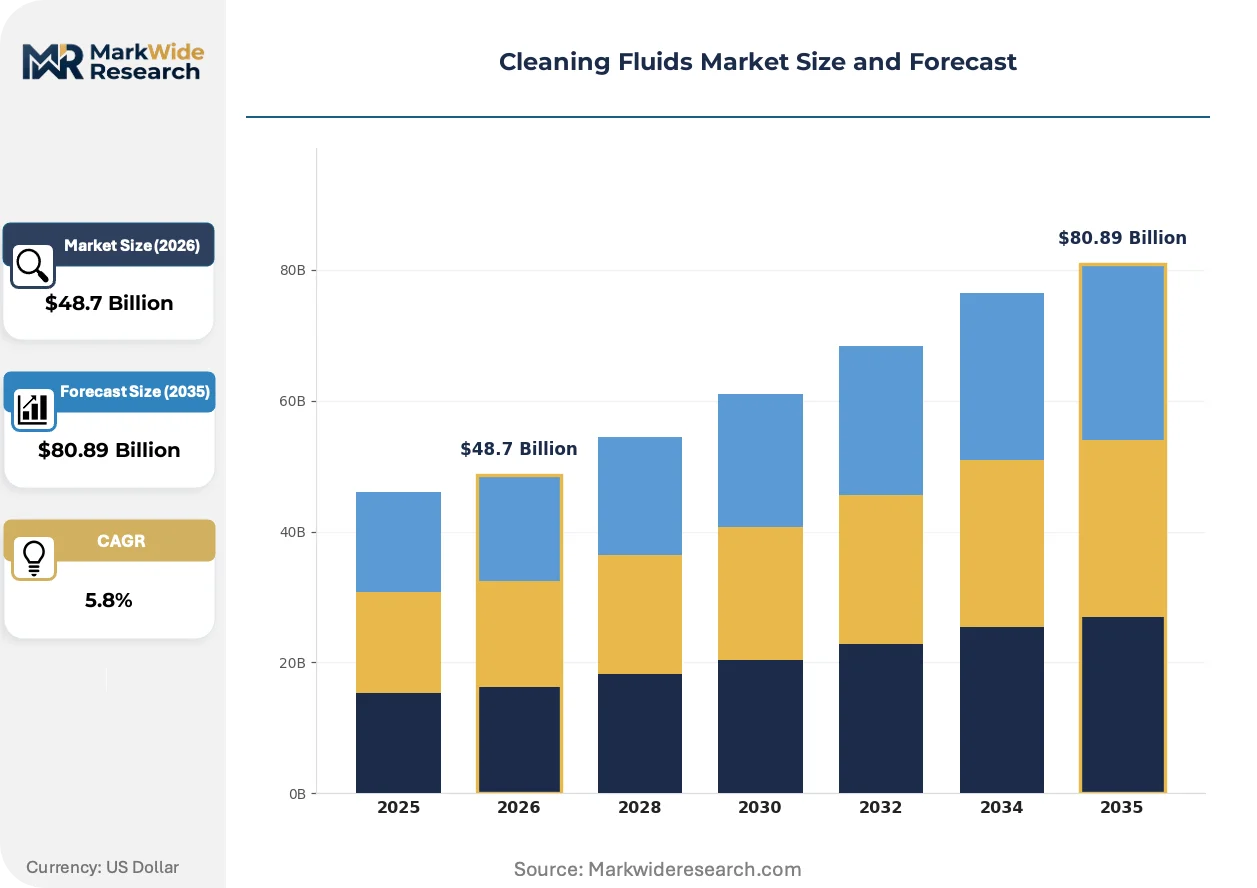
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Cleaners, Degreasers, All-Purpose Cleaners, Disinfectants Application: Household, Automotive, Industrial, Institutional Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Form: Liquid, Spray, Wipes, Powder |
| Companies Covered | BASF SE, Spartan Chemical Company, Ecolab Inc., Clariant International Ltd., Zep Inc., Procter & Gamble, Henkel AG & Co. KGaA, Dow Chemical Company, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleaning Fluids Market Evolving Landscape
Supercritical CO2 cleaning systems and aqueous-based precision chemistries are displacing traditional chlorinated solvents in electronics and aerospace applications. Formulation science now converges with process engineering as end-users demand integrated cleaning-validation packages rather than commodity chemical supply.
Supercritical CO2 precision cleaning is expanding into semiconductor backend assembly and aerospace turbine component maintenance. Taiwan packaging houses and Safran repair facilities in Toulouse are piloting systems at commercial scale. This technology is expanding into solvent-intensive applications previously dominated by N-methyl-2-pyrrolidone and isopropyl alcohol, compressing conventional chemical supplier margins in high-purity segments.
EPA's Safer Choice program and ECHA's 2024-2025 REACH restriction expansions on per- and polyfluoroalkyl substances are forcing surfactant reformulation across disinfectant and industrial degreaser portfolios. The industrial consequence is accelerated R&D spend on bio-based alkyl polyglucosides and biosurfactants. Healthcare and foodservice institutional buyers in Germany and California are now requiring third-party green chemistry certification as a procurement gate, displacing uncertified legacy formulations.
Hospital systems and semiconductor fabs are consolidating chemical supply contracts under single-source technical service agreements with embedded validation documentation. The distributor-wholesaler channel faces disintermediation as Ecolab and Diversey deploy direct field service teams. This pattern is most visible in US metropolitan healthcare markets and South Korean electronics clusters, where procurement departments now prioritize vendor technical response time over unit chemical pricing.
Cleaning Fluids Market Segmentation
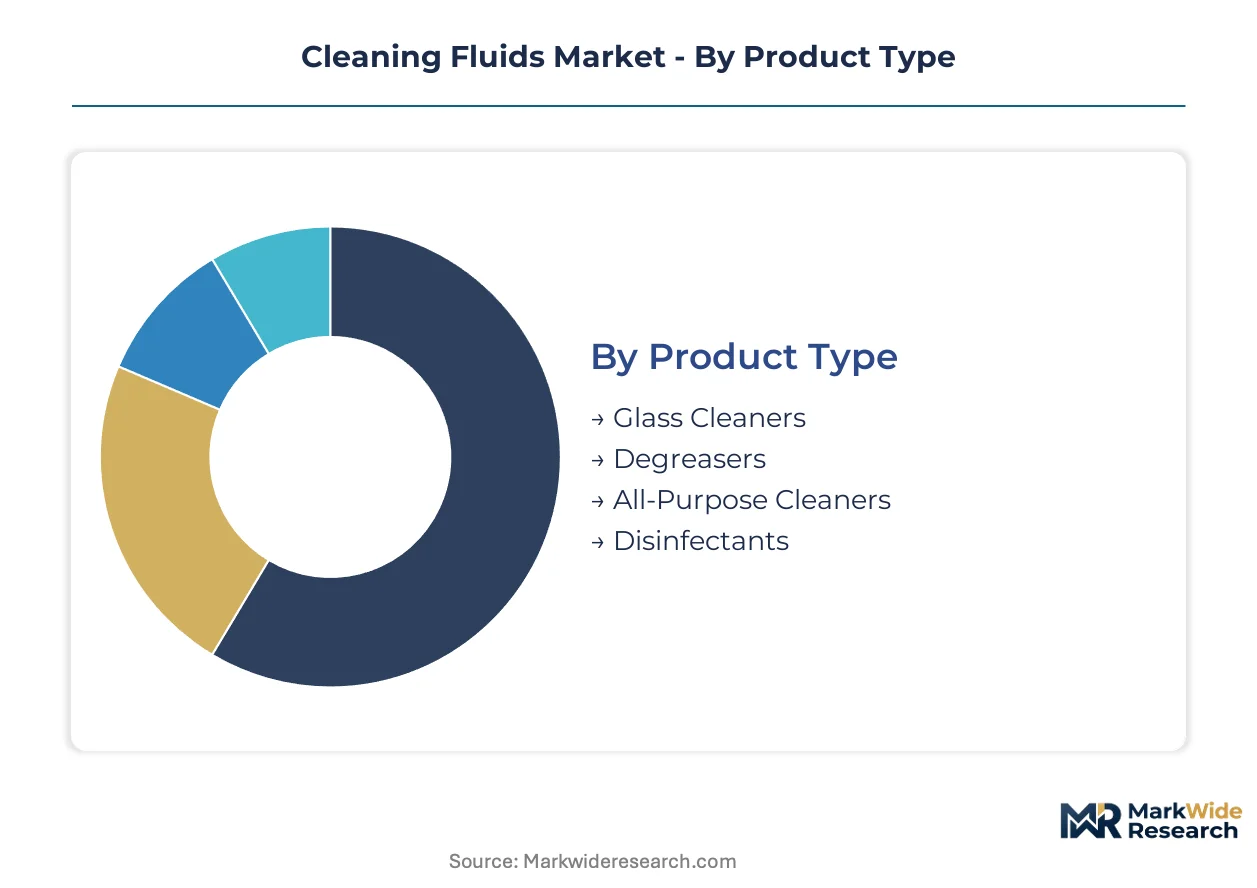
Cleaning fluid segmentation reveals divergent technical specifications across end-use environments. Electronics manufacturing demands parts-per-trillion purity thresholds incompatible with household formulations. Distribution and form factor choices increasingly reflect integrated service contracts rather than commodity purchasing patterns.
Product Type:
Technical specifications for surface compatibility and residue profiles define competitive positioning across chemistry portfolios.
- Disinfectants:Formulations carrying EPA-registered antimicrobial claims against specified pathogen classes. Hospital systems in Germany and California sustain elevated procurement volumes above pre-pandemic baselines through retained infection control protocols.
- Degreasers:Solvent-based and aqueous alkaline chemistries engineered for hydrocarbon removal from metal substrates. Automotive OEM specifications in Stuttgart and Detroit drive formulation differentiation toward low-VOC compliance without sacrificing cutting performance.
- All-Purpose Cleaners:Surfactant blends balanced for broad-spectrum soil removal across variable surfaces.
- Glass Cleaners:Ammonia and ammonia-free variants formulated for streak-free optical clarity on coated surfaces.
Disinfectants lead on scale; degreasers lead on momentum in precision manufacturing applications.
Application:
End-use environments impose distinct purity, documentation, and regulatory compliance requirements.
- Industrial:Process-critical chemistries validated for residue removal in semiconductor fabrication and aerospace component maintenance. Taiwan Semiconductor Manufacturing Company and Samsung Foundry facilities in Hsinchu and Pyeongtaek specify ultra-pure solvents for sub-3nm wafer cleaning protocols.
- Institutional:Healthcare and foodservice contract supply with embedded technical service and validation documentation. Ecolab and Diversey field service teams disintermediate traditional distribution channels in US metropolitan healthcare markets.
- Automotive:Detailing and maintenance formulations spanning interior surfaces through powertrain degreasing.
- Household:Consumer retail products distributed through mass-market channels with simplified application instructions.
Industrial applications command premium positioning; institutional contracts are expanding most quickly through service integration.
Distribution Channel:
Channel selection reflects procurement centralization versus fragmented purchasing authority.
- Wholesale:Bulk supply agreements serving manufacturing facilities and institutional buyers with dedicated logistics. South Korean electronics clusters prioritize vendor technical response time over unit chemical pricing in consolidated chemical supply contracts.
- Online Retail:Direct-to-consumer and small-business procurement platforms with expanded SKU visibility. Post-pandemic purchasing pattern retention sustains digital channel growth in household and light commercial segments.
- Supermarkets:Mass-market retail placement for standardized consumer formulations.
- Specialty Stores:Professional-grade product access for automotive detailing and commercial cleaning contractors.
Wholesale dominates contract value; online retail gains share fastest in fragmented purchasing environments.
Form:
Physical delivery mechanisms determine application precision, storage efficiency, and regulatory classification.
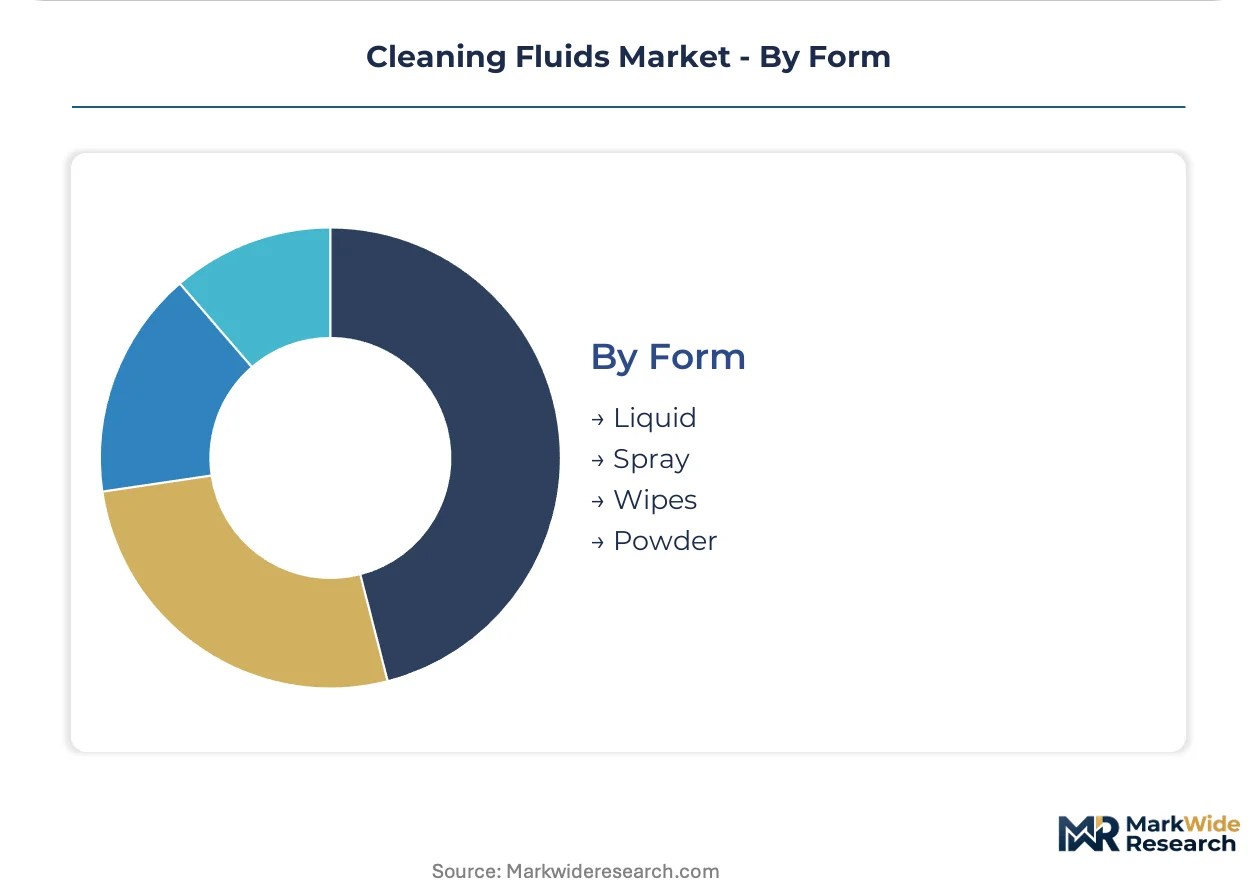
- Liquid:Concentrated and ready-to-use formulations in bulk containers and consumer bottles. Volume shipments concentrate in industrial and institutional procurement with dilution-system compatibility requirements.
- Spray:Aerosol and trigger-dispensed formats capturing premium positioning in automotive detailing and commercial glass maintenance. Precision application reduces overspray waste in controlled environments.
- Wipes:Pre-saturated substrates for standardized application dosage in healthcare and foodservice settings.
- Powder:Concentrated solid formulations requiring reconstitution, common in heavy-duty industrial degreasing applications.
Liquid form factors anchor volume; spray formats climb the fastest in premium positioning segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with surfactant-polymer expertise concentrate in Basel, Ludwigshafen, and New Jersey corridors, anchoring regional R&D capabilities and regulatory submission capacity.
United States
Federal healthcare procurement through the USDA BioPreferred program mandates certified renewable content above 34% thresholds in institutional contracts. EPA antimicrobial registration and OSHA exposure limits constrain product design freedom for cross-border suppliers. Ecolab deploys direct field service teams across metropolitan healthcare markets, disintermediating traditional distribution channels.
Germany
Automotive OEM specifications in Stuttgart drive low-VOC degreaser formulation differentiation without sacrificing cutting performance. ECHA REACH dossier preparation and bio-based surfactant mandates open substitution windows for green chemistry capabilities. Henkel AG & Co. KGaA anchors industrial degreaser portfolios through specialized formulations targeting automotive specifications.
Taiwan
Semiconductor fabrication facilities in Hsinchu intensify ultra-pure solvent consumption for sub-3nm node wafer cleaning protocols. Taiwan Semiconductor Manufacturing Company expansion concentrates 70% of advanced semiconductor solvent demand in facilities vulnerable to geopolitical supply disruption. Procurement departments prioritize vendor technical response time over unit chemical pricing in consolidated chemical supply contracts.
South Korea
Samsung Foundry expansion in Pyeongtaek drives solvent-intensive formulation demand for precision wafer cleaning. MFDS oversight of medical device cleaning validation parallels FDA requirements, extending documentation burdens for suppliers. Electronics manufacturing clusters in Suwon and Hwaseong specify parts-per-trillion purity thresholds incompatible with commodity formulations.
India
CDSCO tightening of GMP cleaning validation standards creates demand for documented residue removal chemistries in Active Pharmaceutical Ingredient synthesis facilities. Pharmaceutical manufacturing expansion in Hyderabad and Ahmedabad requires surfactant chemistries validated for regulatory submission. Domestic formulators compete on cost positioning against imported European and American certified products.
Cleaning Fluids Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive surfactant production and established regulatory submission infrastructure. Three archetypes dominate: backward-integrated raw material suppliers securing feedstock cost advantages, institutional service providers embedding recurring contracts through technical field teams, and specialized industrial formulators targeting OEM specification compliance. Dominant competitive moves include portfolio diversification into bio-based surfactants and geographic expansion through direct service deployment in electronics manufacturing clusters.
Among German-based chemical conglomerates, BASF SE exemplifies the backward-integrated archetype through upstream control over surfactant raw materials. Ecolab Inc. represents the institutional service model, embedding recurring chemical supply contracts within healthcare and foodservice operations through dedicated field infrastructure. Henkel AG & Co. KGaA occupies a position as specialized industrial formulator, anchoring market presence through automotive OEM specification compliance.
| Leading Market Players |
|---|
| BASF SE |
| Spartan Chemical Company |
| Ecolab Inc. |
| Clariant International Ltd. |
| Zep Inc. |
| Procter & Gamble |
| Henkel AG & Co. KGaA |
| Dow Chemical Company |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 cleaning system adoption in semiconductor backend assembly and aerospace turbine maintenance is simultaneously compressing conventional chemical supplier margins and concentrating procurement authority among buyers with integrated process-engineering capabilities. This technology transition rewards suppliers offering validation-documentation bundles over commodity chemical volumes, restructuring how value capture distributes across the value chain.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive pricing architecture across the cleaning fluids market. Three-tier pricing structure across premium, standard, and economy levels separates validated ultra-pure solvents for EUV lithography from institutional disinfectant contracts and commodity household formulations. Price differentiation hinges on certification grade—EPA Safer Choice and ECHA REACH bio-based credentials—and embedded technical field service. Cost compression in standard-tier surfactant formulations is intensifying because bio-based feedstock substitution raises input costs without commensurate performance gains. Healthcare institutional buyers exhibit lowest price sensitivity due to infection-control protocol mandates, while automotive detailing contractors face acute margin pressure from volatile solvent spot markets.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Taiwan Semiconductor Manufacturing Company and Samsung Foundry, bypassing traditional distribution layers. Geographic supply concentration centers on Germany, Taiwan, and South Korea, where formulation chemists with surfactant-polymer expertise anchor regional production. Raw material dependencies draw from naphtha and ethylene oxide feedstocks, plus specialized bio-based alkyl polyglucoside precursors. Single-source vulnerability concentrates in 70% of advanced semiconductor solvent demand clustered in Hsinchu and Pyeongtaek facilities exposed to geopolitical disruption. Distribution runs through consolidated wholesale agreements with embedded logistics and validation documentation, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cleaning fluids market functions as a stable compounder, with regulatory-mandated formulation turnover and precision manufacturing expansion driving steady replacement demand across institutional and industrial segments.
For Market Incumbents: Cement market position through captive surfactant production in Ludwigshafen and Basel corridors, securing feedstock cost advantages against specialty chemical entrants. Deepen technical service infrastructure in South Korean electronics clusters to lock in consolidated supply contracts before bio-based certification mandates reshape procurement gates. Prioritize EPA antimicrobial registration and ECHA REACH dossier preparation to extend product launch cycle advantages over resource-constrained competitors. For New Entrants and Emerging Players: Enter via unaddressed formulation white space in automotive EV battery production, where cell electrode cleaning and dry room maintenance protocols lack validated chemistries. Target Indian pharmaceutical manufacturing in Hyderabad and Ahmedabad, where CDSCO tightening of GMP cleaning validation standards creates demand for documented residue removal solutions. Pursue direct technical service partnerships with mid-tier semiconductor packaging houses as an alternative to consolidated foundry supply contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with EPA-registered disinfectant portfolios and limited backward integration, positioned for acquisition by conglomerates seeking antimicrobial claim infrastructure. Long-term viability over a 5-10 year window rests on regulatory submission capacity and bio-based surfactant R&D pipelines rather than commodity scale. Watch for inflection in federal healthcare procurement mandates under USDA BioPreferred program thresholds as a signal for domestic supplier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstocks | BASF SE secures cost advantages for high-volume disinfectant production against specialty competitors. |
| Direct Field Service Deployment | Ecolab embeds recurring contracts in US metropolitan healthcare markets, disintermediating distributors. |
| Bio-Based Certification Investment | Green chemistry capabilities open substitution windows under EPA Safer Choice and ECHA REACH mandates. |
| Consolidated Supply Contract Capture | Single-source technical service agreements with Samsung Foundry prioritize response time over unit pricing. |
| Geographic Expansion in Electronics Clusters | Supplier presence in Hsinchu and Pyeongtaek addresses 70% of advanced semiconductor solvent demand. |
Research Methodology
Direct dialogue with plant managers at semiconductor fabrication facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors anchored qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA antimicrobial registration databases. Bottom-up and top-down triangulation cross-checked volume estimates against feedstock consumption patterns and end-use application scaling.
Bottom-up modeling aggregated segment-level demand across product type, application environment, and regional production hub dimensions. Top-down constraints applied macroeconomic boundary conditions and petrochemical feedstock price elasticity assumptions across the projection horizon. CAGRs derived from regression analysis of historical volume trends, adjusted for regulatory phase-in schedules and technology substitution curves specific to supercritical CO2 displacement and bio-based surfactant penetration rates.
The model holds under stable regulatory enforcement timelines and continued semiconductor node shrinkage; deviation in REACH restriction acceleration or Taiwan Strait logistics disruption would shift volume and value trajectories. Forecasts incorporate documented assumptions regarding bio-based surfactant performance parity achievement and federal procurement threshold stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market