
 Fabric Softener and Conditioner Market | 2026-2036
Fabric Softener and Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Softener and Conditioner Market Intelligence
The substitution of traditional petroleum-derived quaternary ammonium compounds with biodegradable, plant-based ester quats is hardening the cost structure for formulators. This shift creates new challenges in maintaining performance while managing input price volatility. Procter & Gamble leverages its extensive R&D capabilities to develop advanced formulations that meet evolving consumer preferences for sustainability. Meanwhile, Henkel competes by focusing on specific market niches with specialized products and strong brand positioning in key European countries.
Fabric softener and conditioner refers to a laundry care additive designed to impart softness, reduce static cling, and provide fragrance to textiles after washing. The primary functional ingredients are cationic surfactants, such as ester quats, which possess a positive charge that allows them to deposit onto the negatively charged surface of most fabric fibers. Liquid products continue to lead in the household consumer segment, though concentrated liquid formulations represent the fastest-growing category due to eco-friendly packaging and lower transport costs. Supermarkets and hypermarkets remain the primary distribution channel, but the online retail channel is expanding significantly.
Product formulation and market access are shaped by stringent chemical safety regulations. In Europe, the REACH regulation governs the registration and use of chemical substances, impacting ingredient selection. In the United States, the EPA's Safer Choice program provides a certification for products with safer chemical profiles, influencing consumer purchasing decisions. Stakeholder success will depend on navigating the complex trade-offs between performance, cost, and the rising consumer demand for sustainable ingredients.
Market Dynamics
The fabric softener market's evolution is defined by the transition to sustainable chemistry. This shift, driven by regulations like the EU's REACH framework, forces formulators to substitute petroleum-based ingredients with plant-derived alternatives, fundamentally altering cost structures and performance benchmarks.
Growth Catalysts
- Hospitality Sector Demand:Hotels and resorts are increasingly using premium fabric softeners to enhance linen quality and improve the guest experience, creating a significant B2B growth channel.
- Developing Economy Consumption:Rising disposable incomes and greater household appliance penetration in populous countries, particularly India, are expanding the consumer base for laundry care products.
- Concentrated Formulations:The push for smaller packaging and reduced transport emissions, supported by sustainability goals like the EU Green Deal, favors the adoption of concentrated liquid softeners.
Market Restraints
- Input Cost Volatility:Reliance on agricultural feedstocks like palm and soy for biodegradable ester quats exposes manufacturers to price fluctuations in global commodity markets.
- Performance Parity Challenges:Some bio-based formulations struggle to match the softening efficacy and fragrance longevity of traditional quaternary ammonium compounds, creating a performance gap.
- Regulatory Compliance Burden:The stringent data and testing requirements for chemical registration under frameworks like REACH can create significant costs and delays for introducing new ingredients.
Strategic Opportunities
- Specialty Textile Formulations:There is a growing opportunity to develop conditioners specifically for athletic wear and technical fabrics that preserve properties like moisture-wicking and elasticity.
- Direct-to-Consumer Models:Subscription services for concentrated refills and eco-friendly products offer a channel to build brand loyalty and bypass traditional retail shelf-space competition.
- African Market Penetration:Urbanization and an expanding middle class in several African nations present a largely untapped market for fabric care products as automatic washing machine ownership increases.
Industry Challenges
- Supply Chain Adaptation:Shifting production and logistics from standard liquids to concentrated formats requires significant capital investment in new mixing, filling, and packaging equipment.
- Consumer Value Communication:Manufacturers face the challenge of educating consumers on the benefits of sustainable or advanced formulations to justify premium price points over cheaper, conventional options.
- Eco-Label Navigation:Securing and maintaining multiple certifications, such as the EPA's Safer Choice, across different regions demands substantial administrative and testing resources.
Report Scope
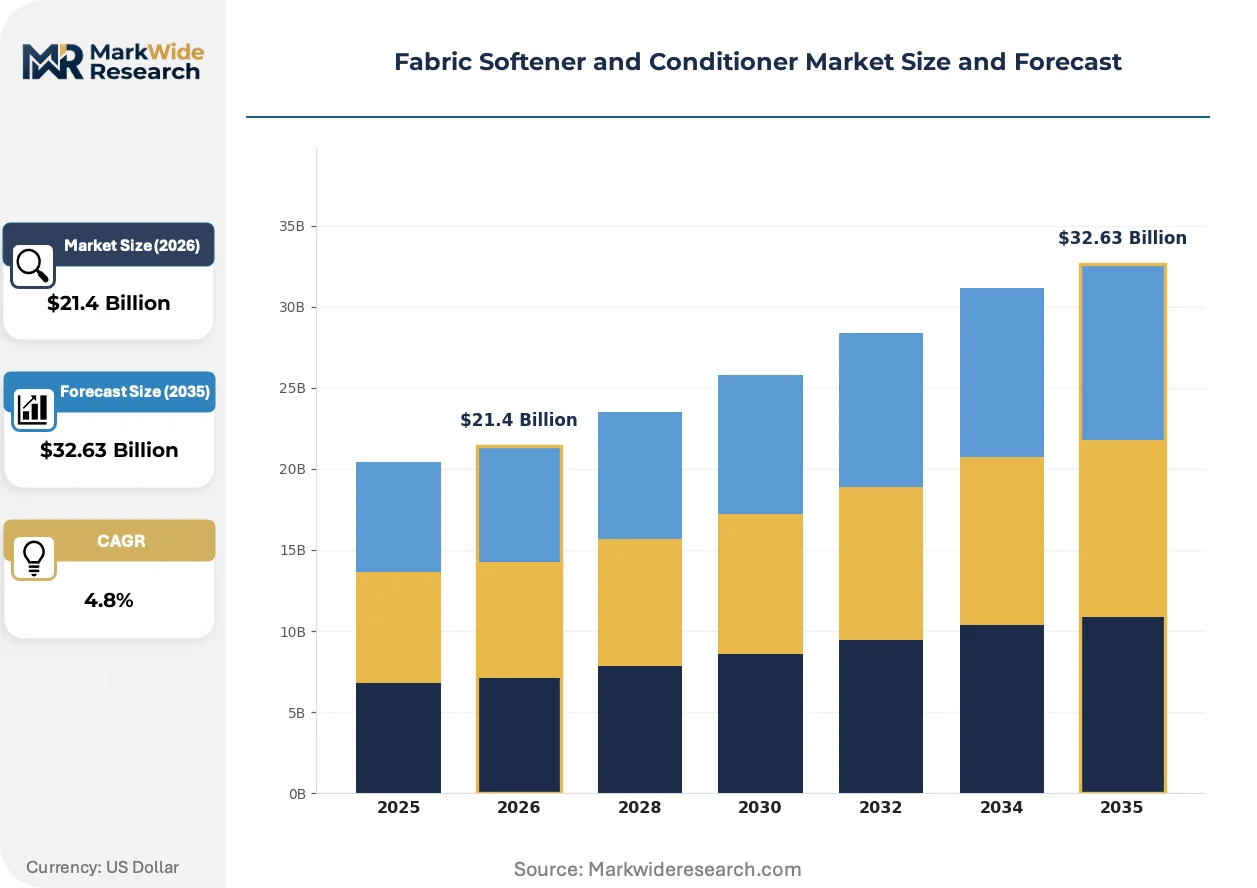
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Softener and Conditioner Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $32.63 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Dryer Sheets, Concentrated Liquid, Fabric Spray, Powder Formulation Technology: Quaternary Ammonium Compounds, Silicone-Based, Ester Quats, Cationic Surfactants, Natural Extracts End User: Household Consumers, Commercial Laundries, Hospitality Services, Textile Manufacturers, Healthcare Facilities Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Church & Dwight, Colgate-Palmolive, Procter & Gamble, S.C. Johnson & Son, Reckitt Benckiser Group, Unilever, Kao Corporation, LG Household and Healthcare, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Softener and Conditioner Market Strategic Shifts & Innovations
Material science advancements are redefining product efficacy and sustainability credentials. The market is witnessing a dual focus on creating high-performance formulations with advanced sensory benefits while simultaneously minimizing environmental impact through innovative chemistry and packaging solutions.
Microencapsulation technology provides a protective barrier for fragrance oils, enabling a delayed or friction-activated scent release on textiles. This feature is increasingly adopted by brands in the premium and concentrated product tiers to differentiate on performance. This sensory enhancement technology is converging with the development of biodegradable polymer shells for the capsules, addressing both consumer demand for long-lasting freshness and regulatory pressure to eliminate microplastics.
India's Plastic Waste Management Rules are creating significant momentum for packaging innovation. The regulation pressures manufacturers to increase the use of post-consumer recycled (PCR) content and develop viable extended producer responsibility (EPR) plans. The household consumer goods sector is most affected, accelerating the launch of concentrated products, refill pouches, and pilot programs for packaging take-back schemes to meet compliance targets.
A significant behavioral shift is underway as consumers migrate toward online channels for purchasing laundry care items. This trend disrupts the historical dominance of supermarkets and hypermarkets, creating openings for niche and direct-to-consumer brands to gain market access without competing for limited shelf space. This online purchasing pattern is most visible in North America and Western Europe, where established e-commerce infrastructure supports subscription models and bulk delivery.
Fabric Softener and Conditioner Market Segmentation
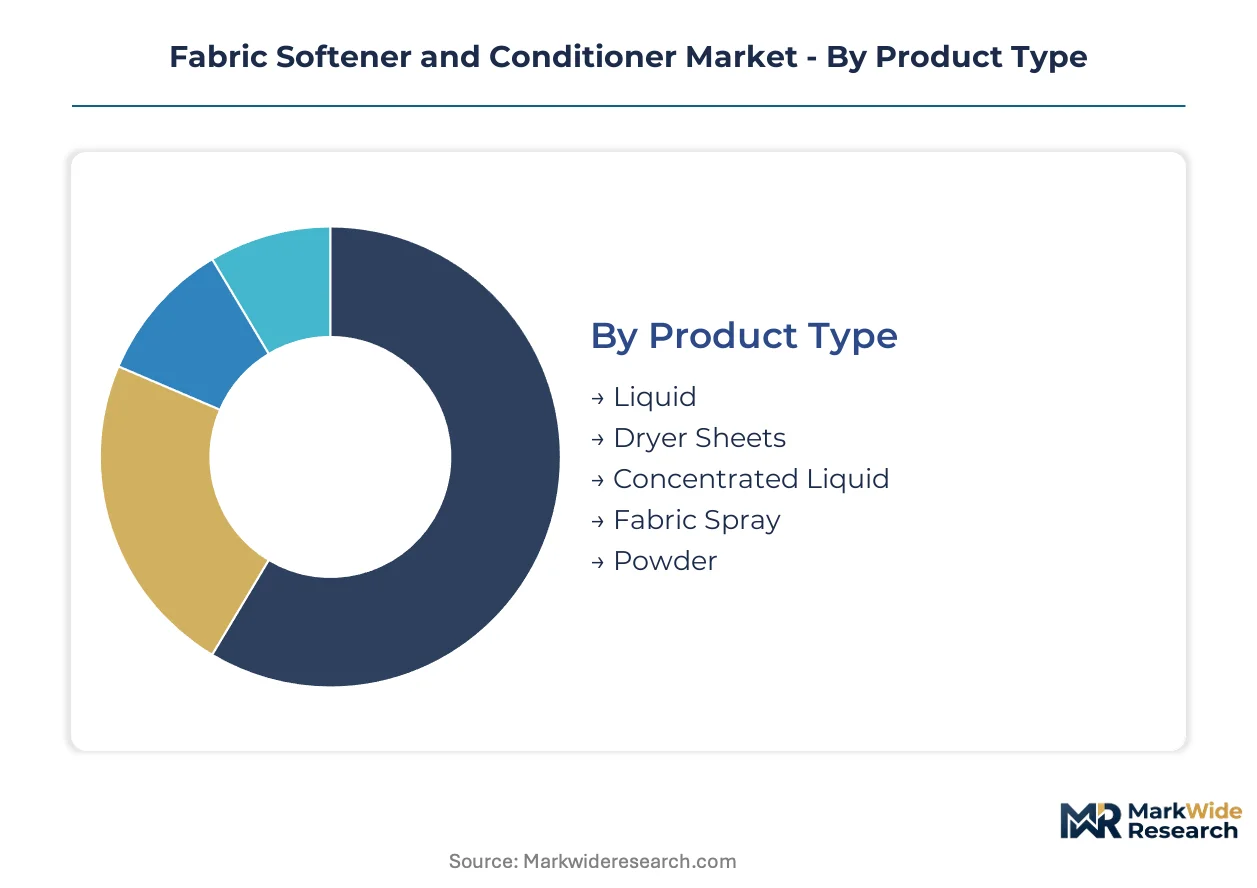
The fabric softener and conditioner market is segmented to reveal distinct consumer needs, technological advancements, and distribution pathways. This detailed classification helps stakeholders understand specific demand patterns and areas of concentrated value creation.
Product Type:
The product type segmentation illustrates the spectrum from highly standardized bulk liquids to specialized, targeted applications for fabric care.
- Liquid:Traditional liquid softeners consist of a dilute aqueous dispersion of cationic surfactants, providing softness and static reduction through fabric coating. Household consumers in populous developing economies like India maintain high demand for these conventional, accessible formats.
- Concentrated Liquid:These formulations offer reduced water content, delivering equivalent softening and fragrance benefits in a smaller volume. Demand is expanding significantly in Europe, driven by EU Green Deal initiatives promoting eco-friendly packaging and lower transport emissions.
- Dryer Sheets:These single-use sheets release softening agents and fragrance into laundry during the tumble drying cycle.
- Fabric Spray:Fabric sprays provide instant freshening and wrinkle reduction for garments between washes.
- Powder:Powdered fabric softeners, often integrated with detergents, offer convenience and are prevalent in specific regional markets.
Leading the category by volume: Liquid. Growing fastest: Concentrated Liquid.
Formulation Technology:
Formulation technology reflects the industry's evolving response to both performance demands and environmental sustainability mandates.
- Ester Quats:Ester quats are biodegradable, plant-based cationic surfactants, formed by esterification of fatty acids with triethanolamine, offering a sustainable alternative to traditional quats. Their adoption is increasing in Europe, influenced by stringent regulations like REACH, which scrutinize chemical substance environmental profiles.
- Quaternary Ammonium Compounds:These traditional compounds, primarily derived from petroleum, serve as the historical backbone for fabric softeners, providing effective softening and anti-static properties. Formulators face challenges in maintaining performance parity as the industry shifts towards more bio-based alternatives.
- Silicone-Based:Silicone-based additives impart a luxurious, smooth feel and enhanced wrinkle resistance to fabrics.
- Cationic Surfactants:This broad class of positively charged molecules underpins the core functionality of most fabric softeners by binding to negatively charged fibers.
- Natural Extracts:Formulations incorporating natural extracts, such as essential oils and plant-derived softeners, cater to consumer demand for eco-friendly and hypoallergenic products.
The shift towards Ester Quats is prominent, while Quaternary Ammonium Compounds continue to define performance benchmarks.
End User:
The end-user segmentation delineates consumption patterns from individual household needs to large-scale industrial textile care operations.
- Household Consumers:This segment encompasses individual households purchasing fabric softeners for personal laundry care, driven by preferences for softness, fragrance, and static reduction. Rising disposable incomes in developing economies like India are expanding the consumer base for these products.
- Hospitality Services:Hotels, resorts, and cruise lines utilize fabric softeners to maintain linen quality, enhance guest comfort, and extend textile lifespan. Premium fabric softeners are increasingly adopted to meet guest expectations for superior linen quality, creating a significant B2B growth channel.
- Commercial Laundries:These facilities process large volumes of textiles for various clients, requiring efficient and cost-effective fabric care solutions.
- Textile Manufacturers:Manufacturers integrate softeners into textile finishing processes to improve fabric hand-feel, drape, and processability.
- Healthcare Facilities:Hospitals and clinics use specialized fabric softeners that are hypoallergenic and compatible with stringent hygiene protocols for patient linens.
While Household Consumers dominate volume, Hospitality Services represent a significant growth area for specialized products.
Distribution Channel:
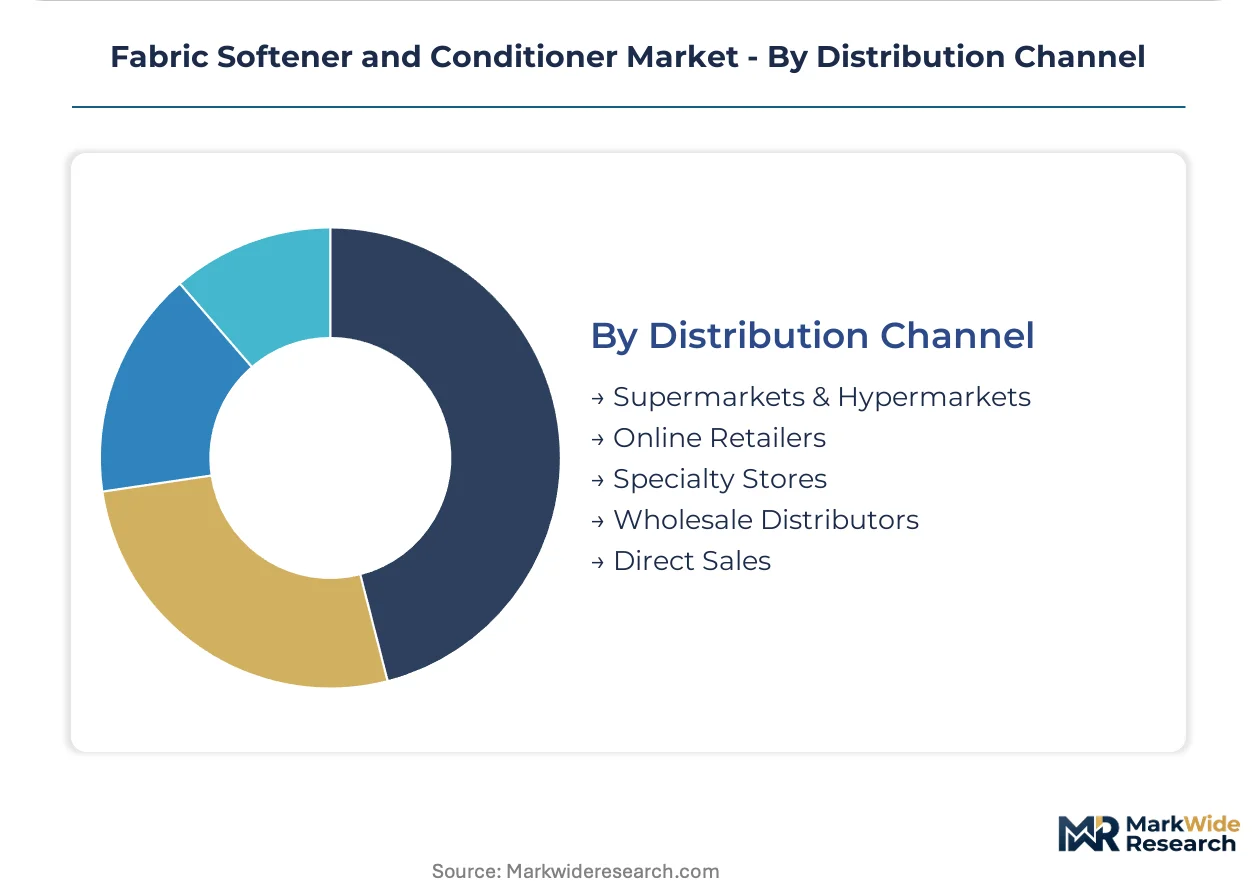
Distribution channels reflect diverse market access strategies, ranging from traditional brick-and-mortar retail to rapidly expanding digital platforms.
- Supermarkets & Hypermarkets:These large-format retail outlets serve as the primary point of sale for fabric softeners, offering broad product assortments and competitive pricing. Their established infrastructure and consumer footfall continue to drive substantial sales volumes across most global markets.
- Online Retailers:E-commerce platforms facilitate the direct purchase and delivery of fabric care products, offering convenience and access to niche brands. This channel is expanding significantly in North America and Western Europe, supported by robust e-commerce infrastructure and subscription models.
- Specialty Stores:These retailers offer curated selections of premium, eco-friendly, or niche fabric care products, targeting specific consumer preferences.
- Wholesale Distributors:Wholesale distributors supply bulk fabric softeners to commercial laundries, hospitality services, and other institutional buyers.
- Direct Sales:Some manufacturers engage in direct sales to consumers or businesses, often through proprietary websites or dedicated sales teams.
The market maintains a strong presence in Supermarkets & Hypermarkets, while Online Retailers are gaining share rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fabric softener and conditioner concentrates significantly in populous, developing economies, particularly India, as disposable incomes rise. Europe drives the adoption of concentrated formulations due to stringent environmental regulations and consumer preferences for sustainable products. The United States also exhibits strong demand for products with safer chemical profiles and a growing online retail presence.
India
Rising disposable incomes and increasing household appliance penetration are primary demand drivers in India. The nation's Plastic Waste Management Rules are influencing packaging innovation, pushing manufacturers towards recycled content. Major consumer goods hubs like Mumbai and Delhi-NCR serve as critical distribution centers for fabric care products.
Germany
Germany leads European demand for concentrated liquid formulations, driven by strong environmental consciousness. The EU's REACH framework significantly impacts ingredient selection, favoring biodegradable alternatives. Chemical industry clusters in the Rhine-Ruhr region actively develop and produce sustainable fabric softener components for regional and global markets.
United States
Consumer preferences for sustainable and safer chemical profiles are shaping product development in the United States. The EPA's Safer Choice program guides consumer purchasing decisions, influencing formulation choices. Major e-commerce infrastructure along the East Coast and West Coast supports the expanding online retail channel for laundry care items.
South Africa
Urbanization and an expanding middle class are increasing the consumer base for fabric care products in South Africa. The National Environmental Management Act (NEMA) influences environmental standards for chemical products. Key urban centers like Johannesburg and Cape Town are seeing increased automatic washing machine ownership, boosting product consumption.
China
China's vast consumer market presents substantial opportunities for fabric softener and conditioner growth. GB standards govern product safety and quality, ensuring compliance for market entry. The Yangtze River Delta region is a significant hub for manufacturing and distribution of household consumer goods, including fabric care products.
Fabric Softener and Conditioner Market Key Industry Players
Portfolio diversification dominates the current landscape, as major players expand their offerings to meet varied consumer needs and regulatory demands. The market exhibits a tiered structure, encompassing global conglomerates, specialized regional players, and emerging sustainable innovators. Strategic archetypes include those focused on extensive R&D capabilities, niche market penetration, and broad market access. Key competitive moves involve significant investment in advanced formulations and geographic expansion into high-growth developing economies.
On the global conglomerate vector, Procter & Gamble exemplifies extensive research and development capabilities, driving innovation in advanced formulations. Henkel, a European-based company, occupies a position focused on specific market niches and strong brand positioning within key European countries. Unilever, a multinational consumer goods company, sits within the broad market access segment, leveraging its extensive distribution networks across diverse geographies.
| Leading Market Players |
|---|
| Church & Dwight |
| Colgate-Palmolive |
| Procter & Gamble |
| S.C. Johnson & Son |
| Reckitt Benckiser Group |
| Unilever |
| Kao Corporation |
| LG Household and Healthcare |
| Henkel |
| Others |
Cost & Logistics Intelligence
Consumer demand for sustainable, plant-based ingredients is reshaping the fabric softener supply chain. This shift forces formulators to adapt sourcing strategies, impacting overall product pricing.
Pricing Analysis
Volume sales in the household consumer segment typically operate on tighter margins, while specialized products for hospitality services command premium pricing. Pricing stratifies across premium, standard, and economy tiers. Performance parity with traditional compounds and brand premium drive significant price differentiation. Pricing pressure stems from the input cost volatility of agricultural feedstocks, and household consumers exhibit high price sensitivity. Hospitality services prioritize product efficacy for guest satisfaction, demonstrating lower price sensitivity.
Supply Chain Analysis
Distribution runs primarily through supermarkets and hypermarkets for household consumers, while wholesale distributors serve commercial and hospitality clients. Supply concentration for key ingredients like ester quats is found in regions with strong chemical industries, such as Germany, and raw material sourcing relies on agricultural feedstocks from diverse global markets. Commodity price volatility for these agricultural inputs represents a structural supply chain risk. Online retail channels are expanding rapidly, altering traditional distribution patterns for finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fabric softener market is fundamentally a cost-of-compliance story, where stringent regulations like the EU's REACH framework create a barrier-to-entry moat for compliant formulators. This necessitates significant investment in sustainable chemistry and ingredient registration.
For Market Incumbents:To counter performance parity challenges from bio-based alternatives, incumbents should invest heavily in R&D for advanced ester quats. This deepens vertical integration into sustainable raw material sourcing, mitigating input price volatility. Capacity addition in developing economies like India can secure market share for conventional products.
For New Entrants and Emerging Players:Launch specialized formulations via direct-to-consumer subscription models, targeting the premium segment in North America. This allows niche brands to bypass traditional retail shelf-space competition. Developing products for athletic wear or technical fabrics represents a white-space opportunity. Focus on eco-friendly packaging and transparent ingredient lists.
For Investors and Strategic Acquirers:The window for entry favors mid-cap specialists with proven sustainable chemistry and agile supply chains over the next five to ten years. Acquisition targets include firms excelling in biodegradable ester quat development or microencapsulation technology. The signal to watch is the widespread adoption of concentrated formulations in new regional markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and ensures compliance with EU Green Deal objectives for product lifecycle. |
| Advanced Formulation R&D | Develops high-performance bio-based alternatives, addressing consumer demand for sustainability and efficacy. |
| Direct-to-Consumer Channel Expansion | Builds brand loyalty and offers access to niche consumer segments in North America and Western Europe. |
| Packaging Innovation for PCR Content | Meets regulatory mandates like India's Plastic Waste Management Rules, enhancing brand sustainability credentials. |
| Geographic Market Penetration in Africa | Capitalizes on urbanization and increasing automatic washing machine ownership in untapped regions. |
Research Approach
Document review covered regulatory filings, academic literature, and corporate sustainability reports, complemented by interviews with industry stakeholders. We engaged R&D directors, procurement leads for raw materials, and category managers at major retailers. This approach triangulated bottom-up market intelligence with top-down industry trends.
Historical market data was cross-referenced with expert panel input to project market trajectories across the analysis window. The model segmented by product type, formulation technology, end-user, and regional consumption patterns. Compound Annual Growth Rates were derived from an iterative assessment of market drivers and restraints. Forecast inputs included raw material price trends and regulatory compliance costs.
The model assumes a particular technology adoption path; alternative pathways for ester quats or microencapsulation would alter the outlook. Forecasts reflect current regulatory landscapes and economic projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Biocides Market