
 Instrument Cleaners and Detergents Market | 2026-2036
Instrument Cleaners and Detergents Market Size, Share, and Industry Trends Forecast 2026-2036
Instrument Cleaners and Detergents Market Foresight
EU MDR reprocessing validation requirements is hardening demand for enzymatic and neutral pH instrument cleaners across European healthcare systems. STERIS Plc leverages its global sterilization services network to bundle detergent contracts with equipment placements. Ecolab Inc. anchors institutional cleaning protocols through integrated water and energy management programs in hospital central sterile departments. Getinge Group competes by linking washer-disinfector hardware with proprietary chemistry formulations.
Instrument cleaners and detergents are aqueous or solvent-based formulations designed to remove biological soils, mineral deposits, and lubricants from reusable medical devices, typically operating within specific pH ranges and temperature parameters validated for material compatibility with stainless steel, aluminum, and polymer instruments. Their primary commercial purpose is to prepare instruments for subsequent disinfection or sterilization by eliminating interfering organic residues that compromise microbial kill efficacy. Liquid enzymatic formulations lead the product type landscape due to faster soil breakdown kinetics, while biodegradable chemistries represent the fastest-expanding formulation category as procurement teams embed sustainability scoring into tender evaluations. Surface cleaning applications within healthcare facilities command the deepest margin pools because of recurring volume contracts tied to infection control accreditation cycles.
The FDA enforces reprocessing validation through 510(k) clearances that require manufacturers to demonstrate cleaning efficacy using specified chemistries on labeled devices, directly shaping detergent selection in US sterile processing departments. EMA's Medical Device Regulation and REACH chemical restrictions in Europe compound formulation complexity by mandating biodegradability thresholds and substance disclosure that exceed prior Medical Device Directive standards. Stakeholders must monitor how diverging US and EU validation pathways reshape global product registration strategies and regional manufacturing footprints.
Market Dynamics
Hospital sterile processing departments are consolidating vendor relationships around validated cleaning chemistries as FDA 510(k) reprocessing requirements harden material compatibility documentation. This regulatory compression is forcing detergent manufacturers to absorb validation costs previously borne by device makers.
Growth Catalysts
- Surgical volume recovery:Elective procedure backlogs in tertiary care centers are expanding enzymatic detergent procurement cycles. Central sterile supply departments are restocking multi-year contracts.
- EU MDR reprocessing validation:The Medical Device Regulation mandates substance disclosure thresholds that exceed prior directive standards. European healthcare systems are sourcing higher-grade instrument cleaners.
- Enzymatic formulation chemistry:Protease-lipase-amylase blends accelerate soil breakdown kinetics at lower temperatures. This performance edge is displacing alkaline cleaners in washer-disinfector protocols.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and solvent inputs track crude oil derivatives. Detergent manufacturers face margin compression when input costs spike without contract repricing mechanisms.
- German supply concentration:Central sterile supply hardware and chemistry clusters around Getinge Group and Dr. Weigert create single-source dependencies. Buyers face limited alternatives for integrated washer-disinfector chemistry bundles.
- REACH biodegradability thresholds:ECHA mandates on aquatic toxicity and substance persistence eliminate legacy quaternary ammonium formulations. Reformulation timelines stretch 18-24 months for full registration.
Strategic Opportunities
- Biodegradable chemistry certification:Procurement teams are embedding sustainability scoring into tender evaluations. Products with Nordic Swan or EU Ecolabel credentials command preference in Scandinavian and Benelux hospital systems.
- Point-of-use pre-cleaning foams:Operating room staff are adopting enzymatic sprays for immediate post-procedure soil stabilization. This channel bypasses central sterile supply contracting delays.
- Water-stressed geographies:California and Arizona hospital systems face escalating wastewater discharge costs. Low-foaming, cold-water enzymatic formulations reduce rinse cycle volumes.
Industry Challenges
- Sterile processing technician certification:CBSPD and IAHCSMM credentialing requirements are tightening. Workforce shortages delay implementation of new chemistry protocols in hospital departments.
- Legacy washer-disinfector compatibility:Older Getinge and Belimed hardware lacks temperature and pH sensors for next-generation enzymatic detergents. Capital replacement cycles lag chemistry innovation.
- 510(k) cleaning validation documentation:FDA requires device manufacturers to specify chemistries on labeling. Detergent suppliers must maintain exhaustive efficacy dossiers for each device-material combination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrument Cleaners and Detergents Market |
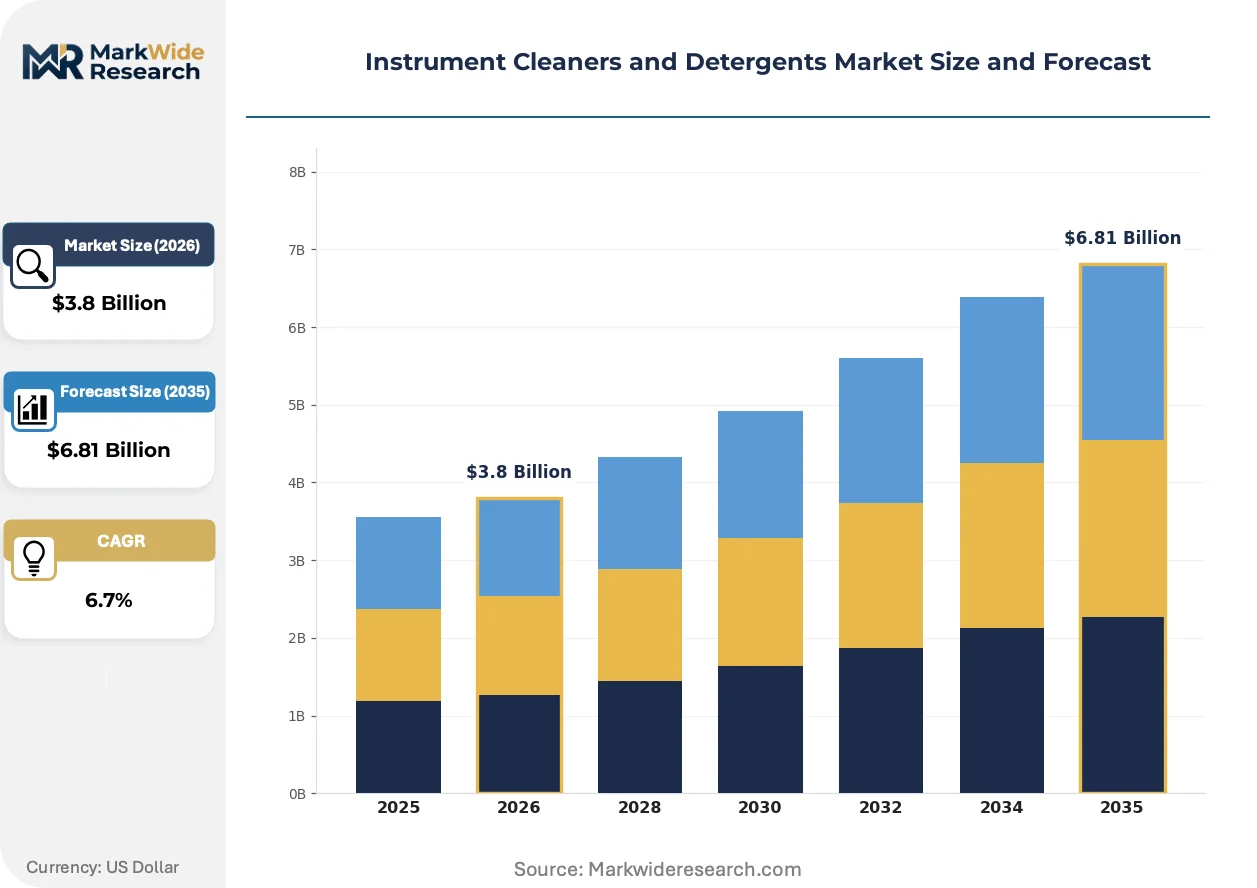
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Powder Cleaners, Foam Cleaners, Wipes End User: Healthcare Facilities, Research Laboratories, Food Processing Industries, Dental Clinics Application: Instrument Maintenance, Surface Cleaning, Disinfection, Sterilization Formulation: Biodegradable, Alkali-Based, Acidic, Enzymatic |
| Companies Covered | STERIS Plc, Ecolab Inc., Getinge Group, 3M Co., Dr. Weigert, Advanced Sterilization Products, Ruhof, Medline Industries, Cantel Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrument Cleaners and Detergents Market Shifts & Advancements
Formulation science is converging with sustainability mandates and automation compatibility requirements. Three developments are compressing competitive timelines and reshaping procurement criteria.
Multi-enzymatic detergent concentrates with stabilized protease, amylase, and lipase activity are rewriting soil removal protocols in automated washer-disinfectors. These formulations operate effectively at 45°C versus 60°C for alkaline chemistries. German and Swiss hospital systems are adopting them to cut energy consumption. The technology is compressing differentiation among mid-tier detergent suppliers.
REACH chemical restrictions and the EU MDR are tightening substance disclosure and biodegradability requirements for instrument cleaners. Formulators must now document aquatic toxicity and persistence profiles that exceed prior Medical Device Directive standards. European manufacturers are eliminating quaternary ammonium compounds and alkylphenol ethoxylates from new product pipelines. This regulatory compression favors suppliers with dedicated regulatory affairs teams.
Hospital procurement departments are consolidating chemistry contracts with equipment vendors through bundled service agreements. Central sterile supply directors prefer single-source accountability for washer-disinfector performance. This buying-pattern shift is squeezing standalone detergent manufacturers. The trend is most visible in US health system consolidation, where IDN procurement offices negotiate enterprise-wide chemistry specifications.
Instrument Cleaners and Detergents Market Segmentation
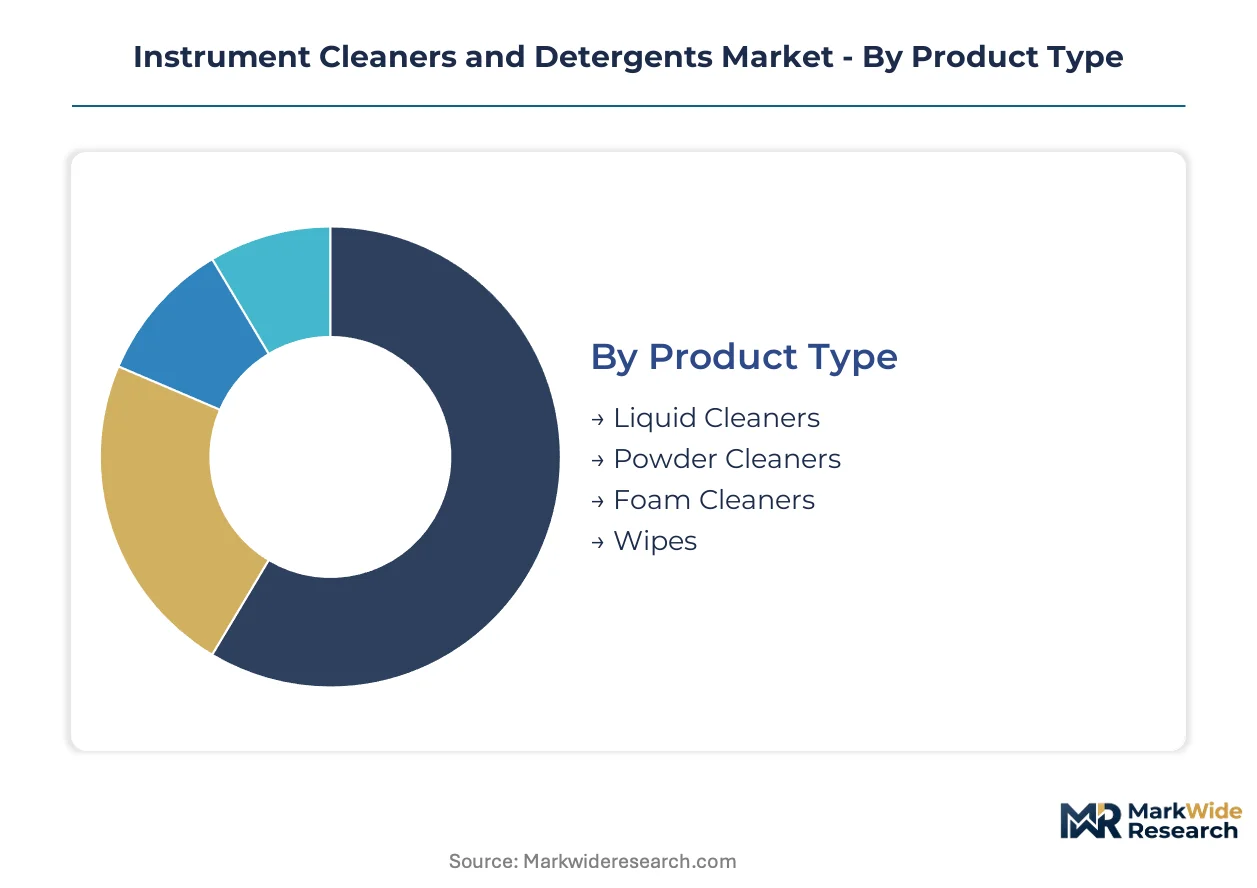
Segmentation in instrument cleaners and detergents reveals how procurement priorities diverge across sterilization workflows, regulatory environments, and material compatibility requirements. Understanding these splits enables suppliers to align formulation investments with specific validation burdens and end-user operational constraints.
Product Type:
Liquid enzymatic concentrates demand the heaviest upfront capital in formulation stabilization and cold-chain logistics infrastructure. Powder systems require lower initial manufacturing investment but face higher packaging and dust-control compliance costs.
- Liquid Cleaners:Aqueous enzymatic and neutral pH formulations dominate sterile processing departments for their rapid soil penetration and compatibility with automated washer-disinfector dosing systems. Demand concentrates in US tertiary care centers where FDA 510(k) validation requirements favor documented cleaning efficacy protocols.
- Powder Cleaners:Alkaline powder formulations persist in cost-sensitive healthcare systems and legacy washer-disinfector installations without precision liquid dosing pumps. German central sterile supply departments retain powder procurement for high-volume surgical instrument batches where temperature parameters exceed liquid enzymatic thresholds.
- Foam Cleaners:Pre-cleaning enzymatic foams stabilize biological soils at point-of-use before transport to central sterile processing.
- Wipes:Saturated wipe formats serve dental clinics and outpatient surgical centers with limited washer-disinfector infrastructure.
Liquid cleaners absorb the bulk of installed capacity; foam cleaners are expanding most quickly through operating room point-of-use adoption.
End User:
Healthcare facilities generate the highest absolute volumes but operate on extended tender cycles with rigorous chemistry validation requirements. Dental clinics and research laboratories purchase at smaller scale yet accept faster product substitution when formulations demonstrate superior material compatibility.
- Healthcare Facilities:Hospital sterile processing departments procure multi-year contracts for enzymatic detergents validated against specific washer-disinfector hardware. US health system consolidation is compressing vendor lists as IDN procurement offices standardize chemistry specifications across enterprise networks.
- Research Laboratories:Academic and pharmaceutical research facilities prioritize residue-free formulations that eliminate interference with analytical instrumentation. Swiss and German life sciences clusters source specialized neutral pH cleaners to protect precision surgical microscopes and endoscopic tools used in preclinical studies.
- Food Processing Industries:Commercial kitchens and protein processing plants deploy instrument-grade cleaners for cutting tool maintenance under HACCP protocols.
- Dental Clinics:Small-scale practices favor pre-moistened wipes and spray formulations for immediate instrument turnover between patients.
Healthcare facilities command the deepest procurement relationships; research laboratories are climbing the fastest as biopharma expansion drives specialized cleaning chemistry demand.
Application:
Surface cleaning applications generate recurring revenue through infection control accreditation cycles, while sterilization preparation demands the most intensive chemistry validation documentation. Instrument maintenance sits at the intersection of both requirements with the longest sales cycles.
- Instrument Maintenance:Cleaning chemistries for reusable surgical devices must demonstrate material compatibility with stainless steel, aluminum, and polymer substrates while eliminating interfering residues prior to disinfection or sterilization steps. REACH biodegradability mandates in Europe are eliminating legacy quaternary ammonium formulations from maintenance protocols.
- Surface Cleaning:Environmental cleaning in operating theaters and patient care areas operates on shorter procurement cycles tied to accreditation surveys. California hospital systems facing wastewater discharge cost escalation are sourcing low-foaming enzymatic formulations to reduce rinse cycle volumes.
- Disinfection:Pre-cleaning chemistries must remove organic soils before high-level disinfection procedures commence.
- Sterilization:Terminal sterilization preparation demands the most exhaustive cleaning validation documentation under FDA and EMA frameworks.
Surface cleaning generates the highest transaction frequency; sterilization applications are gaining share fastest as reprocessing validation requirements harden globally.
Formulation:
Enzymatic formulations require sustained R&D investment in protease, lipase, and amylase stabilization technologies. Biodegradable chemistry development faces extended 18-24 month registration timelines under ECHA persistence and aquatic toxicity evaluation protocols.
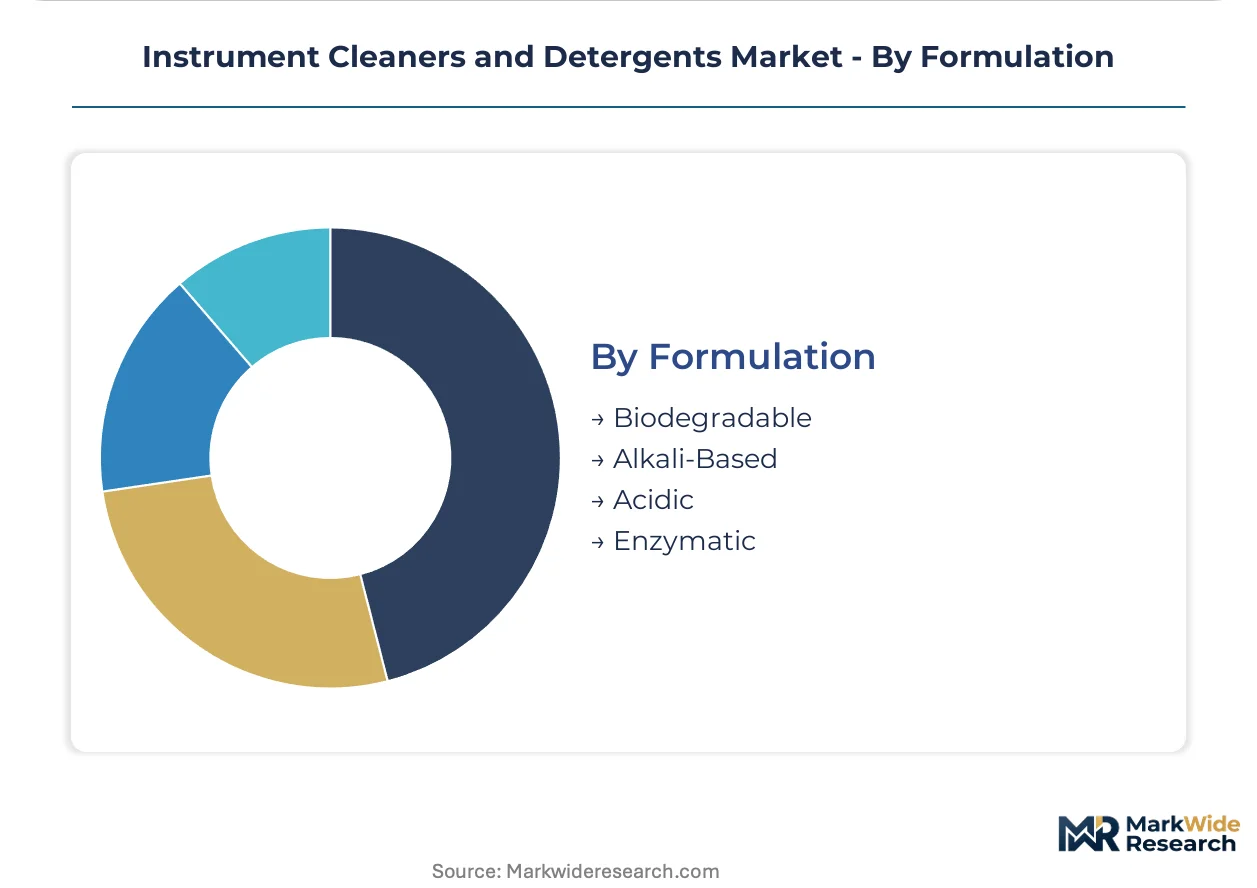
- Biodegradable:Formulations meeting Nordic Swan or EU Ecolabel certification criteria are securing preference in Scandinavian and Benelux hospital procurement tenders. Sustainability scoring integration into tender evaluations is accelerating biodegradable chemistry substitution for legacy petrochemical surfactants.
- Enzymatic:Multi-enzyme blends with stabilized protease, amylase, and lipase activity operate effectively at 45°C versus 60°C for alkaline alternatives. German and Swiss hospital systems have adopted these formulations to reduce energy consumption in washer-disinfector cycles.
- Alkali-Based:High-pH formulations persist for heavy mineral deposit removal and legacy hardware compatibility.
- Acidic:Low-pH chemistries target specific scale and corrosion removal applications in dental and ophthalmic instrument processing.
Enzymatic formulations hold the largest installed base; biodegradable chemistries represent the steepest expansion trajectory as regulatory thresholds tighten and procurement sustainability criteria mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solna anchors European sterile processing innovation through Getinge Group's integrated washer-disinfector manufacturing cluster. German chemical formulators in Hamburg and Lübeck supply enzymatic detergent concentrates validated under EU MDR protocols. Swiss hospital systems in Basel and Zurich drive cold-water enzymatic adoption to reduce energy consumption.
United States
FDA 510(k) reprocessing validation requirements concentrate detergent procurement around documented efficacy protocols. Hospital sterile processing departments in Cleveland and Minneapolis anchor multi-year supply contracts with integrated service providers. IDN procurement offices in Texas and California standardize chemistry specifications across enterprise networks to reduce vendor complexity.
Germany
EU MDR substance disclosure mandates exceed prior Medical Device Directive standards for instrument cleaners. REACH biodegradability thresholds eliminate legacy quaternary ammonium formulations from Hamburg and Berlin hospital systems. The Lübeck-Stockholm corridor clusters central sterile supply hardware and chemistry manufacturing around Getinge and Dr. Weigert operations.
Switzerland
Swissmedic enforcement of reprocessing validation hardens demand for neutral pH enzymatic formulations. Basel life sciences facilities source specialized cleaners to protect precision surgical microscopes used in preclinical studies. Zurich hospital systems adopt 45°C enzymatic cycles to cut washer-disinfector energy consumption.
United Kingdom
NHS procurement frameworks prioritize sustainability scoring in tender evaluations for instrument cleaners. London and Manchester hospital systems source Nordic Swan-certified biodegradable formulations. The Cambridge-Oxford corridor drives specialized demand from pharmaceutical research facilities requiring residue-free chemistries.
Japan
METI energy efficiency guidelines push Osaka and Tokyo medical centers toward low-temperature enzymatic protocols. PMDA alignment with international reprocessing standards validates cleaning chemistry dossiers for export markets. Nagoya manufacturing clusters supply automated washer-disinfector dosing systems to domestic hospital networks.
Instrument Cleaners and Detergents Market Competitive Landscape
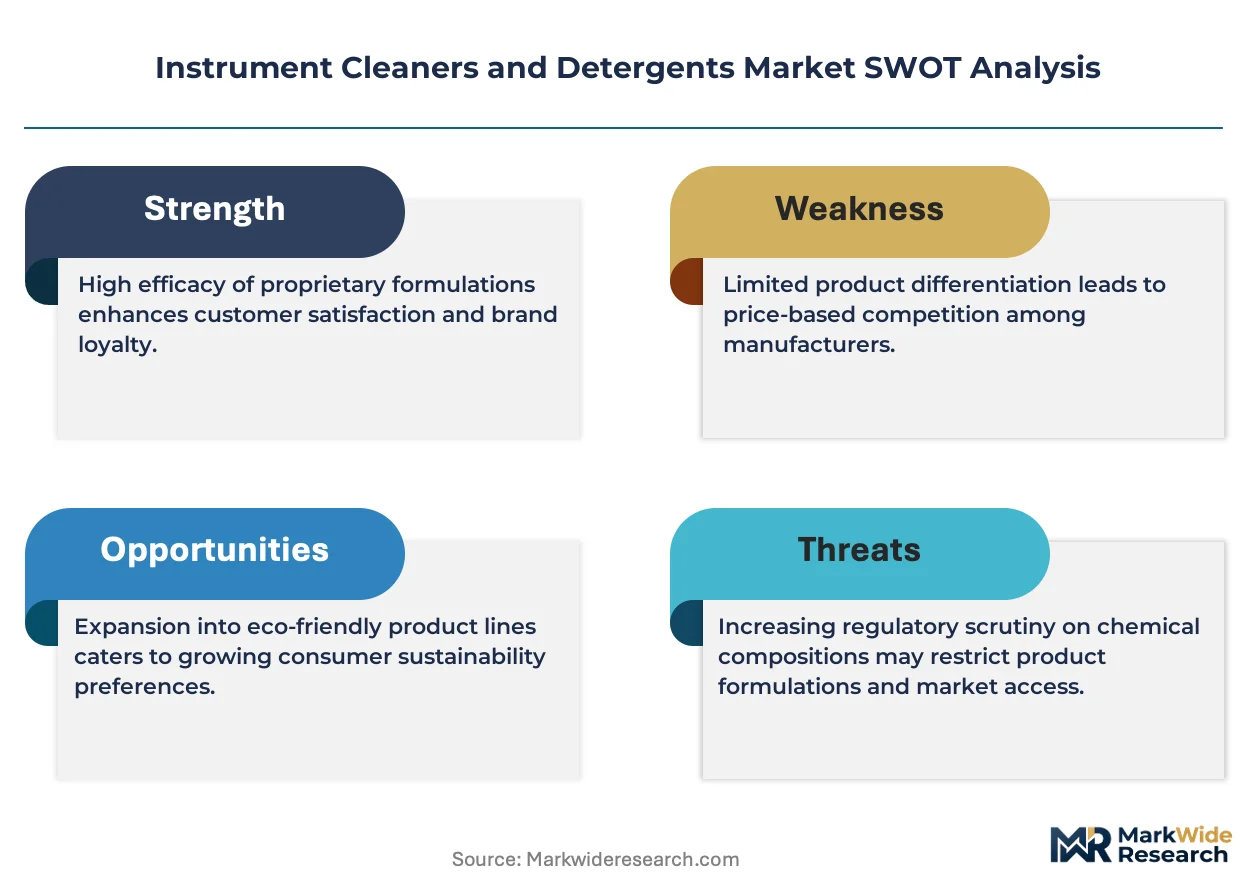
The competitive structure tilts toward integrated equipment-chemistry bundling. Washer-disinfector manufacturers capture detergent procurement decisions through validated protocol specifications. Three archetypes dominate: sterilization service networks, institutional hygiene conglomerates, and specialized central sterile supply formulators. Strategic moves concentrate on regulatory dossier maintenance and sustainability certification acquisition.
Among integrated sterilization service providers, STERIS Plc occupies a position bundling detergent contracts with equipment placements across US health systems. Ecolab Inc. exemplifies the institutional hygiene conglomerate archetype, anchoring hospital central sterile departments through water and energy management program integration. Getinge Group represents the hardware-chemistry bundling specialist, linking washer-disinfector platforms with proprietary enzymatic formulations.
| Leading Market Players |
|---|
| STERIS Plc |
| Ecolab Inc. |
| Getinge Group |
| 3M Co. |
| Dr. Weigert |
| Advanced Sterilization Products |
| Ruhof |
| Medline Industries |
| Cantel Medical |
| Others |
Supply & Pricing Matrix
EU MDR certification tiers bifurcate procurement between validated enzymatic concentrates and legacy alkaline formulations, compressing margins for suppliers lacking regulatory dossiers while concentrating premium pricing power with integrated hardware-chemistry bundlers. This tier divergence manifests in supply chain configurations where German and Swiss manufacturers anchor cold-chain logistics for stabilized enzyme concentrates, while commodity powder suppliers face distribution disintermediation.
Pricing Analysis
Throughput-linked value anchors pricing for enzymatic detergents validated against specific washer-disinfector protocols, with STERIS and Getinge bundling chemistry contracts to equipment placements. Price differentiation rests on FDA 510(k) validation documentation and EU MDR substance disclosure compliance, with Nordic Swan-certified biodegradable formulations commanding 15-25% premiums over legacy surfactants. Cost compression in alkaline powder segments intensifies as REACH biodegradability mandates force reformulation investments. Dental clinics and outpatient surgical centers exhibit highest price sensitivity due to limited washer-disinfector infrastructure and absence of multi-year enterprise contracts.
Supply Chain Analysis
Specialized chemical workforce availability in Hamburg, Lübeck, and Solna clusters enzymatic formulation manufacturing around Getinge Group and Dr. Weigert operations. Supply draws from petrochemical feedstocks for surfactant precursors and precision fermentation capacity for protease-lipase-amylase blends. Single-source vulnerability concentrates in German central sterile supply hardware-chemistry bundling, where integrated vendor relationships limit buyer alternatives. Distribution runs through health system GPO contracts and direct hospital procurement frameworks, with IDN consolidation compressing vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in validated enzymatic formulation capacity prop pricing power for manufacturers with established EU MDR dossiers, with REACH registration timelines creating 18-24 month bottlenecks for new entrants seeking biodegradable certification.
For Market Incumbents: Extend regulatory dossier maintenance investments to capture EU MDR validation requirements that emerging competitors cannot replicate within contract cycles. Deepen backward integration into protease stabilization technologies to defend margin position against petrochemical feedstock volatility threatening surfactant-dependent formulations. For New Entrants and Emerging Players: Point-of-use pre-cleaning foam adoption in US ambulatory surgical centers represents the most penetrable white-space target, bypassing central sterile supply contracting delays and IDN procurement consolidation. Pursue direct-to-facility distribution partnerships with regional dental supply distributors lacking enzymatic chemistry portfolios. For Investors and Strategic Acquirers: Re-rating potential sits with specialized enzymatic formulators possessing EU MDR registration infrastructure given sustainability scoring integration into Scandinavian and Benelux hospital tenders. Long-term viability favors acquisition targets with captive regulatory affairs teams and established Nordic Swan certification pathways. Monitor REACH substance restriction announcements as inflection indicators for accelerated biodegradable chemistry substitution.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Dossier Expansion | Validates cleaning efficacy claims for enzymatic concentrates under EMA substance disclosure mandates exceeding prior directive standards. |
| Biodegradable Certification Investment | Secures Nordic Swan and EU Ecolabel credentials for preference in Scandinavian hospital sustainability-scored tenders. |
| Washer-Disinfector Bundling Agreements | Links detergent procurement to Getinge and Belimed hardware placements, capturing central sterile supply director accountability. |
| Cold-Chain Logistics Infrastructure | Enables stabilized multi-enzyme concentrate distribution from Hamburg and Solna manufacturing clusters to European hospital networks. |
| Point-of-Use Foam Channel Development | Bypasses IDN procurement consolidation by targeting operating room staff for immediate post-procedure soil stabilization adoption. |
Research Methodology
Document review covered FDA 510(k) reprocessing guidance, EMA Medical Device Regulation substance disclosure protocols, and REACH biodegradability evaluation frameworks, complemented by interviews with sterile processing department directors, central sterile supply procurement managers, GPO contracts specialists, and enzymatic formulation R&D directors. Secondary validation drew from hospital procurement database audits, customs trade data for surfactant imports, and SEC filings of integrated sterilization service providers. Bottom-up demand modeling triangulated against top-down healthcare expenditure allocation analysis.
Cross-referencing historical tender award patterns with expert panel input on EU MDR implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type concentration, end-user facility scale, application workflow position, and formulation chemistry class. CAGRs derived from surgical volume recovery trajectories, energy efficiency adoption curves for cold-water enzymatic cycles, and sustainability scoring penetration rates in European procurement frameworks.
Revisions become necessary when REACH substance restriction announcements accelerate quaternary ammonium compound phase-outs, FDA reprocessing guidance shifts validation burden allocation, or health system consolidation alters GPO contracting leverage. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Water-Saving Cleaning Chemical Systems for Professional Use Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market