
 Chlorhexidine Gluconate (CHG) Cloth Market | 2026-2036
Chlorhexidine Gluconate (CHG) Cloth Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorhexidine Gluconate (CHG) Cloth Market Outlook
The gap between conventional alcohol-based prep solutions and CHG-impregnated cloth systems is narrowing as manufacturers integrate sustained-release polymer matrices into woven substrates. Molnlycke Health Care leverages its Nordic hygiene heritage to anchor premium positioning in European surgical suites. BD sustains R&D intensity across antiseptic delivery formats, while Medline Industries controls distribution scale through direct hospital contracting networks.
Chlorhexidine gluconate cloths are non-woven or woven textile substrates impregnated with chlorhexidine gluconate solution, typically at concentrations between 2% and 4%, designed for preoperative skin antisepsis and ongoing patient bathing to reduce microbial bioburden. The product's primary commercial purpose centers on replacing traditional aqueous scrubs with single-use, standardized-dose applications that minimize cross-contamination risk. Pre-moistened cloths dominate current revenue pools due to their convenience and compliance advantages in time-constrained clinical settings, while patient gowns represent the fastest-growing category as facilities adopt full-body decolonization protocols. Hospitals remain the anchor end-user segment, though home health agencies are expanding procurement as post-acute infection prevention programs extend beyond institutional boundaries.
FDA premarket notification requirements and EPA pesticide device registrations govern CHG cloth commercialization in the United States, with the agency's antiseptic guidance documents directly shaping acceptable efficacy endpoints and labeling claims. The EU Medical Device Regulation and REACH chemical compliance frameworks impose additional conformity obligations for European market access, while Health Canada's Natural and Non-prescription Health Products Directorate oversees northern American distribution. Stakeholders must monitor evolving antiseptic resistance surveillance data and regulatory reclassification risks as healthcare-associated infection prevention strategies shift toward bundled intervention models.
Market Dynamics
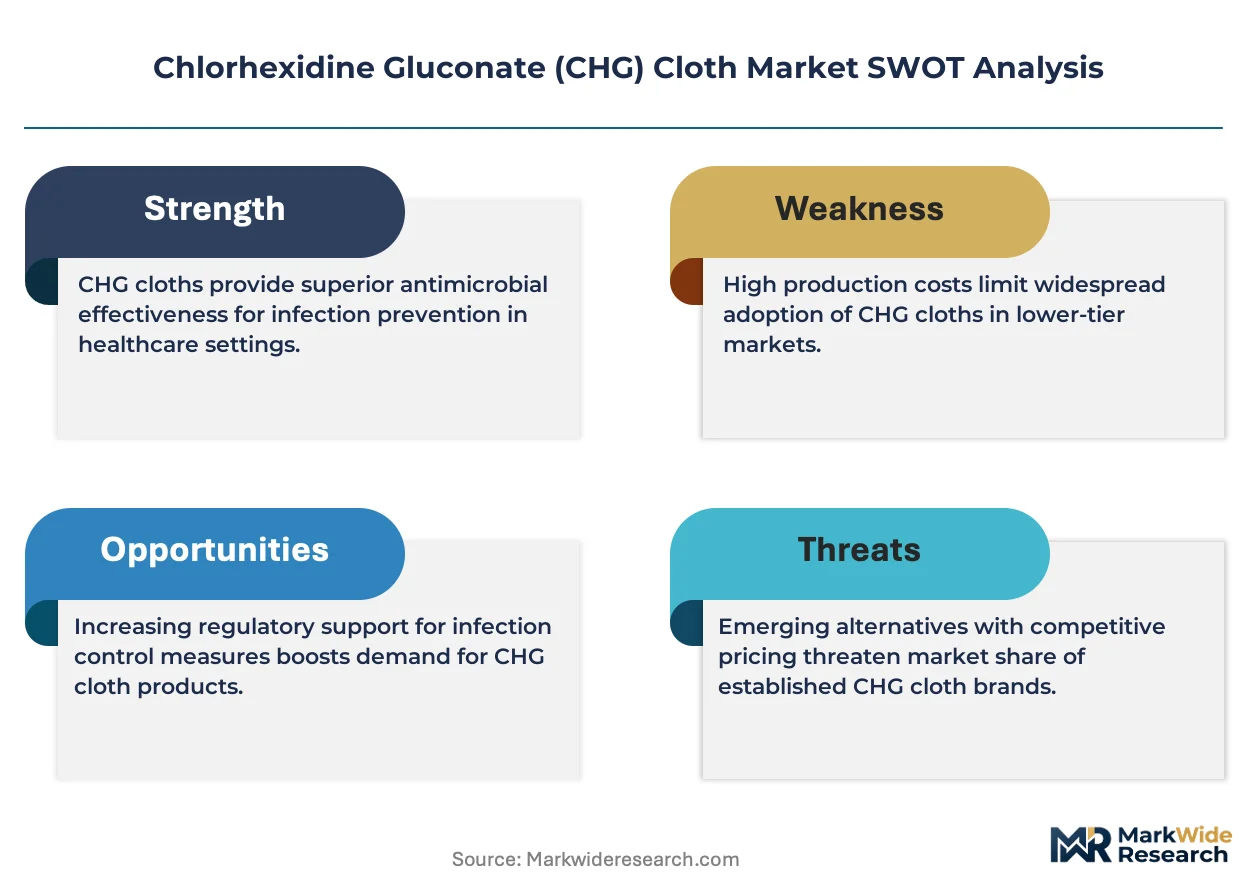
Sustained-release polymer matrices are compressing the performance gap between CHG cloths and conventional alcohol-based prep solutions, forcing manufacturers to differentiate through substrate engineering rather than active ingredient concentration alone. This technological inflection is redistributing margins across the value chain.
Growth Catalysts
- FDA preoperative antiseptic guidance:The agency's efficacy endpoint requirements are institutionalizing CHG cloths as standard-of-care in US surgical preparation protocols, creating compliance-driven procurement mandates.
- Full-body decolonization protocols:Hospital infection prevention committees are expanding CHG bathing from preoperative skin prep to daily patient hygiene, multiplying per-admission consumption volumes.
- Polymer matrix impregnation:Advanced substrate engineering extends antimicrobial persistence on skin surfaces, satisfying clinical demand for prolonged bacterial suppression without reapplication.
Market Restraints
- Isopropyl alcohol price volatility:CHG cloth manufacturing depends on alcohol-based carrier solutions, exposing margins to petrochemical feedstock fluctuations and energy cost spikes.
- EPA pesticide device registration:The dual FDA-EPA oversight framework in the United States creates parallel compliance burdens, extending commercialization timelines and legal review costs.
- Skin sensitivity limitations:Chlorhexidine gluconate contraindications in pediatric and dermatitis-prone populations restrict addressable patient demographics in neonatal and long-term care settings.
Strategic Opportunities
- Post-acute home health expansion:Discharge protocols extending infection prevention into residential settings create procurement channels outside traditional hospital supply chains.
- EU Medical Device Regulation harmonization:MDR conformity assessment streamlining enables single-certification access to 27 member state markets, reducing regulatory fragmentation costs.
- Patient gown integration:CHG-impregnated textiles embedded in disposable garments enable passive decolonization during wear, opening garment manufacturing partnerships.
Industry Challenges
- Antiseptic resistance surveillance gaps:Healthcare facilities lack standardized protocols for detecting reduced chlorhexidine susceptibility, complicating evidence-based formulary decisions.
- REACH chemical compliance complexity:ECHA substance evaluation processes for CHG concentration thresholds create formulation uncertainty across European manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorhexidine Gluconate (CHG) Cloth Market |
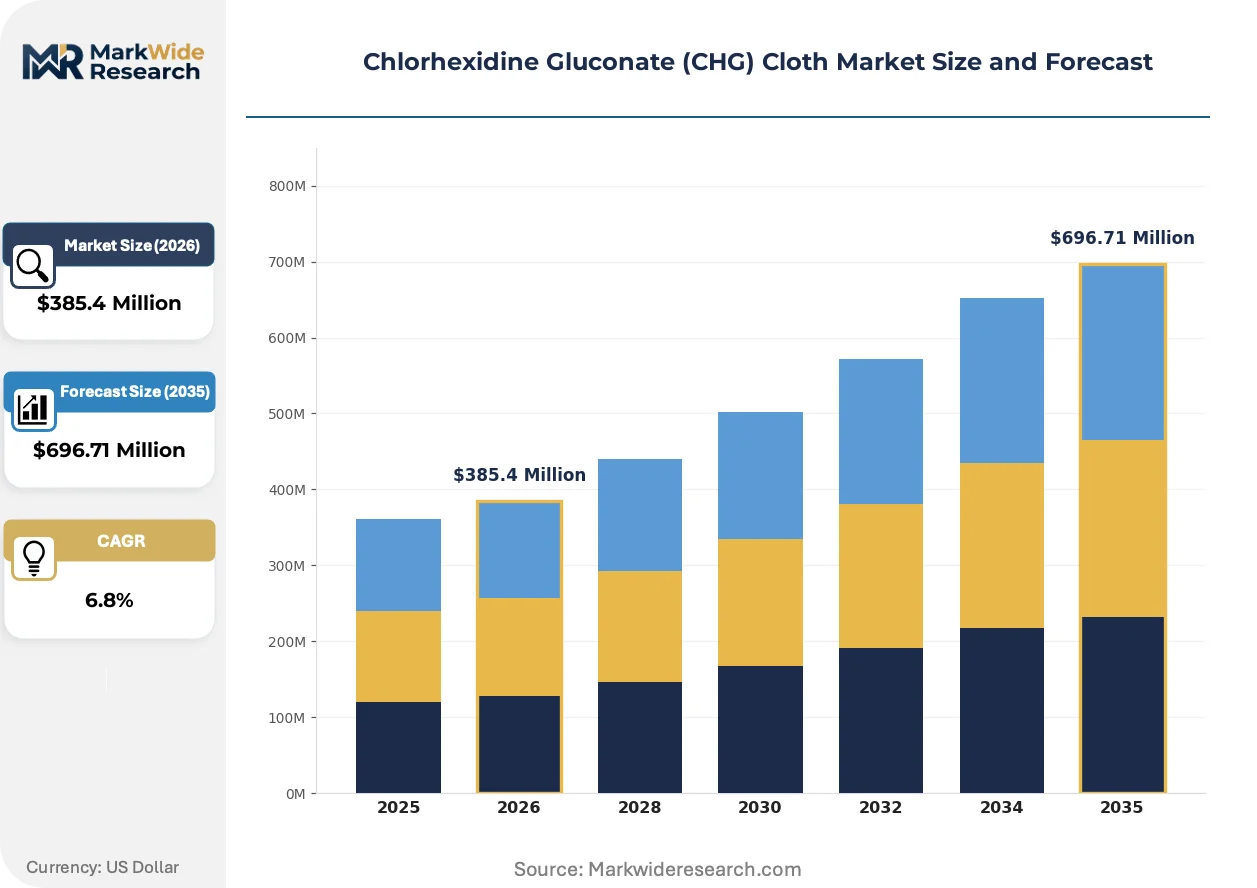
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-moistened Cloths, Patient Gowns, Surgical Drapes, Antiseptic Swabs Application: Infection Control, Surgical Preparation, Healthcare Facilities, Homecare End User: Hospitals, Clinics, Nursing Homes, Home Health Agencies Distribution Channel: Direct Sales, Retail Pharmacies, Online Platforms, Wholesalers |
| Companies Covered | Cardinal Health, GAMA Healthcare, Sage Products LLC, Stryker Corporation, Molnlycke Health Care, 3M Company, Medline Industries, Clinicept Healthcare, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorhexidine Gluconate (CHG) Cloth Market Strategic Shifts
Active ingredient delivery mechanisms are undergoing substrate-level reinvention as manufacturers compete on antimicrobial persistence rather than concentration alone. This shift is elevating materials science capabilities above traditional formulation expertise.
Microencapsulation technology is migrating from pharmaceutical transdermal patches to antiseptic textiles, enabling time-released CHG deposition across 24-hour wear periods. Surgical suites in academic medical centers are piloting these substrates for high-risk orthopedic procedures. The structural consequence is a compression of reapplication frequency, reducing nursing labor allocation to skin prep protocols.
REACH authorization requirements for residual CHG discharge are tightening effluent standards at European manufacturing facilities. ECHA's 2024 substance evaluation roadmap imposes additional analytical testing burdens on woven substrate producers. German and Dutch textile converters are responding by retrofitting finishing lines with closed-loop solvent recovery systems.
Bundled intervention procurement is consolidating vendor relationships as hospital systems seek single-source accountability for surgical site infection outcomes. Group purchasing organizations are displacing individual facility contracting for CHG cloth supply. This concentration is most visible in the United States, where ten health systems control approximately one-third of inpatient surgical volume.
Chlorhexidine Gluconate (CHG) Cloth Market Segmentation
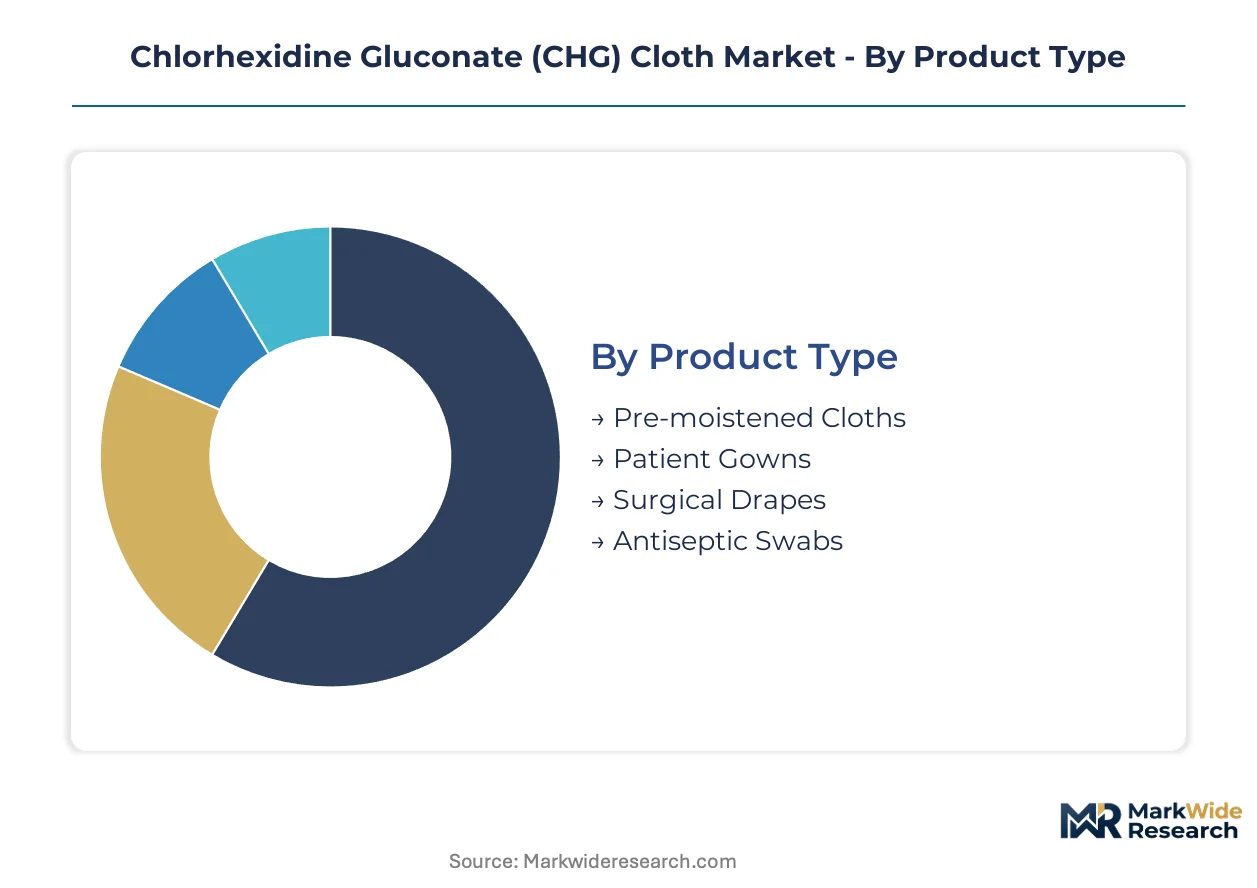
Segmentation in the CHG cloth market reveals how clinical workflows and procurement economics split demand across distinct technical formats and delivery channels. Understanding these divisions exposes where margin pools concentrate and which access routes are displacing traditional supply relationships.
Product Type:
Cost tier stratification across CHG-impregnated formats separates convenience-driven disposable systems from reusable garment integrations.
- Pre-moistened Cloths:Single-use woven or non-woven substrates saturated with 2% to 4% CHG solution in alcohol-based carriers, packaged in standardized counts for surgical prep kits. Hospital infection prevention committees in the United States specify these for compliance with FDA preoperative antiseptic guidance, driving formulary standardization.
- Patient Gowns:Disposable garments with CHG-impregnated textile panels enabling passive decolonization during extended wear. Academic medical centers pilot these for MRSA reduction in high-risk orthopedic admissions, with procurement expanding through group purchasing organization contracts.
- Surgical Drapes:Sterile barrier fabrics incorporating CHG-releasing layers for operative field maintenance.
- Antiseptic Swabs:Small-format applicators for targeted site preparation and device insertion protocols.
Pre-moistened cloths command the established base. The steepest expansion runs through patient gowns.
Application:
Clinical use case maturity spans from institutionalized surgical protocols to emerging post-acute extensions.
- Infection Control:Daily patient bathing protocols using CHG cloths to suppress healthcare-associated pathogen colonization, particularly in ICU and bone marrow transplant units. The United States leads implementation, with Joint Commission accreditation standards reinforcing routine decolonization.
- Surgical Preparation:Preoperative skin antisepsis replacing traditional aqueous scrubs in operating rooms. European surgical suites under EU Medical Device Regulation conformity requirements increasingly specify polymer-matrix substrates for extended antimicrobial persistence.
- Healthcare Facilities:Environmental and equipment disinfection applications extending beyond direct patient contact.
- Homecare:Discharge-based infection prevention programs extending CHG bathing into residential settings, with Medicare reimbursement shifts enabling home health agency procurement outside hospital supply chains.
Infection control applications anchor current volume. Surgical preparation is gaining share fastest as bundled intervention procurement consolidates vendor accountability.
End User:
Customer type concentration reflects institutional purchasing power versus fragmented post-acute access.
- Hospitals:Integrated delivery networks and academic medical centers with dedicated infection prevention committees and standardized formulary controls. These facilities negotiate multi-year supply agreements through group purchasing organizations, concentrating procurement leverage.
- Clinics:Ambulatory surgical centers and specialty procedure facilities with lower volume but higher compliance sensitivity to regulatory inspection.
- Nursing Homes:Long-term care facilities with rising pressure from CMS quality metrics on infection rates.
- Home Health Agencies:Post-acute providers extending CHG protocols into residential care, representing the most dispersed and logistically complex demand segment.
Hospitals retain procurement dominance. Home health agencies are climbing the fastest as discharge protocol redesigns push infection prevention beyond institutional walls.
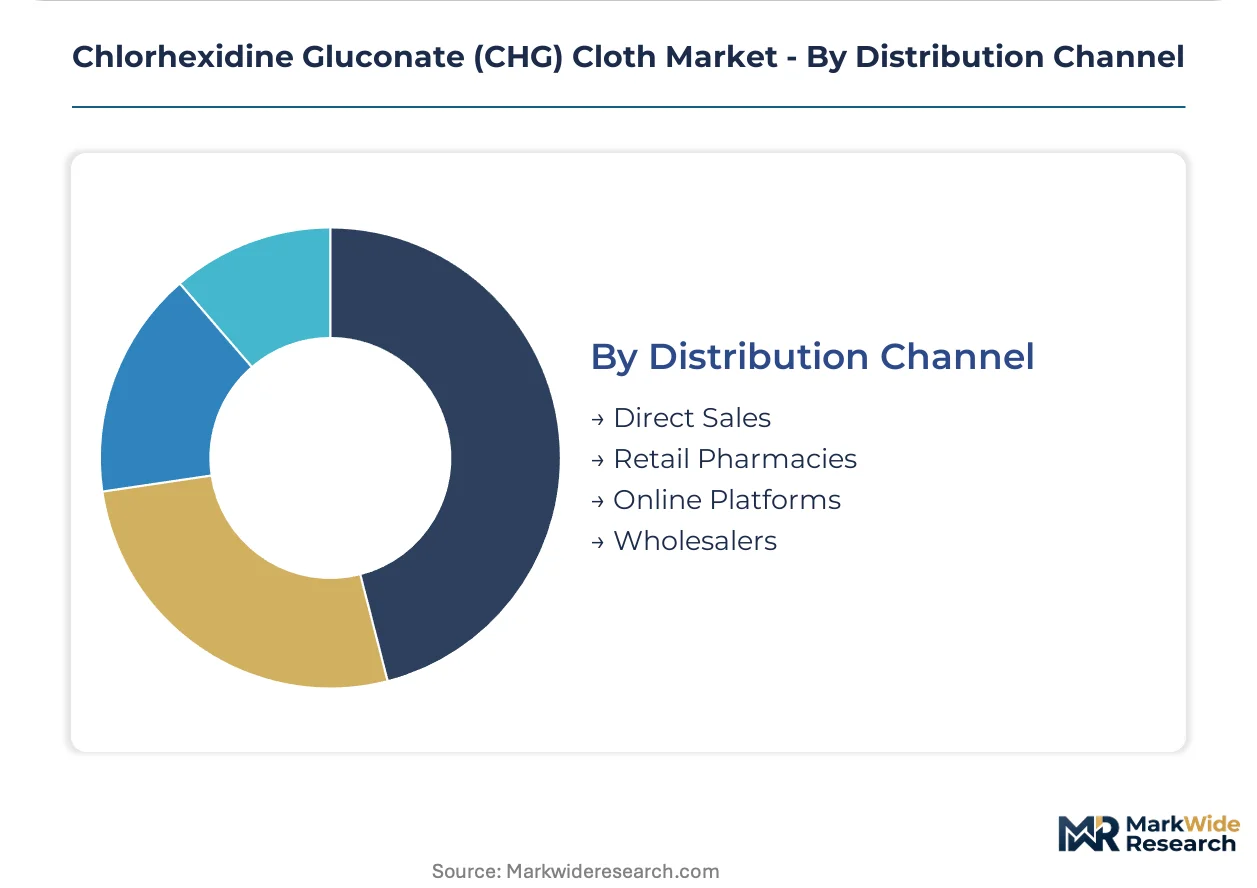
Distribution Channel:
Supply route configuration determines margin capture between manufacturers and end users.
- Direct Sales:Manufacturer contracting with health systems and group purchasing organizations, eliminating distributor markups and enabling outcome-based pricing tied to surgical site infection reduction metrics.
- Retail Pharmacies:Consumer-facing access for post-discharge patient self-purchase, limited by prescription requirements and insurance coverage gaps.
- Online Platforms:E-procurement portals and medical supply marketplaces gaining traction among smaller clinics and home health agencies seeking price transparency.
- Wholesalers:Traditional medical-surgical distributors maintaining inventory positions for emergency and spot purchasing, though their role is compressing under direct contracting pressure.
Direct sales channels control the established volume base. Online platforms are expanding most quickly as smaller end users seek procurement flexibility outside GPO frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement power concentrates in the United States, where ambulatory surgical centers and integrated delivery networks drive CHG cloth volume. European surgical suites under EU Medical Device Regulation conformity requirements increasingly specify polymer-matrix substrates. Asia-Pacific infection prevention programs are expanding as healthcare infrastructure modernizes.
United States
FDA preoperative antiseptic guidance institutionalizes CHG cloths as standard-of-care in surgical preparation protocols, creating compliance-driven procurement mandates. The dual FDA-EPA oversight framework imposes parallel registration burdens on manufacturers. Chicago-area medical supply distributors maintain inventory positions for emergency hospital purchasing.
Germany
EU Medical Device Regulation harmonization enables single-certification access to member state markets for CHG-impregnated textiles. ECHA REACH authorization requirements tighten effluent standards at manufacturing facilities. Bavarian textile converters retrofit finishing lines with closed-loop solvent recovery systems to meet discharge compliance.
United Kingdom
NHS infection prevention committees expand CHG bathing from preoperative skin prep to daily patient hygiene protocols. The Medicines and Healthcare products Regulatory Agency enforces medical device conformity assessment procedures. London-based academic medical centers pilot microencapsulation technology for high-risk orthopedic procedures.
Japan
PMDA medical device regulations govern CHG cloth commercialization with efficacy endpoint requirements aligned to international standards. METI industrial policy supports domestic textile innovation in antimicrobial substrates. Osaka-area surgical suites adopt polymer-matrix CHG cloths for extended antimicrobial persistence in cardiac procedures.
Australia
TGA medical device regulations oversee CHG cloth registration with emphasis on surgical site infection reduction claims. National Health and Medical Research Council guidelines reinforce preoperative antisepsis protocols. Melbourne hospital systems consolidate procurement through group purchasing organization frameworks.
Chlorhexidine Gluconate (CHG) Cloth Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement leverage versus formulation differentiation axes. The market structure reflects moderate consolidation, with distribution scale operators and Nordic hygiene heritage brands occupying distinct competitive positions. Three archetypes dominate: direct-contracting hospital suppliers, polymer-matrix technology specialists, and diversified medical device conglomerates. M&A activity targets regional antiseptic textile capabilities, while strategic partnerships embed CHG substrates into disposable garment manufacturing.
Among diversified medical device conglomerates, 3M Company and Stryker Corporation exemplify scale-driven positioning through integrated hospital supply relationships. BD occupies a position within the antiseptic delivery technology tier, anchoring R&D intensity across multiple formats. Molnlycke Health Care represents the Nordic hygiene heritage archetype, sitting within premium surgical suite positioning in European markets.
| Leading Market Players |
|---|
| Cardinal Health |
| GAMA Healthcare |
| Sage Products LLC |
| Stryker Corporation |
| Molnlycke Health Care |
| 3M Company |
| Medline Industries |
| Clinicept Healthcare |
| BD |
| Others |
Value Chain & Pricing Dynamics
Isopropyl alcohol feedstock concentration in Texas and Louisiana petrochemical corridors anchors margin distribution across CHG cloth value chains, with polymer matrix substrate engineering now capturing downstream premium pools previously held by formulation specialists.
Pricing Analysis
Cost-plus contracts indexed to isopropyl alcohol spot markets dominate procurement between manufacturers and hospital group purchasing organizations. Three-tier pricing structure across premium polymer-matrix, standard pre-moistened, and economy bulk formats separates clinical performance tiers. Pricing pressure stems from alcohol carrier cost volatility rather than CHG active ingredient competition. Ambulatory surgical centers exhibit highest price sensitivity due to case-volume variability, while academic medical centers prioritize antimicrobial persistence metrics over per-unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for woven substrate converters. Manufacturing concentrates in Germany, United States, and China for non-woven impregnation lines. Raw material dependencies center on isopropyl alcohol carriers, medical-grade polyester substrates, and CHG active pharmaceutical ingredients. Distribution runs through direct hospital system contracting and group purchasing organization frameworks, compressing traditional medical-surgical distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CHG cloth procurement is shifting toward platform-economics bundling as hospital systems demand single-vendor accountability for surgical site infection outcomes, with interoperability between CHG protocols and electronic health record systems emerging as the decisive ecosystem battleground.
For Market Incumbents: Insulate formulary position by deepening captive production of polymer matrix substrates and securing multi-year GPO contracts with outcome-based pricing tied to infection reduction metrics. The threat of microencapsulation technology specialists displacing traditional impregnation methods demands accelerated R&D allocation to sustained-release substrate engineering. For New Entrants and Emerging Players: Post-acute home health agencies in Medicare Advantage networks represent the most penetrable entry point for CHG cloth market entry, with daily patient gown protocols for MRSA decolonization offering volume expansion outside hospital supply chain concentration. A direct-to-agency e-procurement platform bypassing GPO intermediaries provides the optimal go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed surgical textile converters possessing EU Medical Device Regulation certification but lacking US FDA-EPA dual registration capabilities. The five-to-ten year viability window favors targets with polymer matrix IP portfolios over commodity impregnation specialists. Watch for bundled intervention procurement mandates from Joint Commission accreditation standards as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Matrix Substrate Development | Enables 24-hour antimicrobial persistence for high-risk orthopedic procedures at academic medical centers. |
| FDA-EPA Dual Registration Pathway | Unlocks US commercialization for European manufacturers seeking hospital system procurement access. |
| Hospital System Partnership | Secures multi-year formulary standardization through infection prevention committee influence. |
| Patient Gown Manufacturing Integration | Captures fastest-growing segment via passive decolonization garment partnerships with disposable apparel producers. |
| Reimbursement Strategy Alignment | Positions CHG bathing protocols for Medicare Advantage post-acute coverage expansion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with infection prevention committee chairs, hospital procurement managers, GPO contracts specialists, and biomedical engineers at integrated delivery networks. Secondary validation drew from FDA premarket notification databases, EPA pesticide device registrations, CMS Medicare reimbursement filings, and EU Medical Device Regulation conformity assessment records. Bottom-up volume modeling triangulated against top-down market sizing across pre-moistened cloth, patient gown, and surgical drape product categories.
Calibration against historical CHG cloth consumption patterns at ten US health systems controlling substantial inpatient surgical volume informed projection assumptions across the analysis window. Segmentation modeling incorporated product type, application workflow, end-user facility tier, and distribution channel structure. CAGRs were derived from surgical procedure volume growth, decolonization protocol penetration rates, and per-admission consumption intensity trends.
Practitioners should monitor antiseptic resistance surveillance data and regulatory reclassification proposals for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market