
 Micellar Cleansing Water Market | 2026-2036
Micellar Cleansing Water Market Size, Share, and Industry Trends Forecast 2026-2036
Micellar Cleansing Water Market Analysis
Subscription-based replenishment programs for personal care routines is realigning how micellar cleansing water reaches repeat buyers. L'Oréal S.A. leverages its pharmacy-channel dominance across Western Europe to sustain loyalty through auto-delivery partnerships. Bioderma Laboratories anchors its dermatological credibility with healthcare professional endorsements. Unilever competes via mass-market retail density and private-label adjacencies in emerging markets.
Micellar cleansing water is a surfactant-based suspension where amphiphilic micelle clusters, typically below 100 nanometers, entrap lipophilic debris and particulate matter without disrupting skin barrier function; formulations often incorporate poloxamers or mild non-ionic surfactants at concentrations between 5% and 15% to achieve iso-osmolarity with epidermal tissue. The product serves consumers seeking rinse-free cleansing alternatives that reduce mechanical irritation compared with traditional foaming agents. All-in-One variants lead volume shipments by consolidating makeup removal and daily cleansing steps into single SKUs, while Oil-Infused formats capture expanding margin pools as consumers with long-wear cosmetic habits trade up. Hydrating sub-segments target working professionals in arid climates where barrier-support claims command shelf-space premiums.
Regulators including the FDA, EMA through its Cosmetic Products Regulation framework, and BIS in India enforce varying thresholds on surfactant classifications, preservative restrictions, and label claims that dictate formulation costs and market entry timelines. REACH compliance in Europe and state-level cosmetic safety statutes in California shape ingredient substitution patterns and reformulation cycles. Stakeholders must monitor evolving restrictions on per- and polyfluoroalkyl substances and fragrance allergen disclosures as these frameworks tighten disclosure requirements and testing burdens.
Market Dynamics
Formulation science is redirecting micellar cleansing water development toward microbiome-compatible surfactant systems that preserve skin barrier integrity while maintaining cleansing efficacy.
Growth Catalysts
- REACH compliance evolution:European surfactant substitution mandates are accelerating biodegradable non-ionic surfactant adoption, creating first-mover advantages for compliant formulators.
- Working professional routines:Post-pandemic hybrid work schedules have normalized midday refresh cleansing, expanding usage occasions beyond traditional morning-evening patterns.
- Amphiphilic micelle engineering:Sub-100 nanometer cluster optimization is automating debris entrapment efficiency, reducing required surfactant concentrations without performance trade-offs.
Market Restraints
- Poloxamer supply concentration:Pharmaceutical-grade poloxamer production clusters in Germany and China, exposing formulators to cross-border logistics disruptions and input cost volatility.
- Preservative restriction tightening:ANSM fragrance allergen disclosure requirements and EMA paraben scrutiny are forcing reformulation cycles that compress margin structures.
- Tap water quality substitution:Regions with high-quality municipal water infrastructure see reduced rinse-free product necessity, limiting category penetration in Nordic markets.
Strategic Opportunities
- Men's grooming underpenetration:Male skincare adoption in India and Brazil remains below category averages, presenting white-space for gender-neutral positioning.
- Healthcare channel integration:Post-procedure cleansing protocols in dermatology and cosmetic surgery practices create professional endorsement pathways.
- Refill station infrastructure:Retail circular economy mandates in France and Italy are incentivizing bulk dispensing formats that reduce packaging cost ratios.
Industry Challenges
- Cosmetic chemist talent scarcity:Specialized expertise in iso-osmolar formulation design remains concentrated among legacy French and Swiss laboratories, constraining R&D expansion.
- Multi-jurisdiction labeling complexity:Simultaneous FDA cosmetic labeling rules, EMA allergen disclosure frameworks, and BIS surfactant classifications create compliance timeline bottlenecks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micellar Cleansing Water Market |
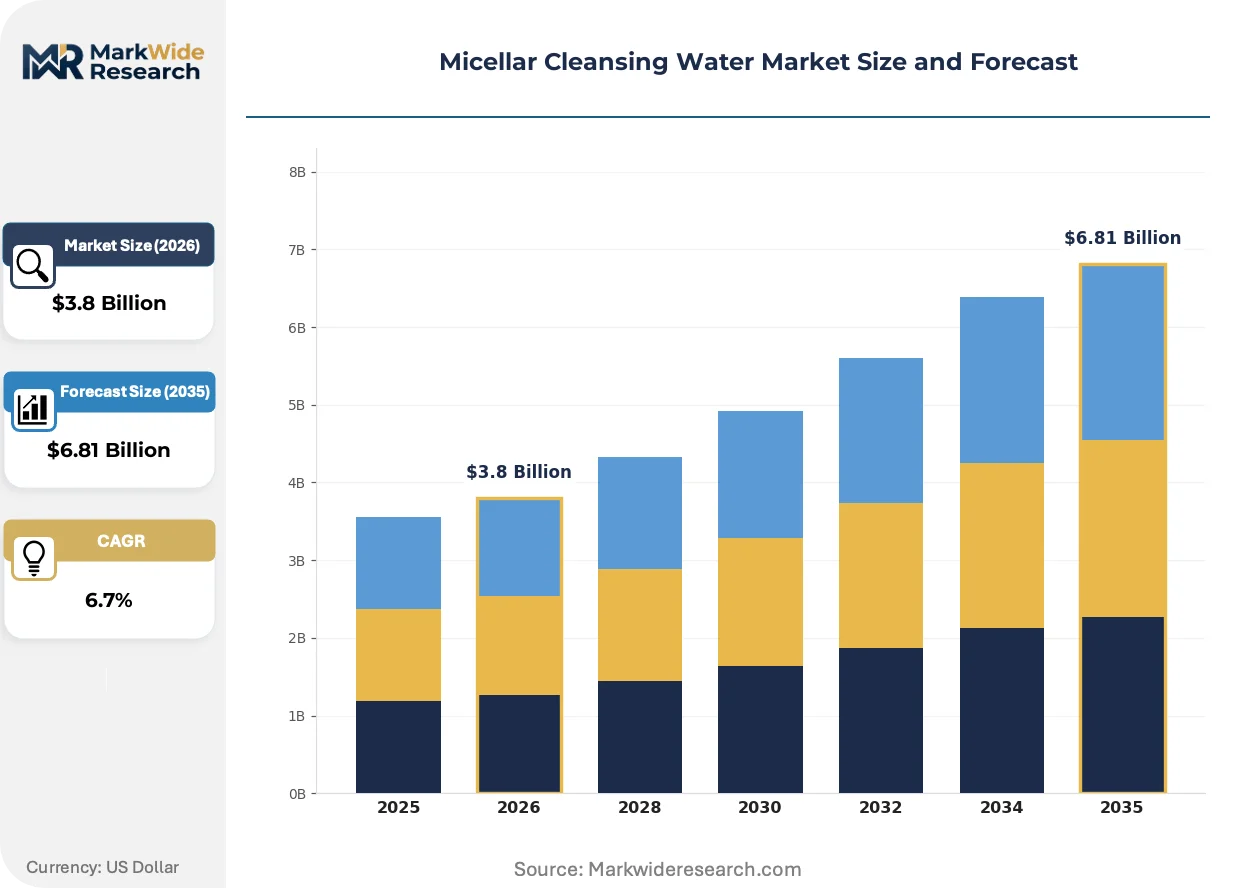
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-in-One, Hydrating, Oil-Infused, Extra-Gentle Application: Makeup Removal, Daily Cleansing, Sensitive Skin, Normal Skin Packaging Type: Pump Bottle, Travel Size, Refillable, Sachets End User: Millennials, Gen Z, Working Professionals, Beauty Enthusiasts |
| Companies Covered | Johnson & Johnson, Kao Corporation, L'Oréal S.A., NAOS, Beiersdorf, Unilever, Shiseido Company, Limited, Bioderma Laboratories, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micellar Cleansing Water Market Emerging Trajectories
Biotechnology-derived surfactants and AI-assisted formulation modeling are compressing development timelines while raising performance benchmarks across cleansing efficacy and skin compatibility metrics.
Encapsulated micelle technology is automating targeted delivery of active ingredients during the cleansing process. Prestige skincare laboratories in France and Switzerland are adopting these systems to differentiate premium tier offerings. The technology is automating the separation of cleansing from treatment functions, enabling multi-step benefit consolidation that reshapes SKU architecture.
EMA's Cosmetic Products Regulation framework is tightening preservative restriction thresholds and mandating expanded fragrance allergen labeling. Formulators serving European pharmacy channels face accelerated stability testing requirements and documentation burdens. Mass-market brands are responding with simplified ingredient lists and "free-from" positioning strategies that trade formulation complexity for regulatory certainty.
Subscription-based replenishment programs are displacing traditional retail replenishment cycles among urban working professionals. Direct-to-consumer platforms and pharmacy auto-delivery partnerships capture higher lifetime value through reduced churn. This behavioral shift concentrates most visibly in France and Germany, where pharmacy channel loyalty programs have normalized automated reordering for core skincare staples.
Micellar Cleansing Water Market Segmentation
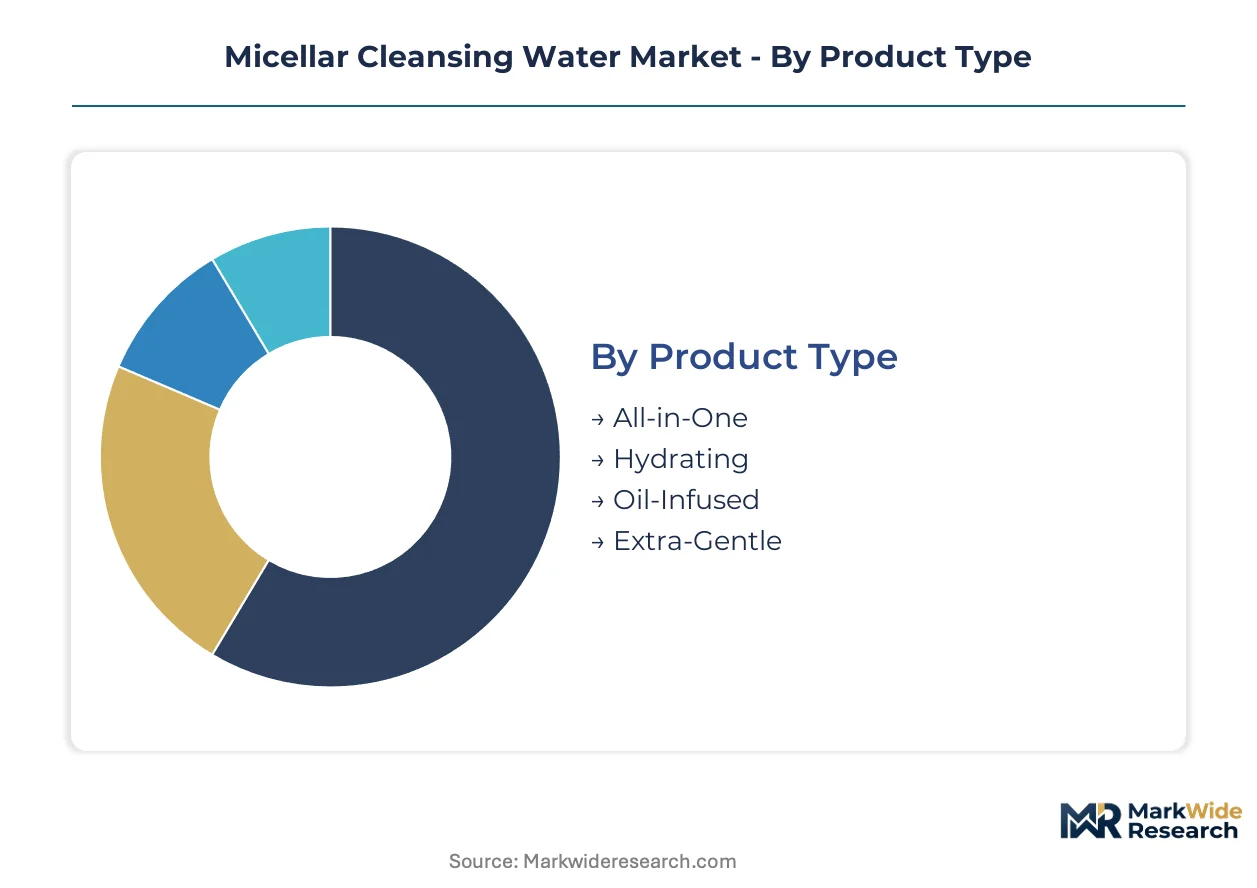
Micellar cleansing water segmentation reflects divergent formulation strategies and channel economics. Product architecture separates mass-market accessibility from dermatological premium positioning, while packaging innovation responds to circular economy mandates and professional mobility patterns.
Product Type:
Supply concentration among French and Swiss laboratories favors variants with complex surfactant engineering and stability testing infrastructure.
- All-in-One:Combines makeup dissolution, surface cleansing, and light hydration through balanced amphiphilic micelle clusters at 8-12% surfactant concentration. Working professionals in urban France and Germany drive repeat purchase frequency through pharmacy auto-delivery programs. This format absorbs the bulk of installed capacity; Oil-Infused is expanding most quickly.
- Oil-Infused:Biphasic systems incorporate lightweight emollients—typically squalane or jojoba esters at 5-10%—to dissolve long-wear and waterproof cosmetics without mechanical rubbing. Beauty enthusiasts in arid climates trade up for barrier-support claims that justify shelf-space premiums.
- Hydrating:Glycerin and hyaluronic acid fortification targets post-cleansing tightness in consumers with compromised barriers; formulations prioritize iso-osmolarity with epidermal tissue.
- Extra-Gentle:Minimalist surfactant loads below 5% and preservative-free positioning serve post-procedure and pediatric segments; ANSM disclosure requirements constrain fragrance options.
Cost tier separation between pharmacy-channel premium and mass-market standard lines determines margin structure and R&D amortization schedules.
Application:
Volume concentration tracks demographic cohorts with expanded skincare step counts and professional appearance requirements.
- Daily Cleansing:Rinse-free convenience anchors morning and evening routines for consumers seeking barrier-preserving alternatives to foaming agents. Working professionals in hybrid work arrangements have normalized midday refresh usage, expanding occasion frequency beyond traditional patterns. This segment absorbs the bulk of installed capacity; Sensitive Skin is climbing the fastest.
- Makeup Removal:Lipophilic micelle entrapment of pigments and film-formers requires higher surfactant payloads; demand concentrates among beauty enthusiasts with multi-step cosmetic routines.
- Sensitive Skin:Formulations exclude fragrance allergens and maintain pH 5.0-5.5 compatibility; EMA disclosure frameworks and dermatologist endorsement protocols shape competitive positioning.
- Normal Skin:Standard surfactant concentrations serve price-sensitive segments through mass-market retail density and private-label adjacencies.
Customer type fragmentation across professional, enthusiast, and minimalist segments requires distinct channel and messaging strategies.
Packaging Type:
Margin structure varies with material cost exposure and circular economy compliance requirements across European markets.
- Pump Bottle:Controlled dispensing reduces product waste and supports premium positioning through tactile engineering; standard sizes range 400-500ml for residential vanity placement.
- Refillable:Bulk dispensing formats respond to French and Italian retail circular economy mandates; packaging cost ratios compress through concentrated refill economics.
- Travel Size:TSA-compliant volumes below 100ml capture professional mobility and trial conversion; sachet alternatives compete on unit economics.
- Sachets:Single-use pouches dominate sample distribution and emerging market entry pricing; environmental scrutiny constrains growth in regulated European markets.
Volume leadership resides in pump formats; refillable systems are gaining share fastest as regulatory pressure intensifies.
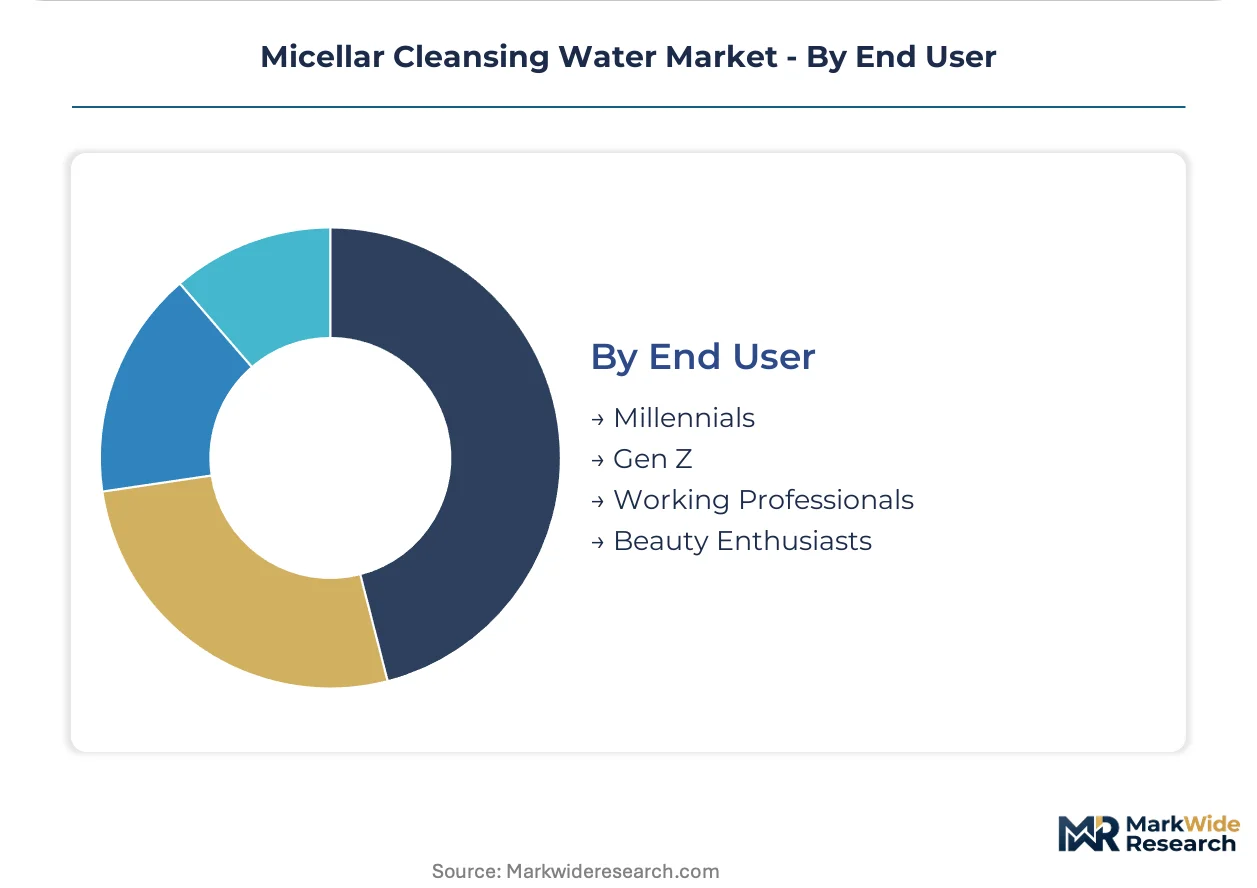
End User:
Generational cohort behavior determines channel preference and ingredient sophistication tolerance.
- Working Professionals:Time-compressed routines favor consolidated cleansing steps and subscription replenishment; hybrid work schedules have normalized midday usage occasions.
- Beauty Enthusiasts:Ingredient literacy and routine layering drive trade-up to Oil-Infused and encapsulated micelle technologies; social platform engagement accelerates trial.
- Millennials:Pharmacy channel loyalty and dermatological endorsement sensitivity support premium tier pricing; auto-delivery partnerships capture lifetime value.
- Gen Z:Sustainability credential scrutiny and TikTok-driven discovery patterns favor transparent supply chains and minimalist ingredient lists; refill station adoption concentrates in this cohort.
Working Professionals absorb the bulk of volume throughput; Gen Z is expanding most quickly as skincare initiation age declines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates production expertise for micellar technology, while consumption spreads across developed and emerging markets with varying channel preferences. Manufacturing clusters in Western Europe supply global demand through pharmacy and mass-market channels. Regulatory divergence shapes regional entry strategies and formulation adaptation requirements.
France
Pharmacy channel loyalty and dermatological endorsement protocols sustain premium pricing power in the category's birthplace. ANSM fragrance allergen disclosure requirements and EMA Cosmetic Products Regulation compliance shape local formulation standards. Paris-based laboratories concentrate encapsulated micelle engineering capabilities, with Île-de-France hosting the majority of specialized surfactant R&D infrastructure.
Germany
Auto-delivery partnerships through pharmacy networks capture repeat purchase frequency among working professionals. REACH compliance evolution mandates biodegradable surfactant substitution, accelerating reformulation investments. North Rhine-Westphalia clusters pharmaceutical-grade poloxamer production, exposing formulators to cross-border logistics dependencies.
United States
Mass-market retail density and subscription platform adoption expand usage among time-compressed urban consumers. FDA cosmetic labeling rules and state-level California safety statutes dictate disclosure thresholds and testing burdens. Northeast corridor distribution centers service pharmacy chain replenishment programs.
India
Rising male skincare initiation and sachet-format affordability drive volume expansion in underpenetrated segments. BIS surfactant classifications and preservative restrictions govern import compliance and local manufacturing standards. Maharashtra and Gujarat host contract manufacturing facilities serving domestic mass-market distribution.
Brazil
Beauty enthusiast engagement through social platforms accelerates trial conversion for Oil-Infused variants. ANVISA cosmetic registration timelines and ingredient approval protocols constrain new product launch cadences. São Paulo anchors regional marketing investment and pharmacy channel development.
Micellar Cleansing Water Market Vendor Landscape
Top-tier vendors anchor pharmacy-channel premium positioning, while mass-market specialists compete through retail density and private-label adjacencies. The vendor base separates into dermatological credibility builders, scale-driven consumer goods conglomerates, and regional pharmacy channel operators. Three strategic archetypes dominate: legacy French laboratories with formulation heritage, multinational FMCG players with distribution leverage, and Asia-Pacific beauty specialists with regional brand equity. Competitive moves concentrate on auto-delivery partnership formation and refill station infrastructure deployment.
Within the dermatological credibility tier, Bioderma Laboratories and L'Oréal S.A. exemplify pharmacy-channel anchoring strategies. Unilever occupies a position representing mass-market scale advantages and emerging market penetration capabilities. These three entities illustrate the competitive spectrum from specialized formulation heritage to diversified consumer goods scale.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Kao Corporation |
| L'Oréal S.A. |
| NAOS |
| Beiersdorf |
| Unilever |
| Shiseido Company, Limited |
| Bioderma Laboratories |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
Pharmacy-channel working professionals in France and Germany anchor subscription-based replenishment economics, concentrating purchasing power around auto-delivery partnerships that compress traditional retail markup structures while sustaining premium tier access.
Pricing Analysis
Margin tightening in pharmacy-channel premium tiers reflects REACH-driven surfactant substitution costs and accelerated stability testing burdens. Three-tier pricing structure across pharmacy premium, mass-market standard, and sachet economy levels separates dermatological endorsement value from retail density scale. Price differentiation hinges on certification grade (ANSM compliance tier) and geographic delivery cost (cross-border pharmacy logistics). Cost-down pressure on mass-market tiers accelerates because private-label adjacencies in emerging markets force brand owners to absorb reformulation expenses without price recovery mechanisms. Sachet-format buyers in India and Brazil exhibit highest price sensitivity; encapsulated micelle technology adopters in Switzerland show lowest.
Supply Chain Analysis
Regional distribution centers in Île-de-France and North Rhine-Westphalia operate hub-and-spoke patterns serving pharmacy networks across Western Europe. Manufacturing concentration clusters in France, Germany, and Switzerland draws from pharmaceutical-grade poloxamer feedstock and biotechnology-derived surfactant inputs. Single-source vulnerability sits with German and Chinese poloxamer production clusters exposed to cross-border logistics disruptions. Distribution runs through pharmacy wholesale cooperatives in France and mass-market retail consolidators in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cosmetic chemist talent scarcity in iso-osmolar formulation design props pricing for legacy laboratory capabilities, constraining capacity expansion and sustaining incumbent margin structures.
For Market Incumbents: Cement pharmacy-channel loyalty through exclusive auto-delivery partnerships that lock in working professional replenishment frequency. Defend against biotechnology-derived surfactant disruptors by acquiring captive R&D capacity in encapsulated micelle engineering. Prioritize backward integration into pharmaceutical-grade poloxamer supply through long-term offtake agreements with North Rhine-Westphalia producers. For New Entrants and Emerging Players: Begin with men's grooming white-space in India and Brazil where category penetration trails female-skewed benchmarks by substantial margins. Target sachet-format affordability tiers in Maharashtra and Gujarat contract manufacturing corridors. Pursue healthcare channel integration through dermatology post-procedure cleansing protocol endorsements as credibility-building pathway. For Investors and Strategic Acquirers: The window for entry favors mid-cap laboratories with encapsulated micelle patents and established ANSM compliance documentation. Long-term viability rests on biotechnology surfactant pipelines and refill station infrastructure deployment rights. Monitor EMA fragrance allergen disclosure threshold tightening as signal for accelerated consolidation among undercapitalized formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Surfactant Pipeline Investment | REACH compliance evolution in Europe mandates biodegradable substitution, rewarding first-mover laboratories with formulation cost advantages. |
| Pharmacy Auto-Delivery Partnership Formation | L'Oréal S.A. and Bioderma Laboratories anchor loyalty programs in France and Germany that capture higher lifetime value through reduced churn. |
| Refill Station Infrastructure Deployment | French and Italian retail circular economy mandates incentivize bulk dispensing formats that compress packaging cost ratios for Gen Z adopters. |
| Healthcare Channel Professional Endorsement | Post-procedure cleansing protocols in dermatology practices create credibility pathways that differentiate from mass-market retail positioning. |
| Encapsulated Micelle Technology Licensing | Prestige skincare laboratories in Paris and Geneva adopt targeted delivery systems that separate cleansing from treatment functions. |
Methodological Framework
Independent corroboration across formulation chemists at legacy French laboratories, pharmacy channel procurement managers in Germany, and mass-market retail category buyers in India underwrites the qualitative findings. Primary interviews with cosmetic R&D directors, dermatology clinic purchasing committees, and contract manufacturing facility managers in Maharashtra and Gujarat supplied forward-looking capacity and pricing intelligence. Secondary validation drew from ANSM regulatory filings, EMA Cosmetic Products Regulation documentation, BIS surfactant classification standards, and customs records tracking poloxamer import flows. Bottom-up segmentation modeling triangulated against top-down category expenditure estimates from pharmacy cooperative financial disclosures.
Historical reference periods spanning pre-pandemic, pandemic disruption, and hybrid work normalization phases anchored the forecast window across the analysis window. The analytical framework modeled product type segmentation (All-in-One, Oil-Infused, Hydrating, Extra-Gentle), packaging format economics, and end-user generational cohort behavior. CAGRs derived from segment-level growth rate reconciliation against macroeconomic skincare expenditure elasticity coefficients. Forecast inputs incorporated REACH surfactant substitution timelines and refill station regulatory adoption curves in France and Italy.
Underlying measurement precision varies by segment; pharmacy-channel premium tiers carry tighter precision than sachet-format emerging market volumes due to data availability disparities. Forecasts reflect documented assumptions on regulatory compliance cost trajectories and biotechnology surfactant adoption velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market