
 Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market | 2026-2036
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market Insights
Industrial-grade concentrate specifications is collapsing the gap between economy and premium tiers in autonomous machine formulations. Ecolab leverages its captive institutional channel to sustain recurring chemical revenue tied to machine placements. Tennant Company anchors its aftermarket strategy through proprietary detergent dispensing systems integrated with its autonomous fleet.
Autonomous floor cleaning machine detergent and care chemicals comprise concentrated surfactant blends, typically formulated at pH ranges from 2 to 13 depending on substrate compatibility, designed for automated dilution and dispensing in robotic scrubbers and sweepers. These formulations incorporate chelating agents, low-foam surfactants, and corrosion inhibitors to prevent damage to machine sensors, brushes, and recovery tanks while maintaining cleaning efficacy on concrete, vinyl, and epoxy surfaces. Enzyme-based solutions occupy the fastest-expanding product tier as facilities managers prioritize residue-free floors that reduce slip hazards in commercial spaces. Cartridge packaging dominates in institutional buildings where standardized dosing prevents operator error, while bulk containers sustain margin pools in warehousing centers with high throughput and centralized chemical rooms.
EPA Safer Choice standards and the EU REACH framework restrict volatile organic compound content and phosphonate discharge limits, forcing reformulation of legacy alkaline detergents toward biodegradable alternatives. FDA oversight of food processing environments and ECHA classification of surfactant hazards further segment compliance requirements between institutional and industrial end users. Stakeholders must monitor how dual carbon mandates in China and extended producer responsibility schemes in Europe reshape raw material sourcing and packaging take-back obligations.
Market Dynamics
EPA Safer Choice certification and the EU REACH framework are forcing surfactant manufacturers to abandon phosphonate-based legacy formulations, compressing R&D timelines while opening margin pools for biodegradable alternatives that protect robotic sensor arrays from corrosive residue.
Growth Catalysts
- Healthcare infection control mandates:Hospital-acquired infection reduction protocols in North American acute care facilities are expanding autonomous cleaning fleet deployments, creating pull-through demand for pH-neutral enzymatic detergents compatible with epoxy flooring.
- REACH phosphonate discharge limits:The EU's tightened restrictions on aquatic toxicity are accelerating reformulation investments toward chelating agent alternatives that maintain scale inhibition in hard water regions without environmental persistence.
- Industrial automation in German facility management:Centralized chemical rooms in Bavarian and North Rhine-Westphalian logistics hubs are standardizing cartridge-based dosing systems that eliminate operator dilution error.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and linear alkylbenzene price swings compress margin stability for concentrated surfactant producers serving warehousing customers with annual contract locks.
- Single-source sensor compatibility risk:Proprietary detergent dispensing architectures from dominant autonomous machine OEMs create technical lock-in that limits third-party chemical supplier switching.
- Legacy alkaline detergent stranded assets:Facilities managers with existing bulk caustic inventory face write-down pressure when migrating to pH-neutral enzymatic systems required for robotic brush longevity.
Strategic Opportunities
- Underpenetrated Japanese aged-care facilities:METI facility automation subsidies and labor shortage demographics in Tokyo and Osaka prefectures create first-mover openings for enzymatic residue-free formulations that reduce slip litigation exposure.
- Food processing FDA compliance tier:Sanitizer-detergent hybrid chemistries with EPA registration and FDA food contact notification are capturing share in protein processing plants where autonomous machines must execute wet cleaning without rinse cycles.
- IoT-enabled consumption tracking:Chemical-as-a-service models leveraging machine telemetry data are displacing volume-based procurement in multi-site retail chains seeking usage visibility across distributed autonomous fleets.
Industry Challenges
- Reformulation chemist scarcity:The specialized expertise required to balance low-foam surfactant performance with sensor-safe corrosion inhibition is concentrating in German and Dutch technical centers, creating recruitment bottlenecks for Asian manufacturers.
- Dual certification timeline compression:Simultaneous EPA Safer Choice and EU ECHA hazard classification approvals demand parallel toxicology studies that extend product launch windows by 18-24 months.
- Legacy dilution system retrofit costs:Facilities with installed central chemical mixing stations face capital expenditure barriers when integrating autonomous machines requiring sealed cartridge architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market |
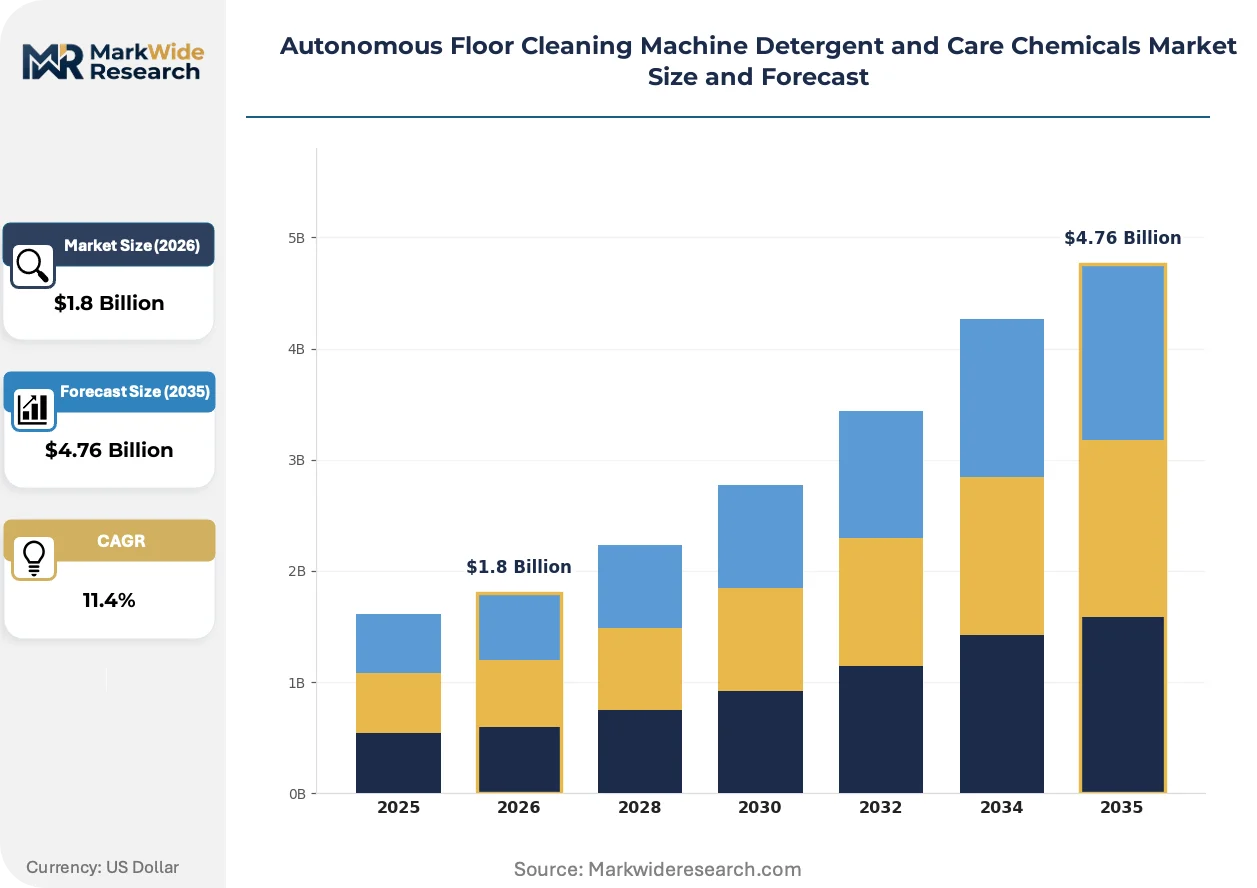
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Detergents, Neutral Cleaners, Acidic Cleaners, Enzyme-Based Solutions, Foam Cleaners Application: Commercial Spaces, Manufacturing Facilities, Educational Institutions, Hospitality Venues, Transport Hubs End User Industry: Institutional Buildings, Warehousing Centers, Event Management, Food Processing Units, Recreational Centers Packaging Type: Cartridges, Refill Packs, Bulk Containers, Spray Bottles, Sachets |
| Companies Covered | Alfred Kärcher, Nilfisk, Tennant Company, Hako Group, Taski, Dyson, Ecolab, Diversey, SC Johnson Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market Trends and Innovations
Formulation chemistry is diverging along two paths: residue-free enzymatic systems for slip-sensitive commercial spaces and heavy-duty alkaline concentrates for industrial soils, with packaging and dosing architectures adapting to each trajectory.
Enzymatic detergent technology is bifurcating the market between premium biological formulations and commodity surfactant blends. Healthcare and aged-care facilities in Germany and Japan are adopting protease-lipase combinations at accelerated rates to eliminate floor film that compromises autonomous machine optical sensors. This biological pathway is compressing traditional alkaline chemistry margins while enabling chemical suppliers to capture recurring revenue through temperature-sensitive cartridge logistics.
REACH Annex XVII restrictions on microplastic-containing cleaning products are compelling manufacturers to eliminate synthetic polymer thickeners from floor care formulations. The industrial consequence is a reformulation rush toward polysaccharide and clay-based rheology modifiers that maintain viscosity stability in automated dilution systems. Institutional buyers in Scandinavian markets are responding fastest, embedding microplastic-free specifications into tender requirements ahead of the 2029 enforcement deadline.
Facility managers are consolidating chemical procurement through integrated service contracts that bundle detergent supply with machine maintenance and telemetry analytics. This bundling is displacing traditional distributor relationships in North American retail and logistics chains. The shift is most visible in California and Texas, where multi-site operators negotiate enterprise-wide agreements with autonomous fleet OEMs that specify exclusive chemical formulations.
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market Segmentation
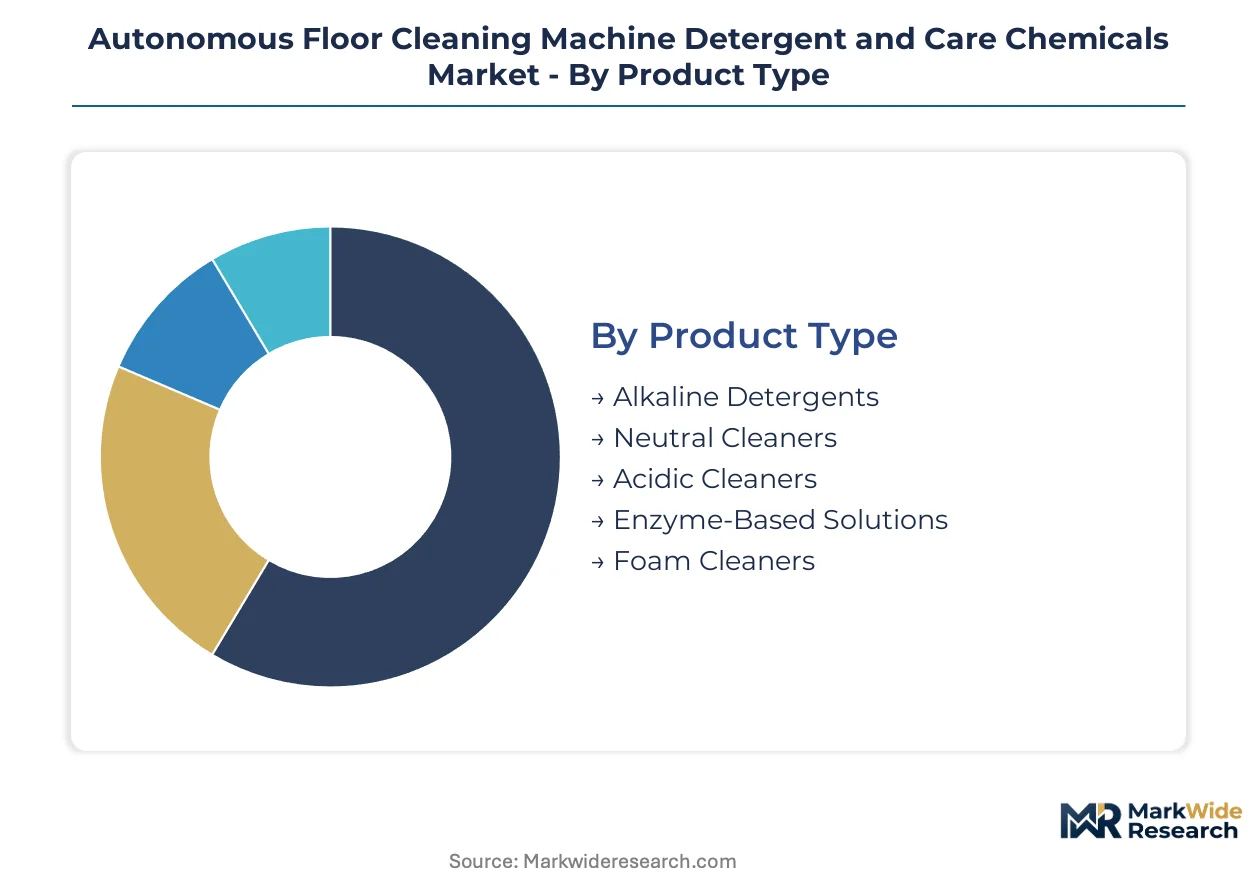
Formulation chemistry, packaging architecture, and end-use compliance requirements fragment this market into distinct competitive arenas. Each segment carries unique margin structures tied to regulatory certification tiers and machine OEM integration depth.
Product Type:
Margin pools concentrate in biological formulations where temperature-controlled logistics and proprietary enzyme blends sustain pricing power against commodity surfactants.
- Alkaline Detergents:High-pH formulations (typically 11-13) incorporating sodium hydroxide and silicates for heavy industrial soil removal. Manufacturing facilities in Germany's Ruhr industrial belt specify these concentrates for autonomous scrubbers handling petroleum residues and carbonized deposits, though REACH phosphonate restrictions are forcing chelating agent substitutions that extend R&D cycles.
- Enzyme-Based Solutions:Protease-lipase-amylase blends operating at neutral pH that digest organic soils without film residue. Healthcare facilities in California and aged-care operators in Osaka prefecture are standardizing these formulations to eliminate slip hazards and protect optical sensor arrays on autonomous fleets.
- Neutral Cleaners:pH 6-8 surfactant systems with mild chelators for daily maintenance cleaning.
- Acidic Cleaners:Phosphoric or citric acid blends for mineral deposit removal and concrete efflorescence control.
- Foam Cleaners:High-viscosity formulations for vertical surface application and extended contact time.
Alkaline detergents hold installed capacity. Enzyme-based solutions are rotating up the share rankings.
Application:
Volume concentration follows autonomous machine deployment density, with transport infrastructure and logistics hubs driving cartridge-format throughput.
- Commercial Spaces:Retail chains and office complexes requiring residue-free finishes for liability reduction. Multi-site operators in Texas and Illinois are consolidating procurement through chemical-as-a-service contracts tied to machine telemetry, displacing traditional distributor relationships.
- Manufacturing Facilities:Heavy-duty cleaning protocols for production floors with chemical resistance specifications. Bavarian automotive suppliers and North Rhine-Westphalian logistics hubs operate centralized chemical rooms that standardize bulk-to-cartridge refill systems for autonomous fleet compatibility.
- Educational Institutions:Budget-constrained segments prioritizing pH-neutral formulations for mixed flooring substrates.
- Hospitality Venues:Aesthetic-focused applications demanding rapid-dry, non-slip finishes for guest safety.
- Transport Hubs:High-frequency cleaning cycles for airports and rail terminals with 24/7 operational requirements.
Manufacturing facilities anchor current procurement volumes. Commercial spaces are gaining share fastest through enterprise contract consolidation.
End User Industry:
Compliance tier differentiation separates institutional buyers with EPA Safer Choice mandates from industrial operators prioritizing cost-per-wash economics.
- Institutional Buildings:Hospitals, government facilities, and corporate campuses with sustainability procurement criteria. Acute care facilities in Ontario and Massachusetts specify EPA Safer Choice-certified enzymatic detergents for infection control protocols, creating pull-through demand for pH-neutral formulations compatible with epoxy flooring systems.
- Food Processing Units:Sanitizer-detergent hybrids requiring FDA food contact notification and EPA registration. Protein processing plants in Wisconsin and poultry operations in Georgia deploy autonomous machines with wet-cleaning chemistries that eliminate rinse cycles while maintaining USDA compliance.
- Warehousing Centers:Throughput-focused operations with centralized chemical mixing stations and bulk procurement.
- Event Management:Temporary deployment scenarios favoring portable cartridge systems for rapid setup.
- Recreational Centers:Chlorine-tolerant formulations for pool decks and locker room environments.
Warehousing centers maintain the largest installed base. Food processing units are climbing the fastest as FDA compliance tiers capture premium pricing.
Packaging Type:
Machine OEM dispensing architectures dictate packaging format viability, with sealed cartridge systems locking out third-party bulk alternatives.
- Cartridges:Pre-measured, sealed containers with RFID or mechanical keying for autonomous machine compatibility. Tennant and Nilfisk fleet operators in Scandinavian markets and German facility management contracts specify these systems to eliminate operator dilution error and enable consumption tracking.
- Bulk Containers:55-gallon drums and totes for high-throughput warehousing centers with centralized chemical rooms. Amazon fulfillment centers and DHL hubs in the US Midwest and German logistics corridors sustain margin pools through annual volume contracts, though retrofit costs for autonomous machine integration create switching friction.
- Refill Packs:Concentrate pouches for manual dilution in semi-autonomous operations.
- Spray Bottles:Spot-cleaning formats for hybrid human-robot cleaning workflows.
- Sachets:Single-use packets for event management and temporary deployments.
Bulk containers retain volume leadership in industrial segments. Cartridges are expanding share through OEM fleet bundling agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in detergent concentrates favor German and Dutch formulation hubs supplying autonomous fleet operators across Northern Europe, while US Gulf Coast petrochemical corridors feed domestic cartridge production. Trade balances shift as REACH compliance costs redirect intra-European supply chains.
United States
Hospital-acquired infection protocols in Massachusetts and California acute care facilities are expanding enzymatic detergent procurement. EPA Safer Choice certification requirements are compressing formulation timelines for Midwest chemical manufacturers. Texas and Illinois multi-site retail operators are consolidating chemical-as-a-service contracts through machine telemetry integration.
Germany
Bavarian automotive suppliers and North Rhine-Westphalian logistics hubs operate centralized chemical rooms standardizing cartridge-based dosing systems. REACH phosphonate discharge restrictions are forcing Ruhr industrial belt formulators toward biodegradable chelating alternatives. Berlin-Brandenburg facility management contracts specify RFID-keyed cartridges to eliminate operator dilution error.
Japan
Tokyo and Osaka prefecture aged-care facilities are adopting residue-free enzymatic formulations to reduce slip litigation exposure. METI facility automation subsidies are accelerating autonomous fleet deployment in labor-constrained demographics. Kanto region procurement managers prioritize temperature-sensitive cartridge logistics for protease-lipase blends.
China
Dual carbon mandates from MEE are reshaping surfactant raw material sourcing for Yangtze River Delta formulators. Shanghai and Jiangsu province warehousing centers with high-throughput operations sustain bulk container margin pools. GB standards compliance is segmenting domestic supply between institutional and industrial end users.
Canada
Ontario hospital procurement specifications mirror EPA Safer Choice criteria for pH-neutral enzymatic systems. Health Canada and PMRA oversight of food processing environments creates compliance tier differentiation from US protocols. Quebec institutional buyers are embedding microplastic-free specifications ahead of 2029 enforcement horizons.
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and autonomous machine OEMs with captive aftermarket channels. The vendor base splits between formulation specialists with regulatory certification depth and equipment manufacturers leveraging proprietary dispensing architectures. Three archetypes dominate: institutional chemical suppliers with EPA Safer Choice portfolios, autonomous fleet OEMs with locked detergent systems, and regional formulators serving warehousing bulk contracts. Competitive moves center on cartridge architecture exclusivity agreements and integrated service contract bundling.
Among diversified chemical conglomerates, Ecolab and Diversey occupy positions anchoring institutional channel access through recurring revenue models tied to machine placements. Tennant Company exemplifies the OEM-captive archetype, leveraging proprietary dispensing system integration to sustain aftermarket chemical lock-in. Alfred Kärcher and Nilfisk represent European equipment manufacturers with formulation capabilities spanning alkaline concentrates to enzyme-based solutions. Hako Group and Taski sit within the mid-tier specialist segment, serving regional facility management contracts with compliance-tier differentiation.
| Leading Market Players |
|---|
| Alfred Kärcher |
| Nilfisk |
| Tennant Company |
| Hako Group |
| Taski |
| Dyson |
| Ecolab |
| Diversey |
| SC Johnson Professional |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day cartridge inventory cycles at German logistics hubs concentrate pricing power with formulation specialists who control temperature-sensitive enzyme logistics, while bulk detergent buyers in US warehousing corridors face divergent cost structures tied to ethylene oxide feedstock exposure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle detergent supply with machine maintenance telemetry. Three-tier pricing structure across premium, standard, and economy levels separates EPA Safer Choice-certified enzymatic formulations from legacy alkaline concentrates and commodity surfactant blends. Pricing pressure stems from REACH phosphonate discharge restrictions forcing Ruhr industrial belt formulators toward biodegradable chelating alternatives that extend R&D cycles. Warehousing centers with annual volume locks demonstrate highest price sensitivity, while acute care facilities in Massachusetts and California prioritize certification tiers over per-unit cost.
Supply Chain Analysis
Container availability constraints on Rotterdam-to-Hamburg trade lanes compress inbound logistics costs for Dutch and German formulation hubs supplying Northern European autonomous fleet operators. Supply concentrates in Germany, the Netherlands, and the US Gulf Coast, with Ruhr industrial belt plants and Rotterdam chemical corridors feeding cartridge production while Texas petrochemical complexes sustain bulk concentrate manufacturing. Raw material dependencies center on ethylene oxide, linear alkylbenzene, and protease-lipase enzyme blends. Single-source sensor compatibility risk from Tennant and Nilfisk proprietary dispensing architectures creates technical lock-in limiting third-party chemical supplier switching. Distribution runs through institutional channel partners and OEM-captive aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry substitution pressure from residue-free enzymatic systems threatens legacy alkaline detergent incumbents, requiring defensive repositioning around certification depth and machine integration lock-in.
For Market Incumbents: Consolidate regulatory certification portfolios by accelerating parallel EPA Safer Choice and EU ECHA hazard classification approvals to compress 18-24 month launch windows. Deepen backward integration into temperature-sensitive enzyme logistics to defend margin pools against emerging biological formulation specialists. Proprietary dispensing architecture exclusivity agreements with autonomous fleet OEMs remain the critical lever for sustaining aftermarket chemical lock-in against third-party surfactant suppliers. For New Entrants and Emerging Players: Chemical-as-a-service telemetry gaps in multi-site retail chains create first-mover openings for IoT-enabled consumption tracking models that displace volume-based procurement. Target Japanese aged-care facilities in Tokyo and Osaka prefectures where METI facility automation subsidies and labor shortage demographics underpenetrate residue-free enzymatic formulations. Lead with FDA food contact notification expertise to capture share in protein processing plants requiring sanitizer-detergent hybrid chemistries without rinse cycles. For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue infrastructure play because enterprise contract bundling of detergent supply with machine maintenance and telemetry analytics displaces traditional distributor relationships. Acquisition targets should emphasize formulation specialists with dual certification depth and proprietary cartridge logistics capabilities. Monitor EPA Safer Choice certification velocity as the inflection signal indicating which formulators can compress R&D timelines while competitors face stranded legacy alkaline assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Logistics | Temperature-controlled supply chains protect protease-lipase blend stability for healthcare contracts. |
| Dual Certification Investment | Parallel EPA Safer Choice and EU ECHA approvals compress product launch windows against competitors. |
| Cartridge Architecture Exclusivity | RFID-keyed dispensing systems lock out third-party bulk alternatives from Tennant and Nilfisk fleets. |
| Chemical-as-a-Service Launch | Telemetry-enabled consumption tracking displaces volume procurement in Texas and Illinois retail chains. |
| Regulatory Compliance Tier Expansion | FDA food contact notification captures premium pricing in Wisconsin protein processing plants. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across facility management directors in German logistics hubs, procurement leads at US acute care facilities, technical R&D directors at surfactant formulators, and aftermarket service heads at autonomous fleet OEMs. Secondary validation drew from EPA Safer Choice certified product listings, EU ECHA REACH registration databases, SEC 10-K filings of diversified chemical conglomerates, and customs trade data tracking ethylene oxide and linear alkylbenzene flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the analysis window, the analytical framework modeled formulation chemistry tiers, packaging architectures, end-use compliance requirements, and regional production hub concentrations. CAGRs were derived from segment-level growth trajectories weighted by autonomous machine deployment density and regulatory mandate timelines. Industry-specific forecast inputs incorporated REACH phosphonate restriction enforcement horizons and METI facility automation subsidy allocation patterns.
Forecasts assume regulatory continuity in EPA Safer Choice certification criteria and EU REACH Annex XVII restrictions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Global Antiseptic Products Market