
 Global Virtual Reality Software Market | 2026-2036
Global Virtual Reality Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Reality Software Market Foresight
Asset-light subscription licensing is tilting competitive dynamics toward developers who can scale without heavy infrastructure commitments. Unity Technologies leverages its engine dominance across mobile and PC-connected deployments to sustain creator loyalty. Epic Games anchors high-fidelity visualization pipelines through Unreal Engine's real-time rendering capabilities. Meta Platforms controls the standalone headset ecosystem, extending its software stack from hardware through content distribution.
Virtual Reality Software encompasses applications, development platforms, and runtime environments that generate immersive three-dimensional simulations rendered at 90 frames per second or higher to achieve presence and minimize motion sickness. These systems integrate spatial computing, haptic feedback protocols, and positional tracking to serve industrial design review, medical procedure rehearsal, and interactive entertainment. Cloud-hosted deployment is capturing enterprise budgets as IT departments prioritize centralized device management and over-the-air updates. Training and simulation solutions lead solution-type revenue as defense agencies and automotive OEMs mandate virtual rehearsal before physical prototyping. Visualization segments serving architecture firms and media production houses carry elevated margins due to bespoke integration requirements and long implementation cycles.
FDA scrutiny of VR-based medical devices is tightening software validation requirements for surgical planning tools, while the EU AI Act classifies certain biometric inference algorithms as high-risk, mandating conformity assessments before CE marking. FCC allocations in the United States for millimeter-wave spectrum directly affect wireless VR latency thresholds, shaping hardware-software co-design priorities. Stakeholders must monitor how national spectrum policies and medical device classifications diverge, as compliance fragmentation will determine which development platforms achieve cross-border deployment scale.
Market Dynamics
Cloud-hosted deployment architectures are compressing infrastructure barriers for enterprise VR adoption, while EU AI Act compliance mandates are forcing simultaneous re-engineering of biometric inference pipelines across medical and training applications.
Growth Catalysts
- EU AI Act high-risk classification:Mandatory conformity assessments for biometric inference algorithms are creating certified vendor ecosystems that lock out uncertified competitors.
- Surgical training modules:Healthcare institutions are deploying immersive rehearsal platforms that reduce cadaveric training costs and accelerate surgeon credentialing timelines.
- Millimeter-wave spectrum allocation:FCC allocations in the United States are enabling sub-20ms wireless latency thresholds that unlock untethered industrial VR workflows.
Market Restraints
- GPU supply concentration:Foundry capacity constraints in Taiwan are throttling rendering hardware availability and inflating headset bill-of-materials.
- GDPR biometric data friction:Cross-border data residency requirements are fragmenting cloud hosting architectures and delaying EU deployment timelines.
- Motion sickness technical ceiling:Vestibular mismatch in 15-20% of users limits session duration and constrains training module design.
Strategic Opportunities
- South Korea innovation clusters:Government-backed metaverse initiatives in Seoul and Pangyo are concentrating R&D tax incentives and testbed infrastructure.
- Automotive design review convergence:Real-time ray tracing integration with digital twin platforms is displacing physical clay modeling in German OEM studios.
- Defense procurement mandates:US Department of Defense virtual rehearsal requirements are creating sole-source contract pathways for compliant simulation vendors.
Industry Challenges
- Spatial computing talent scarcity:Shortages in 3D engine architecture and haptic protocol engineering are inflating development team costs.
- FDA 510(k) software validation timelines:Surgical planning tools face 18-24 month clearance cycles that compress competitive windows.
- Legacy CAD integration complexity:Industrial visualization deployments require bespoke middleware to bridge Siemens NX and Autodesk Revit pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Reality Software Market |
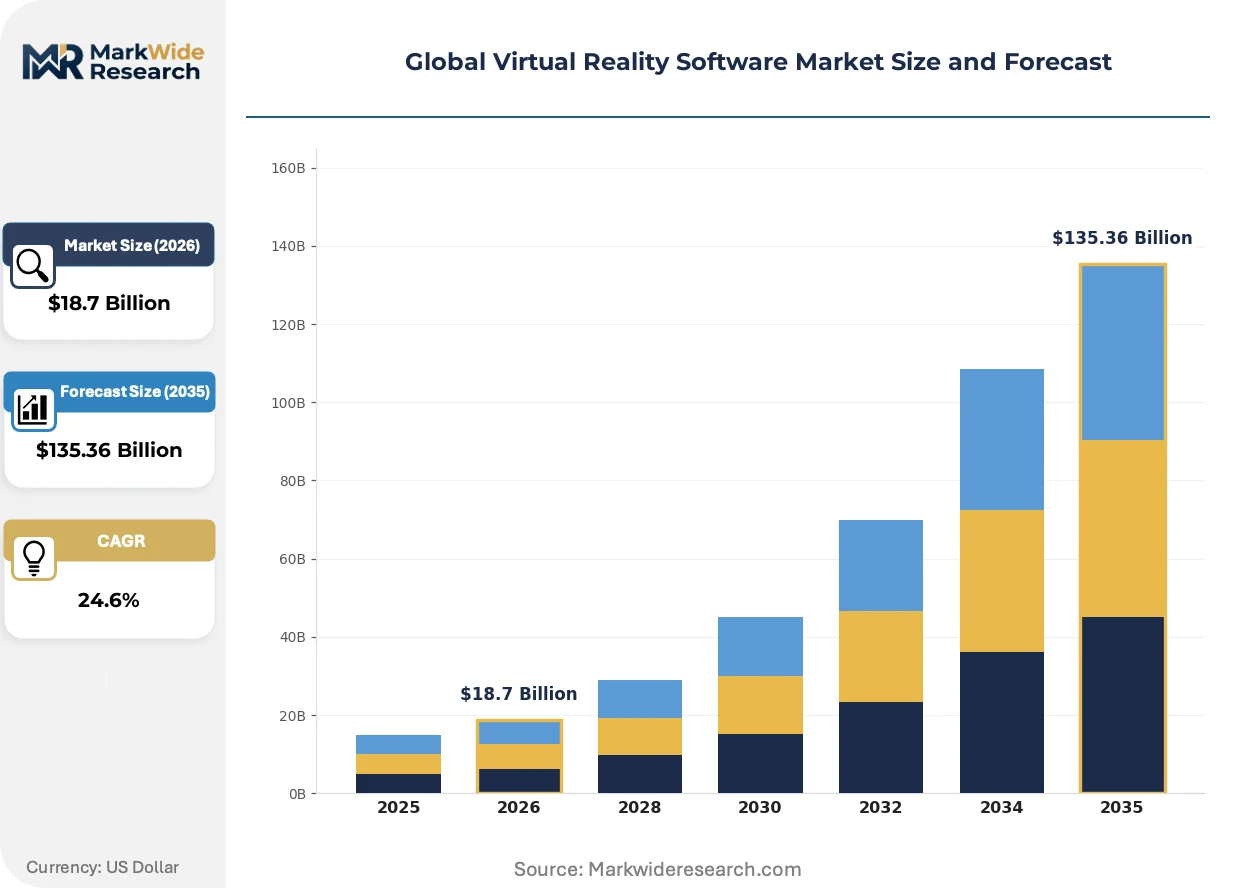
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Standalone, PC-Connected, Mobile-Based, Cloud-Hosted Solution Type: Visualization, Training & Simulation, Design & Modeling, Virtual Tours, Gamification Use Case: Education & Learning, Defense Simulation, Real Estate Showcasing, Entertainment, Product Prototyping End User Industry: Automotive OEMs, Aerospace Engineering, Architecture Firms, Media Production |
| Companies Covered | Meta Platforms, Unity Technologies, Sony, Microsoft, Samsung Electronics, Alphabet, HTC Corporation, Epic Games, Autodesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Reality Software Market Shifts & Advancements
Rendering pipelines are fragmenting across fidelity tiers as enterprise buyers prioritize functional presence over photorealism, while regulatory pressure on biometric data is forcing architectural bets on edge inference versus cloud processing.
Cloud-native runtime environments are migrating from centralized GPU farms to edge-computing nodes that minimize motion-to-photon latency. Automotive OEMs in Germany and defense contractors in the United States are piloting these distributed architectures for design review and mission rehearsal. This topology shift is compressing incumbent platform advantages by lowering the infrastructure threshold for specialized simulation vendors.
The EU AI Act's high-risk classification for emotion recognition and biometric inference algorithms is mandating conformity assessments before CE marking. Medical device manufacturers must now document algorithmic transparency and human oversight protocols for surgical planning tools. This regulatory layering is favoring established healthcare IT vendors with existing quality management systems over pure-play VR entrants.
Enterprise procurement is consolidating around subscription licensing with embedded over-the-air update guarantees. Industrial training departments are displacing perpetual licenses with per-seat annual contracts that bundle content libraries and hardware management. This preference shift is most visible in United States manufacturing and German automotive verticals, where IT standardization committees prioritize centralized device fleets.
Global Virtual Reality Software Market Segmentation
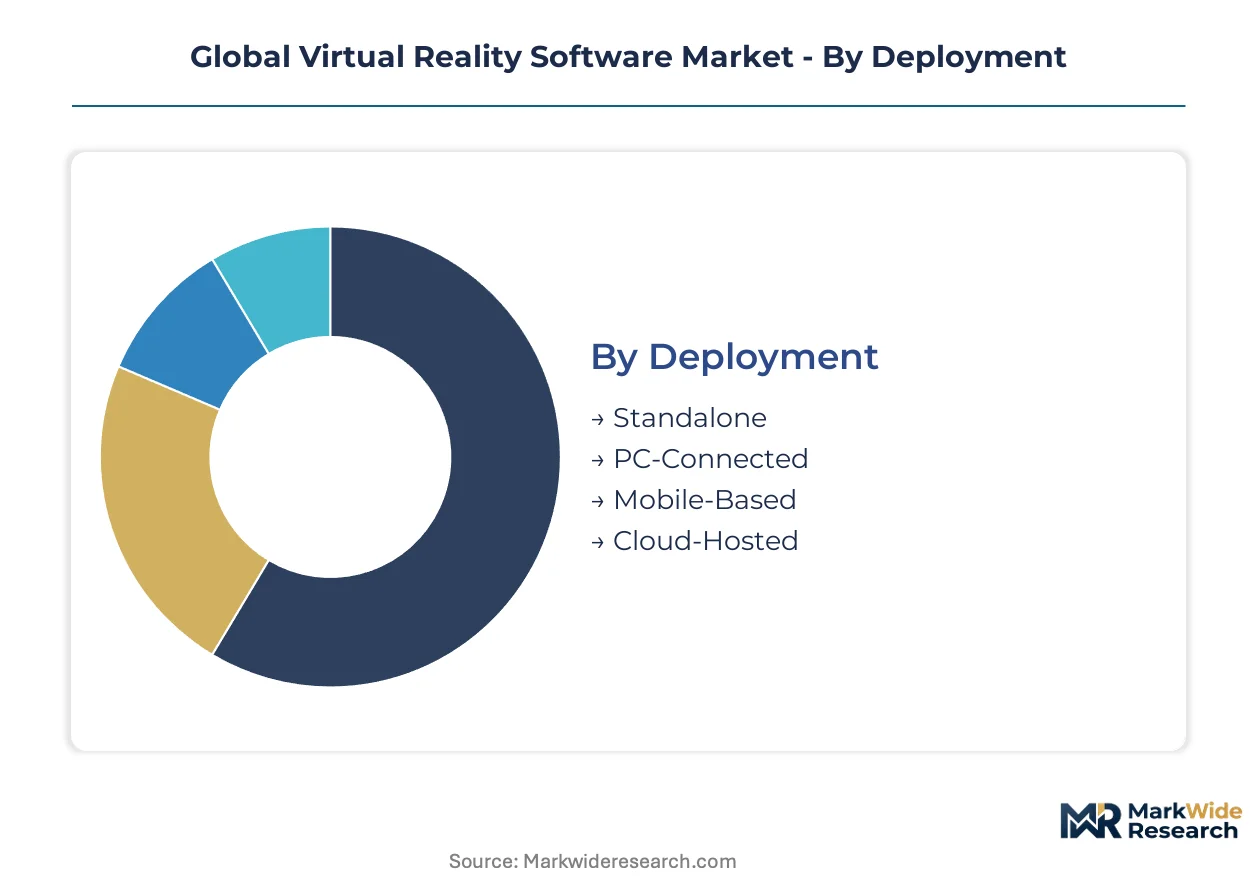
VR software segmentation reveals how deployment architectures and solution types align with distinct latency, fidelity, and compliance requirements across industrial verticals. Each category maps to specific procurement patterns and regulatory exposure that determine vendor competitiveness.
Deployment:
Mature on-device rendering coexists with emerging cloud-streamed pipelines that redistribute computational load across network edges.
- Standalone:All-in-one headsets with embedded Snapdragon or equivalent SoCs process rendering locally without tethering. Meta Platforms dominates this architecture in United States consumer and enterprise training deployments where IT departments prioritize untethered mobility and rapid deployment cycles.
- PC-Connected:Tethered configurations leverage discrete NVIDIA or AMD GPUs for photorealistic fidelity in German automotive design studios and United States defense simulation facilities. Demand concentrates where visual accuracy outweighs mobility constraints and infrastructure investment thresholds remain acceptable.
- Mobile-Based:Smartphone-dependent viewers using Cardboard or Gear VR protocols deliver basic stereoscopic experiences through existing device fleets. South Korean telcos bundle these solutions for mass-market content sampling and lightweight educational modules.
- Cloud-Hosted:Edge-rendered streams transmit compressed frames to thin-client headsets, centralizing GPU resources for enterprise IT governance. German manufacturing conglomerates and United States healthcare systems pilot these architectures to satisfy GDPR and HIPAA data residency requirements while enabling over-the-air content synchronization.
PC-Connected retains volume leadership in high-fidelity industrial applications; Cloud-Hosted holds the steepest expansion curve as compliance pressures favor centralized data governance.
Solution Type:
Application maturity varies sharply across functional depth, with visualization and training modules commanding established budgets while gamification remains experimental.
- Visualization:Real-time rendering pipelines convert CAD and BIM datasets into navigable 3D environments for design review and stakeholder presentation. Architecture firms in Germany and media production houses in South Korea drive premium pricing for bespoke integration with Autodesk Revit and Unreal Engine workflows.
- Training & Simulation:Immersive rehearsal platforms replicate procedural scenarios with haptic feedback and performance analytics. United States defense agencies mandate virtual mission rehearsal before live exercises, while healthcare institutions in Germany deploy surgical modules to reduce cadaveric training costs.
- Design & Modeling:Spatial manipulation tools enable direct sculpting and assembly validation within virtual volumes. Automotive OEMs in Germany displace physical clay modeling with digital twin integration.
- Virtual Tours:Pre-rendered or real-time navigable spaces for property marketing and cultural heritage preservation. Real estate developers in South Korea deploy these for off-plan sales in Seoul's dense urban market.
- Gamification:Engagement-layer mechanics including achievement systems and competitive leaderboards layered atop training or marketing content. United States corporate learning departments experiment with these for retention metrics in soft-skills modules.
Training & Simulation captures the largest share of enterprise procurement; Gamification shows the most volatile growth trajectory as ROI measurement remains immature.
Use Case:
Functional applications span regulated defense systems to discretionary entertainment, with compliance burden determining vendor qualification thresholds.
- Education & Learning:Curriculum-integrated modules spanning STEM visualization to vocational skills rehearsal. South Korea's government-backed metaverse initiatives concentrate R&D funding for K-12 and university deployment.
- Defense Simulation:Mission rehearsal and equipment familiarization systems subject to ITAR and national security classification. United States Department of Defense procurement mandates create sole-source pathways for compliant vendors.
- Real Estate Showcasing:Pre-construction property visualization and interior configuration tools. German developers leverage these for Munich and Frankfurt luxury residential marketing.
- Entertainment:Interactive narrative experiences and location-based attractions. United States theme park operators and South Korean VR cafés drive location-based deployment.
- Product Prototyping:Virtual assembly validation and ergonomic assessment before physical tooling. German automotive suppliers use these to compress design iteration cycles.
Defense Simulation maintains the highest contract values; Product Prototyping is gaining share fastest as digital twin convergence accelerates.
End User Industry:
Customer concentration reflects sector-specific digital maturity and capital intensity for immersive infrastructure.
- Automotive OEMs:Design review, ergonomic validation, and marketing configuration systems. BMW, Mercedes-Benz, and Volkswagen studios in Germany anchor demand for real-time ray tracing and multi-user collaborative review.
- Aerospace Engineering:Maintenance training and cabin configuration visualization subject to FAA and EASA certification requirements. Boeing and Airbus supplier networks in Germany and the United States drive specialized simulation procurement.
- Architecture Firms:Client presentation and construction sequencing visualization. Foster + Partners and Zaha Hadid Architects deploy these for London and Middle East project pitches.
- Media Production:Virtual production stages and previsualization for film and broadcast. Industrial Light & Magic and Framestore facilities in the United States and United Kingdom pioneer LED-volume integration.
Automotive OEMs dominate current spending; Media Production exhibits the most rapid technology refresh cycles as virtual production standards evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed innovation clusters and spectrum allocation policies are steering capital toward three national centers. Seoul, Stuttgart, and Austin anchor distinct specialization vectors that concentrate R&D tax incentives and testbed infrastructure.
United States
Defense procurement mandates from the Department of Defense drive mission rehearsal platform demand. FCC millimeter-wave spectrum allocations enable sub-20ms wireless latency thresholds for untethered industrial workflows. Austin and Seattle concentrate venture funding for cloud-hosted VR architectures serving healthcare systems.
Germany
Automotive OEMs mandate virtual design review before physical prototyping. EU AI Act high-risk classification for biometric inference forces conformity assessments for surgical planning tools. Stuttgart and Munich studios anchor real-time ray tracing development for digital twin integration.
South Korea
Government metaverse initiatives concentrate R&D funding for K-12 and university deployment. MFDS regulatory pathways guide medical device software validation for domestic vendors. Seoul and Pangyo innovation clusters host testbed infrastructure for haptic protocol engineering.
United Kingdom
Media production houses drive virtual production stage deployment for LED-volume integration. GDPR cross-border data residency requirements fragment cloud hosting architectures for biometric applications. London and Manchester anchor post-production pipelines serving broadcast and film verticals.
Japan
Industrial training departments prioritize centralized device fleet management for manufacturing workflows. METI standards coordination shapes haptic feedback protocol adoption across automotive suppliers. Tokyo and Osaka concentrate enterprise procurement for visualization solutions in precision engineering.
Global Virtual Reality Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic layers: engine platforms, hardware ecosystems, and specialized vertical applications. Independent simulation vendors compete against integrated stacks that bundle rendering, distribution, and device management. Dominant competitive moves include strategic partnerships between automotive OEMs and visualization specialists, plus technology licensing agreements that embed rendering engines into enterprise training platforms.
Within the integrated platform tier, Meta Platforms and Unity Technologies exemplify divergent architecture bets—standalone headset ecosystems versus cross-platform engine licensing. Epic Games occupies a position at the high-fidelity visualization frontier, anchoring real-time rendering pipelines for defense and automotive applications. These three entities represent the primary competitive anchors around which specialized vendors cluster.
| Leading Market Players |
|---|
| Meta Platforms |
| Unity Technologies |
| Sony |
| Microsoft |
| Samsung Electronics |
| Alphabet |
| HTC Corporation |
| Epic Games |
| Autodesk |
| Others |
Supply & Pricing Matrix
Taipei-Hsinchu corridor foundry capacity constraints directly compress GPU availability for headset manufacturers, amplifying pricing power among rendering hardware vendors while forcing software developers toward cloud-streamed architectures that redistribute compute costs across subscription tiers.
Pricing Analysis
Certification level creates the primary spread across deployment tiers, with FDA 510(k)-cleared surgical modules and EU AI Act-conformant biometric platforms commanding substantial premiums over uncertified training content. Subscription licensing dominates enterprise procurement, though project-based contracts persist for bespoke visualization integrations in German automotive studios. Pricing pressure stems from GPU supply concentration inflating headset bill-of-materials, which compresses margins for standalone software vendors lacking hardware ecosystem control. Healthcare systems exhibit lowest price sensitivity given compliance mandates, while educational institutions in South Korea demonstrate acute cost consciousness under government procurement ceilings.
Supply Chain Analysis
Foxconn, Pegatron, and Quanta Computer hold dominant contract manufacturing capacity for headset assembly, with TSMC and Samsung Foundry anchoring Snapdragon and equivalent SoC fabrication. Taiwan, South Korea, and China concentrate upstream component supply, drawing from rare earth processing facilities in Inner Mongolia and display panel production in Gumi and Suzhou. Single-source vulnerability in advanced node semiconductor fabrication presents acute exposure, compounded by ITAR restrictions fragmenting defense simulation supply chains. Distribution runs through direct enterprise sales teams for large healthcare and automotive accounts, with cloud marketplaces and value-added resellers serving mid-market training deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles and automotive design refresh timelines drive pronounced demand cyclicality, with current positioning reflecting recovery phase entry as post-pandemic training budgets normalize and digital twin investments accelerate.
For Market Incumbents: Pre-empt cloud-native runtime migration by acquiring edge-computing infrastructure specialists, while locking in multi-year surgical module contracts before FDA validation timelines extend further. Meta Platforms and Unity Technologies face displacement risk from specialized simulation vendors leveraging distributed rendering architectures, necessitating backward integration into haptic protocol engineering to maintain platform stickiness. For New Entrants and Emerging Players: Mid-market manufacturing training in Japan and precision engineering verticals in South Korea represent the most penetrable entry points, given incumbent platform fatigue with legacy CAD integration complexity. Cloud-hosted deployment architectures lower infrastructure barriers sufficiently for specialized vendors to compete against integrated stacks. A channel partnership strategy with industrial automation distributors accelerates initial footprint without direct enterprise sales overhead. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU AI Act conformity assessments and FDA 510(k) clearance pathways create durable moats around certified healthcare and defense vendors. Acquisition targets should demonstrate existing quality management systems and documented algorithmic transparency protocols. Watch millimeter-wave spectrum allocation decisions in the United States and Germany as inflection indicators for untethered industrial workflow adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding Unreal Engine pipelines into Siemens NX workflows displaces physical prototyping at BMW and Mercedes-Benz studios. |
| Regulatory Certification Pathway | EU AI Act conformity assessments for biometric inference algorithms lock out uncertified competitors from CE-marked medical deployments. |
| Strategic Partnership | Cloud service alliances with AWS and Azure enable GDPR-compliant data residency for German healthcare system procurement. |
| Acquisition of Specialist Firm | Haptic protocol engineering teams from Seoul and Pangyo clusters address spatial computing talent scarcity inflating development costs. |
| Geographic Expansion | Defense contractor presence in Austin and Seattle captures sole-source contract pathways from Department of Defense mandates. |
Research Methodology
Cross-validation between primary interviews with VR platform engineers, healthcare IT procurement officers, and defense simulation program managers anchors the qualitative findings, supplemented by secondary validation against FDA 510(k) filings, EU AI Act implementation guidance, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model, solution type, and end-user industry dimensions reconciles with top-down market sizing from trade data and sector reports.
Calibration against historical adoption curves in surgical training and automotive design review informs the projection framework across deployment architectures, organization size tiers, and regional regulatory clusters. CAGRs derive from segment-level growth rate synthesis rather than single-point extrapolation, incorporating millimeter-wave spectrum allocation timelines and GPU foundry capacity expansion announcements as industry-specific inputs.
Practitioners should monitor FCC spectrum auction outcomes, EU AI Act delegated act publications, and TSMC advanced node yield reports for early signals of forecast revision. Quarterly review of defense procurement award announcements and automotive OEM digital twin investment disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market