
 Europe Virtual Reality (VR) Health Market | 2026-2036
Europe Virtual Reality (VR) Health Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Virtual Reality (VR) Health Market Foresight
A shift from single-source hardware procurement to multi-vendor software ecosystems is recalibrating competitive dynamics across the continent. Siemens leverages its imaging infrastructure to anchor hospital-based VR deployments, while Varjo Technologies Oy specializes in high-fidelity headsets for surgical training applications. Mindmaze competes through neuromotor rehabilitation platforms that integrate proprietary motion capture with cloud analytics.
Europe Virtual Reality (VR) Health encompasses immersive computing systems delivering clinically validated visual, auditory, and haptic stimuli for diagnosis, therapy, and medical education, typically operating at sub-20ms motion-to-photon latency to prevent simulator sickness. The primary purpose is to create controlled, repeatable therapeutic environments that reduce pharmacological dependency and accelerate functional recovery. Therapeutic applications dominate current revenue as pain management protocols gain reimbursement codes in France and the Netherlands, while training segments for surgical simulation show the steepest adoption curves among teaching hospitals. Software platforms capture disproportionate margin pools relative to hardware integration, reflecting recurring licensing models and regulatory update cycles.
EMA guidance on digital therapeutics and CE marking under MDR Article 10 shape product development timelines and clinical evidence requirements for VR health solutions across EU member states. Germany's national reimbursement framework for digital health applications (DiGA) creates preferential market access for validated VR therapies, while France's ANSM evaluates cybersecurity protocols for connected medical devices. Stakeholders must monitor divergence between national health technology assessment criteria and harmonized EU conformity pathways as reimbursement fragmentation intensifies competitive positioning.
Market Dynamics
EU Medical Device Regulation (MDR) Article 10 compliance requirements are compressing product development timelines and forcing developers toward structured clinical validation frameworks, fundamentally restructuring competitive entry barriers across the continent.
Growth Catalysts
- Germany's DiGA framework:National reimbursement pathways for digital health applications create institutional pull for validated VR therapies within university hospital networks.
- Post-surgical rehabilitation demand:Hospitals across France and the Netherlands are expanding therapeutic VR programs to reduce pharmacological dependency in chronic pain management.
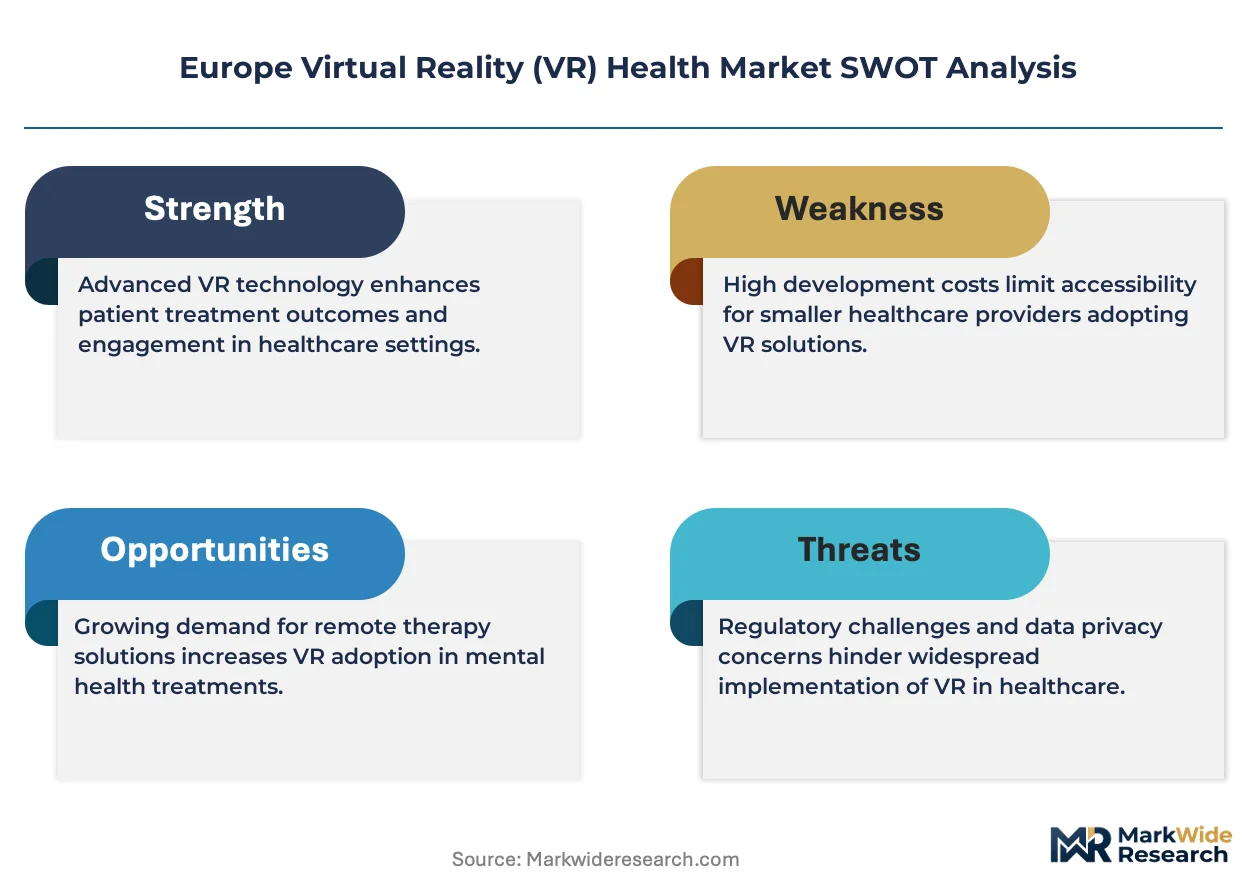
- Cloud-native software architectures:Recurring licensing models for regulatory update cycles capture disproportionate margin pools relative to hardware integration.
Market Restraints
- CE marking complexity:MDR software-as-a-medical-device classifications impose extended conformity assessment timelines and clinical evidence burdens.
- Hardware supply concentration:Sub-20ms motion-to-photon latency requirements constrain headset sourcing to specialized optical component suppliers.
- Reimbursement fragmentation:Divergent national health technology assessment criteria between France's ANSM, Germany's BfArM, and Dutch ZIN create market access inconsistency.
Strategic Opportunities
- Neuromotor rehabilitation expansion:Integration of proprietary motion capture with cloud analytics platforms addresses stroke and traumatic brain injury recovery protocols.
- Surgical training simulation:Teaching hospitals in Switzerland and Belgium show steep adoption curves for high-fidelity haptic feedback systems.
- Cybersecurity certification tailwinds:France's ANSM evaluation protocols for connected medical devices create first-mover advantage for compliant platform vendors.
Industry Challenges
- Clinical validation talent scarcity:Shortage of biostatisticians and regulatory affairs specialists familiar with immersive technology endpoints delays trial design.
- Legacy EHR integration friction:Hospital IT departments struggle with API interoperability between VR therapy platforms and existing patient management systems.
- Simulator sickness mitigation:Engineering teams must optimize rendering pipelines to maintain sub-20ms latency across heterogeneous hardware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Virtual Reality (VR) Health Market |
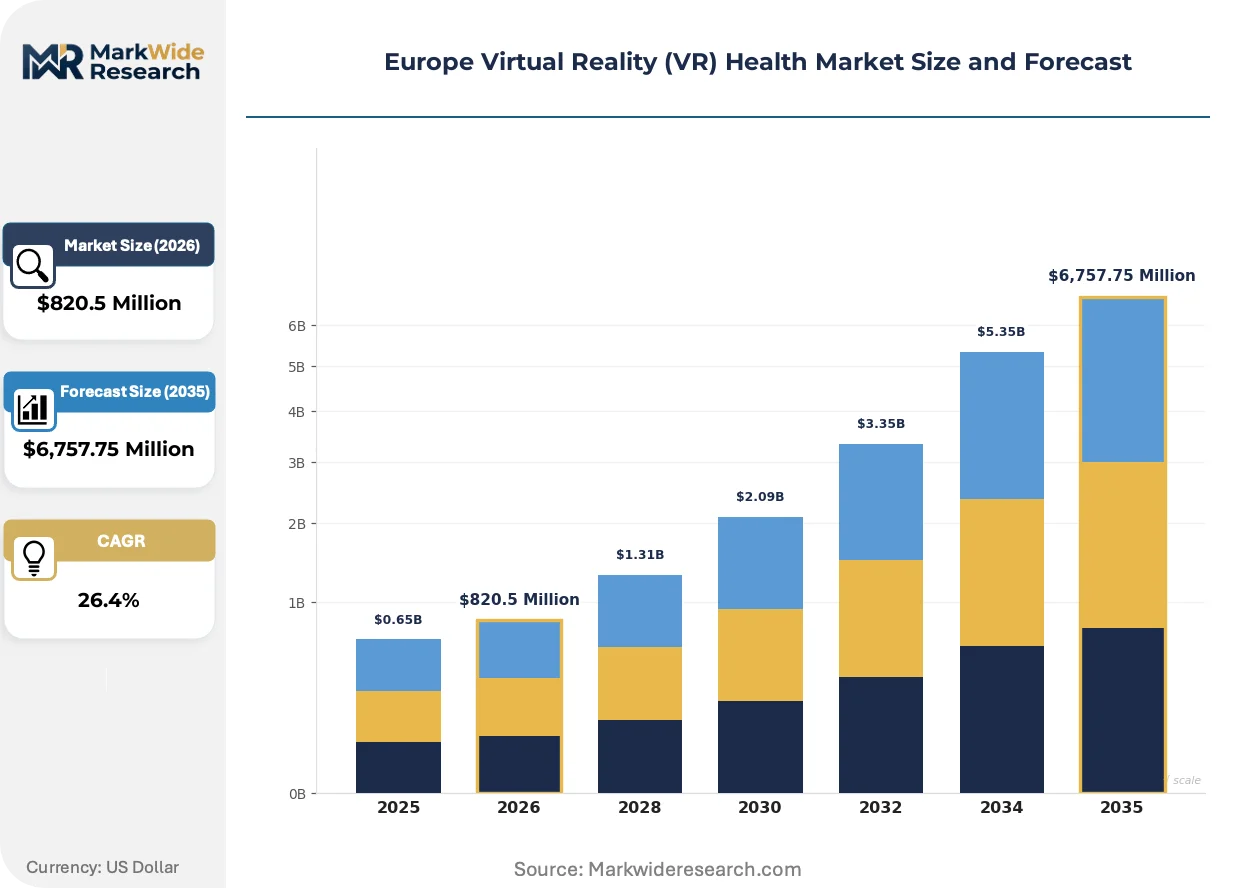
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $6,757.75 Million |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Therapeutic, Training, Rehabilitation, Pain Management End User: Hospitals, Clinics, Rehabilitation Centers, Individual Practitioners Technology: Oculus Rift, HTC Vive, PlayStation VR, Microsoft HoloLens Solution: Software Platforms, Content Development, Hardware Integration, Analytics Tools |
| Companies Covered | AppliedVR, Mindmaze, Medical Realities, Psious, XRHealth, Koninklijke Philips N.V., Siemens, Firsthand Technology, Varjo Technologies Oy, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Virtual Reality (VR) Health Market Shifts & Advancements
Multi-vendor software ecosystems are displacing single-source hardware procurement across European healthcare systems, with platform interoperability emerging as the decisive competitive variable.
Standalone wireless VR headsets is overtaking tethered systems in hospital deployments. Surgical training programs at teaching hospitals in Sweden and Italy are adopting untethered devices for flexible simulation lab configurations. This mobility is compressing installation timelines and reducing dedicated infrastructure capex, enabling faster program scaling across departmental budgets.
MDR Article 10 clinical evidence requirements are tightening software validation protocols. Developers must now submit pre-market clinical investigation data for therapeutic claims, extending time-to-revenue by twelve to eighteen months for new entrants. Germany's notified bodies are processing these submissions fastest, concentrating regulatory expertise in Munich and Berlin assessment clusters.
Hospital procurement teams are consolidating vendor relationships around integrated therapy platforms. French and Dutch purchasing cooperatives now favor single-contract solutions spanning hardware, software licensing, and clinical training over point-product acquisitions. This bundling preference favors established platform vendors with service infrastructure across multiple member states.
Europe Virtual Reality (VR) Health Market Segmentation
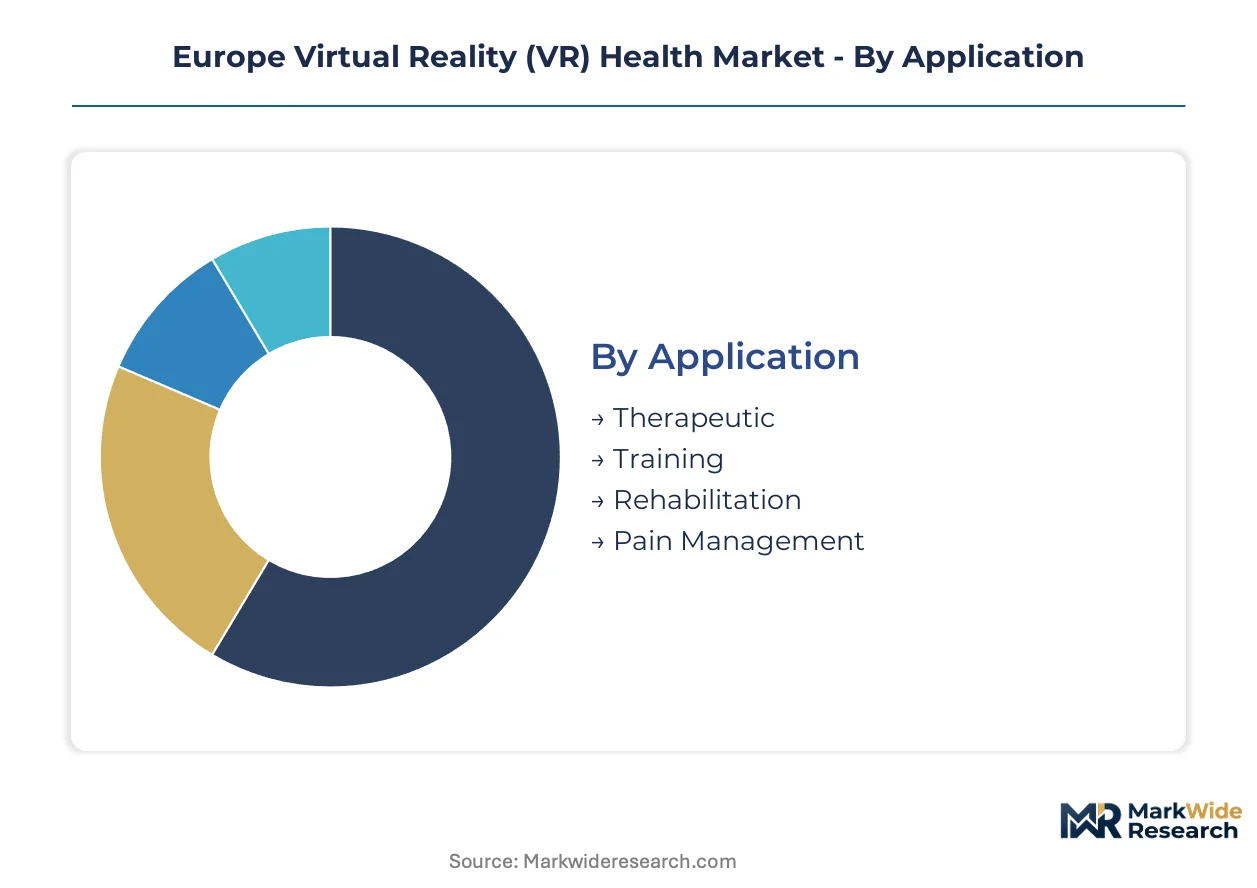
Segmentation in the Europe VR Health market reveals divergent upgrade cycles across therapeutic versus training applications, with procurement patterns shifting from capital-intensive hardware bundles toward recurring software licensing models. Understanding these segment dynamics illuminates where reimbursement frameworks and clinical validation requirements create sustainable margin pools.
Application:
Therapeutic installations operate on three-to-five-year replacement cycles tied to MDR recertification timelines, while training platforms refresh faster as surgical simulation fidelity standards advance.
- Therapeutic:Clinically validated protocols for anxiety disorders, PTSD exposure therapy, and cognitive rehabilitation require pre-market clinical investigation data under MDR Article 10. Demand concentrates in Germany's university hospital network where DiGA reimbursement pilots create institutional pull for validated interventions.
- Training:High-fidelity surgical simulation programs at teaching hospitals in Sweden and Belgium adopt untethered devices for flexible lab configurations, compressing installation timelines and reducing dedicated infrastructure capex.
- Rehabilitation:Neuromotor recovery platforms integrate proprietary motion capture with cloud analytics for stroke and traumatic brain injury protocols.
- Pain Management:Protocols gaining reimbursement codes in France and the Netherlands reduce pharmacological dependency in chronic and post-surgical cases.
Therapeutic applications lead volumes today; training is gaining share fastest.
End User:
Procurement authority varies sharply across customer types, with hospital purchasing cooperatives in France and the Netherlands consolidating vendor relationships around integrated platform contracts.
- Hospitals:Teaching institutions in Switzerland and Germany anchor demand for high-fidelity surgical simulation, while community hospitals prioritize pain management protocols with clearer reimbursement pathways.
- Clinics:Outpatient mental health practices across the Netherlands adopt therapeutic VR for anxiety and phobia treatment, leveraging DiGA framework accessibility.
- Rehabilitation Centers:Specialized facilities in Belgium and France integrate neuromotor platforms with existing physiotherapy equipment.
- Individual Practitioners:Solo practitioners face capital constraints and fragmented reimbursement, limiting adoption to subscription-based software models with minimal hardware requirements.
Hospitals dominate procurement volumes; clinics are expanding most quickly.
Technology:
Hardware sourcing concentrates on specialized optical component suppliers capable of maintaining sub-20ms motion-to-photon latency across heterogeneous deployments.
- Oculus Rift:Tethered systems with established developer ecosystems support complex therapeutic environments requiring sustained computational throughput.
- HTC Vive:Lighthouse tracking precision suits surgical training applications where instrument alignment accuracy is critical.
- PlayStation VR:Lower price points and consumer distribution channels enable pilot programs in underfunded rehabilitation centers.
- Microsoft HoloLens:Mixed reality overlays for surgical navigation and anatomical visualization command premium positioning in academic medical centers.
HTC Vive leads surgical training deployments; standalone wireless systems are displacing tethered configurations fastest.
Solution:
Margin capture shifts decisively toward recurring revenue models as regulatory update cycles and interoperability requirements favor platform vendors with service infrastructure across multiple member states.
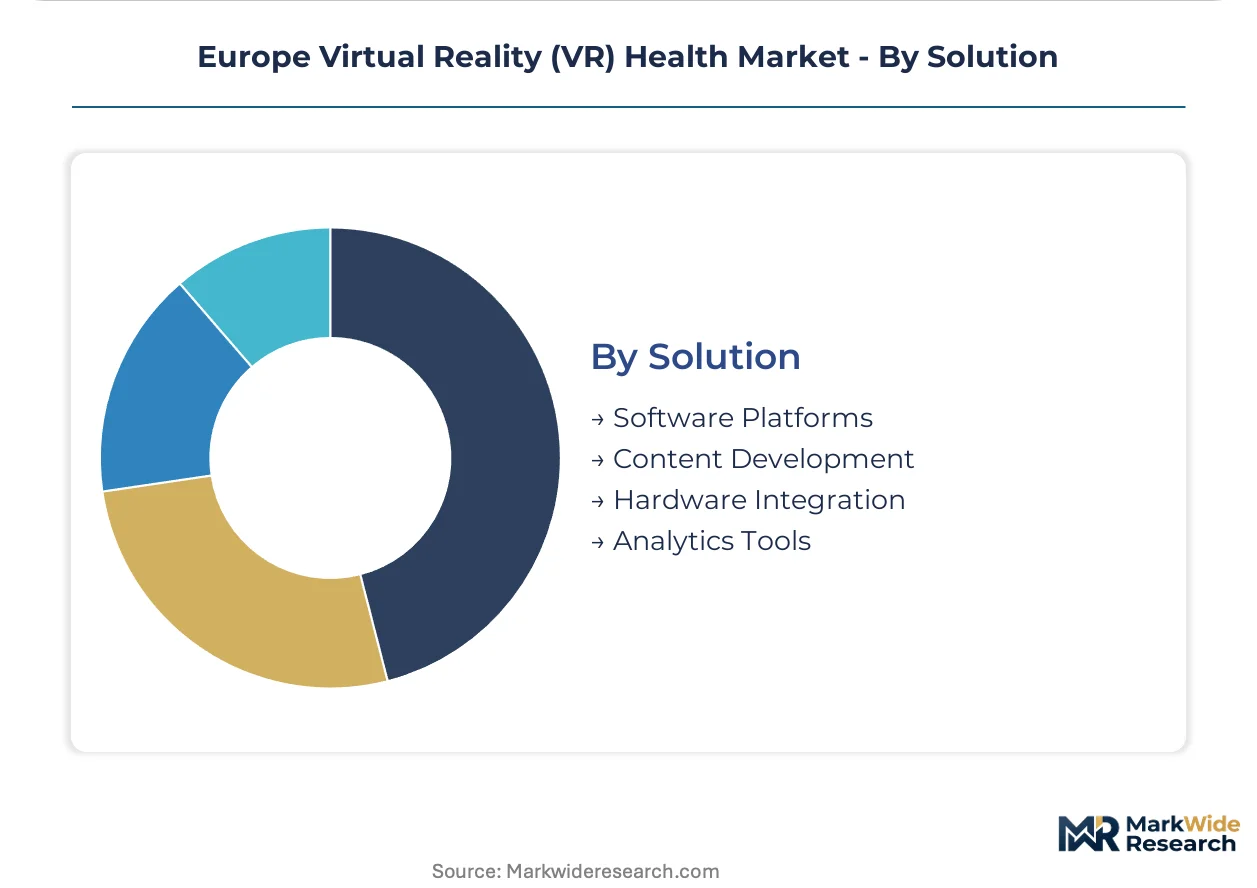
- Software Platforms:Cloud-native architectures with recurring licensing models capture disproportionate margin pools relative to hardware integration, reflecting MDR-mandated validation update cycles.
- Content Development:Clinical scenario libraries for specific therapeutic indications require specialized medical expertise and face extended time-to-revenue from clinical evidence requirements.
- Hardware Integration:System configuration and installation services face margin compression as procurement teams favor bundled single-contract solutions.
- Analytics Tools:Cloud-based outcome tracking and regulatory reporting modules create stickiness through EHR integration and longitudinal patient data capture.
Software platforms command the largest revenue share; analytics tools are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich-Berlin assessment clusters concentrate MDR regulatory expertise and accelerate notified body processing for VR health submissions. National reimbursement frameworks diverge sharply across member states, fragmenting market access while concentrating procurement authority in university hospital networks.
Germany
University hospital networks in Bavaria and Baden-Württemberg anchor therapeutic VR demand through DiGA reimbursement pilots for physiotherapy and chronic pain protocols. BfArM's streamlined digital health application evaluation creates preferential institutional pull for validated interventions. Berlin's notified bodies process MDR Article 10 submissions fastest, drawing regulatory expertise into the capital region.
France
ANSM cybersecurity evaluation protocols for connected medical devices reshape vendor qualification requirements in Paris and Lyon hospital systems. Post-surgical rehabilitation programs expand therapeutic VR deployments to reduce opioid dependency in chronic pain cases. Île-de-France purchasing cooperatives consolidate vendor relationships around single-contract platform solutions spanning hardware and clinical training.
Netherlands
ZIN health technology assessment criteria create reimbursement uncertainty for emerging VR therapeutic categories in Amsterdam and Utrecht medical centers. Outpatient mental health practices adopt anxiety and phobia treatment protocols through accessible DiGA-aligned frameworks. Eindhoven's health technology corridor attracts platform vendors seeking Benelux market entry points.
Switzerland
Swissmedic's medical device conformity pathways enable faster CE marking recognition for surgical training simulation platforms in Zurich and Geneva teaching hospitals. High-fidelity haptic feedback systems show steep adoption curves among academic medical centers with dedicated simulation lab budgets. Basel's pharmaceutical-industrial complex generates crossover demand for VR-enabled clinical trial visualization tools.
Sweden
Teaching hospitals in Stockholm and Gothenburg adopt untethered wireless VR devices for flexible surgical simulation lab configurations. Sub-20ms motion-to-photon latency requirements concentrate headset sourcing through Nordic optical component distributors. National digital health infrastructure investments compress installation timelines across regional hospital networks.
Europe Virtual Reality (VR) Health Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance and reimbursement navigation capabilities. Siemens leverages imaging infrastructure to anchor hospital-based deployments, while specialized optical component suppliers constrain hardware sourcing for latency-critical applications. Three archetypes dominate: imaging conglomerates extending into therapeutic platforms, pure-play VR headset manufacturers, and cloud-native software vendors capturing recurring licensing margins. Competitive moves concentrate on MDR clinical validation partnerships and procurement cooperative bundling contracts.
Within the therapeutic platform tier, Mindmaze exemplifies neuromotor rehabilitation specialists integrating motion capture with analytics, while AppliedVR occupies a position among pain management protocol developers seeking DiGA reimbursement codes. Varjo Technologies Oy represents high-fidelity headset manufacturers serving surgical training applications where optical precision commands premium positioning.
| Leading Market Players |
|---|
| AppliedVR |
| Mindmaze |
| Medical Realities |
| Psious |
| XRHealth |
| Koninklijke Philips N.V. |
| Siemens |
| Firsthand Technology |
| Varjo Technologies Oy |
| Others |
Supply & Pricing Matrix
Optical component spot prices for micro-OLED displays cascade through three distinct pricing tiers as MDR certification requirements stratify vendor qualification levels. German university hospitals absorb premium positioning for sub-20ms latency headsets, while Dutch rehabilitation centers negotiate volume discounts on tethered legacy systems.
Pricing Analysis
Input-cost pass-through from specialized optical component suppliers concentrates pricing power among CE-marked headset manufacturers with MDR Article 10 validation. Three-tier pricing structure across premium, standard, and economy levels separates surgical training platforms with haptic integration from basic therapeutic deployments. Pricing pressure stems from cloud-native software vendors capturing recurring licensing margins that compress hardware integration fees. Hospital purchasing cooperatives in France exhibit highest price sensitivity; Swiss academic medical centers show least sensitivity due to dedicated simulation lab budgets.
Supply Chain Analysis
MDR notified body certification gates concentrate headset sourcing through Taiwan, South Korea, and Finland-based optical component specialists with established CE marking track records. Supply chains draw from gallium nitride semiconductors, precision inertial measurement units, and medical-grade haptic actuators. Single-source vulnerability around sub-20ms motion-to-photon latency chipsets creates procurement risk. Distribution runs through hospital purchasing cooperatives in France and Germany that consolidate vendor relationships around single-contract platform solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Germany's DiGA reimbursement framework and France's ANSM cybersecurity evaluation protocols creates differential cost structures for platform vendors seeking fastest market access.
For Market Incumbents: Cement regulatory expertise concentration in Munich-Berlin assessment clusters to defend against emerging cloud-native software vendors with faster MDR submission timelines. Deepen backward integration into motion capture sensor production to offset optical component supply concentration. Prioritize procurement cooperative bundling contracts across French and Dutch hospital systems to lock out point-product competitors. For New Entrants and Emerging Players: Cloud-native analytics platforms with pre-built EHR interoperability modules offer the cleanest technology-first wedge for neuromotor rehabilitation segments in Belgium and the Netherlands. Target outpatient mental health clinics in the Netherlands where DiGA-aligned frameworks reduce capital barriers. Pursue subscription-based software models with minimal hardware requirements to bypass hospital IT integration friction. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR clinical validation talent scarcity meets fragmented reimbursement navigation capabilities across member states. Five-to-ten year viability favors platform vendors with service infrastructure spanning multiple EU member states. Monitor BfArM DiGA approval velocity as inflection indicator for institutional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Article 10 Clinical Validation Partnership | Accelerates notified body processing through Berlin-Munich regulatory expertise clusters. |
| DiGA Reimbursement Pathway Navigation | Unlocks preferential market access within Germany's university hospital network. |
| Cloud-Native Software Platform Launch | Captures recurring licensing margins from MDR-mandated validation update cycles. |
| EHR Integration Specialist Acquisition | Resolves legacy system interoperability friction delaying hospital deployments. |
| Procurement Cooperative Bundling Contract | Consolidates vendor relationships against point-product competitors in France and Netherlands. |
Research Methodology
Bottom-up therapeutic application modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies combined with secondary validation from EMA guidance documents, BfArM DiGA registers, ANSM cybersecurity protocols, and hospital procurement databases. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices across application, end user, technology, and solution dimensions drive volume and value projections throughout the forecast period. Modeled segments include therapeutic versus training versus rehabilitation deployment patterns, hospital versus clinic procurement authority, tethered versus standalone hardware architectures, and software platform versus hardware integration margin capture. CAGRs derive from regression analysis against reimbursement framework expansion rates and MDR submission velocity metrics.
The model holds under stable DiGA reimbursement eligibility criteria and ANSM cybersecurity evaluation timelines; deviation in MDR Article 10 clinical evidence requirements or notified body processing capacity would shift trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress across member states. A model refresh is warranted upon material change in BfArM approval velocity or ZIN health technology assessment criteria divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market