
 3D Virtual Fence Market | 2026-2036
3D Virtual Fence Market Size, Share, and Industry Trends Forecast 2026-2036
3D Virtual Fence Market Analysis
Aftermarket service revenue is narrowing the gap with initial hardware sales as installation complexity rises. Schneider Electric SE leverages its building automation footprint to bundle virtual fence deployments with energy management contracts. Senstar Technologies Ltd. anchors its position through deep specialization in video analytics for perimeter intrusion detection. RBtec Perimeter Security Systems competes on manufacturing scale, producing ruggedized sensor housings for harsh-environment installations.
A 3D virtual fence constitutes a geospatial boundary system that employs LiDAR, radar, or stereo camera arrays to detect, track, and classify objects in three-dimensional space without physical barriers, typically achieving sub-meter positional accuracy across ranges exceeding 500 meters. The technology serves commercial and industrial users requiring non-invasive perimeter security, livestock containment, or wildlife corridor management. Wireless systems and smart fences capture the dominant share of product type revenue as enterprises prioritize rapid deployment and software-defined zone reconfiguration. Sensor networks and IoT connectivity represent the fastest-expanding technology categories, driven by edge-computing advances that reduce cloud dependency and latency in alarm generation.
The FAA mandates obstacle detection standards for airspace-critical facilities, while the EPA influences wildlife management deployments through habitat disturbance protocols. ISO 22311 provides business-continuity frameworks that shape security agency procurement specifications for perimeter resilience. Stakeholders must monitor convergence between cybersecurity mandates and physical security systems as network-connected sensors expand attack surfaces beyond traditional fence architectures.
Market Dynamics
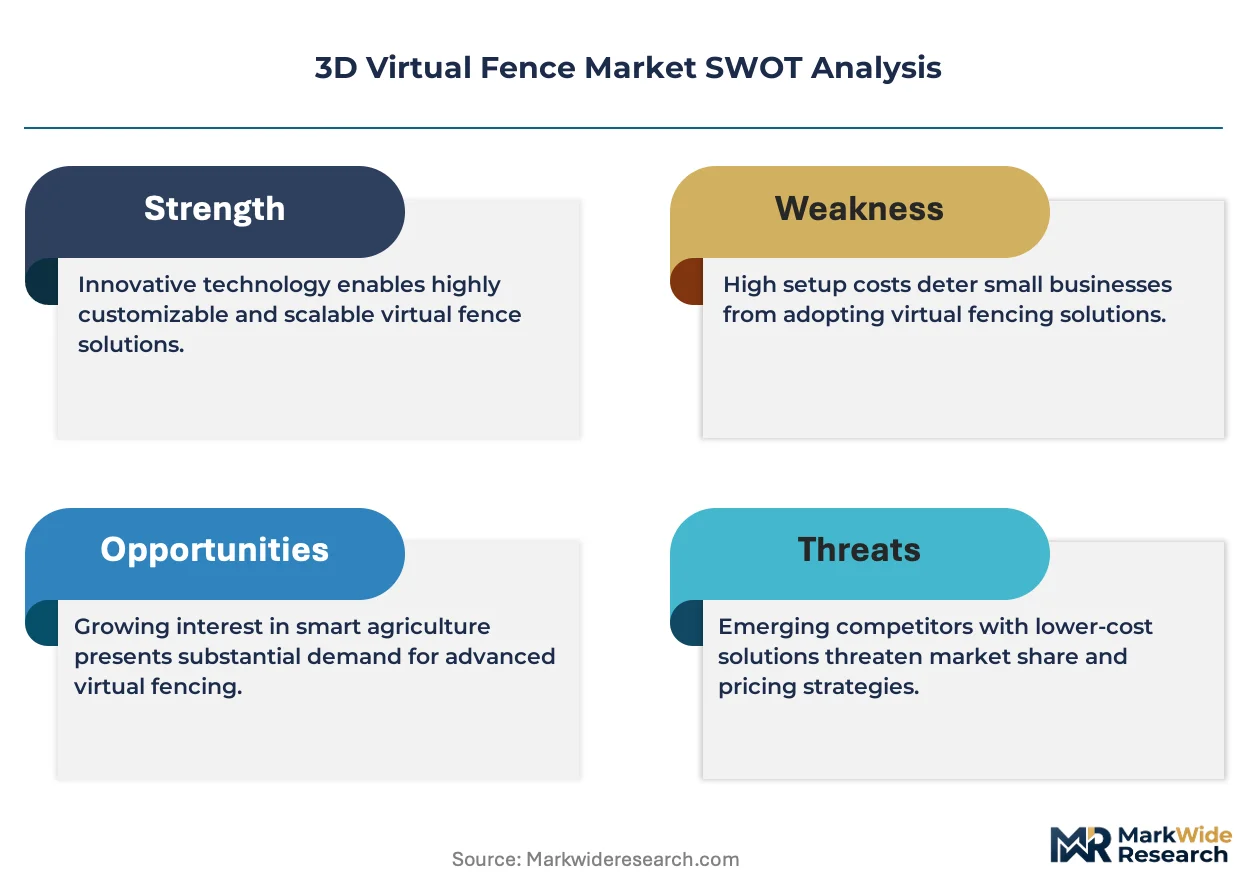
Sensor fusion architectures are compressing hardware margins while elevating software and integration services as the primary value capture mechanism across perimeter security deployments.
Growth Catalysts
- FAA Critical Infrastructure Mandates:Airspace protection standards are accelerating procurement of LiDAR-enabled obstacle detection systems at airports and energy transmission corridors across the United States.
- Edge Computing Maturation:On-device inference capabilities are eliminating cloud latency for intrusion classification, enabling real-time response protocols in livestock containment and wildlife management applications.
- Texas Energy Corridor Concentration:Petrochemical facilities along the Gulf Coast are replacing physical barriers with radar-stereo fusion arrays to satisfy both security and environmental flow requirements.
Market Restraints
- Indium Phosphide Supply Concentration:Photonics-grade semiconductor substrates for LiDAR emitters face sourcing bottlenecks from limited foundry capacity in East Asian supply chains.
- California Environmental Review:CEQA compliance timelines for sensor pole installations extend deployment cycles by 18-24 months in the state's data center corridor.
- Conventional Barrier Substitution:Electrified fencing and buried cable systems retain cost advantages for low-complexity perimeters under 200 meters.
Strategic Opportunities
- Canadian Wildlife Corridor Expansion:Parks Canada habitat connectivity mandates are creating demand for non-invasive boundary systems that permit large mammal passage while deterring human intrusion.
- EU CSRD Reporting Integration:Corporate sustainability disclosure requirements are positioning virtual fence deployments as biodiversity impact mitigation assets eligible for green financing.
- API-First Platform Architectures:Open integration frameworks are enabling security-as-a-service models where perimeter logic migrates between cloud and edge based on threat level.
Industry Challenges
- Multi-Sensor Calibration Expertise:Fusion of radar, LiDAR, and thermal signatures requires scarce field engineering talent capable of resolving interference patterns in heterogeneous terrain.
- Legacy PIDS Integration:Existing perimeter intrusion detection systems from the 2010s lack standardized data interfaces, forcing custom middleware development for each retrofit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Virtual Fence Market |
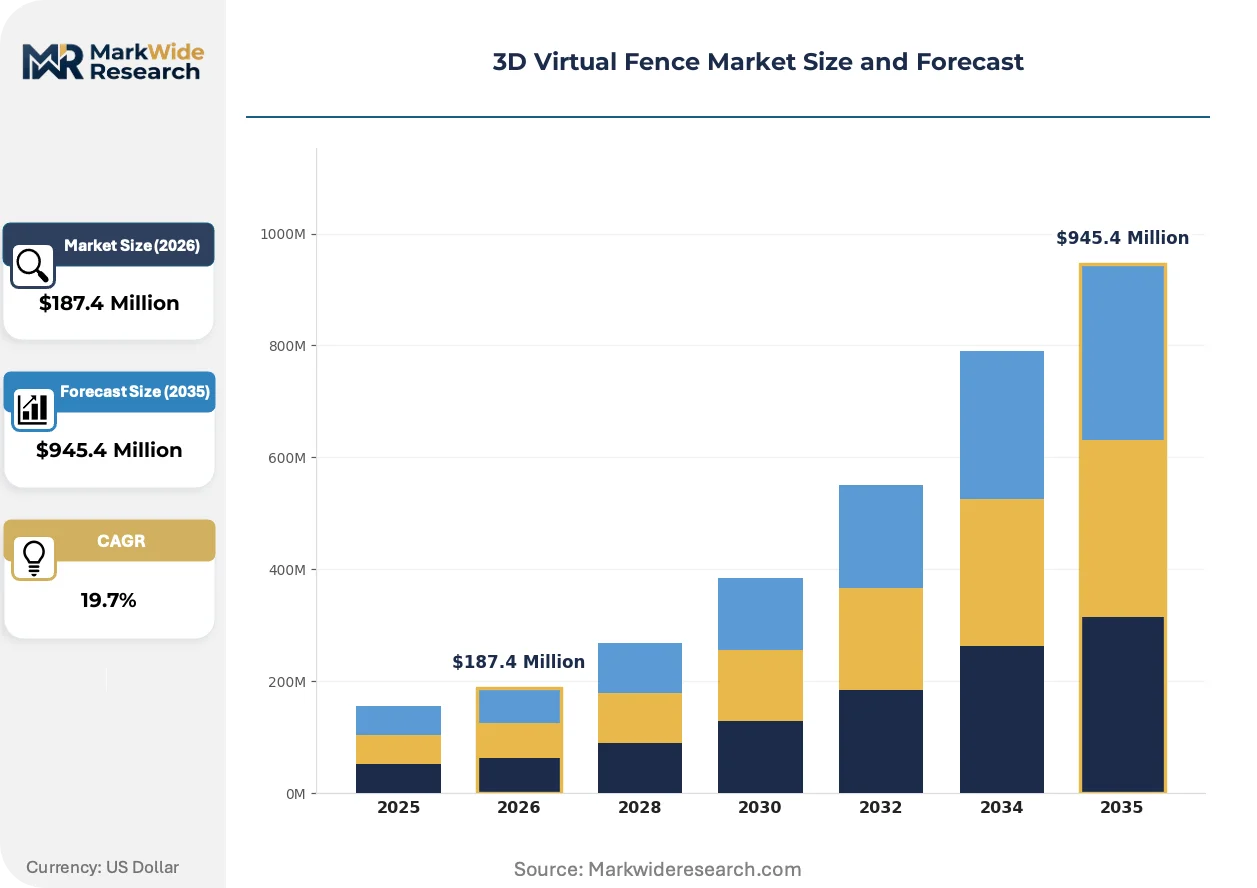
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Systems, Electric Fences, Virtual Barriers, Smart Fences Technology: GPS Tracking, RFID Technology, IoT Connectivity, Sensor Networks Application: Agriculture, Security, Wildlife Management, Residential Protection End User: Farmers, Homeowners, Security Agencies, Wildlife Conservationists |
| Companies Covered | Schneider Electric SE, Senstar Technologies Ltd., Controp Precision Technologies Ltd., G&A Surveillance, Huper Laboratories Co. Ltd., LIPS Corporation, RBtec Perimeter Security Systems, Agersens Pty Ltd, Avigilon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Virtual Fence Market Emerging Trajectories
Software-defined perimeter logic is decoupling detection hardware from alert generation, enabling zone reconfiguration without physical infrastructure modification and compressing deployment timelines for temporary security needs.
Millimeter-wave radar is migrating from automotive origins into perimeter security applications, where Texas energy facilities and California data centers are adopting 77-81 GHz frequency-modulated continuous-wave arrays for all-weather object tracking. The technology's immunity to fog, dust, and precipitation is displacing pure optical systems in coastal and desert environments where camera degradation previously demanded redundant sensor layers.
The EPA's habitat disturbance protocols are mandating wildlife impact assessments for any physical barrier exceeding 500 meters in protected zones, which is accelerating virtual fence adoption for conservation land management. Facilities subject to both FAA and EPA jurisdiction—particularly airports adjacent to wetlands—are converging on sensor fusion architectures that satisfy dual compliance requirements through single infrastructure investments.
California's data center operators are unbundling hardware procurement from integration services, treating perimeter detection as a subscription metric priced per monitored kilometer rather than capital equipment. This consumption-based purchasing is compressing vendor selection cycles and favoring providers with established energy management relationships who can bundle virtual fence deployment into broader facility automation contracts.
3D Virtual Fence Market Segmentation
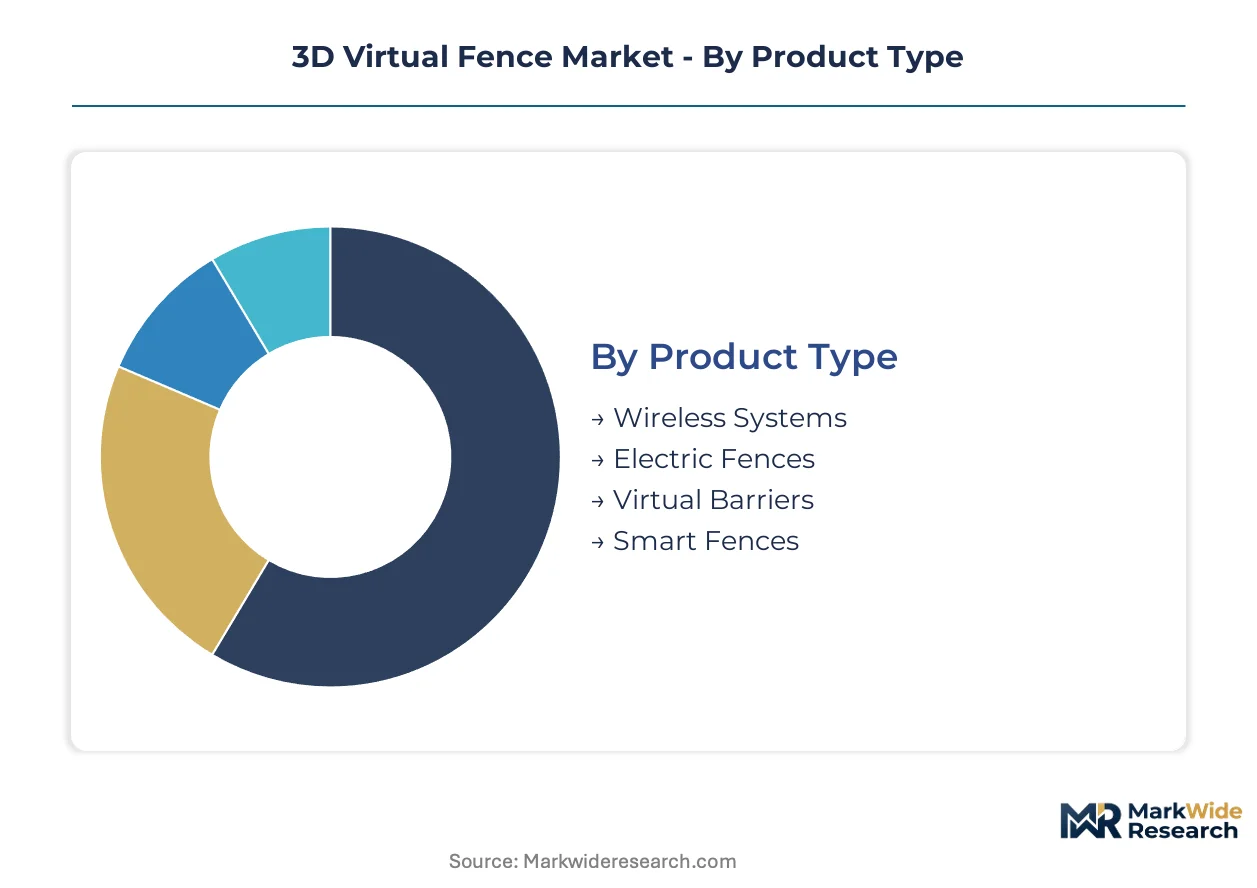
3D virtual fence procurement patterns diverge sharply between capital-intensive hardware buyers and service-oriented subscribers, with installation complexity driving aftermarket revenue toward parity with initial equipment sales. Segment boundaries blur as sensor fusion architectures compress hardware margins while elevating software and integration contracts as primary value capture mechanisms.
Product Type:
After-sales service intensity peaks where rapid deployment needs collide with harsh-environment durability requirements, creating recurring calibration and zone-reconfiguration revenue streams.
- Wireless Systems:Radio-frequency arrays with battery-backed mesh topology eliminate trenching costs and enable temporary perimeter establishment within hours. Demand concentrates in Texas energy corridor petrochemical facilities where hurricane-season mobility requirements override fixed infrastructure preferences.
- Smart Fences:Software-defined boundaries with API-first architectures permit remote zone reconfiguration without physical site visits. California data center operators treat these as subscription metrics priced per monitored kilometer, compressing vendor selection cycles and favoring providers with bundled facility automation contracts.
- Electric Fences:Electrified physical barriers with integrated voltage monitoring retain cost advantages for low-complexity perimeters under 200 meters.
- Virtual Barriers:Pure software geofences leveraging existing camera infrastructure serve livestock containment applications with minimal hardware augmentation.
By volume, Wireless Systems leads. By growth pace, Smart Fences is climbing the fastest.
Technology:
Cost tier stratification separates premium sensor fusion stacks from single-modality deployments, with edge-computing maturation compressing the performance gap between mid-tier and high-end configurations.
- Sensor Networks:Distributed LiDAR-radar-thermal fusion arrays with on-device inference capabilities eliminate cloud latency for intrusion classification. Texas Gulf Coast installations favor these for all-weather tracking immunity against fog and precipitation degradation.
- IoT Connectivity:Cellular and LoRaWAN backhaul with standardized MQTT protocols enables security-as-a-service models where perimeter logic migrates between cloud and edge based on threat level. EPA habitat disturbance protocols are accelerating adoption for wildlife corridor management where physical barriers face 500-meter assessment triggers.
- GPS Tracking:Satellite-based geofencing with sub-meter correction services serves extensive ranchland applications where terrain prohibits dense sensor deployment.
- RFID Technology:Passive and active tag systems with localized reader networks support high-certainty livestock identification at chokepoints.
By installed base, Sensor Networks dominates. By expansion trajectory, IoT Connectivity is gaining share fastest.
Application:
Customer type concentration varies by compliance burden intensity, with dual-jurisdiction facilities subject to both FAA and EPA mandates commanding premium sensor fusion deployments.
- Security:Critical infrastructure protection with FAA-mandated obstacle detection standards accelerates LiDAR-enabled procurement at airports and energy transmission corridors. California's data center corridor and Texas energy facilities drive sensor fusion requirements that outpace conventional barrier adoption.
- Wildlife Management:Non-invasive boundary systems permitting large mammal passage while deterring human intrusion satisfy Parks Canada habitat connectivity mandates and EPA wetland adjacency protocols.
- Agriculture:Livestock containment applications prioritize rapid deployment and software-defined zone reconfiguration for rotational grazing operations.
- Residential Protection:Homeowner deployments favor cost-optimized single-modality solutions with smartphone alert integration.
By revenue contribution, Security leads. By policy tailwinds, Wildlife Management is expanding most quickly.
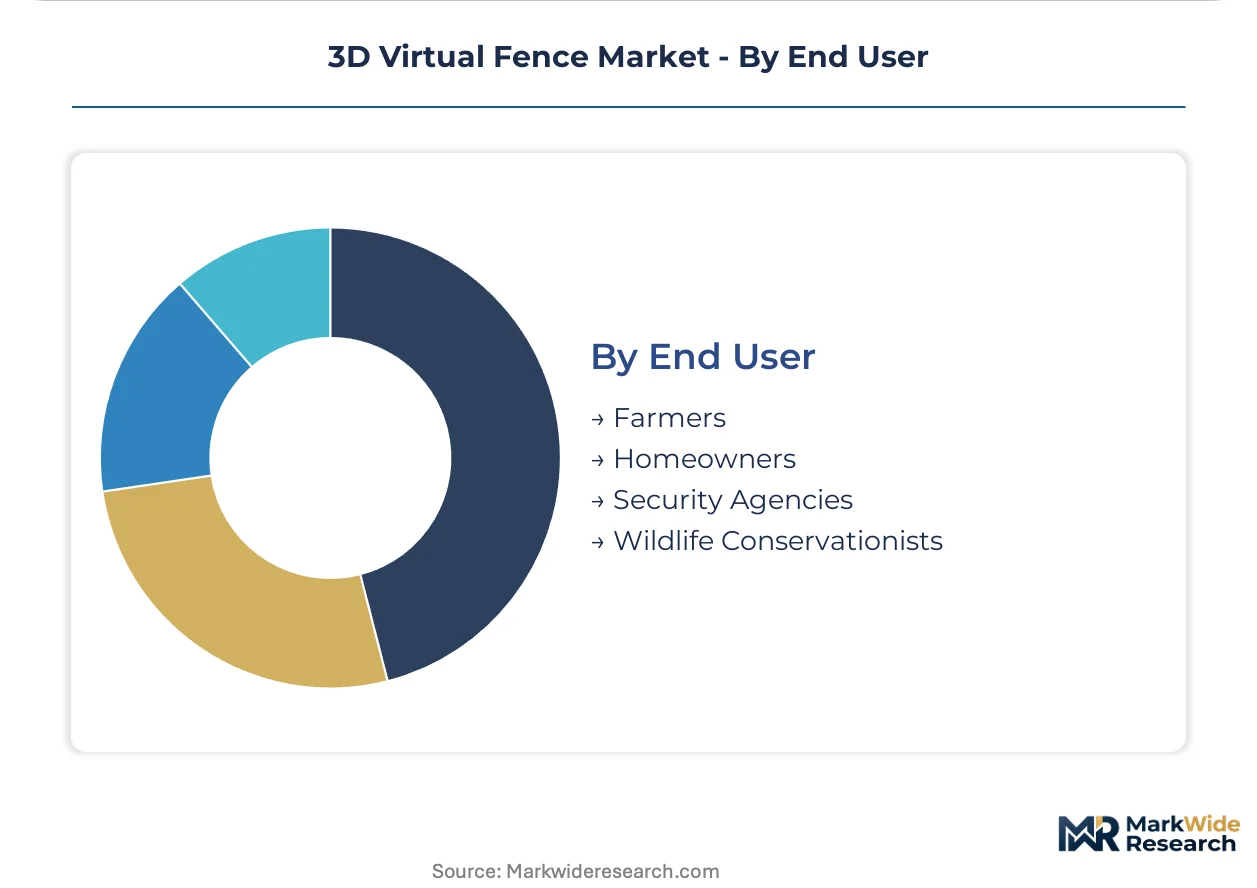
End User:
Procurement sophistication separates enterprise buyers with dedicated security engineering staff from consumer purchasers reliant on installer-channel recommendations.
- Security Agencies:Federal and municipal procurement with ISO 22311 business-continuity frameworks shapes perimeter resilience specifications. FAA guidelines for critical infrastructure protection drive IoT-enabled system expansion.
- Farmers:Agricultural operations with rotational grazing requirements prioritize wireless deployment speed and subscription-based pricing to match seasonal cash flow patterns.
- Wildlife Conservationists:Conservation land managers subject to EPA habitat disturbance protocols favor virtual fence adoption for assessments triggered at 500-meter physical barrier thresholds.
- Homeowners:Residential buyers with perimeter protection needs select from cost-optimized product tiers with minimal integration complexity.
By contract value, Security Agencies lead. By adoption velocity, Farmers are advancing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers absorb premium sensor fusion costs for FAA compliance, while agricultural purchasers in emerging markets prioritize rapid-deployment wireless systems with subscription pricing.
United States
Security agencies at federal and municipal levels drive procurement of IoT-enabled perimeter systems following FAA guidelines for critical infrastructure protection. California's data center corridor and Texas Gulf Coast energy facilities concentrate demand where sensor fusion requirements outpace conventional barrier adoption. CEQA compliance timelines for sensor pole installations extend deployment cycles by 18-24 months in the state's data center corridor.
Canada
Parks Canada habitat connectivity mandates create demand for non-invasive boundary systems that permit large mammal passage while deterring human intrusion. The country's national environmental regulator influences wildlife management deployments through habitat disturbance protocols. Conservation land managers favor virtual fence adoption for assessments triggered at 500-meter physical barrier thresholds in protected zones.
Germany
Industrial automation integrators bundle virtual fence deployments with broader facility automation contracts, leveraging existing building management relationships. EU CSRD reporting requirements position virtual fence deployments as biodiversity impact mitigation assets eligible for green financing. Manufacturing clusters in Bavaria and Baden-Württemberg prioritize API-first platform architectures enabling security-as-a-service models.
Australia
Extensive ranchland applications drive GPS tracking adoption where terrain prohibits dense sensor deployment. The country's national agricultural regulator shapes livestock containment standards for rotational grazing operations. Queensland and New South Wales pastoral operations prioritize wireless deployment speed and subscription-based pricing to match seasonal cash flow patterns.
China
Data center operators in the Yangtze River Delta and Pearl River Delta regions unbundle hardware procurement from integration services, treating perimeter detection as a consumption-based metric. The country's national standards administration influences technical specifications for sensor network interoperability. Beijing-Tianjin-Hebei corridor facilities adopt millimeter-wave radar arrays for all-weather object tracking in high-pollution environments.
3D Virtual Fence Market Vendor Landscape
Building automation conglomerates and perimeter security specialists split the market along integration-versus-specialization lines. The vendor base organizes into three strategic archetypes: diversified industrial technology groups with bundled service capabilities, pure-play perimeter security developers with deep video analytics expertise, and ruggedized hardware fabricators with harsh-environment manufacturing scale. Competitive moves center on strategic partnerships with facility automation providers and geographic expansion through regional system integrator networks.
Within the diversified technology tier, Schneider Electric SE and Senstar Technologies Ltd. anchor contrasting strategic positions. Schneider Electric SE exemplifies the building automation bundling archetype, leveraging energy management contract relationships to embed virtual fence deployments within broader facility infrastructure programs. Senstar Technologies Ltd. occupies the specialized perimeter detection position, with its corporate structure signaling dedicated focus on video analytics for intrusion detection applications. RBtec Perimeter Security Systems sits within the ruggedized manufacturing segment, with its company name indicating scale-oriented production of sensor housings for demanding installation environments.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Senstar Technologies Ltd. |
| Controp Precision Technologies Ltd. |
| G&A Surveillance |
| Huper Laboratories Co. Ltd. |
| LIPS Corporation |
| RBtec Perimeter Security Systems |
| Agersens Pty Ltd |
| Avigilon Corporation |
| Others |
Supply Flow & Price Mechanics
East Asian semiconductor freight corridors govern cost dynamics across the 3D virtual fence value chain, with photonics-grade substrate logistics amplifying hardware margin pressure while installation complexity elevates after-sales service pricing power against capital equipment commoditization.
Pricing Analysis
After-sales service contracts now command lifetime value parity with initial hardware sales as calibration complexity rises. Three-tier pricing structure across premium sensor fusion, standard single-modality, and economy retrofit configurations stratifies by integration depth and FAA certification tier. Cost compression in mid-tier hardware intensifies because edge-computing maturation reduces cloud dependency premiums. Agricultural buyers in Australia and Texas exhibit highest price sensitivity, while dual-jurisdiction facilities subject to FAA and EPA mandates absorb premium sensor fusion costs without volume negotiation.
Supply Chain Analysis
Photonics-grade indium phosphide substrates draw from concentrated foundry capacity in Taiwan, South Korea, and Japan. LiDAR emitters, millimeter-wave radar modules, and edge-computing chipsets rest on East Asian semiconductor fabrication with limited alternative sourcing. Single-source vulnerability in photonics-grade substrate supply creates procurement risk for North American system integrators. Distribution runs through building automation conglomerates and regional security integrators rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D virtual fence market exhibits cyclical recovery characteristics as FAA infrastructure mandates and EPA habitat protocols create synchronized procurement waves across security and conservation applications.
For Market Incumbents: Build switching-cost moats through API-first platform architectures that embed calibration expertise into subscription contracts. Deepen software-defined perimeter logic investments to compress hardware replacement cycles. Counter emerging pure-play video analytics specialists by acquiring field engineering talent capable of resolving multi-sensor interference patterns in heterogeneous terrain.
For New Entrants and Emerging Players: Pursue Canadian wildlife corridor deployments where Parks Canada habitat connectivity mandates outpace incumbent coverage. Target Australian pastoral operations with GPS-tracking subscription models priced to match seasonal cash flow patterns. Lead with rapid-deployment wireless mesh systems that eliminate trenching costs and CEQA compliance timelines.
For Investors and Strategic Acquirers: Edge-computing module developers with FAA certification pathways represent the most defensible acquisition archetype for long-term positioning. Monitor CSRD biodiversity disclosure adoption rates across EU industrial facilities as the signal indicating green financing eligibility for virtual fence deployments. Infrastructure software specialists with existing energy management relationships offer the cleanest bundling synergies.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Enables security-as-a-service models where perimeter logic migrates between cloud and edge based on threat level. |
| Sensor Fusion Patent Portfolio Expansion | Protects LiDAR-radar-thermal integration architectures from automotive technology transfer competitors. |
| Regional System Integrator Acquisition | Accelerates Texas energy corridor and California data center penetration through established facility automation relationships. |
| FAA Certification Fast-Track Investment | Positions obstacle detection systems for airspace-critical infrastructure procurement cycles. |
| Wildlife Corridor Pilot Program Deployment | Generates EPA-compliant case studies for conservation land managers facing 500-meter physical barrier assessment triggers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA regulatory filings, EPA habitat disturbance protocols, and ISO 22311 business-continuity frameworks. Primary interviews with perimeter security engineering directors, building automation procurement leads, conservation land managers, and petrochemical facility security officers combined with customs trade data and SEC 10-K equipment disclosures. Bottom-up sensor deployment estimates and top-down infrastructure spending projections triangulate market sizing.
Forecast inputs include technology adoption curves across wireless mesh, smart fence, and sensor network product types; regulatory compliance timelines for CEQA and FAA mandates; and edge-computing cost reduction trajectories. Segmentation dimensions span product architecture, detection modality, application compliance burden, and end-user procurement sophistication. CAGRs derive from fitted technology diffusion curves applied to infrastructure replacement cycles and policy-driven procurement windows.
Sensitivities concentrate around indium phosphide supply disruptions, CEQA timeline extensions beyond current 18-24 month baselines, and cybersecurity mandate convergence with physical security procurement specifications. Cross-checking against FAA critical infrastructure grant disbursement rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market