
 North America Obsessive-Compulsive Disorder (OCD) Drugs Market | 2026-2036
North America Obsessive-Compulsive Disorder (OCD) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Obsessive-Compulsive Disorder (OCD) Drugs Market Analytics
Serotonin reuptake inhibition chemistry is shifting from legacy small-molecule platforms toward precision-targeted neurotransmitter modulators, altering cost structures for chronic therapy programs. Pfizer Inc leverages its established CNS manufacturing footprint to sustain bulk supply contracts across hospital networks. Eli Lilly and Company anchors its position through deep psychiatric R&D pipelines. AbbVie Inc differentiates via immunology-neuroscience crossover capabilities.
Obsessive-Compulsive Disorder drugs comprise psychopharmacological agents designed to modulate serotonergic and dopaminergic pathways, with SSRI formulations typically requiring four to twelve weeks for therapeutic onset and dosage titration protocols calibrated by patient metabolizer status. These therapeutics serve to reduce intrusive thought frequency and compulsive ritual behaviors in diagnosed patient populations. The SSRI product category dominates prescription volumes due to established efficacy profiles and generic availability, while the antipsychotic segment captures augmentation therapy margins where SSRI monotherapy fails. Oral delivery mode leads dispensation patterns across hospital and clinic settings, though intravenous formulations are gaining traction in treatment-resistant subpopulations requiring supervised administration.
The FDA maintains stringent psychiatric drug approval standards through its Division of Psychiatry Products, while Health Canada's Therapeutic Products Directorate enforces parallel safety benchmarks that shape cross-border formulation strategies. State-level Medicaid formularies in the United States and provincial drug benefit programs in Canada directly influence physician prescribing behavior and patient access tiers. Stakeholders must monitor evolving FDA guidance on digital therapeutics adjuncts and provincial reimbursement shifts to anticipate competitive positioning requirements.
Market Dynamics
Precision-targeted neurotransmitter modulators are displacing legacy SSRI platforms, forcing manufacturers to restructure chronic therapy cost models and realign clinical trial endpoints toward rapid onset metrics rather than traditional eight-week efficacy windows.
Growth Catalysts
- FDA Accelerated Approval Pathways:Psychiatric drug development timelines compress as the Division of Psychiatry Products prioritizes novel mechanisms for treatment-resistant populations, enabling faster market entry for glutamate-targeting candidates.
- Specialty Clinic Expansion:Academic medical centers in Boston, New York, and Toronto are scaling dedicated OCD treatment protocols, creating concentrated demand hubs for augmentation therapies beyond first-line SSRI regimens.
- Pharmacogenomic Integration:CYP2D6 and CYP2C19 metabolizer testing is embedding into titration protocols, reducing adverse event rates and improving adherence curves for chronic psychiatric management.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Serotonin reuptake inhibitor raw material supply clusters in Indian and Chinese contract manufacturing organizations, exposing formulation sponsors to geopolitical supply interruptions and quality consistency variance.
- Medicaid Formulary Rigidity:State-level prior authorization requirements for branded psychiatric agents create 14-21 day access delays, pushing prescribers toward generic fluoxetine and sertraline defaults regardless of individual patient metabolizer profiles.
- Treatment Resistance Ceiling:Approximately 40% of diagnosed patients fail SSRI monotherapy, yet approved augmentation options remain limited to atypical antipsychotics with metabolic side effect burdens that compromise long-term adherence.
Strategic Opportunities
- Intravenous Formulation Development:Supervised administration protocols for treatment-resistant subpopulations open premium pricing tiers within hospital outpatient departments, bypassing retail pharmacy reimbursement friction.
- Digital Therapeutic Adjuncts:FDA breakthrough device designation pathways for cognitive behavioral therapy apps create combination product opportunities that extend drug patent protection through method-of-treatment claims.
- Provincial Realignment in Canada:Ontario and British Columbia drug benefit programs are expanding coverage for obsessive-compulsive disorder under mental health parity mandates, reducing out-of-pocket barriers in previously underpenetrated provincial markets.
Industry Challenges
- Psychiatric Trial Recruitment Bottlenecks:Placebo response rates in OCD studies run 25-35%, inflating required enrollment numbers and extending Phase III durations beyond typical CNS development timelines.
- Legacy Manufacturing Retooling Costs:Transitioning from small-molecule batch synthesis to biologic-precision modulators demands nine-figure capital deployment for C-suite sponsors with existing SSRI infrastructure commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Obsessive-Compulsive Disorder (OCD) Drugs Market |
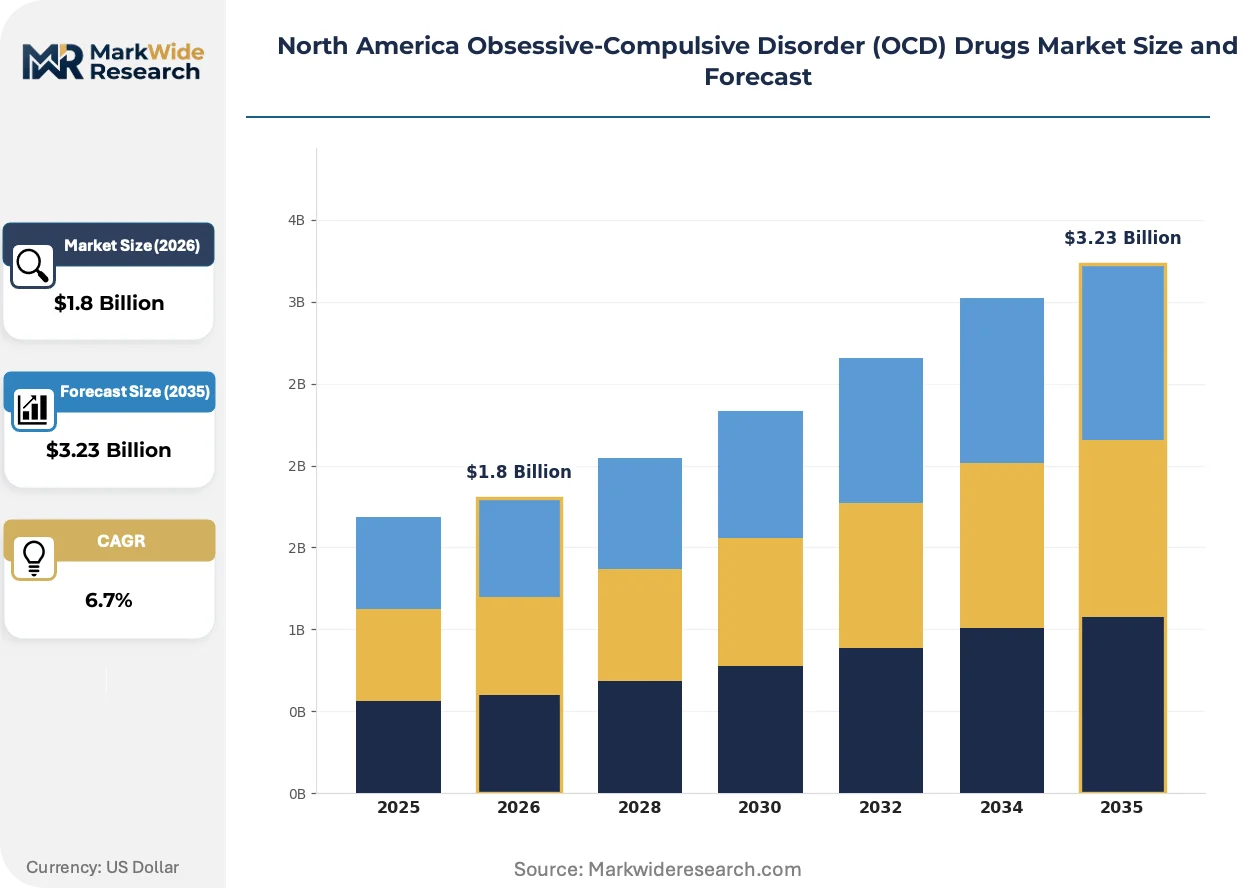
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Benzodiazepines, Antipsychotics Indication: Pure Obsessional, Contamination, Checking, Hoarding Delivery Mode: Oral, Intravenous, Topical, Injectable End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | Pfizer Inc, Eli Lilly and Company, AbbVie Inc, GlaxoSmithKline plc, H. Lundbeck A/S, Johnson & Johnson Services, Inc., Viatris Inc., Abbott, Sebela Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Obsessive-Compulsive Disorder (OCD) Drugs Market Evolving Landscape
Neuroscience-immunology crossover research is unlocking novel target classes, while regulatory frameworks adapt to evaluate digital-therapeutic combinations and real-world evidence supplants traditional placebo-controlled endpoints in payer negotiations.
Ketamine-derived rapid-acting antidepressant mechanisms are converging with obsessive-compulsive disorder indication expansion, with intranasal esketamine protocols now penetrating academic medical center outpatient psychiatry departments at accelerating pace. Treatment-resistant patient cohorts in the United States and Canada are accessing supervised infusion networks that bypass traditional SSRI titration delays, compressing the competitive window for novel oral mechanisms to demonstrate non-inferiority against rapid-onset alternatives.
Health Canada's Therapeutic Products Directorate is harmonizing psychiatric safety benchmarks with FDA Division of Psychiatry Products standards, enabling simultaneous New Drug Submission and New Drug Application filings that reduce cross-border launch gaps from 18-24 months to 6-12 months. Manufacturers with existing Canadian regulatory affairs infrastructure capture first-mover advantage in provincial formulary negotiations, while late entrants face established reference pricing and step-therapy requirements that favor incumbent SSRI generics.
Patient advocacy organizations are consolidating purchasing influence through direct-to-manufacturer contracting for rare disease subpopulations, bypassing traditional pharmacy benefit manager channels in the United States. These concentrated demand pools in major metropolitan treatment hubs negotiate outcome-based access agreements that tie reimbursement to Yale-Brown Obsessive Compulsive Scale response thresholds, shifting financial risk from payers to sponsors and compressing net revenue realization timelines for novel agents.
North America Obsessive-Compulsive Disorder (OCD) Drugs Market Segmentation
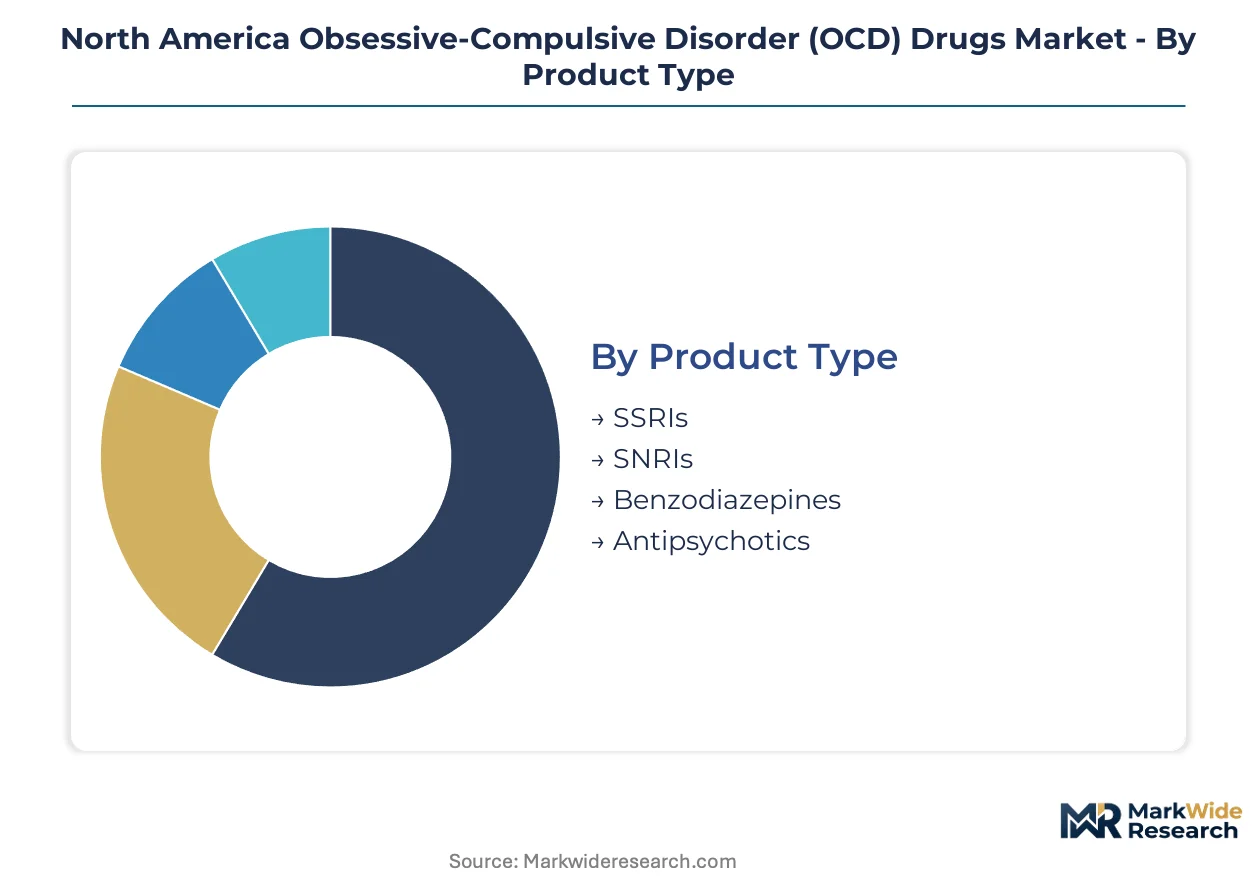
Segmentation across the North America OCD Drugs Market reveals distinct prescribing hierarchies shaped by FDA approval pathways, provincial reimbursement tiers, and metabolizer-guided titration protocols. Manufacturers align portfolio investments against these category boundaries to capture volume in academic medical centers and specialty clinic networks.
Product Type:
The customization-vs-standardization spectrum runs from generic-first-line SSRIs to precision-targeted antipsychotic augmentation, with cost structures and clinical positioning diverging sharply across this axis.
- SSRIs:Selective serotonin reuptake inhibitors constitute the foundational pharmacological class, with fluoxetine and sertraline dominating prescription volumes through established efficacy profiles and deep generic penetration. Demand concentrates in Medicaid-covered populations across Texas, Florida, and California state formularies, where prior authorization friction pushes prescribers toward these defaults despite pharmacogenomic mismatches in poor metabolizers.
- Antipsychotics:Atypical antipsychotic augmentation therapies command premium pricing tiers where SSRI monotherapy fails, with risperidone and aripiprazole protocols penetrating academic medical centers in Boston and New York. Metabolic side effect burdens limit long-term adherence, creating openings for novel glutamate-targeting mechanisms in treatment-resistant cohorts.
- SNRIs:Serotonin-norepinephrine reuptake inhibitors offer dual-mechanism coverage for comorbid anxiety presentations, with venlafaxine XR capturing share in Canadian provincial formularies where Health Canada has expanded mental health parity coverage.
- Benzodiazepines:Short-term anxiolytic adjuncts face prescribing scrutiny under FDA boxed warning protocols for dependence, relegating these agents to acute crisis management rather than chronic OCD maintenance.
Leading the category by volume: SSRIs. Growing fastest: Antipsychotics.
Indication:
Cost tier stratification separates resource-intensive contamination protocols from streamlined pure obsessional management, with reimbursement complexity scaling alongside behavioral intervention requirements.
- Contamination:Washing and cleaning rituals drive the most intensive therapeutic resource allocation, with exposure-response prevention protocols requiring supervised administration settings. Academic medical centers in Toronto and Los Angeles anchor demand for augmentation therapies in severe cases where contamination fears compromise occupational function.
- Checking:Repeated verification behaviors—locks, appliances, safety systems—create chronic disability profiles that sustain long-term SSRI adherence and drive step-therapy escalation to antipsychotic combinations. Demand clusters in urban corridor treatment hubs where cognitive-behavioral therapy integration is standard of care.
- Pure Obsessional:Intrusive thought presentations without overt compulsions present diagnostic complexity that delays pharmacological intervention, with patients cycling through multiple SSRI trials before appropriate dosing.
- Hoarding:Accumulation behaviors increasingly recognized as distinct phenotypic presentation, with specialized clinic protocols in New York and Vancouver developing multimodal interventions beyond standard serotonergic modulation.
Contamination indications command the highest per-patient therapeutic investment. Hoarding presentations are gaining recognition fastest among subtypes.
Delivery Mode:
Margin structures diverge across administration settings, with supervised intravenous protocols capturing hospital outpatient department premiums versus retail pharmacy oral dispensing.
- Oral:Tablet and capsule formulations dominate dispensation patterns across all prescriber settings, with once-daily dosing improving adherence curves in chronic management. Generic fluoxetine and sertraline saturate retail pharmacy channels, compressing branded oral mechanism pricing power.
- Intravenous:Supervised infusion protocols for treatment-resistant subpopulations bypass prior authorization friction through hospital outpatient billing codes, with ketamine-derived mechanisms penetrating academic medical center psychiatry departments at accelerating pace.
- Injectable:Long-acting antipsychotic depot formulations address adherence gaps in severe augmentation cases, though OCD-specific labeling remains limited relative to schizophrenia indications.
- Topical:Transdermal delivery mechanisms remain investigational for psychiatric indications, with no approved OCD-specific topical products in FDA or Health Canada registries.
Oral delivery maintains volume leadership. Intravenous administration is climbing the fastest as academic centers expand supervised infusion networks.
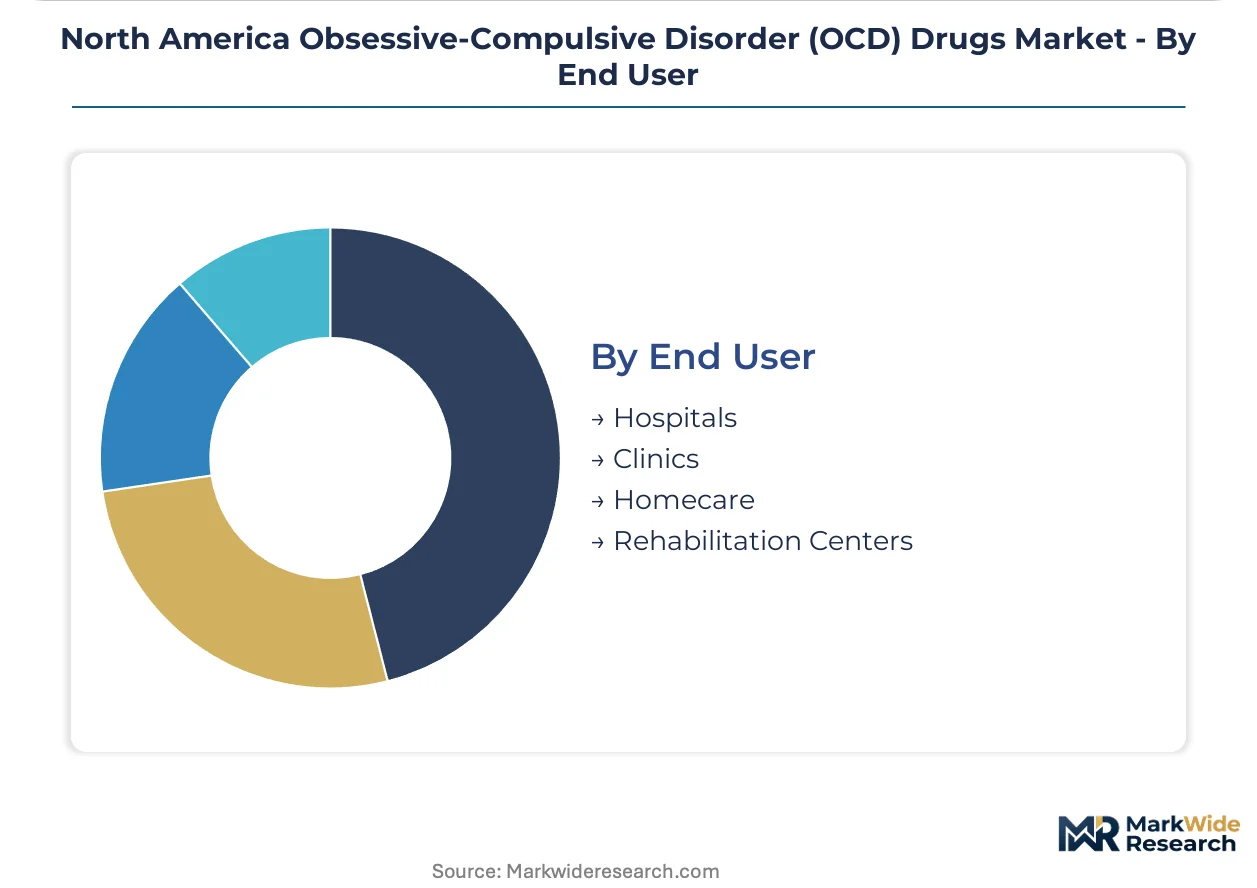
End User:
Customer type segmentation maps to reimbursement pathway complexity, with institutional purchasers leveraging formulary control versus fragmented homecare prescribing.
- Hospitals:Inpatient psychiatry units and emergency departments anchor acute stabilization protocols, with 72-hour hold regulations in California and New York state law driving admission volumes for severe OCD crisis presentations. Hospital formularies prioritize generic SSRI availability with restricted antipsychotic augmentation tiers.
- Clinics:Outpatient specialty psychiatric practices concentrate in Boston, New York, and Toronto metropolitan corridors, where dedicated OCD treatment protocols drive demand for novel mechanisms and pharmacogenomic-guided titration services.
- Rehabilitation Centers:Residential behavioral health facilities integrate medication management with intensive exposure therapy, capturing patients with functional impairment requiring structured environments.
- Homecare:Telepsychiatry expansion post-pandemic has shifted maintenance prescribing into home settings, though controlled substance regulations limit benzodiazepine dispensing through remote channels.
Clinics lead prescription volume through chronic disease management. Hospital-based supervised administration is gaining share fastest among end user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty psychiatric clinic networks concentrate demand in major metropolitan corridors across the United States and Canada, with academic medical centers in Boston, New York, and Toronto anchoring treatment-resistant patient volumes and driving uptake of novel augmentation therapies.
United States
Medicaid formulary structures in Texas, Florida, and California shape prescribing defaults toward generic SSRIs despite pharmacogenomic mismatches. The FDA Division of Psychiatry Products maintains stringent approval benchmarks for novel mechanisms. The New York-Boston corridor hosts the densest concentration of dedicated OCD treatment protocols, with academic medical centers pioneering ketamine-derived supervised infusion networks.
Canada
Ontario and British Columbia drug benefit programs are expanding obsessive-compulsive disorder coverage under mental health parity mandates. Health Canada's Therapeutic Products Directorate harmonizes safety benchmarks with FDA standards, compressing cross-border launch gaps. Toronto's specialty clinic network anchors national demand for augmentation therapies beyond first-line serotonergic regimens.
California
State-level 72-hour psychiatric hold regulations drive inpatient admission volumes for severe OCD crisis presentations. California Medicaid formulary tiers prioritize generic fluoxetine and sertraline availability with restricted antipsychotic augmentation access. Los Angeles academic medical centers concentrate demand for exposure-response prevention protocols in contamination-predominant subtypes.
New York
Commercial insurance density in the New York metropolitan area supports premium-tier branded psychiatric agent access. State Medicaid prior authorization requirements create 14-21 day delays for non-generic therapies. Manhattan and Brooklyn specialty psychiatric practices concentrate pharmacogenomic-guided titration services and novel mechanism trials.
Massachusetts
Massachusetts General Hospital and affiliated academic centers anchor the highest per-capita density of OCD specialty treatment protocols in the United States. State-level mental health parity enforcement exceeds federal baseline requirements. The Greater Boston corridor drives national demand for treatment-resistant cohort management and augmentation therapy development programs.
North America Obsessive-Compulsive Disorder (OCD) Drugs Market Competitive Landscape
Portfolio diversification dominates the current landscape as established CNS manufacturers restructure chronic therapy cost models around precision-targeted mechanisms. The market exhibits tiered concentration with large-cap pharmaceutical sponsors, mid-cap neuroscience specialists, and generic manufacturers occupying distinct competitive positions. Three archetypes define positioning: legacy SSRI infrastructure holders, immunology-neuroscience crossover developers, and rapid-onset mechanism pioneers. M&A activity and strategic partnerships concentrate around glutamate-targeting candidates and digital therapeutic adjunct combinations.
Among large-cap CNS infrastructure holders, Pfizer Inc and Eli Lilly and Company exemplify divergent strategic postures. Pfizer leverages established manufacturing footprints to sustain bulk supply contracts across hospital networks, while Eli Lilly anchors position through deep psychiatric R&D pipelines. AbbVie Inc occupies a distinct tier representing immunology-neuroscience crossover capabilities that differentiate augmentation therapy positioning.
| Leading Market Players |
|---|
| Pfizer Inc |
| Eli Lilly and Company |
| AbbVie Inc |
| GlaxoSmithKline plc |
| H. Lundbeck A/S |
| Johnson & Johnson Services, Inc. |
| Viatris Inc. |
| Abbott |
| Sebela Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Pharmacogenomic testing specialists concentrated in Boston and Toronto create labor-cost differentials that widen pricing-tier spreads between metabolizer-guided precision protocols and standard-of-care SSRI defaults across Medicaid formularies.
Pricing Analysis
Volume concentrates in generic SSRI tiers while margins cluster in antipsychotic augmentation and intravenous supervised administration. Pricing stratifies across premium, standard, and economy tiers based on FDA approval pathway complexity and provincial reimbursement status. Price erosion runs through first-line oral generics as state Medicaid formularies tighten prior authorization requirements. Academic medical centers show lowest price sensitivity; retail pharmacy channels for maintenance therapy show highest.
Supply Chain Analysis
FDA current Good Manufacturing Practice certification and Health Canada ICH Q7 compliance gate active pharmaceutical ingredient sourcing for serotonin reuptake inhibitor precursors. Supply concentrates in Indian and Chinese contract manufacturing organizations for raw materials, with finished formulation capacity anchored in the United States and Canada. The chain draws from specialized chemical precursors, excipient blends, and packaging components. Single-source vulnerability persists for CYP2D6 pharmacogenomic assay kits. Distribution runs through hospital procurement networks, specialty clinic direct purchasing, and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over pharmacogenomic testing infrastructure determines formulary positioning and pricing power across treatment-resistant patient cohorts.
For Market Incumbents: Deploy captive pharmacogenomic laboratory partnerships to lock in metabolizer-guided titration protocols before provincial formularies mandate testing. Consolidate exposure-response prevention clinic networks in Toronto and Los Angeles to capture contamination-predominant patient flows. Counter generic SSRI erosion by embedding digital therapeutic adjuncts into method-of-treatment patent extensions. For New Entrants and Emerging Players: Glutamate-targeting rapid-onset mechanisms offer technology-first wedge positioning against legacy SSRI infrastructure. Penetrate hospital outpatient department infusion networks where prior authorization friction is lowest. Target Canadian provincial markets under mental health parity expansion with esketamine-class supervised administration protocols. Build go-to-market through academic medical center psychiatry departments rather than retail pharmacy channels. For Investors and Strategic Acquirers: Re-rating potential sits with immunology-neuroscience crossover developers given FDA breakthrough therapy designation momentum for novel mechanism psychiatric agents. Five-to-ten year viability favors sponsors with existing Health Canada regulatory infrastructure and simultaneous New Drug Submission capability. Watch Health Canada-FDA harmonization progress as inflection signal for cross-border launch gap compression.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Laboratory Partnership | Captures metabolizer-guided titration revenue streams across Massachusetts and Ontario clinic networks. |
| Intravenous Formulation Development | Bypasses retail pharmacy reimbursement friction through hospital outpatient billing codes in academic centers. |
| Digital Therapeutic Adjunct Integration | Extends patent protection via FDA breakthrough device designation for cognitive behavioral therapy apps. |
| Provincial Formulary Pre-Positioning | Secures first-mover advantage in Ontario and British Columbia mental health parity expansion windows. |
| Supervised Infusion Network Expansion | Captures treatment-resistant patient volumes in New York-Boston corridor academic medical centers. |
Research Methodology
Document review covered FDA Division of Psychiatry Products guidance documents, Health Canada Therapeutic Products Directorate filings, and ClinicalTrials.gov protocol registrations, complemented by interviews with drug development executives at CNS-focused pharmaceutical sponsors, regulatory affairs leads managing cross-border submissions, formulary directors at state Medicaid agencies and provincial drug benefit programs, and hospital procurement managers overseeing psychiatry department formularies. Secondary validation drew from FDA Orange Book entries, Health Canada Drug Product Database records, and academic medical center clinical trial announcements. Bottom-up prescription volume modeling and top-down market sizing triangulated against manufacturer-reported therapeutic category revenues.
Cross-referencing historical approval timelines against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions included product type, indication subtype, delivery mode, and end-user setting, with additional modeling for treatment line positioning and regional regulatory cluster. CAGRs derived from weighted regression against baseline prevalence estimates and projected treatment rate expansion. Forecast inputs incorporated pharmacogenomic testing penetration curves and provincial mental health parity implementation schedules.
Several conditions sit outside the modeled scope, including potential FDA guidance revisions on digital therapeutics, unforeseen geopolitical disruption to Indian and Chinese API supply, and shifts in commercial insurance coverage for augmentation therapies. Forecasts reflect assumptions about regulatory pathway stability and reimbursement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Italy Healthcare Market