
 Oral Antibiotics Market | 2026-2036
Oral Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Antibiotics Market Analysis
Hospital procurement networks is rewriting how oral antibiotics reach end users, with centralized tender systems displacing fragmented wholesale channels. Pfizer Inc. leverages its hospital formulary relationships to sustain volume across infectious disease therapy areas. Sun Pharmaceutical Industries Ltd. anchors the generic amoxicillin segment through manufacturing scale in regulated markets. Teva Pharmaceutical Industries Ltd. competes on capsule and suspension portfolios across European pharmacy chains.
Oral antibiotics constitute systemically absorbed antimicrobial agents formulated for gastrointestinal administration, typically achieving therapeutic plasma concentrations within one to two hours post-ingestion to eradicate bacterial pathogens or suppress their replication. These agents serve as first-line interventions for community-acquired respiratory infections, skin and soft tissue infections, and dental abscesses where intravenous therapy is clinically unnecessary or logistically impractical. The therapy area dimension shows respiratory infections commanding the largest patient volume, while infectious disease protocols are expanding fastest as stewardship programs narrow spectrum selection. Tablet formulations occupy the dominant share of manufacturing output, though suspension demand rises in pediatric and geriatric home care settings where swallowing difficulties limit solid-dose adherence.
The FDA's qualified infectious disease product designation accelerates review timelines for novel oral antibiotics targeting resistant pathogens, while the EMA's antimicrobial resistance strategy tightens environmental discharge standards for manufacturing effluent. India's CDSCO mandates bioequivalence documentation for generic oral antibiotic approvals, filtering substandard entrants from pharmacy shelves. Stakeholders must monitor how antimicrobial stewardship mandates in hospital formularies reshape demand toward narrow-spectrum oral agents over broad-spectrum alternatives.
Market Dynamics
Hospital formulary centralization is compressing manufacturer margins as procurement networks consolidate purchasing authority across integrated delivery networks, displacing fragmented wholesale relationships that historically buffered price volatility.
Growth Catalysts
- Outpatient parenteral-to-oral conversion protocols:Hospital systems in the United States are expanding step-down therapy programs that discharge patients on oral regimens, pulling volume from intravenous infusion centers into retail pharmacy channels.
- FDA qualified infectious disease product designation:Streamlined review timelines for novel agents targeting resistant pathogens are accelerating pipeline progression for manufacturers with anti-microbial development capabilities.
- India's hospital tender expansion:Cost-driven procurement by state government medical colleges and district hospitals is concentrating volume among domestic generic manufacturers with scale advantages in regulated export markets.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of beta-lactam intermediates concentrates in Zhejiang and Jiangsu provinces of China, exposing formulators to single-source disruption risk during environmental compliance inspections.
- Antimicrobial stewardship mandates:Joint Commission accreditation standards for U.S. hospitals now require prospective audit and feedback programs that restrict broad-spectrum oral prescribing, compressing volume for legacy agents.
- Generic substitution ceilings:Pharmacokinetic bioequivalence requirements for narrow therapeutic index antibiotics create technical barriers to interchangeable generic entry for certain macrolide and fluoroquinolone formulations.
Strategic Opportunities
- Pediatric suspension home care:Geriatric swallowing difficulties and pediatric compliance requirements are expanding demand for liquid oral formulations in Japan's aging-in-place healthcare infrastructure.
- EMA environmental discharge standards:Tightening manufacturing effluent limits for antibiotic residues are creating first-mover advantages for European facilities with advanced biodegradation capabilities.
- Direct-to-hospital distribution platforms:Digital procurement exchanges in Germany are disintermediating traditional pharmaceutical wholesalers, enabling manufacturers to capture margin through contracted direct fulfillment.
Industry Challenges
- Stewardship program integration:Hospital pharmacy information systems require costly middleware development to embed real-time spectrum guidance at the point of prescribing decision.
- Multi-jurisdiction bioequivalence documentation:Divergent reference product requirements across CDSCO, FDA, and EMA filing pathways extend regulatory approval timelines for generic developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Antibiotics Market |
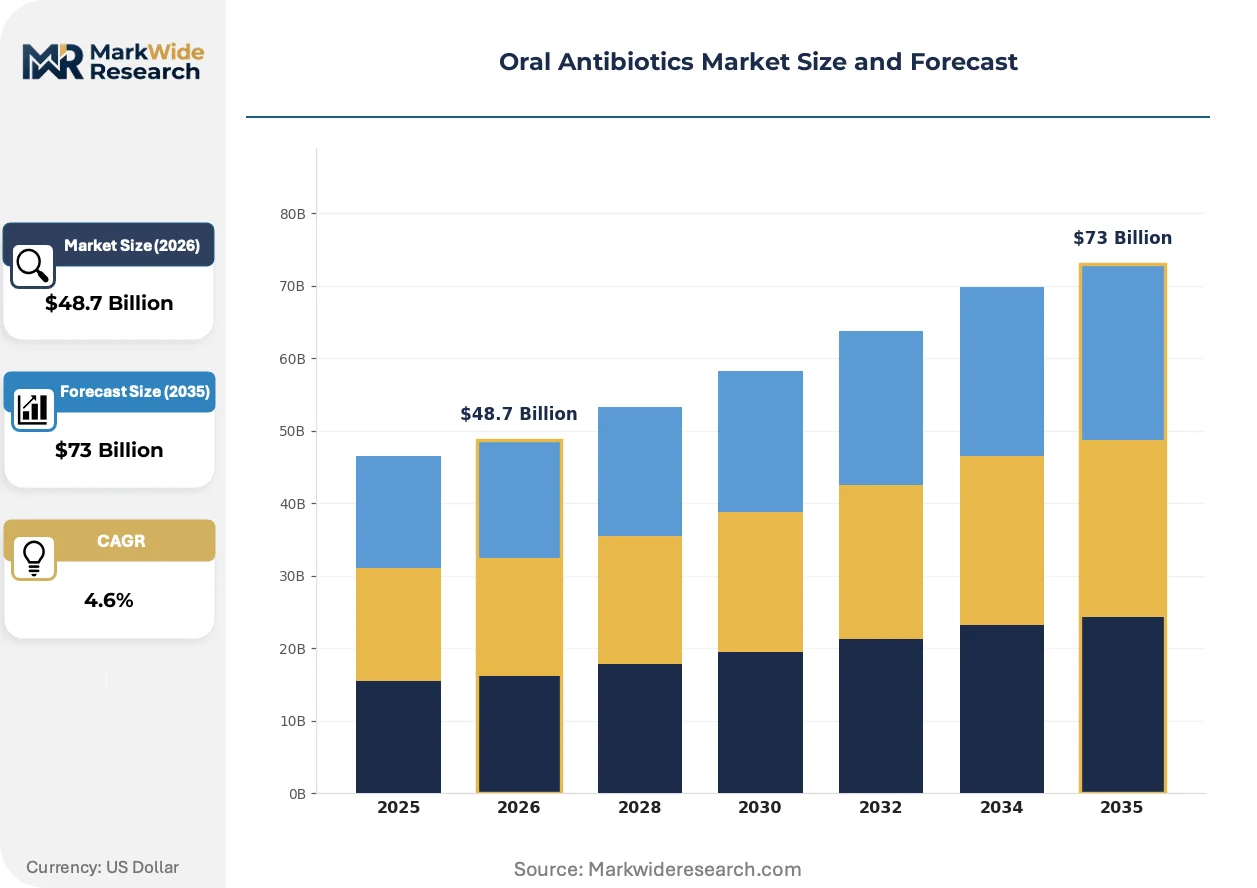
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ampicillin, Amoxicillin, Cephalexin, Clindamycin Therapy Area: Infectious Diseases, Respiratory Infections, Skin Infections, Dental Infections End User: Hospitals, Clinics, Pharmacies, Home Care Formulation: Tablet, Capsule, Suspension, Powder |
| Companies Covered | Pfizer Inc., GSK plc., Abbott Laboratories, Merck & Co., Inc., Novartis AG, Sanofi, Bayer AG, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Antibiotics Market Emerging Trajectories
Digital therapeutics integration and manufacturing process intensification are reconfiguring how oral antibiotics are developed, produced, and clinically deployed across acute and ambulatory settings.
Pharmacokinetic modeling software is virtualizing traditional in-vivo bioequivalence study requirements for certain oral antibiotic classes. Generic developers in India are adopting physiologically-based pharmacokinetic simulation to reduce clinical trial burden. This compression of development timelines is virtualizing the historical 18-24 month generic approval cycle into 9-12 month regulatory submissions.
The EMA's antimicrobial resistance strategy now mandates environmental risk assessment for all new antibiotic marketing authorizations. Manufacturing sites in the European Union must demonstrate activated sludge degradation of active pharmaceutical ingredients exceeding 80% removal rates. Facilities in the Netherlands and Denmark are retrofitting biological treatment trains to meet these discharge thresholds ahead of 2027 enforcement deadlines.
Hospital pharmacy and therapeutics committees are consolidating formulary decision authority previously distributed across individual clinical departments. Integrated delivery networks in the United States are narrowing oral antibiotic formularies to three agents per therapeutic class, displacing historical preference for physician-specific prescribing autonomy. This concentration is most visible in California's Kaiser Permanente system, where centralized procurement now governs 90% of oral antimicrobial spend.
Oral Antibiotics Market Segmentation
Oral antibiotics fragment across formulation chemistry, clinical indication, and care setting, with procurement patterns diverging sharply between institutional tenders and retail pharmacy dispensing. Understanding these segment boundaries reveals where pricing power concentrates and where volume commoditization erodes margin.
Product Type:
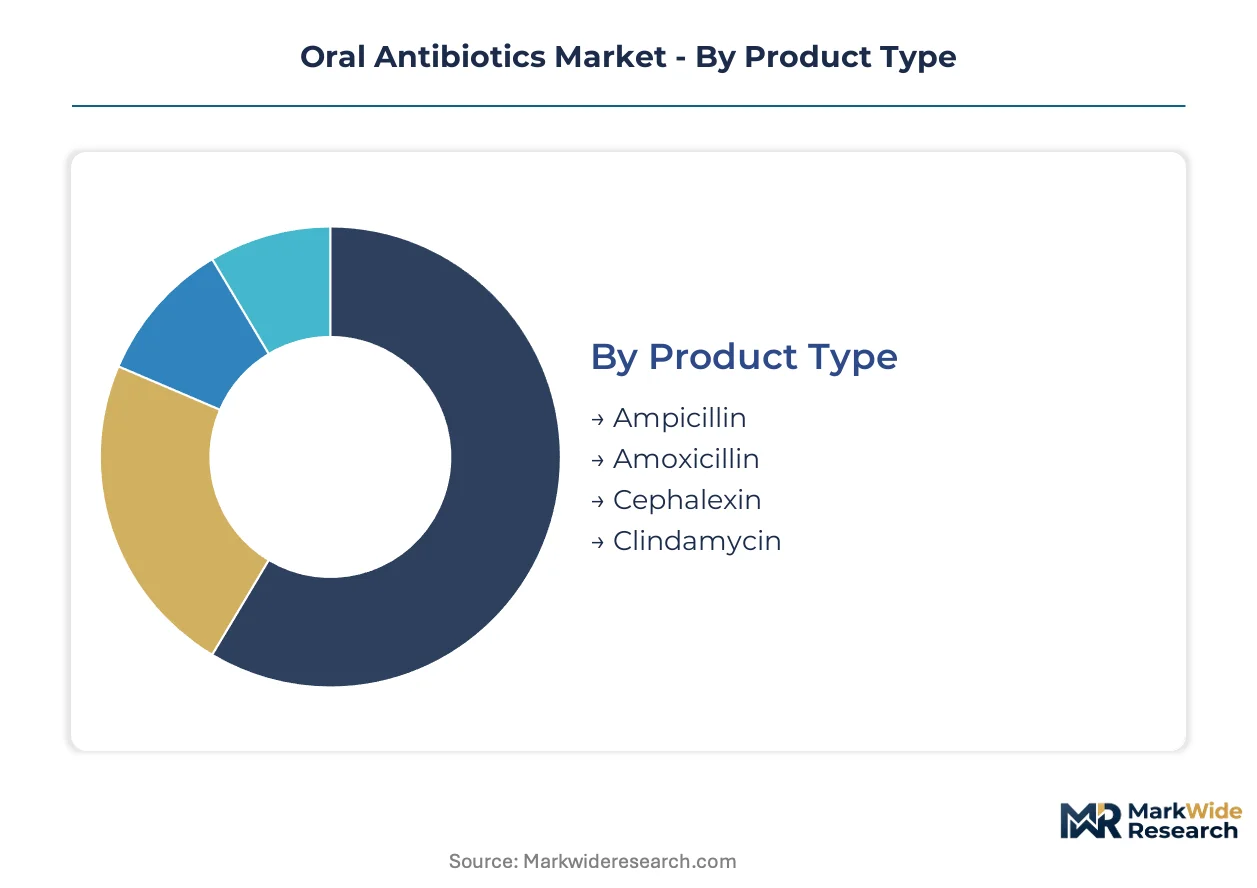
The use-case spectrum spans beta-lactam backbone variants with distinct resistance profiles and spectrum breadth.
- Ampicillin:Aminopenicillin with extended gram-negative coverage compared to natural penicillins, retaining relevance for enterococcal infections and uncomplicated urinary tract infections. Demand concentrates in India's government hospital tender system, where cost-per-dose metrics dominate procurement scoring over spectrum sophistication.
- Amoxicillin:Aminopenicillin with superior oral bioavailability and broader H. influenzae coverage, formulated as the most dispensed oral antibiotic globally. Volume clusters in European pharmacy chains, where pharmacist-led generic substitution protocols drive rapid interchangeability.
- Cephalexin:First-generation cephalosporin with methicillin-susceptible Staphylococcus aureus activity, prescribed primarily for skin and soft tissue infections. Pediatric formulations sustain niche positioning in North American retail channels.
- Clindamycin:Lincosamide with anaerobic coverage and MRSA alternative activity, reserved for penicillin-allergic patients and dental abscess protocols. Narrower volume reflects stewardship restrictions on indiscriminate prescribing.
Established volume favors amoxicillin; emerging adoption favors clindamycin in penicillin-restricted protocols.
Therapy Area:
Clinical application determines reimbursement tiering and formulary placement authority.
- Infectious Diseases:Protocol-driven prescribing for resistant gram-negative and atypical pathogens, requiring infectious disease consultation in integrated delivery networks. Stewardship program integration is reshaping demand toward narrow-spectrum agents with documented susceptibility.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis constitute the largest patient volume segment. Primary care prescribing in Germany and France drives seasonal demand spikes aligned with influenza circulation patterns.
- Skin Infections:Cellulitis and impetigo management, with cephalexin and dicloxacillin dominating outpatient therapy. Urgent care centers in the United States generate concentrated prescription volume through standardized order sets.
- Dental Infections:Periapical abscess and periodontal prophylaxis, where amoxicillin-clavulanate and clindamycin serve as first-line alternatives. Dental school curricula in Japan are narrowing antibiotic indications, compressing prophylactic prescribing volume.
Respiratory infections anchor current prescribing volume; infectious disease protocols are climbing the fastest as resistance surveillance intensifies.
End User:
Customer type dictates channel economics and pricing leverage.
- Hospitals:Centralized pharmacy and therapeutics committees govern formulary inclusion, with step-down protocols converting intravenous to oral regimens at discharge. Kaiser Permanente's California network exemplifies concentrated procurement authority.
- Clinics:Federally qualified health centers and urgent care chains with standardized treatment algorithms. Volume aggregates through group purchasing organizations serving multi-site operators.
- Pharmacies:Retail dispensing with pharmacist substitution rights and insurance formulary tiers. European chains leverage generic substitution ceilings to capture margin.
- Home Care:Long-term care facilities and aging-in-place programs requiring liquid formulations for dysphagia management. Japan's geriatric infrastructure sustains suspension demand growth.
Hospital procurement governs premium pricing; home care channels are gaining share fastest as parenteral-to-oral conversion expands.
Formulation:
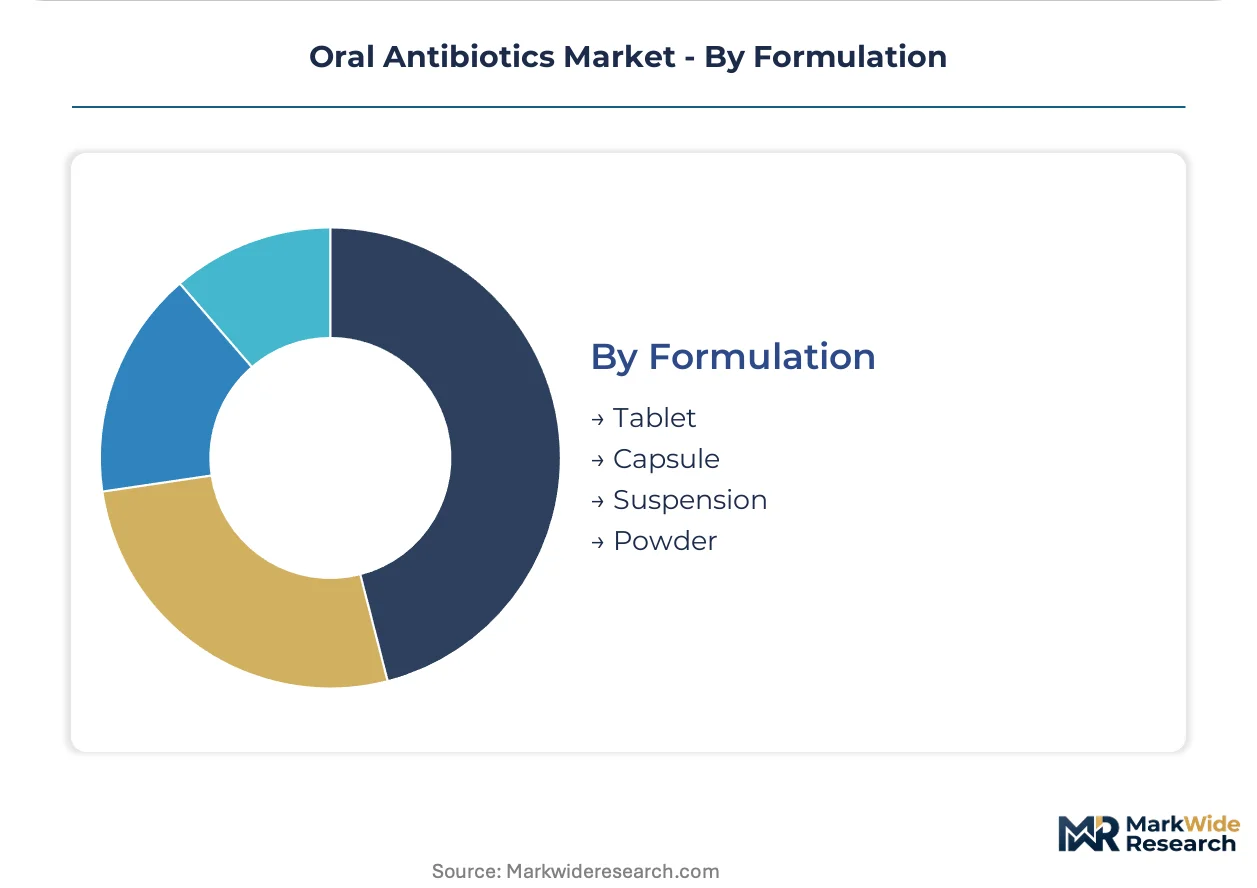
Physical presentation shapes manufacturing complexity and patient adherence economics.
- Tablet:Compressed solid dosage with highest manufacturing throughput and lowest unit cost. Indian generic exporters achieve scale advantages in regulated markets through dedicated tablet lines.
- Capsule:Gelatin-shell delivery with taste-masking advantages for bitter actives. European pharmacy chains stock capsule portfolios as differentiation from commoditized tablet offerings.
- Suspension:Liquid formulation for pediatric and geriatric populations with swallowing impairment. CDSCO bioequivalence requirements for suspensions create technical barriers to generic entry.
- Powder:Reconstitutable granules for extended stability and flexible dosing. Niche positioning in tropical markets with cold chain limitations.
Tablet output dominates manufacturing scale; suspension formulations are expanding most quickly in aging demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution of oral antibiotics, while Mumbai's JNPT port handles India's generic export surge to regulated markets.
United States
Outpatient parenteral-to-oral conversion protocols at Kaiser Permanente and HCA Healthcare are pulling volume from infusion centers into retail channels. The FDA's qualified infectious disease product designation accelerates novel agent review timelines. New Jersey's pharmaceutical corridor concentrates formulation capacity for hospital-directed supply.
Germany
Digital procurement exchanges in Bavaria and North Rhine-Westphalia are disintermediating traditional wholesalers. The EMA's environmental discharge standards tighten manufacturing effluent limits for antibiotic residues. Heidelberg's biopharmaceutical cluster advances biodegradation capabilities ahead of 2027 enforcement deadlines.
India
State government medical college tenders in Maharashtra and Tamil Nadu concentrate volume among domestic generic manufacturers. CDSCO mandates bioequivalence documentation that filters substandard entrants from pharmacy shelves. Hyderabad's API synthesis belt faces environmental compliance pressure during Zhejiang supply disruptions.
Japan
Geriatric swallowing difficulties in Kanto's aging-in-place infrastructure expand demand for liquid oral formulations. PMDA streamlines pediatric indication expansions for approved antibiotics. Osaka's pharmaceutical manufacturing base retrofits suspension production lines for home care channels.
Netherlands
EMA headquarters proximity attracts environmental risk assessment capabilities for new antibiotic authorizations. REACH compliance infrastructure supports advanced biodegradation demonstration for manufacturing sites. Rotterdam-Antwerp port complex enables just-in-time API import from Asian suppliers.
Oral Antibiotics Market Vendor Landscape
On the supply side, the industry is consolidating around hospital formulary gatekeepers and tender-winning generic scale players. Three archetypes dominate: patented novel-agent developers pursuing FDA qualified infectious disease product status, high-volume Indian generic exporters with regulated-market manufacturing scale, and European pharmacy chain suppliers with capsule and suspension differentiation. Competitive moves center on backward integration into API synthesis and geographic expansion through direct-to-hospital distribution platforms.
Among originator-drug developers, Pfizer Inc. and GSK plc. occupy positions anchored by hospital formulary relationships across infectious disease therapy areas. Within the generic manufacturing tier, Sun Pharmaceutical Industries Ltd. and Teva Pharmaceutical Industries Ltd. exemplify scale-driven competition through tablet line specialization and European pharmacy chain presence respectively.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc. |
| Abbott Laboratories |
| Merck & Co., Inc. |
| Novartis AG |
| Sanofi |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp port logistics costs shape margin structures across oral antibiotic supply tiers, concentrating pricing power among manufacturers with captive API capacity while forcing spot-market dependent formulators into aggressive tender discounting to retain hospital formulary placement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs oral antibiotic procurement, with FDA qualified infectious disease product designation commanding premium placement, Indian generic scale players dominating standard tier through state tender wins, and commodity amoxicillin volume eroding economy-tier margins. Price differentiation hinges on bioequivalence documentation quality and hospital formulary exclusivity duration. Cost compression in the economy tier is intensifying because China's environmental compliance inspections disrupt beta-lactam intermediate supply. Government hospital procurement managers in India exhibit highest price sensitivity; infectious disease specialists in integrated delivery networks show lowest sensitivity when resistance profiles justify spectrum premiums.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for oral antibiotic formulators, as Zhejiang and Jiangsu province API synthesis concentration creates single-source vulnerability during environmental enforcement actions. Raw material dependencies center on 6-aminopenicillanic acid, cephalosporin C, and clavulanic acid fermentation outputs. Distribution runs through hospital procurement exchanges in Germany, direct-to-government tender platforms in India, and retail pharmacy chains in Europe, with cold chain integrity monitored from Mumbai's JNPT port through Rotterdam's pharmaceutical handling facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral antibiotic markets reward service-layer attachment, with antimicrobial stewardship program integration and real-time susceptibility guidance software expanding faster than commodity tablet manufacturing.
For Market Incumbents: Build formulary lock-in moats through embedded pharmacy information system middleware that embeds spectrum guidance at prescribing decision points. Defensive priorities center on backward integration into beta-lactam API synthesis in Hyderabad's manufacturing belt and CDSCO bioequivalence certification investments that filter substandard generic competitors from tender eligibility. Threat vectors include digital procurement exchanges disintermediating traditional wholesale relationships and EMA environmental discharge standards advantaging European facilities with advanced biodegradation capabilities. For New Entrants and Emerging Players: Build out pediatric suspension manufacturing capabilities targeting Japan's aging-in-place infrastructure and Kanto region geriatric dysphagia management protocols. White-space concentration sits in liquid formulation bioequivalence documentation where CDSCO requirements create technical barriers to rapid generic entry. Go-to-market execution should prioritize direct-to-hospital distribution platforms in Germany's Bavaria and North Rhine-Westphalia digital procurement corridors, bypassing traditional pharmaceutical wholesaler margin capture. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting legacy oral antibiotic portfolios lacking qualified infectious disease product pipeline candidates. Long-term viability frames around stewardship program integration capabilities and environmental compliance infrastructure rather than pure manufacturing scale. Acquisition screening should prioritize facilities with demonstrated activated sludge degradation exceeding regulatory thresholds. The signal to watch is FDA review timeline acceleration for novel agents targeting resistant gram-negative pathogens, indicating pipeline premium potential.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA qualified infectious disease product designation compresses novel agent review timelines for resistant pathogen targets. |
| Backward Integration | Captive 6-APA synthesis in Hyderabad's API belt buffers margin against Zhejiang environmental compliance disruptions. |
| Green Manufacturing Transition | EMA discharge standards for antibiotic residues mandate activated sludge degradation exceeding 80% removal rates. |
| Hospital System Partnership | Kaiser Permanente's centralized procurement governs 90% of oral antimicrobial spend through formulary concentration. |
| Software Companion Development | Real-time spectrum guidance middleware embeds stewardship protocols at point of prescribing decision. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital formulary directors, CDSCO regulatory affairs leads, generic manufacturing plant managers, and infectious disease stewardship program officers; and secondary validation against FDA ANDA filings, EMA marketing authorization databases, Indian state government tender records, and ClinicalTrials.gov pipeline disclosures. Bottom-up volume aggregation across tablet, capsule, and suspension formulation segments triangulated against top-down therapy area spend analysis.
Forecast inputs considered parenteral-to-oral conversion protocol expansion rates, antimicrobial stewardship mandate adoption curves, and bioequivalence study virtualization through physiologically-based pharmacokinetic modeling across the analysis window. Segmentation dimensions modeled included product chemistry class, therapy area indication, end-user procurement channel, and regional regulatory cluster. CAGRs derived from weighted scenario analysis incorporating tender volume concentration trends and environmental compliance cost trajectories.
Practitioners should monitor Zhejiang environmental inspection intensity, FDA qualified infectious disease product approval velocity, and digital procurement exchange penetration for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Adamantane Antiviral Drugs Market