
 North America Temperature Sensor Market | 2026-2036
North America Temperature Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Temperature Sensor Market Analytics
Market Context
Specialized electromechanical engineering talent is redrawing competitive boundaries across the North America temperature sensor landscape. Texas Instruments leverages its analog semiconductor heritage to sustain design-in relationships with industrial OEMs. Honeywell International anchors its position through captive aerospace and building automation channels. Analog Devices competes by integrating signal conditioning and sensor fusion into single-package solutions.
Technical Definition and Segment Structure
A temperature sensor converts thermal energy into an electrical signal through thermoelectric, resistive, or radiative principles, typically operating across ranges from -200°C to 1750°C depending on the sensing element and sheath material. Thermocouples dominate heavy industrial applications where extreme temperatures and mechanical durability matter, while RTDs command premium positioning in pharmaceutical and food processing lines demanding ±0.1°C precision. Smart sensor architectures represent the fastest-expanding technology category as edge computing and IO-Link connectivity displace legacy 4-20 mA loops in manufacturing and automotive end-user segments.
Regulatory Framework
The US FDA enforces 21 CFR Part 820 quality system regulations for temperature sensors deployed in medical devices and pharmaceutical cold chains, while OSHA process safety management standards mandate continuous thermal monitoring in chemical facilities. The EPA's Clean Air Act compliance protocols and emerging DOE efficiency rules for industrial equipment collectively tighten accuracy and calibration requirements. Stakeholders must monitor how NHTSA thermal runaway testing standards for EV batteries reshape sensor specification thresholds across the automotive supply base.
Market Dynamics
Smart sensor architectures are compressing design cycles across industrial and automotive supply chains, forcing legacy 4-20 mA suppliers to requalify products for IO-Link and edge-native protocols or face specification lockouts.
Growth Catalysts
- US Inflation Reduction Act:Domestic clean energy manufacturing incentives are accelerating temperature monitoring deployment in battery gigafactories across Texas and Arizona.
- EV thermal management:Automotive OEMs are mandating precision sensing for battery thermal runaway prevention, pulling high-accuracy RTDs into vehicle platforms.
- Semiconductor fab expansion:Process control sensor procurement is surging at fabrication facilities in the US Southwest as domestic chip production scales.
Market Restraints
- Platinum supply concentration:RTD sensing elements depend on platinum group metals sourced from concentrated mining geographies, exposing margins to raw material volatility.
- Calibration infrastructure gaps:FDA 21 CFR Part 820 traceability requirements demand expensive metrology lab networks that smaller sensor vendors cannot replicate.
- Optical pyrometer substitution:Non-contact temperature measurement is displacing thermocouples in high-temperature steel and glass applications above 1200°C.
Strategic Opportunities
- NHTSA thermal runaway testing:Emerging EV battery safety standards are creating specification wedges for multi-point sensor arrays with sub-second response times.
- Digital twin integration:Sensor-to-cloud architectures that feed real-time thermal data into predictive maintenance platforms remain underpenetrated in food processing.
- Canadian cold chain:Health Canada pharmaceutical distribution rules are tightening temperature excursion tracking requirements for last-mile logistics.
Industry Challenges
- Analog signal conditioning talent:Mixed-signal IC design expertise for noise-immune thermocouple amplifiers is concentrating at a handful of US semiconductor firms.
- Legacy system integration:Brownfield manufacturing facilities running Modbus and DeviceNet require protocol gateway investments that complicate smart sensor rollouts.
Report Scope
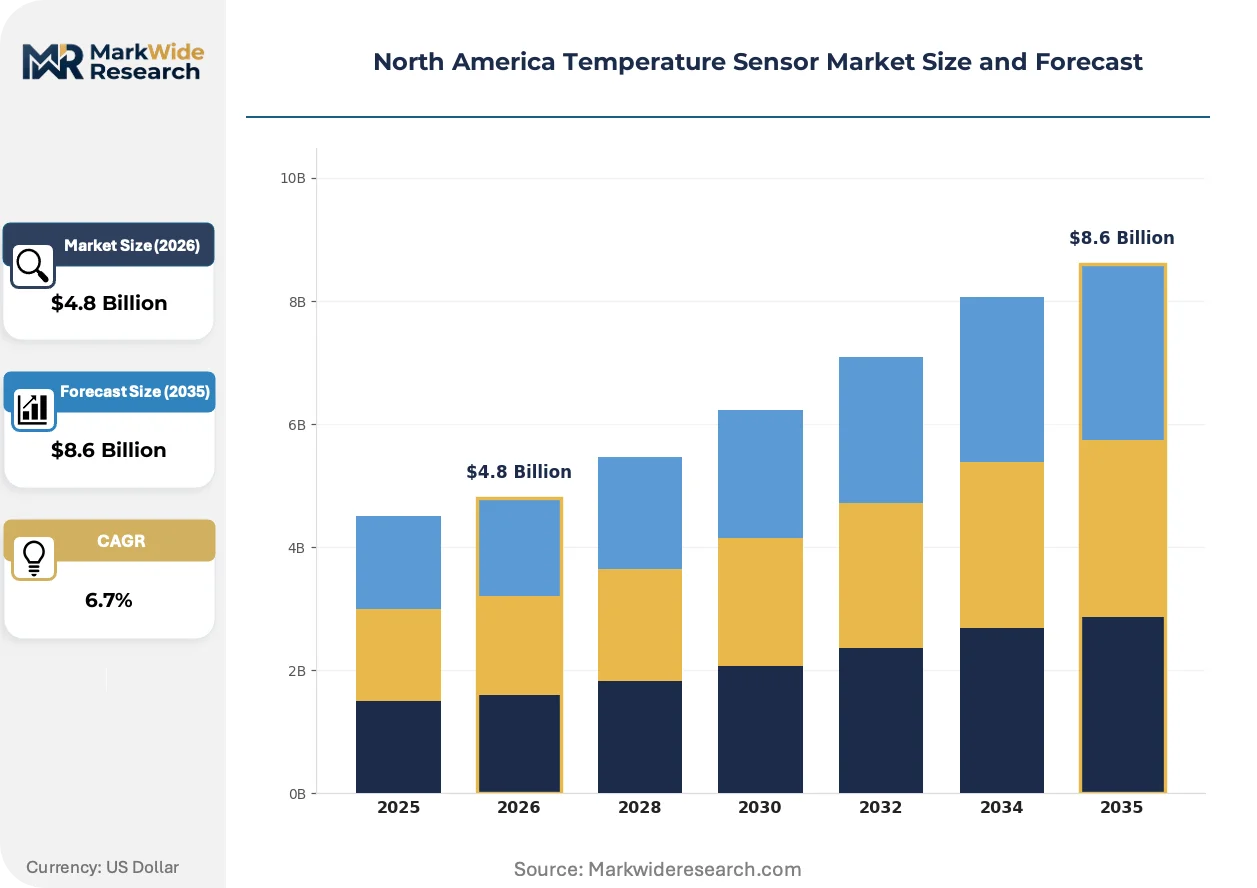
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Temperature Sensor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, RTDs, Thermistors, Infrared Sensors Use Case: Industrial Automation, HVAC, Food Processing, Healthcare Technology: Analog, Digital, Wireless, Smart Sensors End User: Manufacturing, Automotive, Energy, Aerospace |
| Companies Covered | Texas Instruments Incorporated, Honeywell International Inc., Analog Devices Inc., TE Connectivity, Emerson Electric Company, Siemens AG, Microchip Technology Inc., NXP Semiconductors, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Temperature Sensor Market Evolving Landscape
Edge-native sensing is collapsing the traditional separation between measurement hardware and control intelligence, redrawing value capture across the temperature sensor stack.
MEMS-based temperature sensing is bifurcating the market between high-volume, low-cost silicon devices for consumer and automotive cabin applications and precision thermopile arrays for industrial process control. Automotive Tier 1s are adopting MEMS for battery pack monitoring at scale. This technology is bifurcating supplier tiers, as silicon foundries capture value previously held by discrete sensor specialists.
OSHA process safety management standards are tightening continuous thermal monitoring mandates for chemical facilities handling reactive materials. Facilities must now deploy redundant sensing loops with automatic failover logic. Chemical processors in the US Gulf Coast are responding by consolidating sensor procurement with vendors offering integrated safety instrumented systems.
Specification consolidation by automotive OEMs is compressing approved vendor lists from dozens to single-digit qualified suppliers per platform. Battery thermal management teams at EV manufacturers are unbundling sensor selection from pack integrators and centralizing qualification at the OEM level. This pattern is most visible in Michigan and California engineering centers where platform decisions are made eighteen months ahead of production.
North America Temperature Sensor Market Segmentation
Temperature sensor procurement patterns diverge sharply across end-use environments, with industrial buyers prioritizing calibration traceability while automotive OEMs emphasize multi-point array integration. Channel strategy must align with these divergent specification workflows to capture design-in opportunities.
Product Type:
Channel mix varies by precision tier: thermocouples flow through industrial distributors to MRO accounts, while RTDs reach pharmaceutical and food processors via specialized instrumentation channels.
- Thermocouples:These junction-based sensors exploit the Seebeck effect to generate millivolt signals across extreme temperature spans from -200°C to 1750°C. Demand concentrates in Texas and Louisiana chemical processing corridors where OSHA process safety mandates require redundant high-temperature monitoring. Steel and glass manufacturers above 1200°C are migrating toward optical alternatives, compressing thermocouple growth in traditional strongholds.
- RTDs:Platinum or nickel wire-wound elements deliver ±0.1°C precision through resistance-temperature correlation. Battery gigafactories in Arizona and Texas are pulling RTD volumes for thermal runaway prevention as NHTSA testing standards tighten. Platinum supply concentration in South African and Russian mining geographies exposes procurement costs to raw material volatility.
- Thermistors:Ceramic oxide semiconductors provide steep resistance curves ideal for narrow-span medical and consumer applications. HVAC OEMs in the US Southeast specify NTC thermistors for residential climate control systems.
- Infrared Sensors:Non-contact pyrometers measure radiated thermal energy for moving or hazardous targets. Food processing lines in California deploy IR arrays for continuous conveyor monitoring without product contamination risk.
By volume, thermocouples lead. By growth pace, RTDs are ahead.
Use Case:
Cost tier stratification separates premium-specification healthcare and pharmaceutical applications from price-sensitive HVAC retrofit markets.
- Industrial Automation:IO-Link and edge-native protocols are displacing 4-20 mA loops in Michigan and Ohio manufacturing clusters. Brownfield facilities running legacy Modbus require gateway investments that complicate smart sensor rollouts.
- HVAC:Building automation systems integrate MEMS-based sensors for zone-level climate control. California Title 24 energy efficiency rules are accelerating digital thermostat sensor replacement cycles.
- Food Processing:FDA 21 CFR Part 820 traceability requirements demand expensive metrology lab networks that smaller vendors cannot replicate. Digital twin integration for predictive maintenance remains underpenetrated in this segment.
- Healthcare:Cold chain monitoring for pharmaceutical distribution requires calibrated sensors with continuous data logging. Health Canada rules are tightening temperature excursion tracking for last-mile logistics in Ontario and Quebec.
Industrial Automation captures the largest revenue pool. Healthcare is climbing the fastest.
Technology:
Customer type divides the landscape: process engineers specify analog for legacy compatibility while platform architects mandate digital for Industry 4.0 architectures.
- Analog:4-20 mA and voltage-output devices dominate existing installed bases across US Gulf Coast chemical facilities. Mixed-signal IC design expertise for noise-immune thermocouple amplifiers is concentrating at Texas Instruments and Analog Devices.
- Digital:I2C and SPI interface sensors embed ADC conversion and linearization algorithms. Automotive battery management systems in California engineering centers specify digital outputs for direct microcontroller integration.
- Wireless:Battery-powered LoRa and Bluetooth Low Energy sensors eliminate cabling in rotating or remote equipment. Oilfield operators in West Texas deploy wireless mesh networks for wellhead temperature surveillance.
- Smart Sensors:Edge-computing architectures combine sensing, signal conditioning, and protocol conversion in single packages. These devices are expanding most quickly as IO-Link connectivity becomes mandatory in new automotive platform specifications.
Analog maintains installed base dominance. Smart Sensors are gaining share fastest.
End User:
Application maturity varies: aerospace and energy demand qualified supplier lists while manufacturing tolerates broader vendor bases.
- Manufacturing:Discrete and process industries deploy sensors across machining, welding, and heat treatment operations. Automotive OEMs in Michigan are consolidating approved vendor lists from dozens to single-digit qualified suppliers per platform.
- Automotive:EV thermal management teams unbundle sensor selection from pack integrators and centralize qualification at the OEM level. Battery pack monitoring is adopting MEMS devices at scale, shifting value capture toward silicon foundries.
- Energy:Solar inverter and wind turbine OEMs specify outdoor-rated sensors with wide operating temperature ranges. The US Inflation Reduction Act is accelerating domestic clean energy manufacturing sensor procurement.
- Aerospace:Honeywell and Collins Aerospace anchor captive supply chains with decades-long qualification protocols. FAA certification requirements for flight-critical thermal monitoring sustain premium pricing tiers.
Manufacturing leads by unit volume. Automotive shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America. The United States dominates precision sensing for EV batteries and semiconductor fabrication. Canada concentrates cold chain monitoring for pharmaceutical distribution. Mexico serves as a manufacturing base for automotive sensor exports.
United States
EV battery gigafactories in Texas and Arizona are pulling RTD volumes for thermal runaway prevention. The US Inflation Reduction Act accelerates domestic clean energy manufacturing sensor procurement. Michigan engineering centers centralize sensor qualification at the OEM level, consolidating approved vendor lists.
Canada
Health Canada pharmaceutical distribution rules tighten temperature excursion tracking for last-mile logistics in Ontario and Quebec. The Canadian cold chain requires calibrated sensors with continuous data logging. Toronto and Montreal logistics hubs are expanding sensor deployment for vaccine distribution networks.
Mexico
Automotive Tier 1 suppliers in Nuevo León and Baja California manufacture temperature sensors for export to US EV platforms. Nearshoring trends under the USMCA trade framework expand industrial sensor assembly capacity. Querétaro's aerospace cluster demands FAA-certified thermal monitoring for flight-critical applications.
North America Temperature Sensor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America temperature sensor market. Texas Instruments, Honeywell International, and Analog Devices anchor the consolidated top tier through captive design-in relationships and aerospace qualification protocols. The mid-market fragments across regional distributors serving MRO accounts and brownfield industrial facilities. Strategic moves concentrate on smart sensor requalification for IO-Link protocols and MEMS-based integration for automotive battery management.
Within the analog semiconductor archetype, Texas Instruments Incorporated and Analog Devices Inc. occupy positions sustained by mixed-signal IC design expertise. Honeywell International Inc. anchors the diversified industrial conglomerate tier through building automation and aerospace channels. TE Connectivity exemplifies the connectivity-focused specialist model serving automotive and industrial end-users.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Honeywell International Inc. |
| Analog Devices Inc. |
| TE Connectivity |
| Emerson Electric Company |
| Siemens AG |
| Microchip Technology Inc. |
| NXP Semiconductors |
| Amphenol Corporation |
| Others |
Value Network & Pricing Analysis
MEMS silicon displacement of wire-wound platinum elements is redrawing procurement economics across automotive and industrial tiers, compressing margins for legacy RTD specialists while shifting value capture toward semiconductor foundries in Taiwan and Arizona.
Pricing Analysis
Long-term offtake contracts dominate RTD procurement for EV battery gigafactories, while spot-market transactions govern thermocouple replacement cycles in Gulf Coast chemical facilities. Price differentiation rests on FDA 21 CFR Part 820 certification tier and platinum wire purity grade. Cost compression in standard-grade thermocouples is intensifying because optical pyrometer substitution above 1200°C erodes volume leverage. HVAC OEMs exhibit highest price sensitivity; aerospace qualified suppliers command lowest elasticity.
Supply Chain Analysis
South Africa and Russia anchor platinum group metal extraction for RTD sensing elements, while Taiwan and South Korea feed silicon wafer inputs for MEMS temperature devices. The supply chain draws from concentrated mining geographies for noble metals and lithography equipment for semiconductor fabrication. Single-source vulnerability in South African platinum refining exposes North American sensor manufacturers to raw material disruption. Distribution runs through industrial distributors for MRO thermocouple accounts and direct OEM supply agreements for automotive platform qualifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among automotive OEMs—compressing approved vendor lists from dozens to single-digit qualified suppliers per EV platform—has shifted procurement leverage decisively toward buyers with multi-year volume commitments.
For Market Incumbents: Consolidate design-in relationships by embedding IO-Link protocol stacks and edge-computing firmware into next-generation sensor packages. Threats from silicon foundries capturing MEMS value previously held by discrete specialists demand backward integration into signal conditioning ASIC design. Priority investment in NHTSA thermal runaway testing pre-qualification secures specification lock-in before platform decisions freeze eighteen months ahead of production. For New Entrants and Emerging Players: Digital twin integration for predictive maintenance in food processing represents a service-layer gap where incumbents under-serve mid-size processors lacking in-house data science teams. White-space targets include wireless LoRa sensor networks for rotating equipment in West Texas oilfields and calibrated cold chain loggers for Health Canada-compliant last-mile logistics. Go-to-market through specialized instrumentation channels bypasses entrenched industrial distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial sensor specialists carrying FDA calibration infrastructure but lacking smart sensor engineering talent. Long-term viability hinges on five-to-ten year conversion of analog installed bases to digital-native architectures. Watch NHTSA rulemaking timelines as inflection signal—thermal runaway testing standard finalization will trigger specification refresh cycles across Michigan and California engineering centers.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Requalification for IO-Link Protocols | IO-Link mandates in automotive platform specifications lock out legacy 4-20 mA suppliers from design-in opportunities. |
| MEMS-Based Integration for Battery Management | Silicon foundries capture value previously held by wire-wound RTD specialists as automotive Tier 1s adopt MEMS at scale. |
| Backward Integration into Signal Conditioning ASICs | Mixed-signal IC design expertise concentrates at Texas Instruments and Analog Devices, creating captive supply advantages. |
| Calibration Infrastructure Expansion for FDA Compliance | 21 CFR Part 820 traceability requirements demand metrology lab networks that smaller vendors cannot replicate. |
| Digital Twin Platform Partnerships | Sensor-to-cloud architectures feeding predictive maintenance platforms remain underpenetrated in food processing verticals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, NHTSA regulatory dockets, and customs trade data for temperature sensor import flows. Primary interviews engaged sensor procurement managers at automotive OEMs, plant engineers at Texas and Arizona battery gigafactories, and distribution channel partners serving MRO accounts across the US Gulf Coast. Bottom-up unit demand estimates triangulate against top-down semiconductor and industrial equipment production forecasts.
Segmentation dimensions modeled include product type, use case, technology interface, and end-user industry across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against EV production schedules and semiconductor fab construction timelines. Industry-specific inputs incorporate NHTSA thermal runaway testing standard development status and US Inflation Reduction Act clean energy manufacturing incentive disbursement trajectories.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820 quality system enforcement and OSHA process safety management mandates; material policy shifts in medical device or chemical facility oversight would require re-modeling. Recalibration cycles align with material shifts in EV platform qualification timelines and platinum group metal supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Level Transmitter Market