
 Condition Monitoring System Market | 2026-2036
Condition Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Condition Monitoring System Market Analysis
The EU Green Deal is shifting industrial asset management priorities across European manufacturing, compelling facilities to retrofit legacy equipment with continuous monitoring infrastructure. SKF Group leverages its bearing expertise to anchor predictive maintenance ecosystems in heavy industry. Emerson Electric Co. competes through integrated vibration analysis platforms that extend from sensor hardware to cloud analytics. Siemens AG dominates digital twin integrations that pair condition data with simulation models for process optimization.
A condition monitoring system comprises sensors, data acquisition hardware, and analytical software that detect mechanical degradation in rotating and reciprocating machinery through vibration spectrum analysis, thermal imaging, and oil particulate measurement. These systems enable transition from calendar-based maintenance to condition-based strategies, reducing unplanned downtime in capital-intensive operations. Vibration sensors occupy the largest product category due to universal applicability across turbines, motors, and gearboxes, while edge computing architectures represent the fastest-expanding technology segment as latency-sensitive applications demand local preprocessing. Cloud-based deployments concentrate margin pools in recurring software subscriptions rather than one-time hardware sales.
OSHA machinery safety standards and the EU Machinery Directive shape product certification requirements, mandating functional safety ratings for sensors deployed in hazardous environments. EPA emissions tracking rules indirectly drive monitoring adoption as leak detection correlates with compressor and pump health surveillance. Stakeholders must weigh the trade-off between wireless sensor deployment speed and wired infrastructure reliability when designing monitoring architectures for brownfield industrial sites.
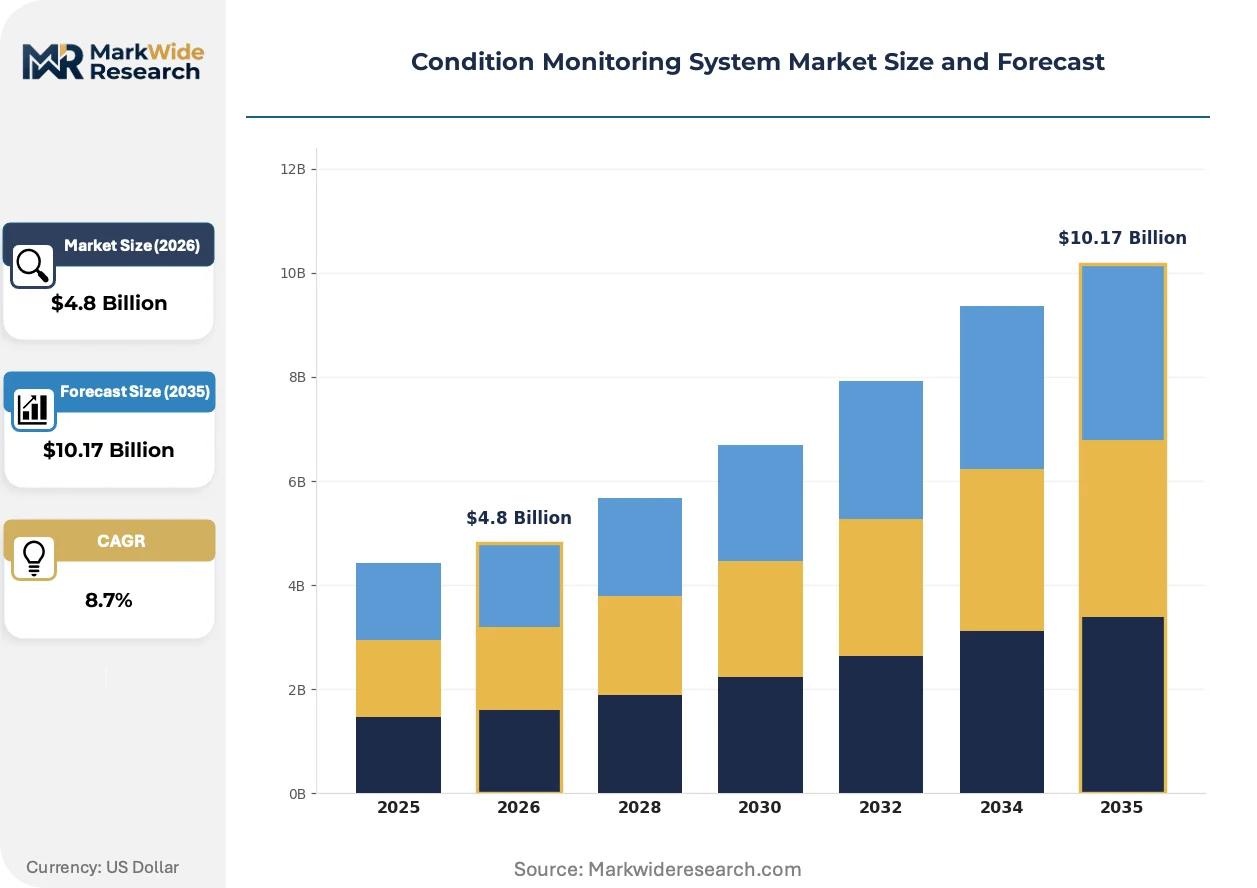
Market Dynamics
Power generation utilities are accelerating predictive maintenance adoption to eliminate unplanned turbine outages, while EU Machinery Directive amendments mandate functional safety ratings for rotating equipment sensors deployed in hazardous industrial environments.
Growth Catalysts
- EU Machinery Directive compliance mandates:Tightened safety requirements for rotating equipment monitoring compel facilities to retrofit legacy machinery with continuous sensor infrastructure across German and French manufacturing bases.
- Edge computing architectures:Latency-sensitive vibration analysis applications in steel mills and chemical plants demand local preprocessing capabilities that reduce cloud dependency and enable real-time fault detection.
- Oil particulate measurement integration:Compressor health surveillance now correlates with EPA emissions tracking rules, extending monitoring scope from mechanical failure prevention to environmental compliance verification.
Market Restraints
- Wireless versus wired infrastructure trade-offs:Brownfield industrial sites face capital-intensive decisions between rapid wireless sensor deployment and proven wired reliability for critical rotating assets.
- Specialized technician scarcity:Vibration spectrum analysis and thermal imaging interpretation require certified personnel that concentrated industrial clusters in Germany cannot sufficiently supply.
- Legacy system integration friction:Decades-old SCADA architectures in European heavy industry resist seamless connection with modern cloud analytics platforms without middleware investments.
Strategic Opportunities
- EU Green Deal retrofit wave:Industrial asset management priorities across European manufacturing compel facilities to install continuous monitoring infrastructure on aging equipment previously maintained through calendar-based schedules.
- Digital twin convergence:Pairing real-time condition data with simulation models enables process optimization beyond maintenance into operational efficiency gains for process industries.
- Cloud-based subscription economics:Recurring software revenue pools displace one-time hardware margins as deployment models shift from capital expenditure to operational expenditure frameworks.
Industry Challenges
- Functional safety certification timelines:Sensors deployed in hazardous environments require IEC 61508 compliance validation that extends product launch cycles and strains engineering bandwidth.
- Interoperability standard fragmentation:Competing communication protocols between sensor hardware and analytics platforms force integrators to maintain multiple interface configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condition Monitoring System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Sensors, Temperature Sensors, Pressure Sensors, Ultrasonic Sensors Technology: Wireless, Wired, Cloud-Based, Edge Computing End User: Manufacturing, Oil & Gas, Healthcare, Transportation Installation: On-Premise, Remote, Hybrid, Mobile |
| Companies Covered | Emerson Electric Co., SKF Group, Honeywell International Inc., General Electric, ABB Ltd., Siemens AG, Rockwell Automation Inc., Schaeffler Group, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condition Monitoring System Market Emerging Trajectories
Vibration analysis hardware is fragmenting into interoperable components that industrial buyers assemble into customized monitoring stacks rather than purchasing monolithic systems from single vendors.
Sensor hardware is modularizing into standardized form factors with swappable communication modules. Chemical processing facilities in the Netherlands and Belgium are adopting these configurable units to mix wireless and wired nodes within identical mechanical enclosures. This architecture is modularizing procurement decisions, allowing maintenance teams to upgrade connectivity without replacing calibrated measurement elements.
REACH chemical substance restrictions are reshaping sensor material specifications for oil analysis equipment deployed in European manufacturing. Manufacturers must reformulate wetted components to eliminate restricted substances while maintaining compatibility with hydrocarbon-based lubricants. The F-Gas Regulation is simultaneously pressuring thermal imaging sensor cooling systems toward alternative refrigerants, with German automotive suppliers leading retrofit demand.
Maintenance service contracts are unbundling from original equipment supply agreements as end-users seek specialized analytics providers. German steel producers and French aerospace subcontractors now procure vibration analysis separately from bearing hardware, compressing traditional supplier margins. This pattern is most pronounced in the Rhine-Ruhr industrial corridor where dense automation infrastructure supports multi-vendor integration.
Condition Monitoring System Market Segmentation
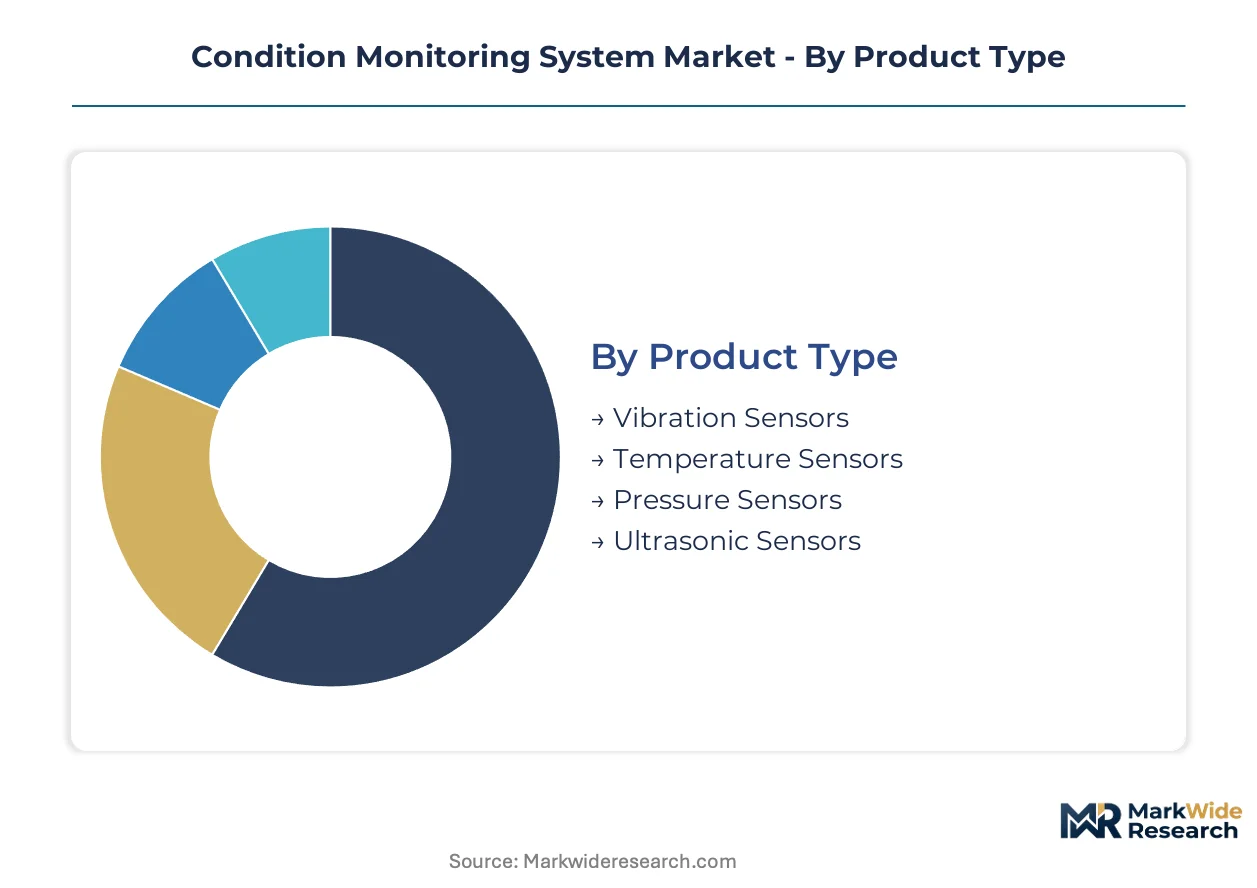
Segmentation in condition monitoring systems determines procurement architecture and integration complexity for industrial buyers. Vibration analysis platforms, edge computing nodes, and wireless sensor networks each impose distinct technical requirements on maintenance departments.
Product Type:
Standardization dominates vibration and temperature sensing, while ultrasonic and pressure monitoring demand application-specific calibration protocols.
- Vibration Sensors:Piezoelectric accelerometers and velocity transducers capture mechanical oscillation signatures across rotating machinery. German automotive suppliers and French aerospace subcontractors deploy these universally across turbine, motor, and gearbox assets to satisfy EU Machinery Directive safety mandates.
- Temperature Sensors:Infrared thermocouples and RTD probes detect thermal anomalies in bearing assemblies and electrical connections. Dutch chemical processing facilities concentrate procurement for reactor vessel monitoring where heat dissipation correlates with mechanical degradation.
- Pressure Sensors:Piezoresistive transducers track hydraulic system integrity and pneumatic line fluctuations.
- Ultrasonic Sensors:High-frequency acoustic detectors identify lubrication failures and early-stage bearing defects in high-speed rotating equipment.
Leading the category by volume: Vibration Sensors. Expanding most quickly: Ultrasonic Sensors.
Technology:
Deployment cost tiers separate legacy wired infrastructure from premium wireless and edge architectures requiring specialized engineering integration.
- Wireless:Battery-powered sensor nodes with mesh networking protocols enable rapid brownfield retrofit without cable routing. Belgian steel mills favor these for overhead crane and remote pump monitoring where conduit installation proves prohibitively expensive.
- Edge Computing:Localized preprocessing units execute real-time frequency analysis and anomaly detection algorithms at the sensor layer. German chemical plants deploy these for latency-critical compressor protection where cloud round-trip delays exceed fault reaction windows.
- Wired:Shielded coaxial and Ethernet connections deliver interference-resistant signal transmission for safety-critical rotating assets.
- Cloud-Based:Centralized analytics platforms aggregate fleet-wide condition data for predictive model training and cross-facility benchmarking.
Leading the category by volume: Wired installations. Gaining share fastest: Edge Computing.
End User:
Application maturity varies sharply, with manufacturing and oil & gas commanding established maintenance protocols while healthcare and transportation build specialized competencies.
- Manufacturing:Discrete and process production lines deploy comprehensive sensor networks across CNC machines, conveyor systems, and robotic workcells. Rhine-Ruhr industrial corridor facilities lead European adoption density for continuous monitoring infrastructure.
- Oil & Gas:Upstream drilling platforms and downstream refineries monitor critical turbomachinery under EPA emissions tracking rules that correlate compressor health with leak detection compliance.
- Healthcare:Hospital HVAC systems and medical imaging equipment utilize vibration monitoring to ensure continuous patient care operations.
- Transportation:Railway rolling stock and marine propulsion systems adopt ruggedized sensors for mobile asset condition tracking.
Leading the category by volume: Manufacturing. Climbing the fastest: Oil & Gas.
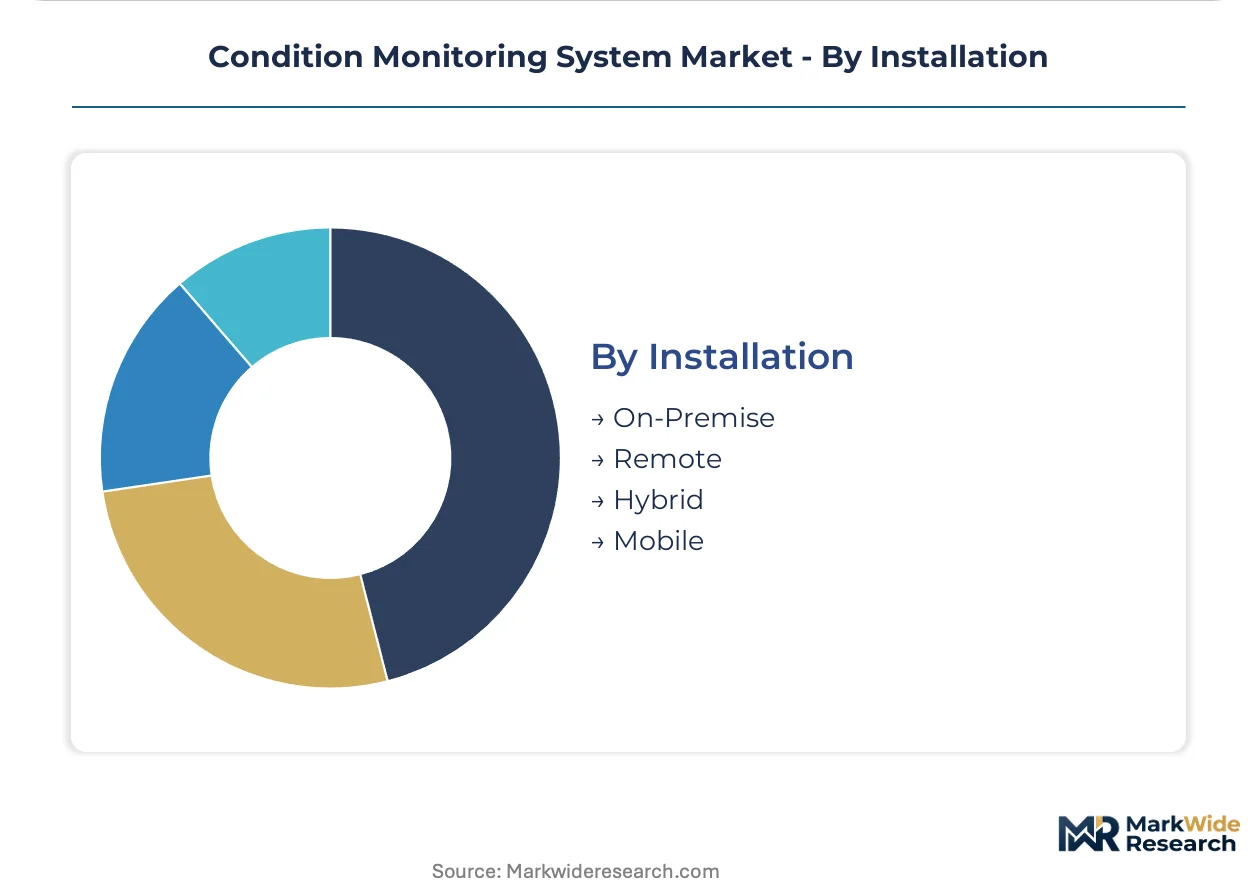
Installation:
Customer infrastructure maturity determines architecture selection between capital-intensive on-premise systems and flexible remote deployments.
- On-Premise:Dedicated server rooms and local data lakes maintain complete data sovereignty for security-sensitive industrial operations. German automotive manufacturers prefer these configurations for proprietary process optimization algorithms.
- Hybrid:Tiered architectures process latency-sensitive alerts locally while archiving historical trends in cloud repositories. French nuclear facilities adopt these for regulatory compliance documentation combined with real-time safety system isolation.
- Remote:Fully externalized monitoring services shift capital expenditure to operational expenditure frameworks.
- Mobile:Portable diagnostic equipment enables periodic route-based data collection for non-critical auxiliary machinery.
Leading the category by volume: On-Premise. Steepest expansion trajectory: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor concentrates European condition monitoring deployment density, with German manufacturing automation infrastructure supporting advanced sensor networks across turbine and motor assets.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg deploy vibration sensors across CNC machining lines and robotic workcells. The EU Machinery Directive mandates functional safety ratings for rotating equipment sensors in hazardous environments. Stuttgart's aerospace subcontractor cluster drives ultrasonic sensor procurement for high-speed bearing defect detection.
United States
Power generation utilities accelerate predictive maintenance adoption to eliminate unplanned turbine outages across Texas and Gulf Coast refining corridors. EPA emissions tracking rules correlate compressor health surveillance with leak detection compliance. Houston's petrochemical complex concentrates oil particulate measurement integration for environmental verification.
France
Nuclear facilities adopt hybrid installation architectures combining local real-time safety systems with cloud archival for regulatory documentation. The country's national industrial safety regulator enforces IEC 61508 compliance validation for sensors in hazardous environments. The Île-de-France aerospace subcontractor cluster unbundles maintenance service contracts from original equipment supply agreements.
Netherlands
Chemical processing facilities in Rotterdam and Antwerp corridor adopt modular sensor hardware with swappable communication modules mixing wireless and wired nodes. REACH chemical substance restrictions reshape oil analysis equipment material specifications. Dutch chemical plants deploy edge computing nodes for latency-critical compressor protection.
China
Steel mills and heavy manufacturing bases in the Yangtze River Delta demand localized preprocessing capabilities for real-time fault detection. The Ministry of Industry and Information Technology drives industrial automation upgrade programs. Shanghai's industrial automation density supports rapid brownfield retrofit with battery-powered wireless sensor nodes.
Condition Monitoring System Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with bearing and automation heritage. Sensor hardware specialists and cloud analytics platforms occupy distinct capability layers rather than competing directly. Three archetypes dominate: rotating equipment manufacturers extending into predictive maintenance services, automation conglomerates integrating vibration analysis into control system portfolios, and specialized sensor fabricators supplying interoperable measurement components. M&A activity concentrates on edge computing software acquisitions, while capacity expansion targets modular sensor form factors for brownfield retrofit flexibility.
Among European-based industrial conglomerates, SKF Group and Schaeffler Group represent bearing-centric archetypes that anchor predictive maintenance ecosystems through mechanical expertise. Siemens AG exemplifies the automation-integrated archetype, pairing condition data with digital twin simulation models. Emerson Electric Co. occupies a position spanning sensor hardware through cloud analytics platforms. These three companies illustrate how competitive positioning fragments across measurement hardware, edge preprocessing, and centralized analytics layers rather than consolidating vertically.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| SKF Group |
| Honeywell International Inc. |
| General Electric |
| ABB Ltd. |
| Siemens AG |
| Rockwell Automation Inc. |
| Schaeffler Group |
| Fluke Corporation |
| Others |
Supply Flow & Price Mechanics
EU Machinery Directive compliance mandates for functional safety ratings are forcing procurement teams to qualify dual sensor suppliers, compressing margins for uncertified vendors while elevating IEC 61508-validated hardware premiums across German and French manufacturing bases.
Pricing Analysis
Uptime-guarantee contracts now anchor pricing for condition monitoring systems, with vibration analysis platforms commanding recurring revenue premiums tied to turbine availability metrics. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61508-certified edge computing nodes from uncertified wired installations and basic wireless sensor kits. Pricing pressure stems from unbundled maintenance service contracts that strip aftermarket margins from bearing manufacturers. Small-to-mid chemical processors exhibit highest price sensitivity, while nuclear facilities and aerospace subcontractors absorb premiums for validated safety ratings.
Supply Chain Analysis
Dual-sourcing requirements for piezoelectric accelerometer elements mandate qualified suppliers in Germany, Japan, and the United States, insulating procurement from single-source disruption. Sensor fabrication draws from silicon wafer substrates, rare-earth magnetic components for velocity transducers, and specialized ceramic formulations for high-temperature thermocouples. Supply chain risk centers on F-Gas Regulation compliance timelines for thermal imaging sensor cooling systems, which compress delivery windows for refrigerant-dependent hardware. Distribution runs through authorized industrial automation distributors with certified integration capabilities, bypassing commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician scarcity for vibration spectrum analysis propels pricing power for training-certified system integrators, creating supply-constrained margin pools for qualified service providers.
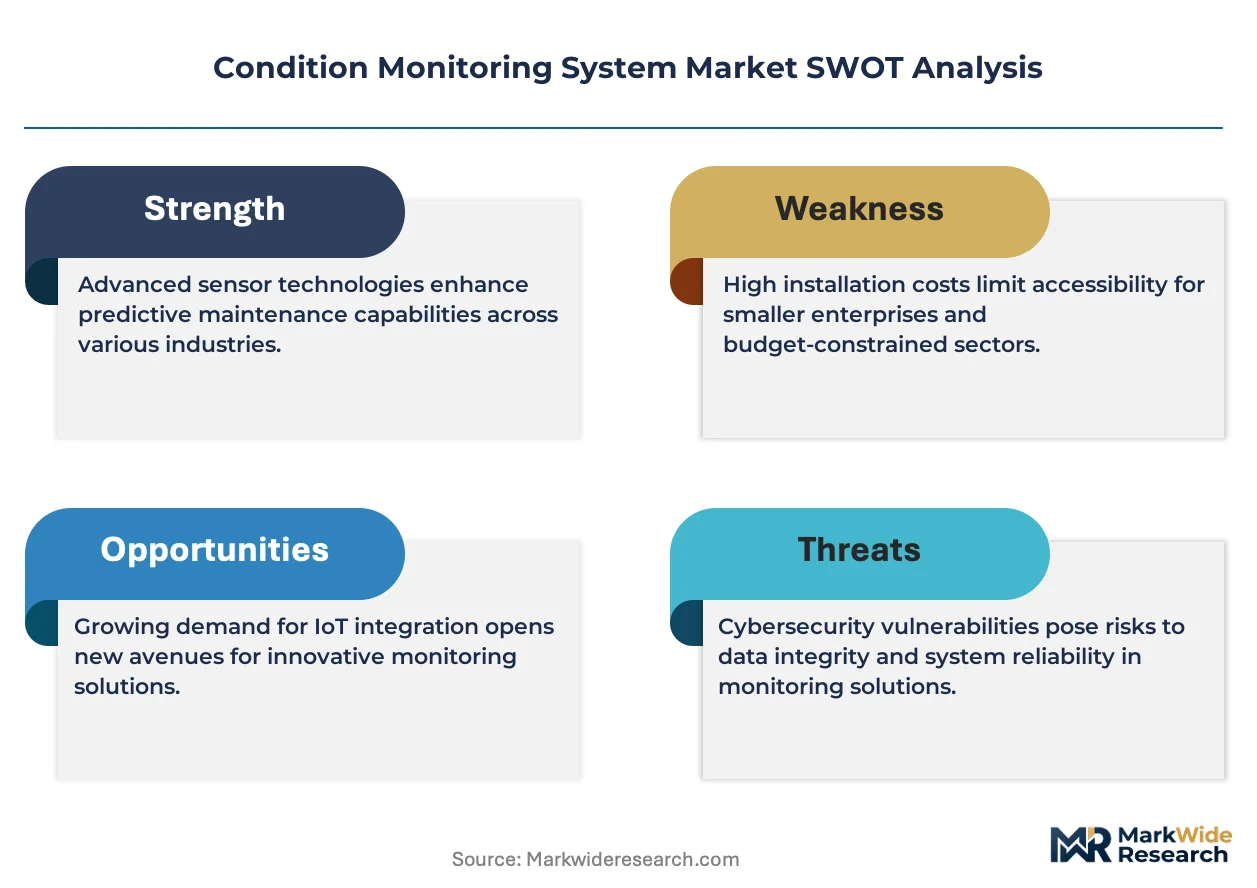
For Market Incumbents: Deploy backward integration into edge computing software stacks to capture preprocessing value that unbundled analytics vendors currently extract. Defensive consolidation should prioritize acquisition of ultrasonic sensor specialists before REACH chemical restrictions eliminate smaller material-science players. Certification investment in IEC 61508 validation capacity protects margin position against emerging Chinese sensor fabricators. For New Entrants and Emerging Players: Begin with brownfield wireless retrofit projects in Belgium and Dutch chemical corridors where conduit installation costs exclude incumbent wired solutions. White-space concentration sits with portable diagnostic equipment for auxiliary machinery monitoring, a segment neglected by fixed-installation specialists. Channel partnership with established industrial automation distributors accelerates qualification timelines for safety-critical deployments. For Investors and Strategic Acquirers: Re-rating potential sits with edge computing software specialists given EU Green Deal retrofit mandates that demand localized preprocessing for aging equipment fleets. Long-term viability favors acquisition targets with modular sensor architectures that accommodate REACH-mandated material substitutions without full redesign cycles. The signal to watch is F-Gas Regulation enforcement intensity, which determines retrofit demand velocity for thermal imaging cooling system upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Software Acquisition | Captures latency-critical preprocessing value previously held by cloud analytics platforms in German chemical plants. |
| Modular Sensor Form Factor Expansion | Enables REACH-compliant material swaps without bearing recalibration, reducing regulatory-driven engineering cycles. |
| Functional Safety Certification Investment | Unlocks EU Machinery Directive-mandated procurement pools in French nuclear and German automotive supplier facilities. |
| Maintenance Service Contract Unbundling | Separates analytics provision from hardware supply, compressing traditional bearing manufacturer margins in Rhine-Ruhr corridor. |
| Wireless Sensor Network Partnership | Accelerates brownfield deployment in Belgian steel mills where conduit installation costs exclude wired alternatives. |
Methodological Framework
Multi-period observation of sensor deployment density, predictive maintenance adoption rates, and functional safety certification timelines anchored the trend analysis, supplemented by interviews with maintenance directors at German automotive suppliers, plant engineers in Dutch chemical processing facilities, aftermarket service heads at bearing manufacturers, and procurement leads at French nuclear operators. Secondary validation incorporated EU Machinery Directive amendment tracking, EPA emissions rulemaking dockets, IEC 61508 certification database analysis, and customs data for vibration sensor trade flows. Bottom-up facility-level deployment estimates triangulated against top-down industrial automation spending benchmarks.
Segment-weighting across product type, technology architecture, end-use industry, and installation model shaped the analytical framework, with vibration sensor volumes, edge computing adoption velocity, and hybrid deployment trajectories modeled separately across the projection horizon. CAGRs derived from facility retrofit pipeline analysis, regulatory compliance deadline clustering, and technology substitution elasticity estimates for wireless versus wired infrastructure. Forecast inputs incorporated REACH chemical restriction implementation schedules and F-Gas Regulation cooling system phase-out timelines.
Underlying measurement precision varies by segment; wired infrastructure deployments carry tighter precision than emerging wireless retrofit estimates due to established procurement documentation practices. Forecasts reflect documented assumptions regarding EU Green Deal funding continuity and industrial automation upgrade program persistence. A model refresh is warranted upon material change in EU Machinery Directive enforcement intensity or REACH substance restriction expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Doppler Lidar Market