
 Smart Dust Market | 2026-2036
Smart Dust Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Dust Market Analysis
Defense procurement channels is rewriting how smart dust suppliers secure long-term contracts. Cisco Systems leverages its networking infrastructure footprint to anchor large-scale sensor mesh deployments for government clients. Honeywell International sustains aerospace-grade manufacturing protocols that differentiate its microelectromechanical systems from commercial-grade alternatives. Analog Devices competes through precision signal-processing architectures that dominate low-power wireless communication endpoints.
Smart dust denotes networks of autonomous, millimeter-scale wireless sensors capable of detecting temperature, vibration, light, or chemical composition while operating on micro-watt power budgets. These devices typically integrate MEMS transducers with CMOS circuitry and sub-GHz radio transceivers to enable distributed environmental or structural monitoring without wired infrastructure. Microelectromechanical systems occupy the deepest margin pools due to fabrication complexity and limited foundry capacity, while smart particles represent the fastest-growing category as pharmaceutical and agricultural buyers pilot ingestible and soil-embedded variants. Military applications lead current revenue contribution, though environmental monitoring is narrowing the gap as EPA-aligned air quality mandates expand sensor network procurement.
FDA scrutiny of implantable biosensors, EPA ambient monitoring standards, and ISO 13485 quality management requirements collectively shape product certification timelines and market access conditions for smart dust developers. IEEE 802.15.4 and LoRaWAN protocol certifications further constrain which radio architectures gain commercial traction across regulated industries. Stakeholders must monitor which regulatory bodies classify passive smart particles as medical devices versus environmental equipment, as this determination locks in multi-year compliance pathways and channel partnerships.
Market Dynamics
Defense procurement cycles are compressing as nanoscale wireless sensor networks replace legacy surveillance infrastructure, forcing suppliers to reconfigure fabrication capacity around aerospace-grade MEMS protocols rather than commercial semiconductor economics.
Growth Catalysts
- Precision agriculture pilots:Soil-embedded smart particles enable real-time moisture and nutrient mapping across large-scale farming operations in the United States and Germany.
- REACH chemical compliance mandates:European industrial monitoring requirements are accelerating deployment of distributed air quality sensor networks in manufacturing zones.
- Sub-GHz radio miniaturization:Advances in low-power wireless transceiver design extend operational lifespans for battery-constrained field deployments.
Market Restraints
- Limited MEMS foundry capacity:Fabrication complexity concentrates production among a handful of specialized semiconductor facilities in Japan and Germany.
- Raw material input volatility:Rare earth element pricing fluctuations directly impact magnetostrictive transducer production costs.
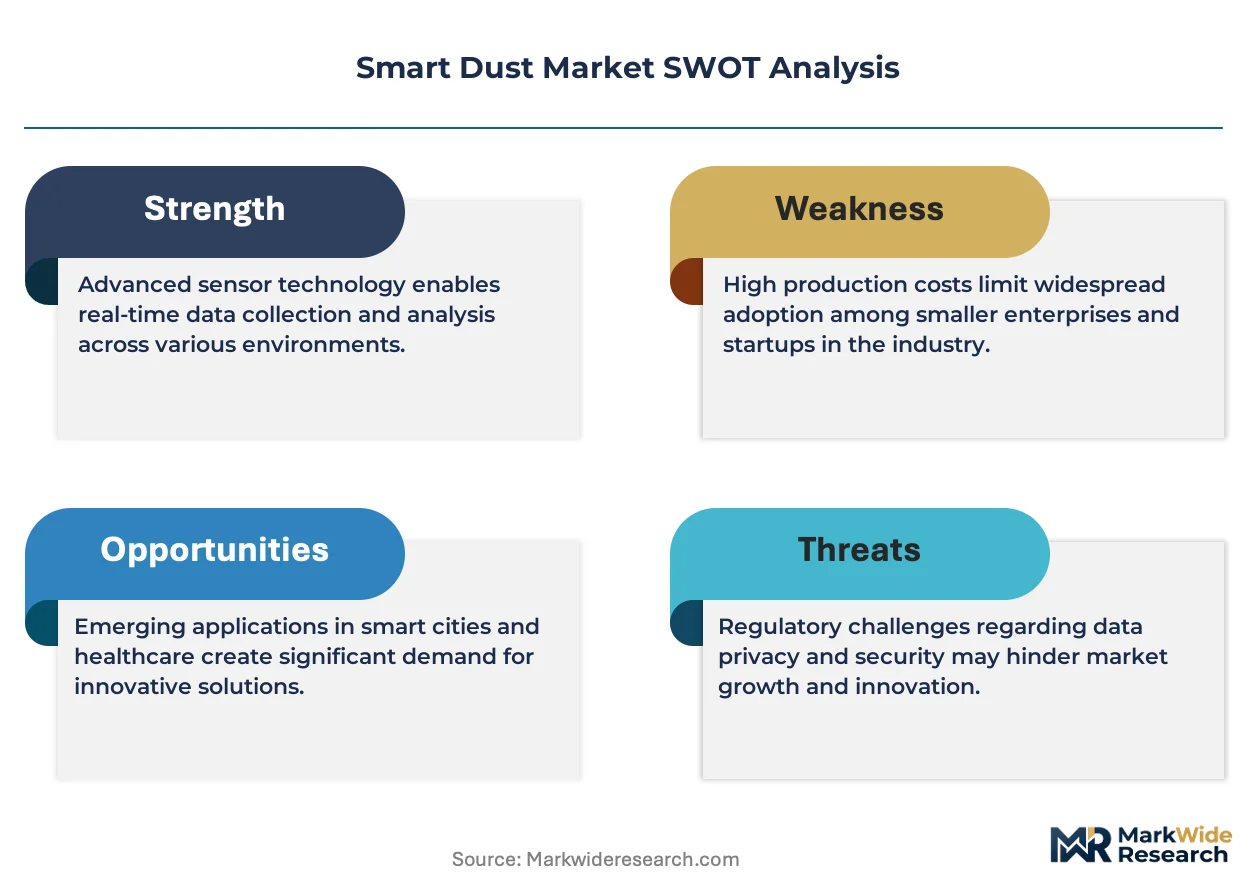
- ISO 13485 certification timelines:Medical-grade quality management requirements extend product launch cycles by 18-24 months for implantable biosensor variants.
Strategic Opportunities
- Pharmaceutical traceability applications:Ingestible smart particles for gastrointestinal monitoring represent an emerging therapeutic category with distinct regulatory pathways.
- Indian precision agriculture expansion:Government irrigation efficiency programs create procurement channels for soil-embedded moisture sensors in water-stressed agricultural districts.
- LoRaWAN protocol standardization:IEEE 802.15.4 certification alignment enables interoperability across municipal smart city infrastructure deployments.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in sub-milliwatt radio design remains concentrated among legacy aerospace and telecommunications engineering pools.
- Multi-standard compliance burden:Simultaneous FDA, EPA, and FCC certification requirements fragment quality assurance resources across parallel review tracks.
- Legacy system integration friction:Existing SCADA and building management architectures lack native interfaces for millimeter-scale wireless sensor data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Dust Market |
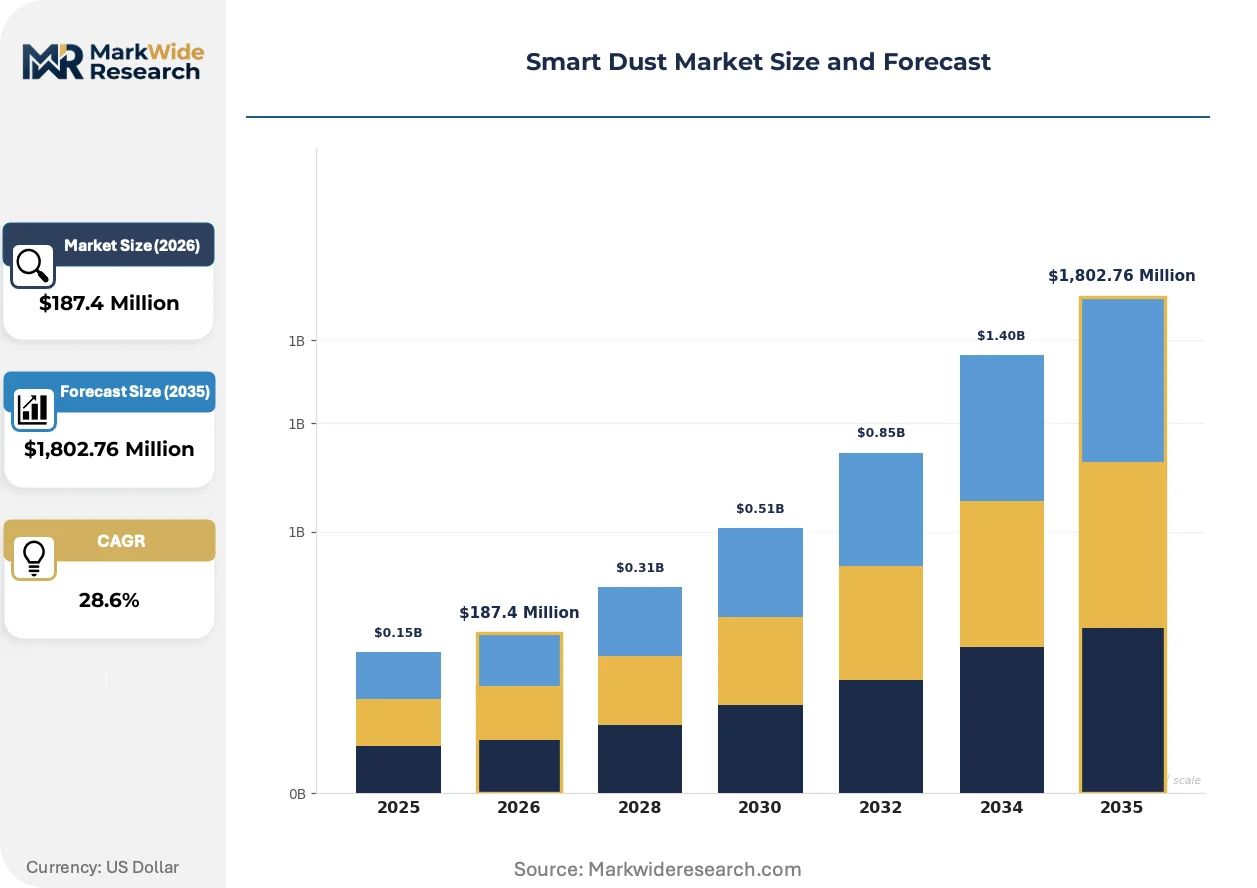
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microelectromechanical Systems, Wireless Sensors, Smart Particles, Nanotechnology Application: Environmental Monitoring, Healthcare, Smart Agriculture, Military Applications End User: Manufacturers, Research Institutions, Government Agencies, Farmers Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Cisco Systems, Honeywell International, Analog Devices, Texas Instruments, STMicroelectronics, IBM Corporation, Intel Corporation, NXP Semiconductors, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Dust Market Emerging Trajectories
Energy harvesting architectures are displacing battery-dependent power models, reshaping device lifecycle economics and enabling perpetual operation in remote deployment scenarios previously inaccessible to maintenance-constrained sensor networks.
Photovoltaic and piezoelectric energy harvesting is migrating from experimental prototypes to field-hardened production designs. Military surveillance programs in the United States and Germany are specifying ambient light and vibration-powered units for unattended ground sensor arrays. This migration from battery-reliant to energy-autonomous architectures compresses total cost of ownership calculations and extends operational timelines in denied-access environments.
EPA ambient monitoring standards are tightening particulate detection thresholds for industrial emissions reporting. Manufacturing facilities in the American Midwest and German Ruhr region face expanded sensor network mandates. Environmental compliance officers are specifying IEEE 802.15.4 mesh topologies to satisfy real-time data logging requirements without hardwired infrastructure retrofits.
Buyers are consolidating vendor relationships around full-stack sensor network providers rather than component specialists. Agricultural cooperatives and municipal utilities now demand integrated hardware-software-deployment packages. This preference shift is most visible in Japanese precision agriculture clusters, where farm operators prioritize single-contract accountability over multi-vendor integration risk.
Smart Dust Market Segmentation
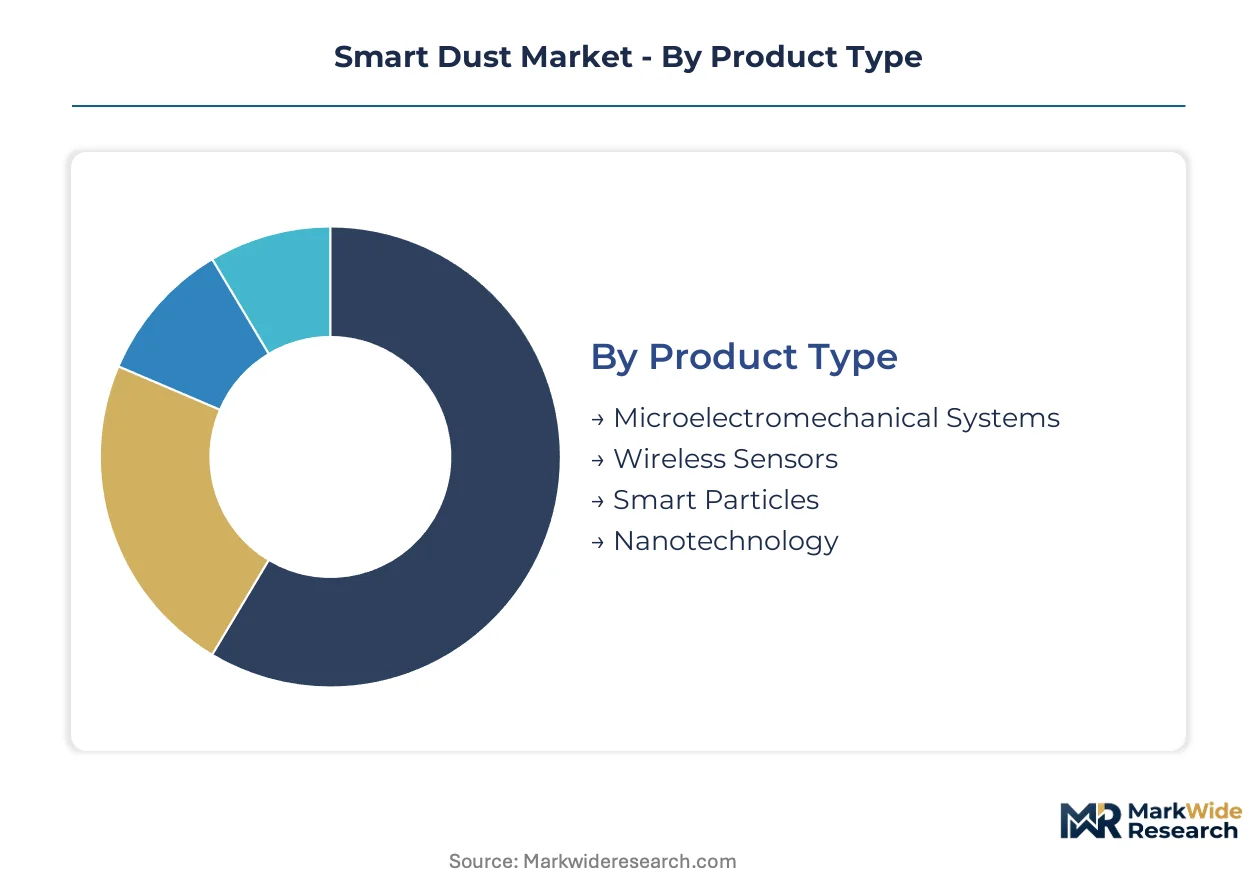
Smart dust segmentation reflects competing fabrication philosophies and divergent power-autonomy requirements. Buyers select architectures based on whether deployments prioritize perpetual operation, regulatory compliance, or rapid field reconfiguration.
Product Type:
Microelectromechanical systems anchor precision applications demanding sub-millimeter accuracy, while nanotechnology variants target biological and chemical detection use-cases.
- Microelectromechanical Systems:Fabrication integrates transducers with CMOS circuitry using specialized foundry protocols. Defense procurement in the United States and Germany concentrates here due to aerospace-grade reliability requirements and limited supplier certification.
- Smart Particles:Ingestible and soil-embedded variants operate without external power harvesting. Pharmaceutical traceability pilots and Indian irrigation efficiency programs are expanding procurement volumes fastest for this category.
- Wireless Sensors:Sub-GHz radio architectures enable distributed mesh topologies for industrial monitoring.
- Nanotechnology:Molecular-scale detection mechanisms target chemical composition analysis in environmental compliance applications.
Established volume favors microelectromechanical systems; emerging adoption favors smart particles.
Application:
Defense contracts currently dominate revenue concentration, though environmental monitoring is narrowing the gap through tightening EPA and ECHA compliance mandates.
- Military Applications:Unattended ground sensor arrays specify ambient energy harvesting and denied-access durability. United States and German surveillance programs are replacing bulkier legacy infrastructure with nanoscale wireless networks.
- Environmental Monitoring:EPA ambient standards and REACH chemical compliance are mandating real-time particulate detection. Manufacturing zones in the American Midwest and German Ruhr region face expanded sensor network procurement.
- Healthcare:Implantable biosensors face FDA and ISO 13485 certification timelines extending launch cycles.
- Smart Agriculture:Soil-embedded moisture mapping enables precision irrigation across water-stressed farming districts.
Defense procurement maintains current revenue leadership; environmental compliance is gaining share fastest.
End User:
Government agencies command longest contract horizons, while farmers and manufacturers prioritize integrated hardware-software-deployment packages over component sourcing.
- Government Agencies:Military and environmental regulators specify IEEE 802.15.4 mesh topologies and LoRaWAN interoperability. Procurement cycles are compressing as nanoscale networks replace legacy surveillance infrastructure.
- Farmers:Agricultural cooperatives in Japan and the United States demand single-contract accountability. Japanese precision agriculture clusters particularly favor full-stack providers over multi-vendor integration risk.
- Research Institutions:Pilot programs test energy harvesting architectures and pharmaceutical traceability applications.
- Manufacturers:Industrial facilities face EPA and ECHA emissions reporting mandates requiring distributed air quality networks.
Institutional buyers anchor contract value; agricultural adopters are climbing the fastest.
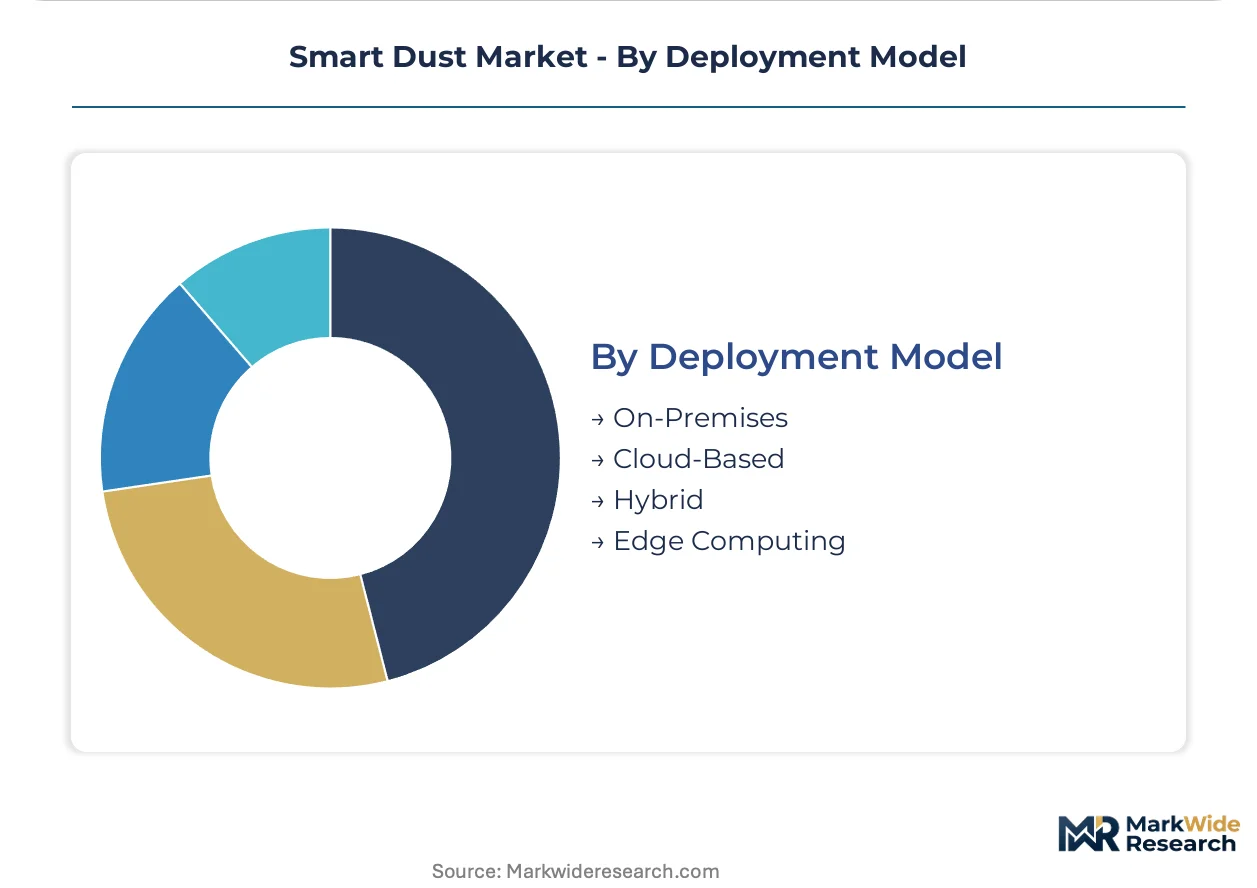
Deployment Model:
Power constraints and data sovereignty requirements fragment architecture preferences across remote field sites and regulated facilities.
- Edge Computing:Localized processing reduces radio transmission duty cycles, extending operational lifespan for battery-constrained deployments. Military surveillance arrays in denied-access environments specify edge architectures to minimize detectable RF signatures.
- Hybrid:Combinations of on-premises processing with cloud analytics balance latency against computational depth. Municipal smart city infrastructure in Japan and Germany favors hybrid models for air quality monitoring compliance.
- On-Premises:Fully localized data retention satisfies defense and healthcare security requirements.
- Cloud-Based:Centralized analytics support large-scale agricultural moisture mapping across distributed farmland.
Security-sensitive applications favor edge computing; scale-dependent analytics favor hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German fabrication clusters where MEMS foundry scarcity commands premium unit economics, while procurement volume leadership sits with United States defense programs absorbing early production at scale.
United States
Defense surveillance programs and EPA ambient monitoring mandates drive procurement concentration. FCC certification requirements for sub-GHz radio architectures filter market access for foreign suppliers. The American Midwest manufacturing corridor faces expanded sensor network mandates for industrial emissions compliance.
Germany
REACH chemical compliance and precision agriculture pilots absorb significant smart particle volumes. ECHA monitoring standards tighten particulate detection thresholds for Ruhr region industrial facilities. Bavarian MEMS foundries anchor aerospace-grade fabrication protocols for defense contractors.
Japan
METI-backed precision agriculture clusters and municipal smart city infrastructure create integrated procurement channels. JIS standards for wireless sensor interoperability shape product certification requirements. Farm operators in Kanto and Kansai regions prioritize full-stack provider accountability over multi-vendor integration.
India
Government irrigation efficiency programs and pharmaceutical traceability pilots expand addressable demand. CDSCO scrutiny of implantable biosensors extends certification timelines for medical-grade variants. Agricultural districts in Maharashtra and Gujarat pilot soil-embedded moisture mapping for water-stressed farming operations.
United Kingdom
Environmental compliance mandates and research institution pilot programs sustain niche procurement volumes. The national pharmaceutical regulator's classification of passive smart particles determines multi-year compliance pathways for therapeutic applications. London-based municipal utilities specify LoRaWAN interoperability for air quality infrastructure deployments.
Smart Dust Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in MEMS fabrication and radio architecture design. The vendor base stratifies across three tiers: full-stack providers delivering hardware-software-deployment packages, semiconductor fabricators with captive MEMS capacity, and specialized radio engineering houses. Dominant competitive moves include strategic partnerships anchoring government procurement channels and portfolio diversification into energy-harvesting architectures.
Among networking infrastructure providers, Cisco Systems occupies a position exemplifying platform-tier consolidation. Honeywell International and Analog Devices represent distinct archetypes within the component-specialist segment, with the former anchoring aerospace-grade manufacturing protocols and the latter sitting within precision signal-processing architectures for low-power communication endpoints.
| Leading Market Players |
|---|
| Cisco Systems |
| Honeywell International |
| Analog Devices |
| Texas Instruments |
| STMicroelectronics |
| IBM Corporation |
| Intel Corporation |
| NXP Semiconductors |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors from Japanese MEMS foundries to United States defense contractors carry unit economics that concentrate pricing power among aerospace-grade fabricators, while downstream buyers face widening spreads between configured-to-order surveillance arrays and standard agricultural sensor kits.
Pricing Analysis
The customization-premium spread separates military-specified unattended ground sensor arrays from commercial precision agriculture kits by factors tied to ISO 13485 certification tiers and MEMS foundry allocation priority. Contract-based long-term offtake dominates defense procurement, with price differentiation driven by aerospace-grade reliability protocols and volume scale commitments. Cost compression in commercial-grade smart particles is intensifying because limited foundry capacity forces agricultural buyers into queue-based allocation. Government agencies exhibit lowest price sensitivity due to mission-critical requirements; Indian irrigation cooperatives face acute budget constraints that favor standard-tier soil-embedded variants.
Supply Chain Analysis
Export-control regimes restricting dual-use MEMS fabrication technology limit component flows from Japan and Germany to non-allied defense programs, concentrating supply among ITAR-compliant facilities. Raw material dependencies draw from rare earth elements for magnetostrictive transducers, silicon wafers from Taiwanese foundries, and specialized packaging substrates from South Korean suppliers. Single-source vulnerability pervades aerospace-grade MEMS capacity, where Bavarian and Kanto fabrication clusters anchor production. Distribution runs through defense procurement channels for military applications and agricultural cooperative aggregators for soil-embedded deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart dust sits in early-cycle expansion as pharmaceutical traceability pilots and Indian irrigation efficiency programs accelerate penetration beyond defense-centric origins.
For Market Incumbents: Build captive MEMS foundry capacity as the defensive moat against fabless entrants. Anchor long-term contracts with United States surveillance programs to lock allocation priority. Invest in ISO 13485 certification pathways to capture pharmaceutical traceability demand before medical-grade competitors consolidate.
For New Entrants and Emerging Players: Indian precision agriculture districts present the most penetrable white-space for soil-embedded moisture sensors. Target Maharashtra and Gujarat irrigation cooperatives with full-stack hardware-software-deployment packages that mirror Japanese farm operator preferences. Pursue CDSCO pre-certification engagement to shorten medical-grade launch timelines.
For Investors and Strategic Acquirers: Specialized radio engineering houses with sub-milliwatt design expertise represent priority acquisition targets as RF talent scarcity intensifies. Frame long-term viability around energy-harvesting architecture transitions that displace battery-dependent models. Watch EPA ambient monitoring standard tightening as the inflection signal for industrial sensor network procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Aerospace-grade fabrication scarcity in Japan and Germany commands allocation priority for defense contractors. |
| Energy Harvesting Architecture Migration | Ambient light and vibration-powered designs extend operational timelines in denied-access military environments. |
| LoRaWAN Protocol Certification | IEEE 802.15.4 alignment enables interoperability across Japanese municipal smart city infrastructure deployments. |
| Pharmaceutical Traceability Partnership | Ingestible smart particle pilots with CDSCO engagement open therapeutic category regulatory pathways. |
| Precision Agriculture Full-Stack Packaging | Single-contract accountability reduces multi-vendor integration risk for Japanese and Indian farm cooperatives. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of defense procurement databases, EPA emissions compliance filings, and MEMS foundry capacity disclosures. Interviews with aerospace procurement officers, agricultural cooperative managers, biomedical regulatory consultants, and MEMS fabrication engineers informed demand-side and supply-side validation. Top-down market sizing from macro sensor network expenditure trends triangulates against bottom-up unit economics from foundry utilization rates and bill-of-materials analysis.
Forecast inputs incorporate product type segmentation across microelectromechanical systems, smart particles, wireless sensors, and nanotechnology variants; application segmentation spanning military, environmental, healthcare, and agricultural use-cases; and deployment model differentiation between edge computing and hybrid architectures. CAGRs derive from adoption curve modeling across defense procurement cycles, EPA mandate implementation timelines, and pharmaceutical pilot program scaling patterns. Energy harvesting technology maturation and sub-GHz radio miniaturization trajectories shape unit cost decline assumptions across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in rare earth element pricing, semiconductor capital expenditure cycles, or defense budget authorization trajectories would shift the trajectory. Material shifts in FDA classification determinations for implantable biosensors, ECHA REACH enforcement intensity, or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market