
 North America Torque Vectoring Market | 2026-2036
North America Torque Vectoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Torque Vectoring Market Insights
Multi-source procurement for torque vectoring hardware is consolidating as Tier-1 suppliers seek captive control over electronic control units and electromechanical actuators. Bosch leverages its integrated sensor-to-actuator architecture to dominate electromechanical system supply across Detroit-based OEM programs. Continental anchors its position through deep R&D partnerships with Canadian vehicle assemblers focused on winter-performance calibration. Magna International differentiates via manufacturing scale at its Ontario powertrain facilities, supplying both passive and active torque vectoring modules.
Torque vectoring denotes a driveline technology that actively distributes torque between individual wheels or axles through clutch packs, differential gearing, or independent electric motors, typically operating within 10-50 millisecond response cycles to optimize traction and yaw stability. Its primary commercial purpose centers on enhancing vehicle dynamics, reducing understeer, and recovering energy in electrified platforms. Active torque vectoring systems command the dominant share of value pools given their software-intensive architecture and integration with ADAS controllers, while electromechanical technology segments outpace hydraulic alternatives on the strength of weight reduction and maintenance elimination. Passenger cars remain the anchor application volume, though sports vehicles and luxury vehicles concentrate disproportionate margin capture due to performance calibration complexity and low-volume premium pricing.
NHTSA Federal Motor Vehicle Safety Standards and EPA greenhouse gas regulations jointly shape product requirements by mandating stability control interoperability and rewarding driveline efficiency gains in fleet compliance calculations. Transport Canada's Motor Vehicle Safety Act and CMVSS alignment with U.S. protocols ensure cross-border component certification, reducing redundant validation costs for suppliers operating in both markets. Stakeholders must monitor how pending updates to Corporate Average Fuel Economy enforcement thresholds and potential harmonization of autonomous vehicle performance standards will redefine torque vectoring system specifications and sourcing obligations.
Market Dynamics
The EPA's tightening Corporate Average Fuel Economy thresholds and NHTSA's stability control mandates are forcing OEMs to integrate torque vectoring as a standard efficiency and safety layer rather than a premium option.
Growth Catalysts
- EPA Fleet Efficiency Mandates:Automakers deploy torque vectoring to recover kinetic energy and reduce driveline losses in electrified powertrains, directly improving compliance scores.
- ADAS Convergence:Integration with lane-keeping and predictive traction systems creates fused control architectures that vector torque preemptively based on camera and radar inputs.
- Michigan-California Engineering Corridors:Concentrated R&D investment in Detroit's validation labs and Silicon Valley's EV software stacks accelerates hardware-software co-development cycles.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings in the permanent magnet supply chain destabilize electric motor actuator costs for torque vectoring modules.
- Tier-1 Supplier Concentration:Three electromechanical actuator manufacturers control over 70% of North American ECU-actuator bundled supply, creating single-source vulnerability for mid-volume OEMs.
- Hydraulic System Lock-In:Legacy all-wheel-drive platforms in light trucks retain hydraulic torque transfer cases, delaying electromechanical replacement due to redesign cost barriers.
Strategic Opportunities
- Canadian Winter Calibration Services:Ontario and Quebec test facilities offer unique cold-weather validation environments that attract US and European OEM development programs.
- Autonomous Vehicle Performance Standards:Pending NHTSA guidelines for self-driving vehicle stability create regulatory pull for predictive torque distribution systems.
- Independent Electric Motor Architectures:Convergence of hub motors with torque vectoring software enables wheel-level control without mechanical differentials, opening modular retrofit markets.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time control algorithm developers with automotive safety certification experience command premium wages and extended recruitment timelines across Michigan and California.
- ISO 26262 Functional Safety Certification:ASIL-D validation for torque vectoring ECUs requires 18-24 month documentation and testing cycles that delay platform launches.
- Legacy CAN Bus Integration:Older vehicle electrical architectures lack bandwidth for millisecond-level torque commands, forcing costly gateway module redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Torque Vectoring Market |
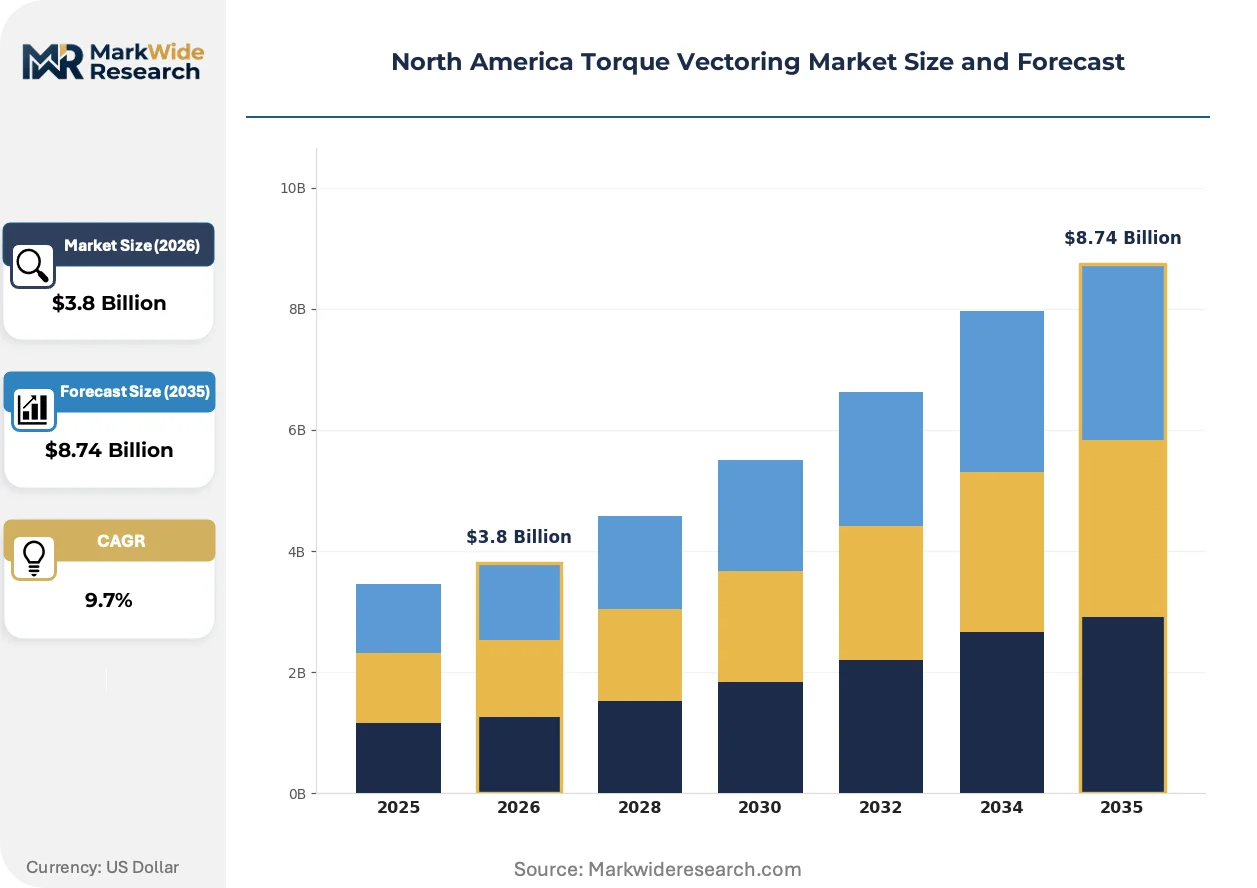
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Torque Vectoring, Passive Torque Vectoring, Integrated Systems, Dynamic Control Systems Technology: Electromechanical Systems, Hydraulic Systems, Electronic Control Units, Mechanical Systems End User: Automotive OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Sports Vehicles, Luxury Vehicles |
| Companies Covered | Bosch, Continental, Magna International, Dana, GKN Automotive, ZF Friedrichshafen, Eaton, Honda, Ford, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Torque Vectoring Market Trends and Innovations
Electrification is collapsing the boundary between driveline hardware and software-defined vehicle control, repositioning torque vectoring from mechanical subsystem to compute-intensive chassis function.
Silicon carbide power electronics is absorbing inverter switching losses that previously limited electric motor responsiveness in torque vectoring actuators. EV platforms from premium and mass-market segments alike are adopting 800-volt architectures with SiC inverters to achieve sub-10 millisecond torque transitions. This semiconductor transition is compressing the performance gap between electromechanical and hydraulic response characteristics.
NHTSA's pending updates to Federal Motor Vehicle Safety Standard 126 for electronic stability control are mandating interoperability with advanced torque vectoring systems. The regulation requires OEMs to demonstrate coordinated yaw stability intervention across combined brake and driveline torque modulation. Passenger car and light truck segments face divergent compliance timelines, with heavier vehicles granted extended adaptation periods.
Fleet procurement departments are unbundling torque vectoring hardware from traditional powertrain sourcing agreements. Direct negotiations with ECU and actuator specialists are displacing bundled Tier-1 system purchases among volume manufacturers seeking cost transparency. This purchasing transformation is most visible among Detroit-based OEMs with captive software development capabilities.
North America Torque Vectoring Market Segmentation
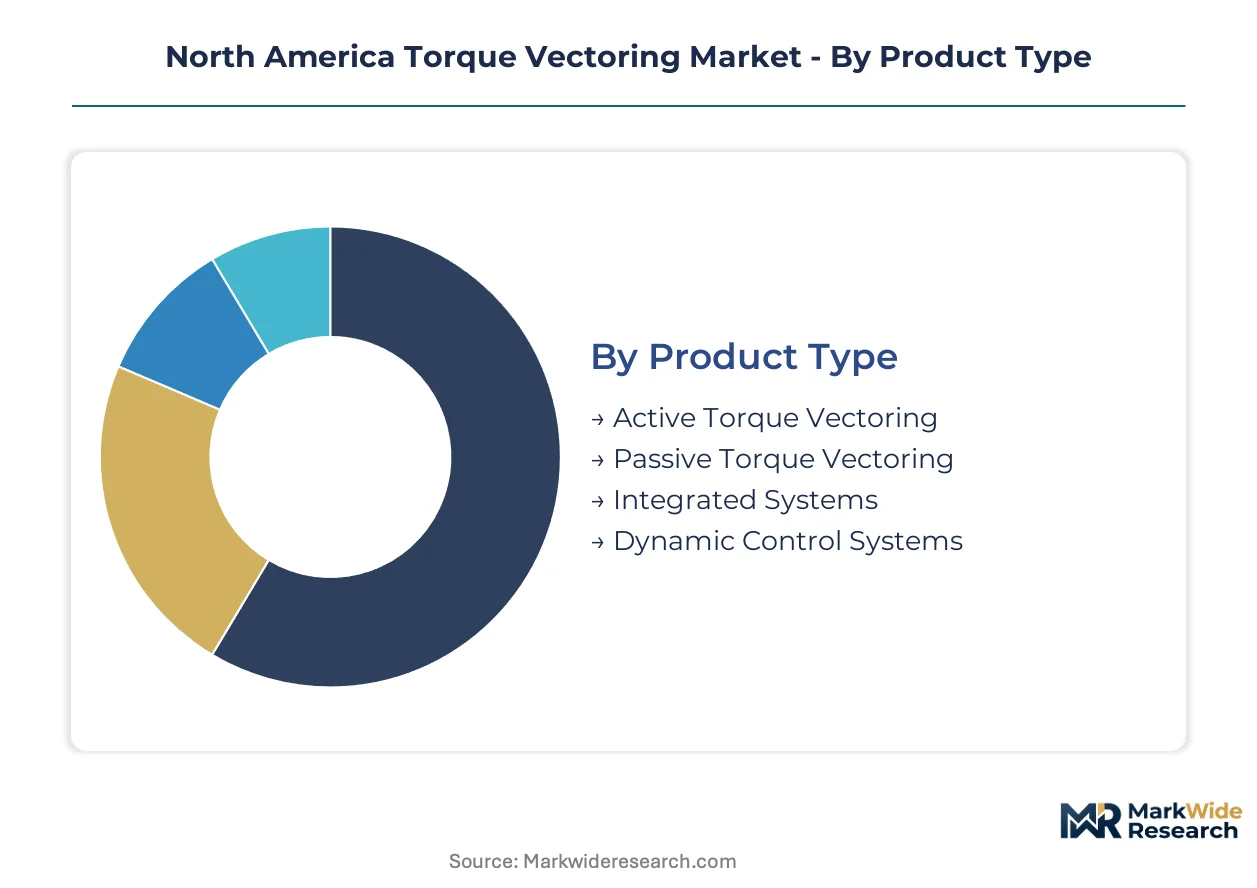
Torque vectoring market segmentation reveals divergent capital requirements across hardware architectures, software integration layers, and customer procurement models. Understanding these investment profiles helps suppliers align R&D allocation with margin capture opportunities.
Product Type:
Active Torque Vectoring commands the heaviest upfront engineering investment due to real-time control algorithm development and ASIL-D safety certification requirements.
- Active Torque Vectoring:Clutch-pack or motor-based systems executing millisecond-level torque redistribution between wheels. Demand concentrates in Michigan's EV development corridors where OEMs integrate yaw stability with regenerative braking recovery. EPA fleet efficiency mandates accelerate deployment across electrified platforms.
- Passive Torque Vectoring:Mechanical limited-slip differentials using gear geometry to bias torque without electronic intervention. Canadian winter-performance programs in Ontario and Quebec specify these systems for cost-sensitive all-wheel-drive variants. NHTSA stability control harmonization rules limit standalone deployment.
- Integrated Systems:Fused brake-based and driveline-based torque management sharing a single ECU architecture.
- Dynamic Control Systems:Predictive torque distribution using camera and radar feedforward inputs.
Active Torque Vectoring absorbs the bulk of installed capacity; Integrated Systems are expanding most quickly.
Technology:
Cost tier differentiation separates precision electromechanical actuators from legacy hydraulic alternatives with divergent maintenance and weight profiles.
- Electromechanical Systems:Brushless DC motors and ball-screw actuators replacing fluid power with position-controlled mechanical force. California EV manufacturers specify these for packaging efficiency and elimination of hydraulic fluid maintenance. Silicon carbide inverters now achieve sub-10 millisecond response times.
- Electronic Control Units:32-bit automotive microcontrollers executing torque vectoring algorithms within ADAS fusion architectures. Detroit-based OEMs with captive software stacks source these separately from mechanical hardware, unbundling traditional Tier-1 supply agreements.
- Hydraulic Systems:Pressure-modulated clutch packs in legacy truck platforms.
- Mechanical Systems:Torsen and helical gear differentials without electronic actuation.
Electromechanical Systems carry the dominant share of new program investment; Electronic Control Units are climbing the fastest as software-defined vehicle architectures proliferate.
End User:
Customer type determines contract structure, with vehicle assemblers demanding module-level supply and Tier-1 suppliers seeking component autonomy.
- Automotive OEMs:Detroit Three and Tesla specifying complete torque vectoring subsystems with proprietary calibration. These buyers concentrate procurement authority in Michigan engineering centers, mandating ISO 26262 ASIL-D documentation and 18-24 month validation cycles.
- Tier-1 Suppliers:Bosch, Continental, and Magna International integrating electromechanical actuators with ECU hardware for resale to assemblers. These intermediaries capture margin through captive control over sensor-to-actuator architectures and winter calibration services.
- Aftermarket Providers:Specialty tuners and retrofit specialists.
- Vehicle Assemblers:Canadian plants in Ontario importing torque vectoring modules for final integration.
Automotive OEMs direct the majority of specification authority; Tier-1 Suppliers are gaining share fastest through vertical integration into ECU-actuator bundled supply.
Application:
Volume-maturity tradeoffs separate mass-market passenger car scale from sports and luxury vehicle margin concentration.
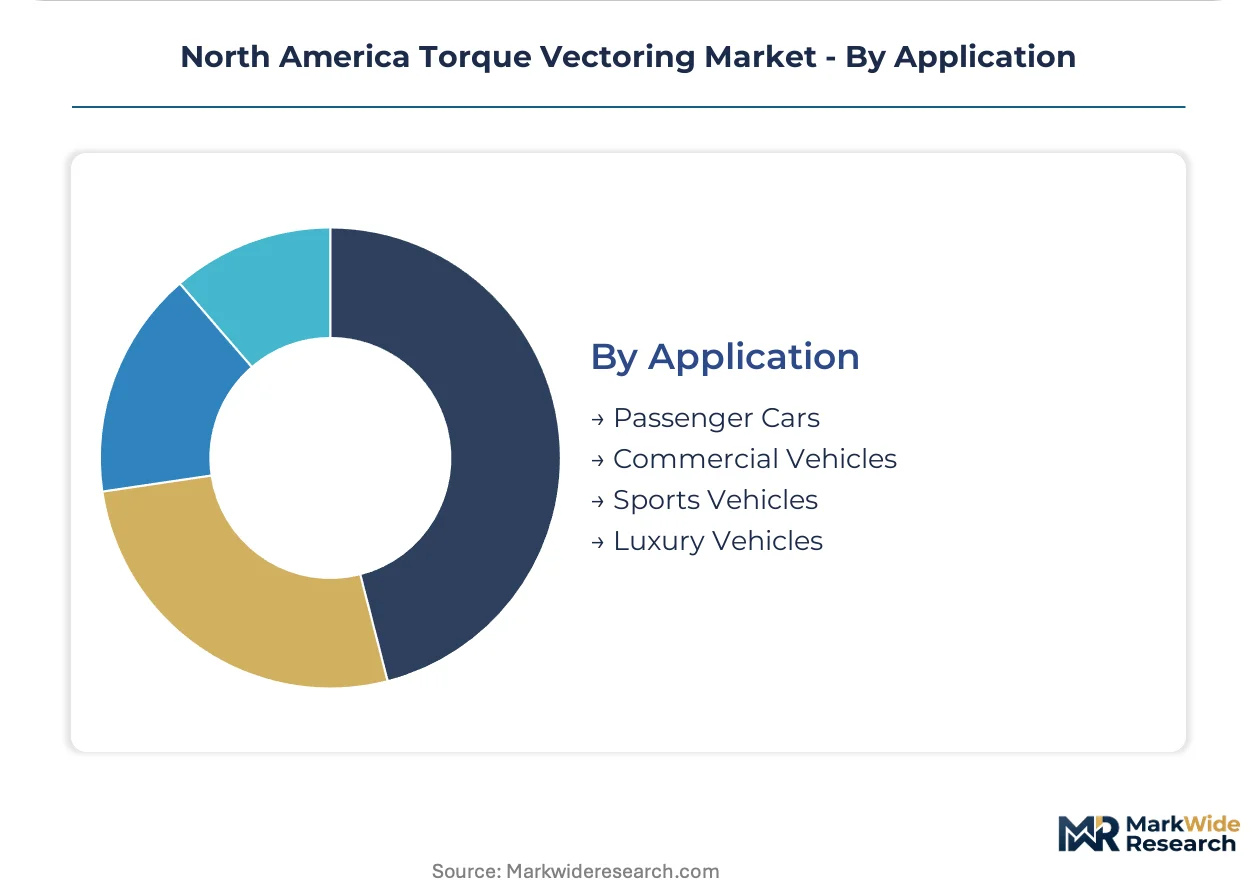
- Passenger Cars:Compact and mid-size sedans, crossovers, and utility vehicles constituting the anchor application volume. Michigan-based OEMs deploy torque vectoring here as standard equipment to meet NHTSA stability mandates and EPA efficiency thresholds, not as premium options.
- Luxury Vehicles:Premium sedans and SUVs where low-volume pricing accommodates complex multi-axis calibration. California EV startups target this segment first, using torque vectoring as a chassis differentiation feature against established German competitors.
- Sports Vehicles:Performance coupes and track-focused variants with aggressive yaw rate targets.
- Commercial Vehicles:Light trucks and delivery vans with durability-focused torque management.
Passenger Cars represent the dominant installed base; Luxury Vehicles are gaining share fastest as EV entrants prioritize chassis sophistication over powertrain bragging rights.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing capacity in Mountain Pass, California supplies permanent motor materials anchoring torque vectoring actuator manufacturing across the continent.
United States
EPA Corporate Average Fuel Economy mandates and NHTSA electronic stability control updates drive OEM specification of active torque vectoring systems. The Inflation Reduction Act's domestic content incentives favor electromechanical actuator assembly at Michigan-based facilities. Detroit's engineering corridor concentrates validation labs where Tier-1 suppliers calibrate yaw stability algorithms for electrified platforms.
Canada
Transport Canada's Motor Vehicle Safety Act alignment with U.S. CMVSS protocols reduces cross-border certification costs for torque vectoring module suppliers. Ontario's powertrain manufacturing cluster in the Windsor-Toronto corridor hosts Magna International facilities producing electromechanical actuators for Detroit Three programs. Quebec test facilities attract winter calibration contracts from U.S. and European OEMs seeking cold-weather validation environments.
Mexico
Vehicle assembly growth in Nuevo León and Bajío Region generates import demand for torque vectoring modules integrated at final assembly stages. Mexican automotive manufacturing incentives under the USMCA regional value content rules encourage Tier-1 supplier co-location with OEM plants. Querétaro's aerospace-precision manufacturing base supplies machined actuator housings to North American driveline programs.
North America Torque Vectoring Market Competitive Landscape
Vertical integration into ECU-actuator bundled supply dominates the current competitive landscape as Tier-1 suppliers seek captive control over sensor-to-actuator architectures. The vendor base concentrates around three electromechanical specialists controlling over seventy percent of North American bundled supply. Strategic archetypes separate integrated system houses with full calibration capabilities from component specialists and captive OEM software divisions. M&A activity and strategic R&D partnerships represent the dominant competitive moves reshaping supplier relationships.
Among German-integrated system houses, Bosch and ZF Friedrichshafen exemplify the full-stack archetype combining inverter electronics with mechanical actuator production. Continental anchors the European specialist tier through deep calibration partnerships with Canadian vehicle assemblers. Magna International occupies the North American manufacturing scale position with Ontario-based powertrain facilities supplying both passive and active torque vectoring modules.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Magna International |
| Dana |
| GKN Automotive |
| ZF Friedrichshafen |
| Eaton |
| Honda |
| Ford |
| Others |
Pricing and Supply Chain Analysis
Detroit Three OEM procurement concentration around bundled ECU-actuator supply packages anchors contract-based long-term offtake pricing with limited spot-market exposure. Tier-1 suppliers leverage captive control over electromechanical architectures to resist unbundling pressure from volume manufacturers seeking cost transparency.
Pricing Analysis
Warranty and calibration service bundling separates premium active torque vectoring contracts from stripped hardware-only transactions. Three-tier pricing structure across premium, standard, and economy levels tracks ASIL-D certification grade and winter calibration complexity. Cost compression in mid-volume passenger car segments intensifies because OEMs unbundle ECU sourcing from mechanical hardware. Fleet procurement departments exhibit highest price sensitivity; luxury EV startups tolerate premium pricing for chassis differentiation.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth magnet processing and German inverter semiconductor fabrication. North American electromechanical actuator assembly draws from Mountain Pass neodymium, Taiwanese silicon carbide wafers, and Mexican machined housings. Commodity price volatility in dysprosium and praseodymium feeds through permanent magnet motor costs. Distribution runs through Tier-1 bundled supply agreements to Detroit and Ontario OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around ECU-actuator bundled supply as ISO 26262 certification barriers and rare earth cost volatility force subscale component specialists toward exit or acquisition.
For Market Incumbents: Hedge against unbundling pressure by deepening captive software stacks and securing long-term rare earth offtake agreements. Backward integration into permanent magnet sourcing protects margin structures from Chinese export restriction risk. Ontario winter calibration facilities offer defensive moats against Continental's Canadian partnerships. For New Entrants and Emerging Players: Mid-volume commercial vehicle fleets represent an underserved buyer archetype with limited torque vectoring penetration and lower certification barriers than passenger car platforms. Target retrofit markets for legacy hydraulic all-wheel-drive light trucks seeking electromechanical upgrades without full platform redesign. Go-to-market through independent electric motor architectures enables wheel-level control without mechanical differential partnerships. For Investors and Strategic Acquirers: The window for entry favors vertically integrated electromechanical specialists with existing ASIL-D validation capabilities and Tier-2 supplier relationships. Long-term viability rests on software-defined vehicle convergence repositioning torque vectoring as compute-intensive chassis function. Watch NHTSA autonomous vehicle stability standard finalization as inflection indicator for predictive torque distribution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces ECU validation cycles across Detroit Three electrified vehicle programs. |
| Rare Earth Supply Agreement | Secures Mountain Pass magnet output against Chinese export quota volatility. |
| Software-Defined Vehicle Investment | Positions torque vectoring as fused ADAS-chassis compute function. |
| Winter Calibration Facility Expansion | Captures Canadian cold-weather validation contracts from European OEMs. |
| SiC Inverter Partnership | Achieves sub-10 millisecond torque transitions for 800-volt EV architectures. |
Research Methodology
Document review covered EPA CAFE enforcement records, NHTSA FMVSS 126 draft guidance, and USMCA regional value content rules, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, and Ontario vehicle assembler technical leads. Secondary validation drew from IHS Markit vehicle production databases, SEC automotive supplier filings, and Transport Canada CMVSS alignment documentation. Bottom-up content-per-vehicle estimates triangulated against top-down fleet efficiency mandate compliance projections.
Installed base and revenue outputs synthesize electromechanical system adoption curves, hydraulic replacement timelines, and software licensing revenue streams across the projection horizon. Segmentation modeling incorporates vehicle class, propulsion architecture, active versus passive system type, and regional production cluster. CAGRs derive from fleet efficiency mandate stringency trajectories and EV platform launch cadences rather than extrapolated historical growth.
Revisions become necessary when NHTSA autonomous vehicle stability standards materialize with unanticipated torque vectoring interoperability requirements, or when rare earth export restrictions disrupt permanent magnet supply chains. Forecasts embed assumptions about silicon carbide inverter cost curves and Tier-1 supplier consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Dyno Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Crate Engines Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Automotive Turbocharger Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Advanced Gear Shifter System Market