
 Car Drive System Market | 2026-2036
Car Drive System Market Size, Share, and Industry Trends Forecast 2026-2036
Car Drive System Market Insights
Electrification of the powertrain is tilting engineering resources toward integrated motor-inverter-gearbox modules. Bosch Rexroth AG leverages its industrial hydraulics heritage to compete in heavy-duty electric axle development. ZF Friedrichshafen AG anchors its position through in-house production of integrated e-drives for European OEM platforms. Continental AG differentiates via its tire-to-software systems approach spanning torque vectoring and vehicle dynamics control.
A car drive system encompasses the mechanical, hydraulic, and electric assemblies that transmit torque from the power source to the road wheels, typically operating at voltage ranges from 48V mild-hybrid architectures to 800V full-electric platforms and sustaining continuous power outputs exceeding 150 kW in performance variants. Its primary purpose is to modulate traction, efficiency, and vehicle stability across operating conditions. Electric technology is capturing the fastest expansion as OEMs phase out pure internal combustion programs, while all-wheel-drive configurations sustain premium pricing power in SUV and crossover segments where torque distribution complexity elevates system value. Hydraulic drive systems occupy declining share in passenger applications but retain defensive positions in commercial vehicle off-highway sectors where peak torque density requirements persist.
The EPA enforces Corporate Average Fuel Economy standards that directly constrain drive system efficiency thresholds in the United States, while the EU Green Deal and F-Gas Regulation shape thermal management and refrigerant choices affecting electric drive cooling architectures. China's MIIT administers new energy vehicle credit mandates that accelerate domestic electric drive system localization. Stakeholders must monitor how battery-electric platform standardization across multiple OEMs alters supplier bargaining power and intellectual property control.
Market Dynamics
Platform electrification is compressing development cycles and forcing suppliers to re-architect around integrated e-axle modules rather than discrete component sales. The EPA's Corporate Average Fuel Economy mandates and the EU Green Deal's fleet emissions targets are accelerating this transition faster than legacy tooling depreciation schedules allow.
Growth Catalysts
- EPA CAFE Standards:Stringent efficiency benchmarks in the United States compel OEMs to adopt multi-speed transmissions and electrified drivelines across light-duty portfolios.
- Stuttgart-Munich Engineering Cluster:Concentrated R&D infrastructure in southern Germany enables rapid prototyping of 800V silicon carbide inverter systems for premium platforms.
- Silicon Carbide Power Semiconductors:Wide-bandgap devices reduce switching losses in electric drive inverters, extending vehicle range without proportional battery cost increases.
Market Restraints
- Rare Earth Supply Concentration:Permanent magnet motors depend on neodymium and dysprosium processing dominated by Chinese refining capacity, creating single-source vulnerability.
- Copper Price Volatility:Winding and busbar materials face commodity market swings that compress margin predictability for high-volume e-motor suppliers.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases complicate thermal management system design for liquid-cooled electric drives.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive technology attract localized electric drive manufacturing for domestic and export markets.
- Vehicle-to-Grid Integration:Bidirectional charging capability transforms parked EVs into grid stabilization assets, requiring new inverter control architectures.
- Software-Defined Torque Vectoring:Over-the-air updatable differential control creates recurring revenue potential beyond hardware shipment.
Industry Challenges
- Embedded Systems Talent Scarcity:Functional safety engineering for ISO 26262 ASIL-D rated motor controllers outpaces European and North American university pipeline output.
- Legacy Powertrain Decommissioning:Supplier footprints tied to internal combustion transmission plants face stranded asset risk as OEMs consolidate electrified platform sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Drive System Market |
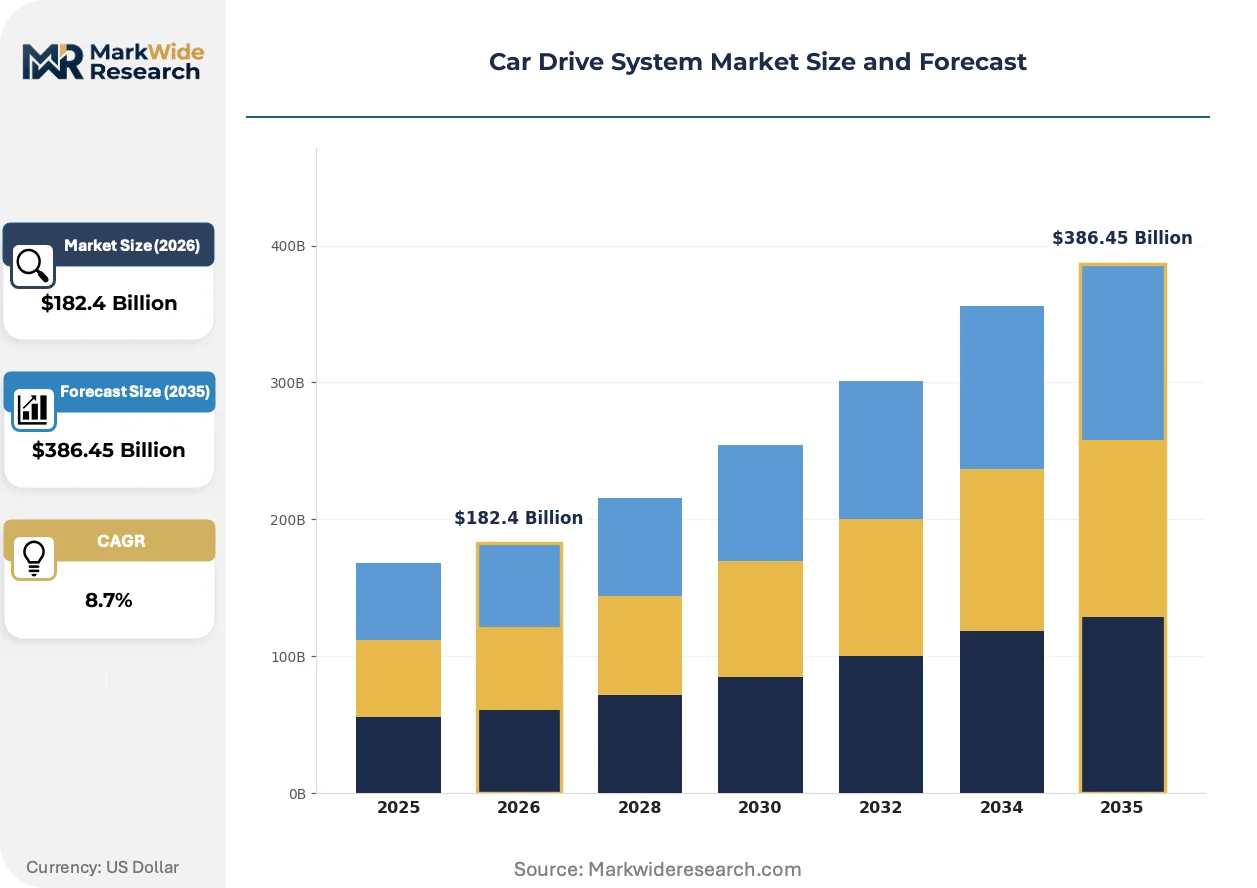
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $386.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanic, Hydraulic, Electric, Hybrid Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Sports Cars Drive Type: AWD, FWD, RWD, 4WD Application: Performance, Safety, Fuel Efficiency, Comfort |
| Companies Covered | Bosch Rexroth AG, ZF Friedrichshafen AG, Robert Bosch GmbH, Nexteer Automotive, JTEKT Corporation, Aisin Corporation, Magna International, Continental AG, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Drive System Market Trends and Innovations
Digital twin integration and model-based systems engineering are collapsing the boundary between hardware design and control software validation. This convergence is shortening prototype-to-production timelines while raising the bar for supplier simulation capabilities.
Silicon carbide MOSFET technology is digitizing power conversion efficiency in 800V architectures. Premium passenger car manufacturers in Germany and South Korea are adopting these devices for next-generation performance EVs. The shift is digitizing thermal management requirements and compressing the competitive window for legacy IGBT suppliers.
The EU Green Deal's 2035 internal combustion phase-out deadline is forcing powertrain supplier portfolio restructuring. Component manufacturers must redirect engineering capacity toward electric axle programs or exit automotive supply chains entirely. Heavy-duty commercial vehicle segments face the steepest compliance cost curves under the new framework.
Fleet procurement departments are consolidating supplier relationships around full-system integrators rather than discrete component vendors. Large-scale ride-hail and logistics operators in the United States now specify complete e-axle modules with guaranteed performance metrics. This behavior concentrates contract value with tier-one suppliers possessing in-house motor, inverter, and gearbox production.
Car Drive System Market Segmentation
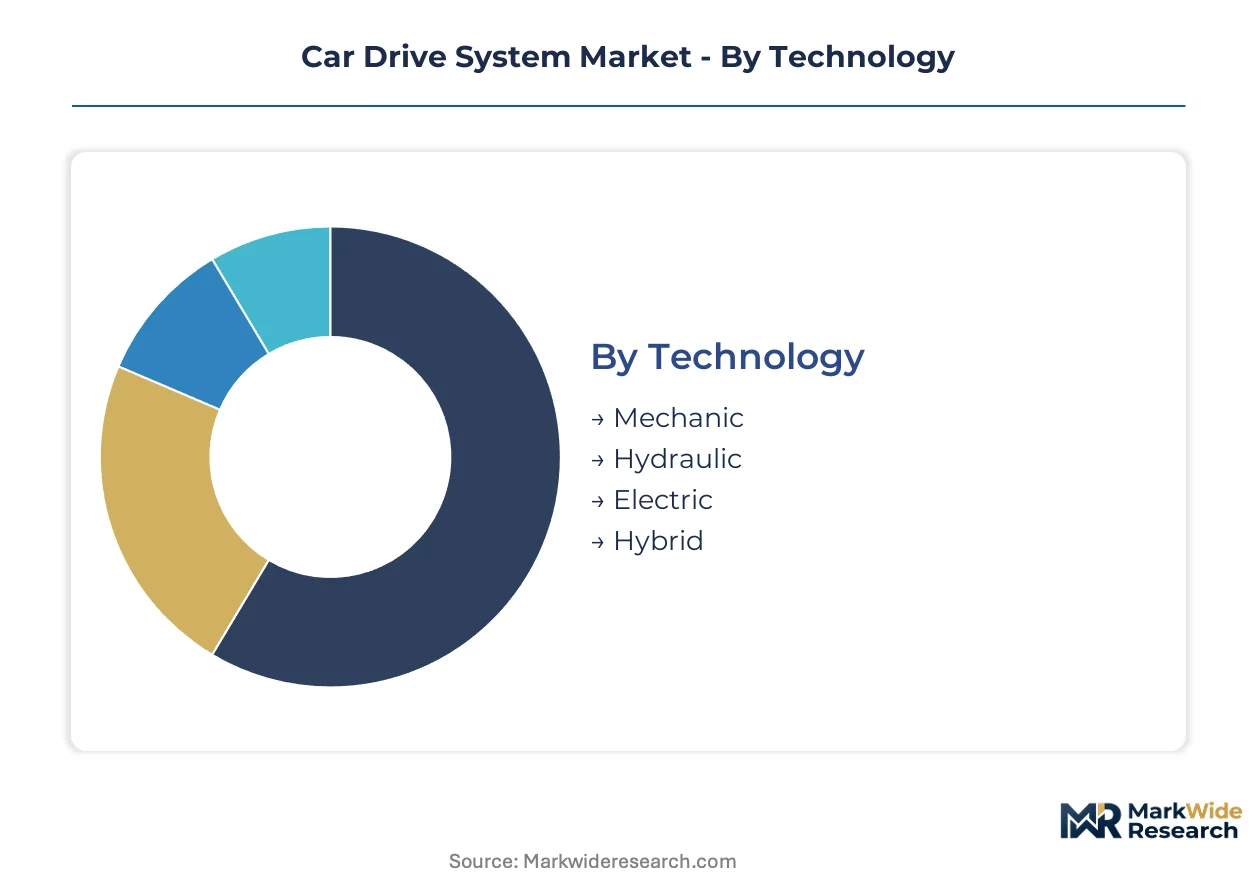
Car drive system segmentation reveals how powertrain architecture choices cascade through vehicle design, procurement strategy, and supplier margin structure. Technology and vehicle type classifications dominate supplier resource allocation, while drive type and application dimensions govern OEM platform engineering decisions.
Technology:
Power source architecture spans from legacy mechanical assemblies through fully electrified torque delivery systems.
- Electric:Integrated motor-inverter-gearbox modules operating at 400V to 800V architectures deliver continuous outputs exceeding 150 kW. Demand concentrates in Germany's Stuttgart-Munich corridor where premium OEMs specify silicon carbide inverter systems for next-generation platforms.
- Hybrid:48V mild-hybrid through full parallel-series architectures bridge combustion and electric-only operation. European passenger car manufacturers deploy these systems to meet EU Green Deal fleet emissions targets without full platform redesign.
- Mechanic:Conventional driveshaft, differential, and transmission assemblies transmit torque from internal combustion engines.
- Hydraulic:Fluid power systems delivering peak torque density for off-highway commercial applications.
The dominant share belongs to Electric, while Hybrid is closing the gap fastest.
Vehicle Type:
Platform scale and duty cycle requirements segment engineering priorities across automotive OEM portfolios.
- SUVs:Elevated curb weights and all-terrain capability requirements demand sophisticated torque vectoring and multi-mode drive systems. North American fleet procurement departments specify complete e-axle modules with guaranteed performance metrics for light truck platforms.
- Passenger Cars:Sedan and hatchback formats prioritize packaging efficiency and NVH reduction in compact drive units.
- Commercial Vehicles:Heavy-duty cycles and payload requirements sustain hydraulic system demand alongside emerging electric axle development.
- Sports Cars:High-performance variants emphasize power-to-weight ratio and thermal management in track-capable configurations.
Volume leadership sits with Passenger Cars, though SUVs command premium system pricing.
Drive Type:
Wheel torque distribution architecture determines hardware complexity and control software requirements.
- AWD:Multi-clutch differentials and torque-vectoring differentials modulate power delivery across axles. South Korean premium manufacturers integrate these systems with vehicle dynamics control for crossover segments.
- FWD:Transverse engine packaging with compact transaxle assemblies dominates mass-market compact and mid-size platforms.
- RWD:Longitudinal powertrain layouts with separate gearbox and differential units persist in performance and luxury applications.
- 4WD:Part-time and full-time systems with transfer case architectures serve off-highway and commercial vehicle duty cycles.
AWD holds the revenue concentration, while 4WD faces steepest electrification transition costs.
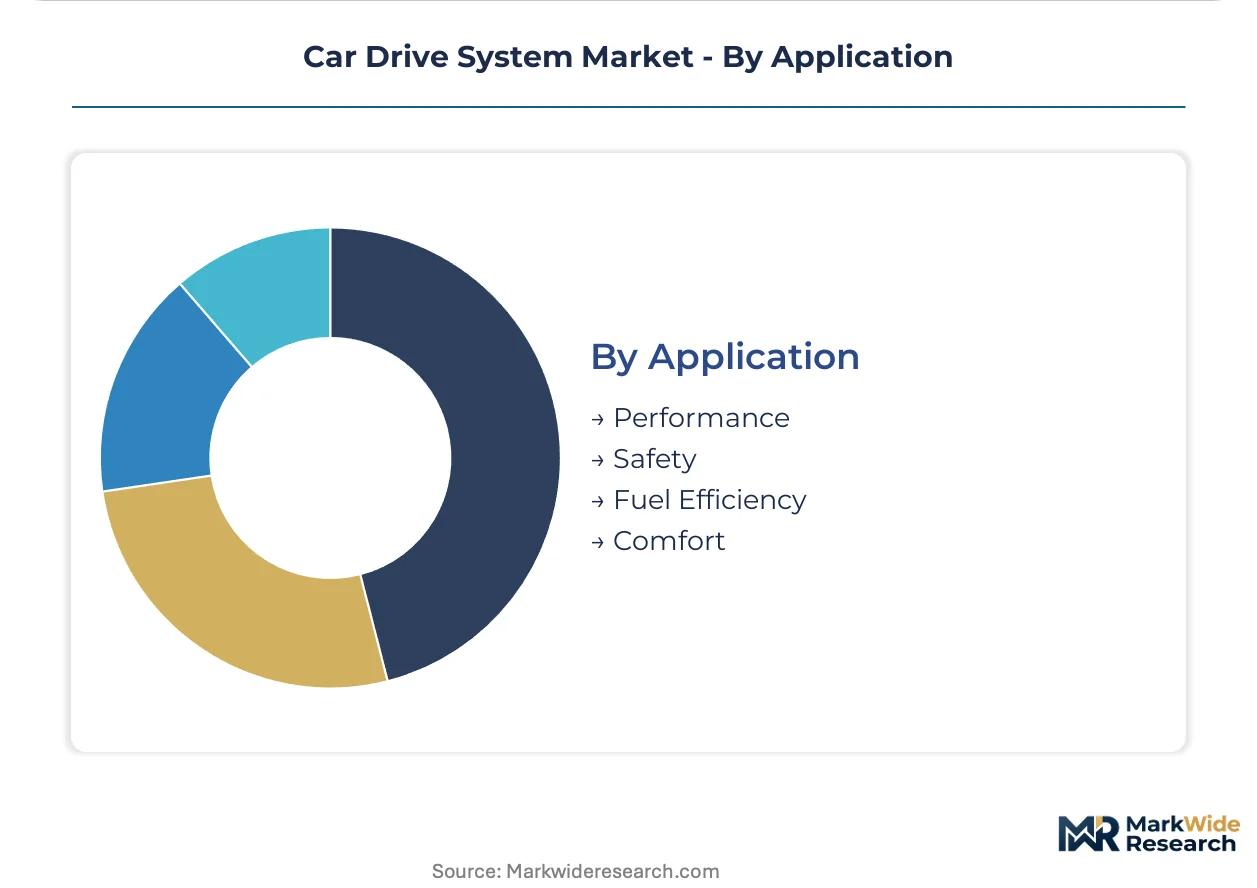
Application:
Functional priority hierarchies shape control system calibration and hardware specification trade-offs.
- Fuel Efficiency:Optimized gear ratios, regenerative braking integration, and thermal management prioritize energy conservation. EPA CAFE standards compel adoption across United States light-duty portfolios.
- Performance:Launch control, traction optimization, and thermal endurance calibration target acceleration and lap time metrics.
- Safety:Electronic stability control integration and predictive torque intervention support collision avoidance and vehicle controllability.
- Comfort:NVH isolation and seamless torque delivery prioritize occupant experience in luxury segments.
Fuel Efficiency anchors procurement specifications, while Performance applications sustain highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium passenger car manufacturers concentrate procurement authority in Germany's Stuttgart-Munich corridor, while fleet operators in the United States specify complete e-axle modules. China's MIIT credit mandates accelerate domestic supplier localization. South Korean premium platforms drive silicon carbide inverter adoption.
United States
Fleet procurement departments at ride-hail and logistics operators now specify complete e-axle modules with guaranteed performance metrics. The EPA's Corporate Average Fuel Economy standards compel multi-speed transmission and electrified driveline adoption across light-duty portfolios. Detroit's engineering base retools around integrated motor-inverter architectures for truck platforms.
Germany
Premium OEMs in the Stuttgart-Munich engineering cluster specify 800V silicon carbide inverter systems for next-generation performance platforms. The EU Green Deal's 2035 internal combustion phase-out deadline forces powertrain supplier portfolio restructuring. Baden-Württemberg's supplier ecosystem redirects engineering capacity toward electric axle programs.
China
Domestic OEMs accelerate platform electrification to capture new energy vehicle credit mandates administered by MIIT. Dual carbon goals at the national level shape thermal management and refrigerant choices affecting electric drive cooling architectures. Yangtze River Delta manufacturing hubs localize permanent magnet motor supply chains.
South Korea
Premium manufacturers integrate all-wheel-drive systems with vehicle dynamics control for crossover segments. The country's national industrial policy supports wide-bandgap semiconductor adoption in next-generation inverters. Seoul Capital Area R&D centers prototype torque-vectoring differentials for export platforms.
India
Production-linked incentives for advanced automotive technology attract localized electric drive manufacturing for domestic and export markets. The central bank's monetary framework influences capital availability for supplier capacity expansion. Tamil Nadu and Gujarat automotive corridors host emerging e-axle assembly operations.
Car Drive System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market structure concentrates contract value with full-system integrators possessing in-house motor, inverter, and gearbox production. Three archetypes dominate: diversified industrial conglomerates with automotive divisions, dedicated automotive powertrain suppliers, and diversified tier-one component manufacturers. Competitive moves center on strategic partnerships for silicon carbide supply security and portfolio diversification into software-defined torque control.
Within the diversified industrial tier, Bosch Rexroth AG and ZF Friedrichshafen AG exemplify channel-controlling positions through integrated e-drive production capabilities. Continental AG occupies a specialist position spanning tire-to-software systems. These three German-based entities anchor supplier consolidation trends as OEMs reduce discrete component vendor relationships.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Nexteer Automotive |
| JTEKT Corporation |
| Aisin Corporation |
| Magna International |
| Continental AG |
| Dana Incorporated |
| Others |
Pricing and Supply Chain Analysis
Rare earth refining concentration in China funnels margin capture downstream toward magnet motor manufacturers and integrated e-axle assemblers. Cost pass-through mechanics in copper windings and silicon carbide substrates determine how commodity volatility transmits to OEM procurement desks.
Pricing Analysis
Cost-plus contracts with copper and rare earth indexation dominate long-term supply agreements between tier-one integrators and OEM platform teams. Three-tier pricing structure across premium 800V silicon carbide systems, standard 400V architectures, and economy-grade 48V mild-hybrid modules reflects performance tier and thermal management complexity. Pricing pressure stems from OEM consolidation around single-source e-axle integrators squeezing component-level margins. Fleet procurement departments exhibit highest price sensitivity due to volume scale, while premium passenger car manufacturers prioritize performance metrics over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for permanent magnet motors and processed rare earth elements. Manufacturing concentrates in China, Germany, and South Korea for power semiconductors, precision gear machining, and motor winding operations. Raw material dependencies rest on neodymium-dysprosium magnet alloys, high-purity copper rod, and silicon carbide wafers. Single-source vulnerability in Chinese rare earth processing creates supply interruption exposure. Distribution runs through tier-one system integrators delivering complete e-axle modules to OEM final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Car drive system demand sits in early-cycle expansion as battery-electric platform proliferation accelerates beyond legacy powertrain replacement rates. Silicon carbide inverter adoption and 800V architecture migration provide structural tailwinds for integrated module suppliers.
For Market Incumbents: Harden silicon carbide supply security through long-term offtake agreements with wafer manufacturers or backward integration into substrate processing. Consolidate engineering talent pools for ISO 26262 ASIL-D motor controller development before functional safety expertise scarcity worsens. Defend against emerging Chinese e-axle exporters by anchoring European premium OEM relationships through co-located R&D facilities in the Stuttgart-Munich corridor. For New Entrants and Emerging Players: Mid-market commercial vehicle fleets in India represent the most penetrable entry point given PLI scheme localization incentives and less consolidated supplier relationships than European or North American markets. Software-defined torque vectoring modules for retrofit AWD systems offer a component-level beachhead without full e-axle integration requirements. Partner with domestic Indian motor manufacturers for permanent magnet supply chain access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive powertrain specialists carrying stranded internal combustion transmission plant footprints. Five-to-ten year viability hinges on successful portfolio pivot to electric axle programs and software control layer development. Watch for OEM platform standardization announcements across multiple brands as the signal indicating supplier consolidation acceleration and valuation compression for non-integrated component vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures wide-bandgap semiconductor access for 800V inverter production without spot market exposure. |
| Platform Standardization Partnership | Reduces engineering duplication across OEM brand portfolios and concentrates contract value with integrators. |
| Software-Defined Torque Control Investment | Creates recurring revenue streams through over-the-air updatable differential calibration beyond hardware shipment. |
| India Manufacturing Footprint Expansion | Captures PLI scheme incentives and positions for domestic market growth plus export tariff advantages. |
| Vehicle-to-Grid Integration Development | Enables bidirectional charging architectures that transform parked EVs into grid stabilization revenue assets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-one supplier procurement directors, aftermarket distribution managers, and dealership operations heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA CAFE compliance filings, and EU Green Deal implementation trackers. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand projections.
Calibration against historical platform adoption curves and technology substitution patterns anchored the analytical framework across the analysis window. Segmentation dimensions included vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from fitted adoption curves weighted by announced OEM platform timelines. Forecast inputs incorporated silicon carbide cost decline trajectories and rare earth supply elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in battery metal prices, central bank interest rate regimes, or trade policy stringency would shift the trajectory. Forecasts reflect documented assumptions about technology cost curves and regulatory enforcement timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Sway Bar Bushing Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Automotive Camshaft Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Crate Engines Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
United Kingdom Automotive Engine Oils Market