
 Wind Alarm Controller Market | 2026-2036
Wind Alarm Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Alarm Controller Market Insights
IEC 61400-12-1 compliance for wind measurement and turbine safety certification is redrawing competitive boundaries in this sector. Vaisala leverages its calibration infrastructure in Finland to sustain premium positioning for offshore-grade controllers. PCE Instruments competes aggressively on cost while anchoring volume sales through German industrial distribution channels.
A wind alarm controller is an electromechanical or solid-state monitoring device that processes real-time wind speed, direction, and gust data against programmable safety thresholds, typically operating across measurement ranges of 0-75 m/s with response latencies under two seconds to trigger automated alerts or equipment shutdowns. Fixed installations dominate revenue contribution due to permanent integration with turbine control systems and port crane operations, while smart controllers represent the fastest-expanding category as edge computing and predictive maintenance protocols penetrate renewable energy asset management. Ultrasonic sensor technology leads new technology adoption by eliminating moving parts and reducing maintenance cycles in harsh marine environments.
FAA obstruction lighting standards for meteorological towers, IEC 61400 turbine safety frameworks, and DNV maritime classification rules collectively mandate redundant wind monitoring for operational licensing across aviation, energy, and shipping sectors. China's GB standards for wind power equipment and the EU F-Gas Regulation on industrial sensors further shape product design requirements and market access conditions. Stakeholders must track evolving certification reciprocity between European notified bodies and emerging Asian test laboratories to anticipate qualification bottlenecks.
Market Dynamics
Ultrasonic sensor technology is decomposing the installed base of mechanical anemometers across offshore wind installations, while IEC 61400-12-1 certification requirements compress procurement cycles and elevate technical barriers for controller suppliers serving Northern European markets.
Growth Catalysts
- IEC 61400-12-1 Certification Mandates:Tightened turbine safety standards in Europe require redundant wind monitoring systems, forcing operators to upgrade legacy controllers and expanding addressable demand for certified suppliers.
- Offshore Wind Expansion:Developers in the North Sea and Baltic Sea are commissioning larger turbine arrays that demand hardened alarm controllers capable of operating in salt-laden, high-vibration marine environments.
- Ultrasonic Sensor Migration:Solid-state wind measurement eliminates moving parts, reducing maintenance intervals and total cost of ownership for remote installations where technician access is expensive.
Market Restraints
- Semiconductor Supply Concentration:Controller manufacturers depend on concentrated Asian sources for ultrasonic transducer chips and precision ADC components, exposing production schedules to geographic supply shocks.
- Calibration Infrastructure Scarcity:IEC 61400-12-1 compliance requires traceable wind tunnel validation, and accredited test facilities remain concentrated in Germany and Finland, creating qualification bottlenecks for new market entrants.
- Mechanical Anemometer Substitute:Mature cup-and-vane technology retains cost advantages in onshore applications with accessible maintenance crews, slowing ultrasonic adoption in price-sensitive segments.
Strategic Opportunities
- Floating Offshore Wind:Emerging platforms in Portugal, Japan, and California require motion-compensated wind measurement systems that integrate alarm controllers with vessel motion sensors.
- Edge Computing Convergence:Smart controllers combining real-time wind processing with predictive maintenance algorithms command premium positioning as asset operators seek to reduce unplanned turbine downtime.
- Port Crane Modernization:Maritime classification societies including DNV are mandating redundant wind monitoring for container handling equipment, opening industrial channels beyond renewable energy.
Industry Challenges
- Embedded Systems Talent Gap:Controller vendors compete for firmware engineers capable of implementing IEC 61508 functional safety protocols in resource-constrained microcontroller architectures.
- Multi-Standard Certification Timelines:Suppliers must simultaneously navigate FAA obstruction lighting rules for meteorological towers, IEC turbine standards, and DNV maritime codes, extending product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Alarm Controller Market |
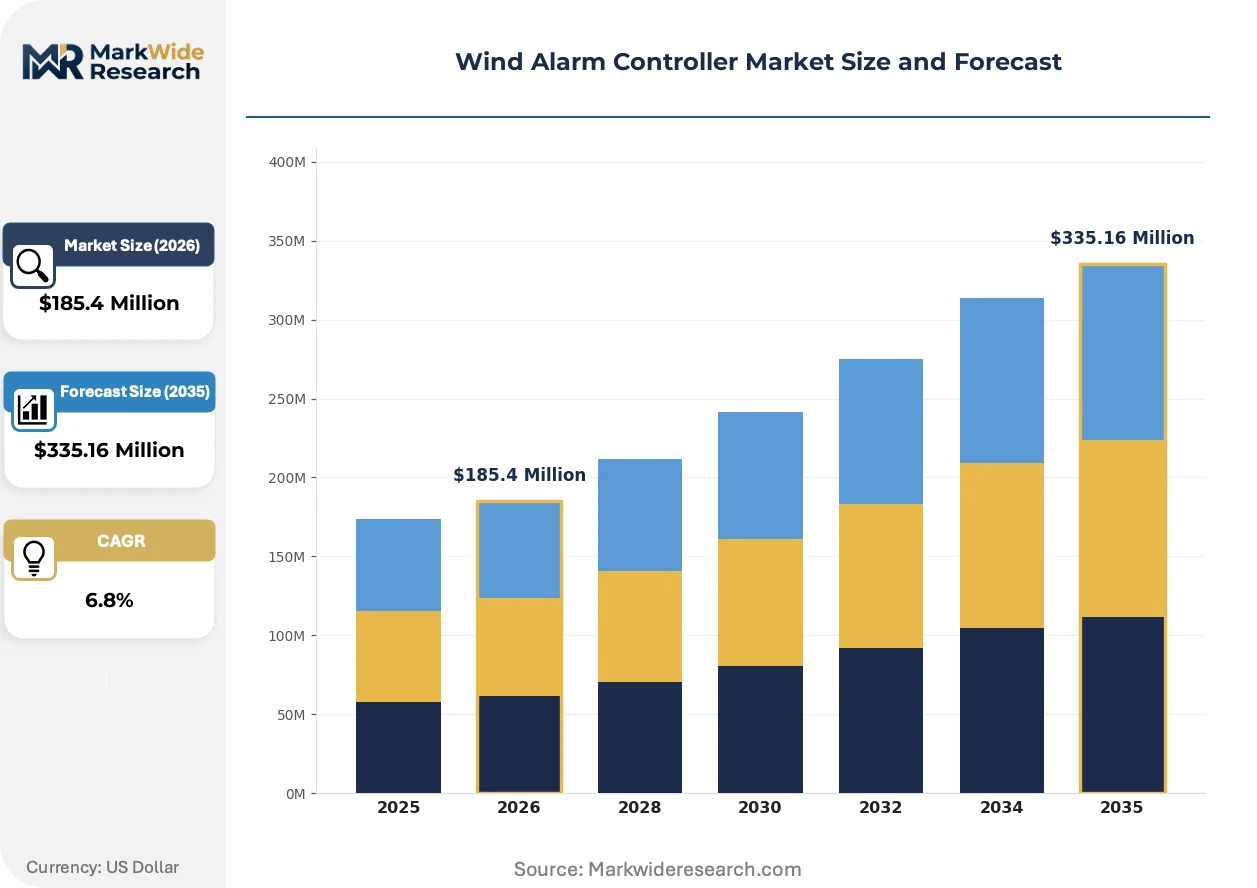
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Installations, Wireless Systems, Smart Controllers Technology: Anemometer-Based, Ultrasonic Sensors, Barometric Pressure, IoT Integration End User: Aerospace, Marine, Civil Engineering, Renewable Energy Installation: Onshore, Offshore, Residential, Commercial |
| Companies Covered | PCE Instruments, Comptus, Maximum Weather Instruments, Belfort Instrument, SCARLET TECH, Davis Instruments, Observator Instruments, Gill Instruments, Vaisala, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Alarm Controller Market Trends and Innovations
Hardware-software decoupling is reshaping how wind alarm controllers are architected, with edge intelligence and predictive algorithms displacing purely electromechanical safety logic and creating new competitive dimensions around data services.
Ultrasonic wind sensing arrays are decomposing the traditional mechanical anemometer supply chain. These solid-state systems measure wind speed and direction through time-of-flight calculations between paired transducers, eliminating bearings and rotating assemblies that fail in marine environments. Offshore wind developers in Denmark and Germany are specifying ultrasonic-only configurations for new turbine platforms. The technology is decomposing maintenance cost structures and compressing the addressable market for replacement parts and field service contracts.
EU F-Gas Regulation restrictions on industrial sensor refrigerants are accelerating design changes in heated anemometer configurations. Manufacturers must reformulate thermal management systems to eliminate prohibited warming fluids while maintaining ice-free operation in sub-zero conditions. Heated ultrasonic variants for Nordic and Baltic installations face the most stringent compliance timelines, with notified bodies in Finland and Germany processing certification renewals through 2027.
Buyers are unbundling hardware procurement from long-term service agreements. Wind farm operators increasingly source controllers through direct manufacturer relationships while contracting predictive maintenance analytics to specialized software vendors. This pattern fragments supplier revenue streams and compresses margins on standalone hardware sales. The shift is most visible in the United States, where independent power producers favor modular procurement to optimize capital deployment across dispersed renewable portfolios.
Wind Alarm Controller Market Segmentation
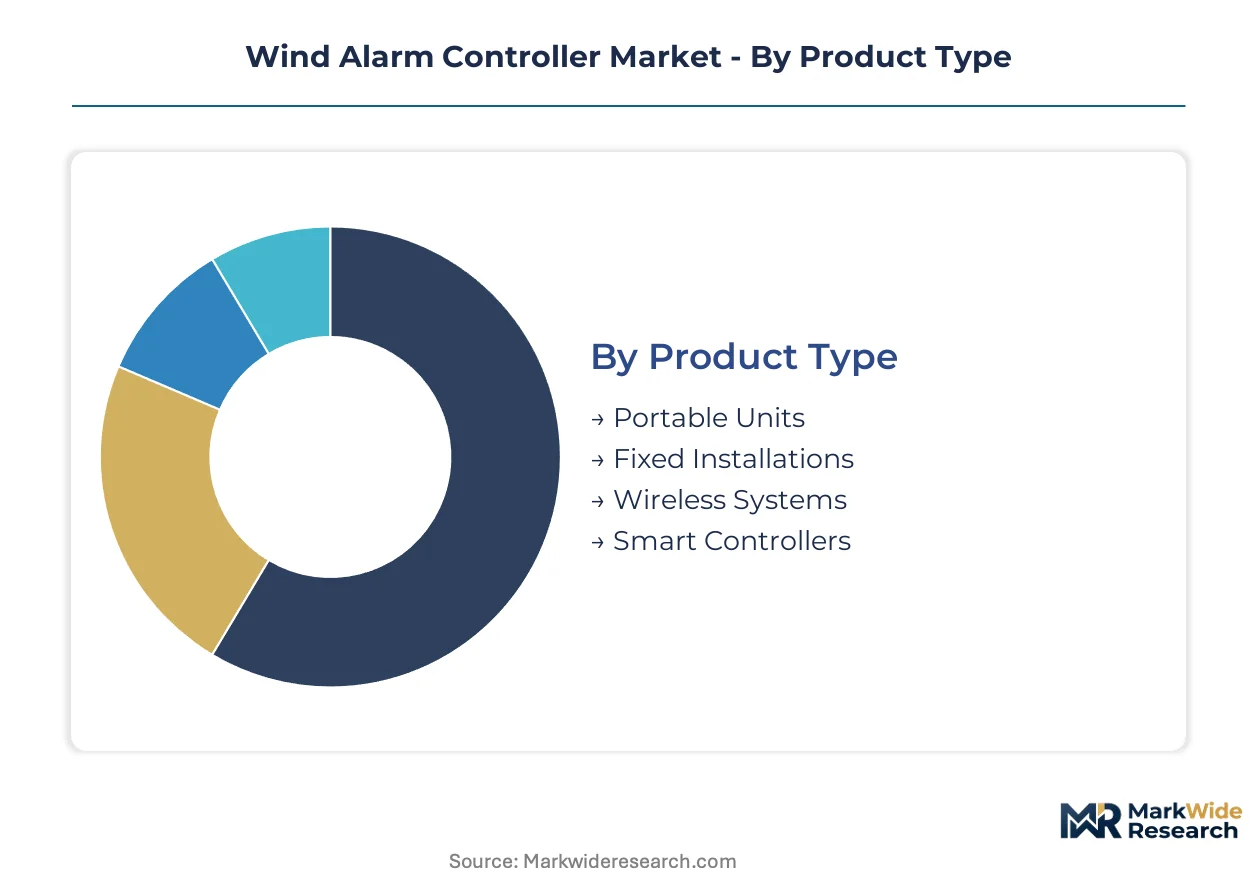
Wind alarm controller procurement splits sharply across certification requirements, sensor architectures, and environmental exposure ratings. Each segmentation axis carries distinct regulatory obligations that reshape supplier qualification and pricing power.
Product Type:
IEC 61400-12-1 certification mandates create tiered compliance burdens that separate certified fixed installations from uncertified portable alternatives.
- Fixed Installations:Permanently mounted electromechanical or solid-state units integrate directly with turbine control systems and port crane safety circuits. Offshore wind developers in Denmark and Germany specify these for all new turbine platforms, driven by DNV maritime classification requirements for redundant monitoring.
- Smart Controllers:Edge-computing devices embed predictive maintenance algorithms and real-time data processing beyond basic threshold alarming. Independent power producers in the United States favor modular procurement of these units to optimize capital deployment across dispersed renewable portfolios.
- Portable Units:Battery-powered or temporary configurations serve construction sites and event staging where permanent infrastructure is impractical.
- Wireless Systems:Radio-linked sensor arrays eliminate cabling runs across large turbine arrays or bridge construction zones.
Established volume favors Fixed Installations; emerging adoption favors Smart Controllers.
Technology:
Sensor architecture determines maintenance cycles, calibration intervals, and total cost of ownership across marine and terrestrial deployments.
- Ultrasonic Sensors:Solid-state transducer pairs measure wind speed through time-of-flight calculations without rotating assemblies. Salt-laden, high-vibration environments in the North Sea and Baltic Sea accelerate displacement of mechanical alternatives, though semiconductor supply concentration in Asia creates procurement risk.
- Anemometer-Based:Cup-and-vane mechanical systems retain cost advantages in onshore applications with accessible maintenance crews. Mature supply chains and simpler calibration requirements sustain volume in price-sensitive segments where IEC certification is not mandated.
- Barometric Pressure:Auxiliary atmospheric sensors supplement wind data for turbulence modeling and icing prediction.
- IoT Integration:Networked connectivity protocols enable centralized fleet monitoring and cloud-based analytics.
Maintenance cost compression favors Ultrasonic Sensors; capital expenditure constraints favor Anemometer-Based systems.
End User:
Industry-specific safety frameworks dictate redundant monitoring requirements and response latency specifications.
- Renewable Energy:Wind farm operators face tightened IEC 61400 turbine safety standards requiring redundant wind monitoring with sub-two-second response latencies. Northern European offshore expansion compresses procurement cycles for certified suppliers.
- Marine:Port crane operations and vessel loading systems fall under DNV classification rules mandating hardened controllers for salt-laden environments. Container handling equipment modernization opens industrial channels beyond energy applications.
- Aerospace:FAA obstruction lighting standards for meteorological towers require certified wind monitoring for aviation safety compliance.
- Civil Engineering:Bridge construction and high-rise building sites deploy temporary monitoring for crane operations and worker safety protocols.
Procurement scale favors Renewable Energy; regulatory expansion favors Marine applications.
Installation:
Environmental exposure ratings and accessibility determine hardware specifications and service contract structures.
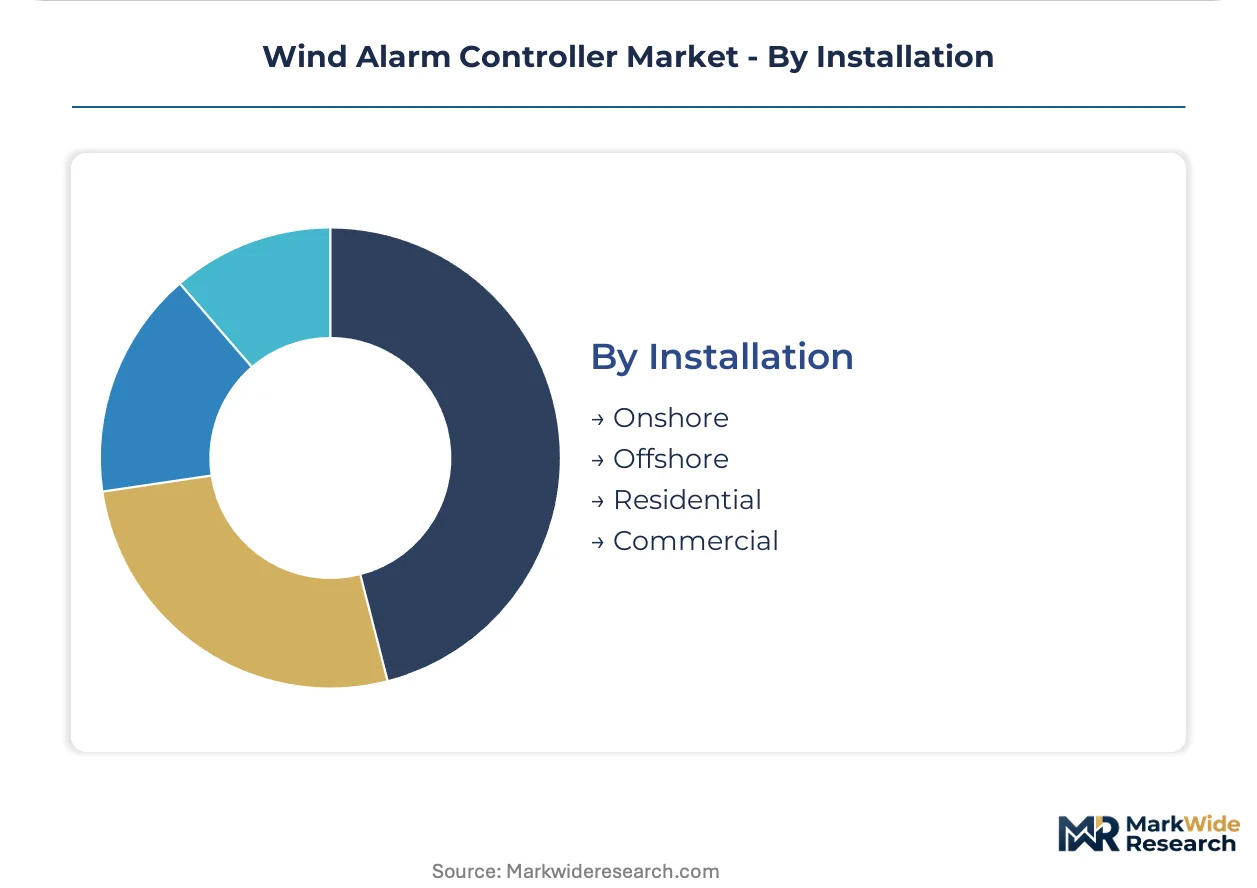
- Offshore:Floating and fixed-bottom turbine platforms demand motion-compensated measurement systems with marine-grade enclosures. Emerging projects in Portugal and Japan require integration with vessel motion sensors.
- Onshore:Land-based wind farms and industrial sites utilize standard environmental protection ratings with periodic technician access for calibration and maintenance.
- Commercial:Industrial facilities and infrastructure projects specify mid-tier durability for moderate exposure conditions.
- Residential:Small-scale renewable installations and private meteorological stations drive demand for simplified, cost-optimized configurations.
Technical complexity favors Offshore; volume accessibility favors Onshore deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dogger Bank offshore wind interconnect anchors United Kingdom demand for marine-grade wind alarm controllers as turbine platforms multiply across the North Sea. German North Sea ports and Baltic Sea arrays drive parallel procurement cycles for certified monitoring systems.
Germany
Offshore wind arrays in the North Sea and Baltic Sea compress procurement timelines for IEC 61400-12-1 certified controllers. The EU F-Gas Regulation forces heated anemometer redesigns through notified bodies in Hamburg and Berlin. Bremerhaven clusters host turbine integration facilities where motion-compensated measurement systems undergo pre-deployment validation.
United States
Independent power producers across Texas and California favor modular smart controller procurement to optimize capital deployment. FAA obstruction lighting standards for meteorological towers mandate redundant wind monitoring for aviation safety compliance. Port modernization in Long Beach and Houston drives DNV-classified crane controller installations beyond renewable energy applications.
China
GB standards for wind power equipment shape domestic controller design requirements as offshore expansion accelerates in Fujian and Guangdong provinces. MIIT industrial policy channels semiconductor procurement toward domestic ultrasonic transducer sources. Yangtze River Delta manufacturing clusters concentrate assembly capacity for export-grade marine monitoring systems.
Denmark
Ørsted and Vestas supply chain proximity concentrates demand for hardened offshore controllers in Esbjerg and Copenhagen port zones. IEC 61400 turbine safety frameworks tighten certification reciprocity requirements for Asian component suppliers. Danish test laboratories process wind tunnel validation for Nordic and Baltic installation contracts.
Japan
Floating offshore wind demonstrators off Goto Islands and Fukushima require motion-compensated alarm controllers integrating vessel motion sensors. METI energy transition targets accelerate procurement for salt-laden environment hardware. Osaka-Kobe industrial corridors host marine equipment fabricators adapting European certification protocols for domestic platform specifications.
Wind Alarm Controller Market Competitive Landscape
Listed leaders compete with private specialists across calibration infrastructure and certification depth, creating tiered competitive boundaries. The vendor base separates between premium-positioned offshore-grade suppliers and cost-optimized volume producers serving onshore applications. Three archetypes dominate: Nordic calibration-heavy specialists, German industrial distribution-anchored fabricators, and Asian scale-driven component integrators. Geographic expansion through notified body accreditation and strategic partnerships for edge computing capability represent the dominant competitive moves.
Within the calibration-specialist tier, Vaisala anchors premium positioning through Finnish wind tunnel infrastructure, while PCE Instruments exemplifies the German distribution-anchored archetype competing on cost. Gill Instruments occupies a position representing British marine instrumentation heritage. These three named entities illustrate how competitive positioning fragments across certification depth, channel control, and geographic origin rather than converging on uniform technology or pricing strategies.
| Leading Market Players |
|---|
| PCE Instruments |
| Comptus |
| Maximum Weather Instruments |
| Belfort Instrument |
| SCARLET TECH |
| Davis Instruments |
| Observator Instruments |
| Gill Instruments |
| Vaisala |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week lead times for IEC 61400-12-1 certified ultrasonic transducers concentrate pricing power among Finnish and German calibration houses while compressing margins for Asian component integrators serving price-sensitive onshore segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates marine-grade certified controllers from industrial uncertified units and portable construction-site alternatives. Price differentiation hinges on IEC 61400-12-1 certification depth and after-sales calibration bundling. Cost compression in the economy tier is intensifying because mechanical anemometer substitutes retain procurement share in accessible maintenance environments. Independent power producers in the United States exhibit highest price sensitivity, while North Sea offshore developers accept premium positioning for redundant safety systems.
Supply Chain Analysis
Taiwan Strait shipping lanes concentrate risk for precision ADC component delivery to controller manufacturers in Germany and Denmark. Semiconductor fabrication draws from Taiwan, South Korea, and China, while ultrasonic transducer assembly rests on Yangtze River Delta clusters. Single-source vulnerability in marine-grade enclosure aluminum extrusions exposes production schedules to commodity price volatility. Distribution runs through German industrial distributors and direct manufacturer relationships with wind farm operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineers capable of implementing IEC 61508 functional safety protocols in resource-constrained architectures remain scarcer than production capacity, constraining how quickly suppliers can expand certified product lines.
For Market Incumbents: Secure calibration infrastructure reciprocity agreements with emerging Asian test laboratories before qualification bottlenecks harden. Deepen backward integration into ultrasonic transducer chip sourcing to reduce exposure to Taiwan Strait logistics disruptions. Anchor channel control through long-term service contracts that bundle predictive maintenance analytics with hardware procurement. For New Entrants and Emerging Players: IEC 61400-12-1 fast-track partnerships with Finnish or German notified bodies unlock access to North Sea offshore procurement cycles. Target floating offshore wind demonstrators in Portugal and Japan where motion-compensated measurement systems lack established suppliers. Pursue direct relationships with independent power producers in Texas and California favoring modular smart controller procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial sensor parents with undermonetized marine-grade controller divisions. Five-to-ten-year viability depends on edge computing convergence positioning for predictive maintenance revenue streams. Watch for inflection when floating offshore wind project announcements exceed fixed-bottom installations in quarterly development databases.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Accredited wind tunnel validation in Finland and Germany accelerates IEC 61400-12-1 certification timelines for offshore suppliers. |
| Ultrasonic Sensor Technology Licensing | Time-of-flight transducer patents from marine instrumentation specialists unlock solid-state migration in salt-laden environments. |
| Edge Computing Partnership | Predictive maintenance algorithm integration with turbine OEM control systems commands premium positioning in smart controller procurement. |
| Backward Integration into Semiconductor Sourcing | Captive supply of precision ADC components reduces exposure to Taiwan Strait logistics chokepoints and geographic supply shocks. |
| Floating Platform Motion Compensation Development | Integration with vessel motion sensors addresses emerging demand from Portugal and Japan floating wind demonstrators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wind farm operations directors, port crane safety engineers, turbine control system architects, and marine classification surveyors. Secondary validation drew from IEC 61400 certification databases, DNV maritime equipment registers, FAA obstruction lighting compliance filings, and customs trade records for ultrasonic transducer imports. Bottom-up unit demand estimates and top-down market sizing triangulated across installation forecasts and controller replacement cycles.
Across the analysis window, the analytical framework modeled segmentation across product type, sensor technology, end-user industry, and installation environment. CAGRs derived from weighted average growth across certified and uncertified product tiers, with specific inputs from offshore wind capacity pipelines and port modernization expenditure tracking. Floating platform deployment timelines and edge computing adoption curves informed technology transition assumptions.
Decision-makers should treat outputs as directional under sustained IEC 61400-12-1 certification reciprocity and stable semiconductor supply availability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas Regulation compliance timelines and floating offshore wind demonstration outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Flue Gas Desulfurization Unit Market
Power
Global Hydraulic Turbine Market
Power
Electric Arc Furnaces Market
Power
Sudan Power EPC Market
Power
Wind Turbine Drivetrain Market
Power
Asia-Pacific Power Market
Power
Iran Power Market
Power
Global Ancillary Services Power Market
Power
Uzbekistan Power Market
Power
Power Sled Market
Power
Power Shelf Market
Power
Malaysia Power EPC Market
Power
Telecom Power Rental Market
Power
Italy Power EPC Market
Power
Power Capacitors Market
Power
Kuwait Power Market