
 Battery Scrap Market | 2026-2036
Battery Scrap Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Scrap Market Analysis
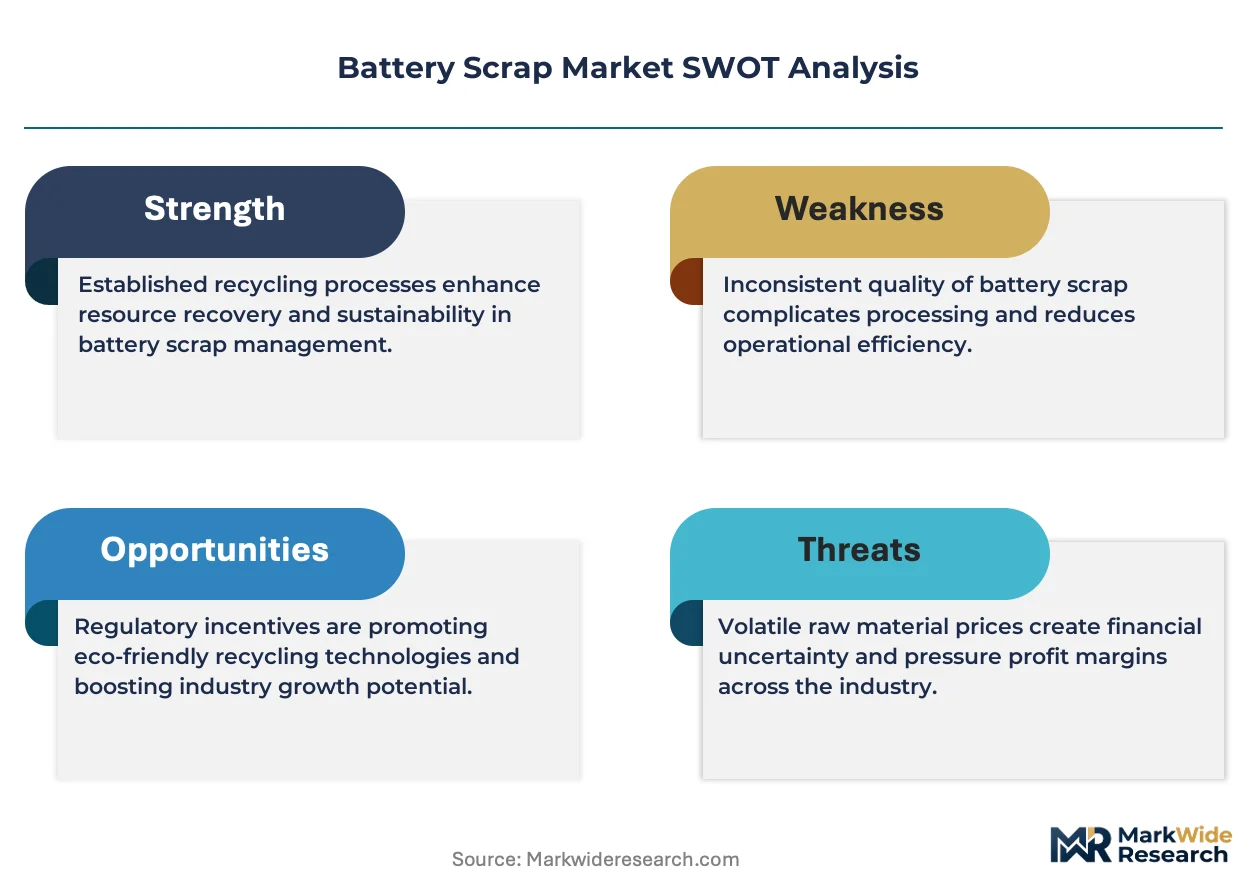
Chinese hydrometallurgical refineries is expanding capacity to recover battery-grade lithium and cobalt from black mass. Li-Cycle anchors North American processing through its spoke-and-hub network. Umicore leverages integrated smelting capabilities across Europe and Asia. Redwood Materials specializes in direct recycling pathways for cathode active materials.
Battery scrap comprises spent cells, manufacturing rejects, and end-of-life packs containing recoverable metals including lithium, cobalt, nickel, and manganese through pyrometallurgical or hydrometallurgical extraction. The material serves primarily as feedstock for renewed cathode production, reducing virgin mining requirements. Lithium-ion scrap now dominates value pools given chemistry complexity and metal density. Hydrometallurgical processing leads growth margins due to higher recovery rates and lower emissions profiles. Mechanical shredding remains the volume gateway for downstream separation stages.
The EU Battery Regulation and China's MIIT dual carbon framework now mandate traceable recycled content minimums, forcing OEMs to secure qualified scrap supply chains. EPA hazardous waste rules in the US govern interstate transport and storage classifications, shaping facility siting decisions. Stakeholders must monitor evolving extended producer responsibility schemes and certification standards that will determine market access and premium pricing for compliant material streams.
Market Dynamics
EU Battery Regulation recycled content mandates are forcing OEMs to restructure cathode supply chains around qualified scrap streams rather than virgin mining contracts.
Growth Catalysts
- EU Battery Regulation:Minimum recycled content thresholds for lithium, cobalt, and nickel in new batteries sold across member states create guaranteed offtake for compliant scrap processors.
- Automotive electrification:End-of-life electric vehicle packs from early adopter fleets in Germany and California are entering the waste stream, expanding feedstock availability for hydrometallurgical refiners.
- Black mass:This intermediate product from mechanical shredding of lithium-ion cells now trades as a standardized commodity, enabling price discovery and forward contracting between collectors and refiners.
Market Restraints
- Cobalt price volatility:Fluctuations in London Metal Exchange pricing compress margins for processors locked into fixed-price black mass purchase contracts.
- Chinese processing concentration:Over 70% of battery-grade lithium carbonate refining capacity resides in Hunan and Jiangsu provinces, creating single-point-of-failure risk for Western OEMs.
- Collection infrastructure gaps:Inconsistent hazardous waste transport classifications across US state EPA jurisdictions fragment feedstock aggregation economics.
Strategic Opportunities
- US IRA domestic content credits:The Inflation Reduction Act's clean vehicle tax credits reward batteries with North American recycled metal content, incentivizing spoke-and-hub network investments.
- Direct recycling:Cathode active material regeneration without full elemental dissolution preserves crystal structure and reduces reprocessing energy intensity versus hydrometallurgy.
- Reverse logistics partnerships:Collaboration between automotive OEMs and battery leasing operators secures captive end-of-life feedstock streams before competitive bidding.
Industry Challenges
- Battery passport compliance:The EU's digital tracking requirement demands granular chain-of-custody documentation from cell manufacturing through final recycling, requiring IT system overhauls across the value chain.
- Pyrometallurgical emission controls:Smelting operations face tightening MEE air quality standards in China and Best Available Technique requirements under EU Industrial Emissions Directive, elevating capex for facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Scrap Market |
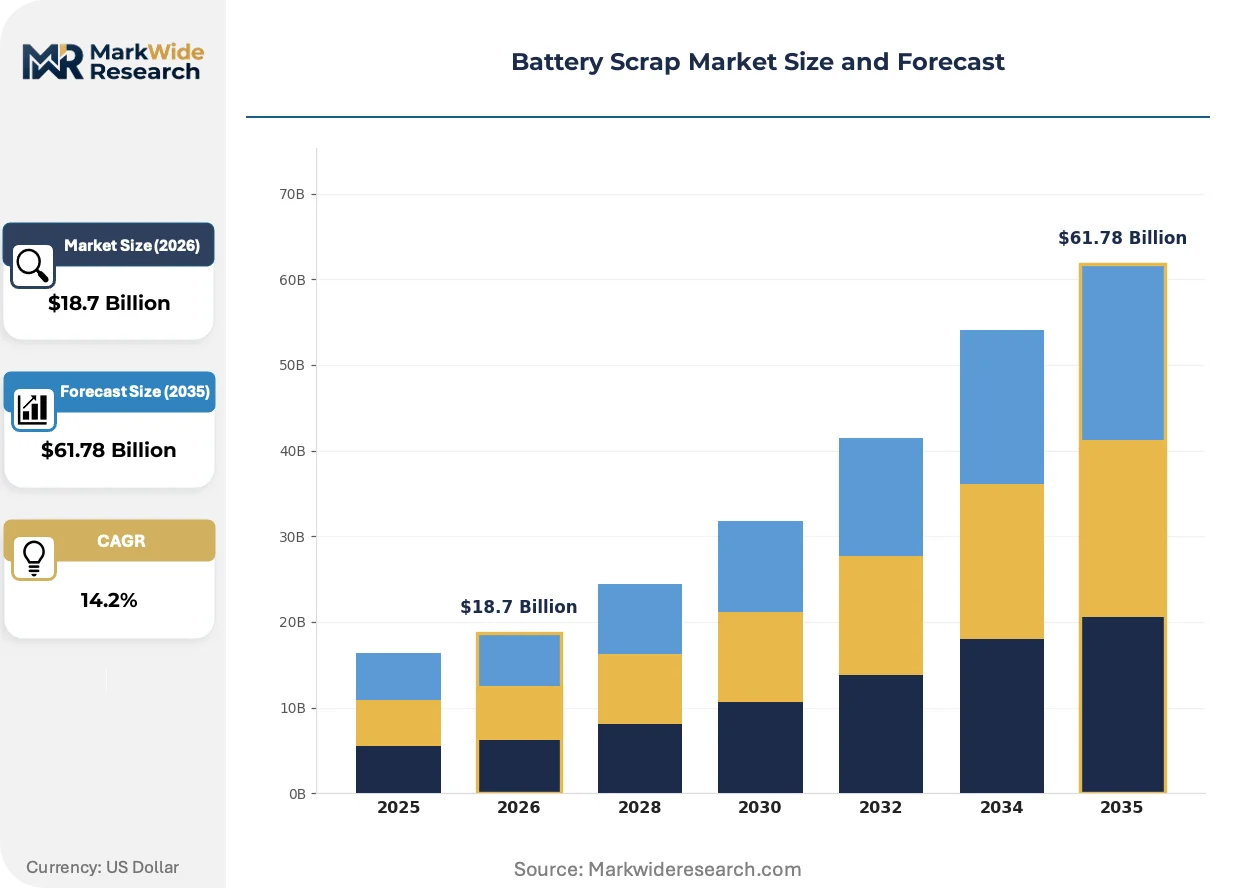
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lead-acid, Lithium-ion, Nickel-cadmium, Alkaline Processing Method: Mechanical, Pyrometallurgical, Hydrometallurgical, Biotechnological End User: Recycling Facilities, Battery Manufacturers, Automotive Industry, Electronics Sector Application: Energy Storage, Reuse, Raw Material Recovery, Waste Management |
| Companies Covered | Gravita India, Li-Cycle, Umicore, RSR Corporation, Retriev Technologies, Exide Technologies, Call2Recycle, East Penn Manufacturing, Redwood Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Scrap Market Emerging Trajectories
Processing technology convergence and regulatory traceability mandates are compressing the traditional separation between scrap collection, intermediate processing, and cathode remanufacturing into integrated regional hubs.
Direct cathode recycling is absorbing capital and engineering talent from conventional hydrometallurgical pathways. This approach preserves nickel-manganese-cobalt crystal structures through selective relithiation rather than full elemental dissolution. Automotive OEMs in South Korea and Germany are piloting partnerships with specialized recyclers to validate performance parity with virgin cathode material. The technology is absorbing market share from black mass traders by offering closed-loop supply security against volatile metal prices.
REACH authorization requirements for cobalt compounds are tightening due diligence obligations across European battery supply chains. The regulation now extends to recycled content, forcing scrap processors to document conflict-mineral-free origins alongside recovery rates. Refiners in Poland and Belgium are investing in mass-balance certification systems to maintain market access. Cell manufacturers with EU assembly operations face the steepest compliance timelines and are pre-qualifying scrap suppliers two years ahead of mandate deadlines.
Automotive OEMs are consolidating cathode procurement around vertically integrated recyclers with demonstrated battery-grade output. Long-term offtake agreements now span 5-7 years, displacing spot-market metal purchasing. This preference shift favors processors with proven hydrometallurgical or direct recycling capabilities over mechanical shredders without downstream refining. German and US electric vehicle manufacturers are driving this restructuring most aggressively, linking supplier selection to IRA domestic content calculations and EU Battery Regulation compliance roadmaps.
Battery Scrap Market Segmentation
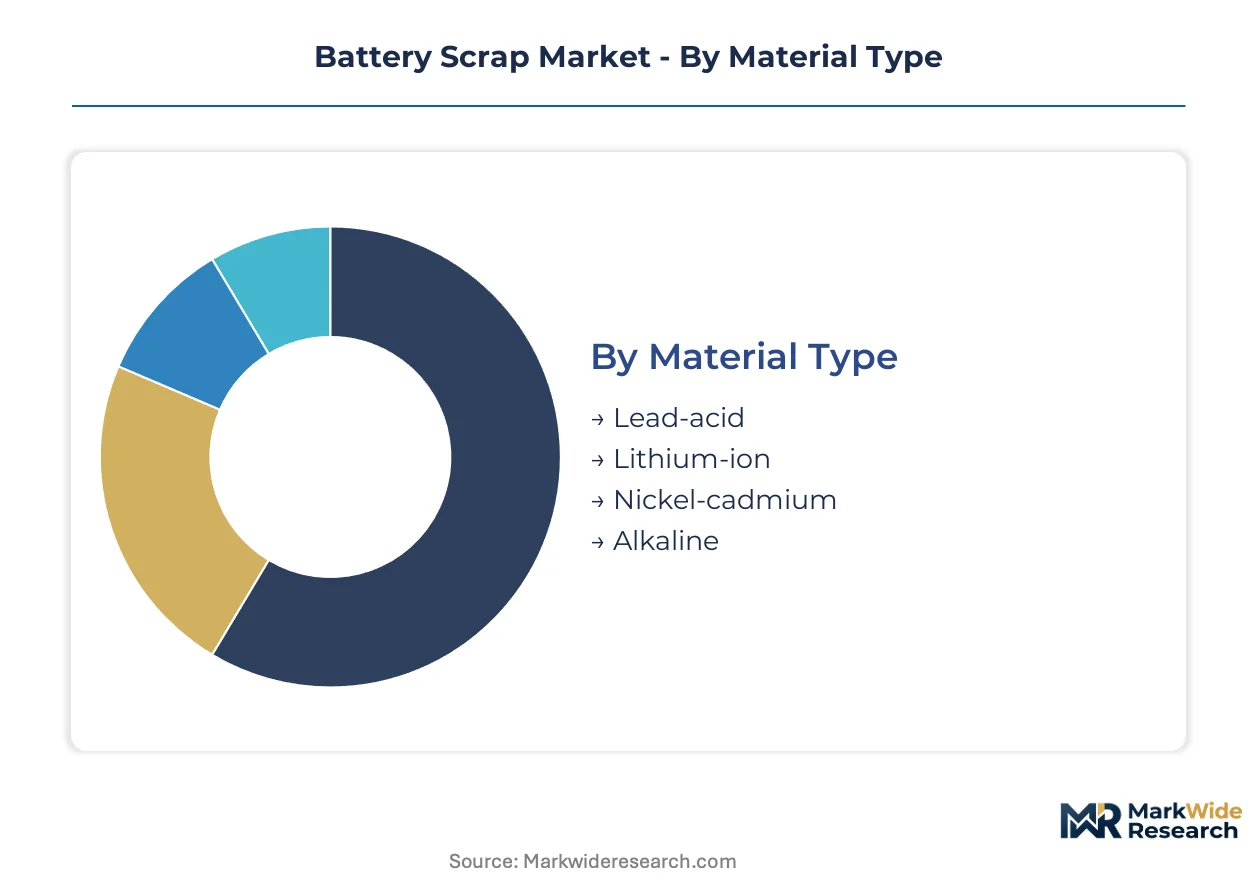
Battery scrap segmentation reveals distinct value pools tied to chemistry complexity and processing technology maturity. Material type determines metal recovery economics, while processing method separates volume handlers from margin capturers.
Material Type:
Replacement cycles vary dramatically by chemistry, with automotive and industrial applications driving differential feedstock availability across segments.
- Lithium-ion:Complex cathode chemistries including nickel-manganese-cobalt and lithium-iron-phosphate deliver the highest metal density per ton. Demand concentrates in German and South Korean automotive OEM supply chains as EU Battery Regulation mandates escalate; processors with hydrometallurgical capabilities command premium offtake terms.
- Lead-acid:Mature recovery infrastructure and standardized smelting economics dominate this high-volume, low-margin category. Collection networks in the US and India anchor supply security; the segment faces compression from declining internal combustion engine vehicle production.
- Nickel-cadmium:Specialized industrial and aviation applications generate limited but concentrated waste streams requiring cadmium-specific handling protocols.
- Alkaline:Consumer battery waste contributes marginal metal value, serving primarily volume-driven municipal collection programs with minimal downstream refining interest.
Volume placements concentrate in Lead-acid; the faster expansion belongs to Lithium-ion.
Processing Method:
Capital intensity and recovery rate differentials separate mechanical pre-processing from value-capturing refining stages.
- Hydrometallurgical:Aqueous chemical dissolution achieves selective lithium, cobalt, and nickel recovery rates exceeding pyrometallurgical alternatives. Chinese refineries in Hunan province anchor global capacity; Western investments accelerate under IRA domestic content incentives.
- Mechanical:Shredding and sorting operations produce standardized black mass for downstream sale. Li-Cycle's spoke-and-hub deployment across Ontario and Alabama illustrates the model; margins depend on forward contracting discipline against metal price swings.
- Pyrometallurgical:High-temperature smelting remains cost-competitive for cobalt-rich feeds but faces tightening MEE emission standards in China and EU Industrial Emissions Directive compliance costs.
- Biotechnological:Bioleaching using acidophilic bacteria offers selective metal extraction at ambient temperatures; pilot-scale operations in Finland and Belgium target reduced reagent costs and wastewater treatment burdens.
Mechanical operations handle the greatest tonnage; hydrometallurgical capacity is climbing the fastest.
End User:
Procurement authority is shifting from spot traders to integrated OEMs seeking qualified supply chains.
- Recycling Facilities:Independent refiners and integrated smelters purchase black mass and manufacturing scrap for metal recovery. Umicore's European and Asian operations exemplify scale advantages; facility certification under EU Battery Regulation determines market access.
- Battery Manufacturers:Cathode producers and cell assemblers source recycled content directly to meet regulatory thresholds. South Korean manufacturers are pre-qualifying scrap suppliers two years ahead of mandate deadlines.
- Automotive Industry:OEMs with German and US assembly operations negotiate long-term offtake agreements spanning five to seven years, displacing spot metal purchasing.
- Electronics Sector:Consumer device manufacturers contribute fragmented, low-volume feeds with limited traceability documentation for regulatory compliance.
Recycling Facilities retain the largest procurement volumes; Battery Manufacturers are gaining share fastest through captive supply arrangements.
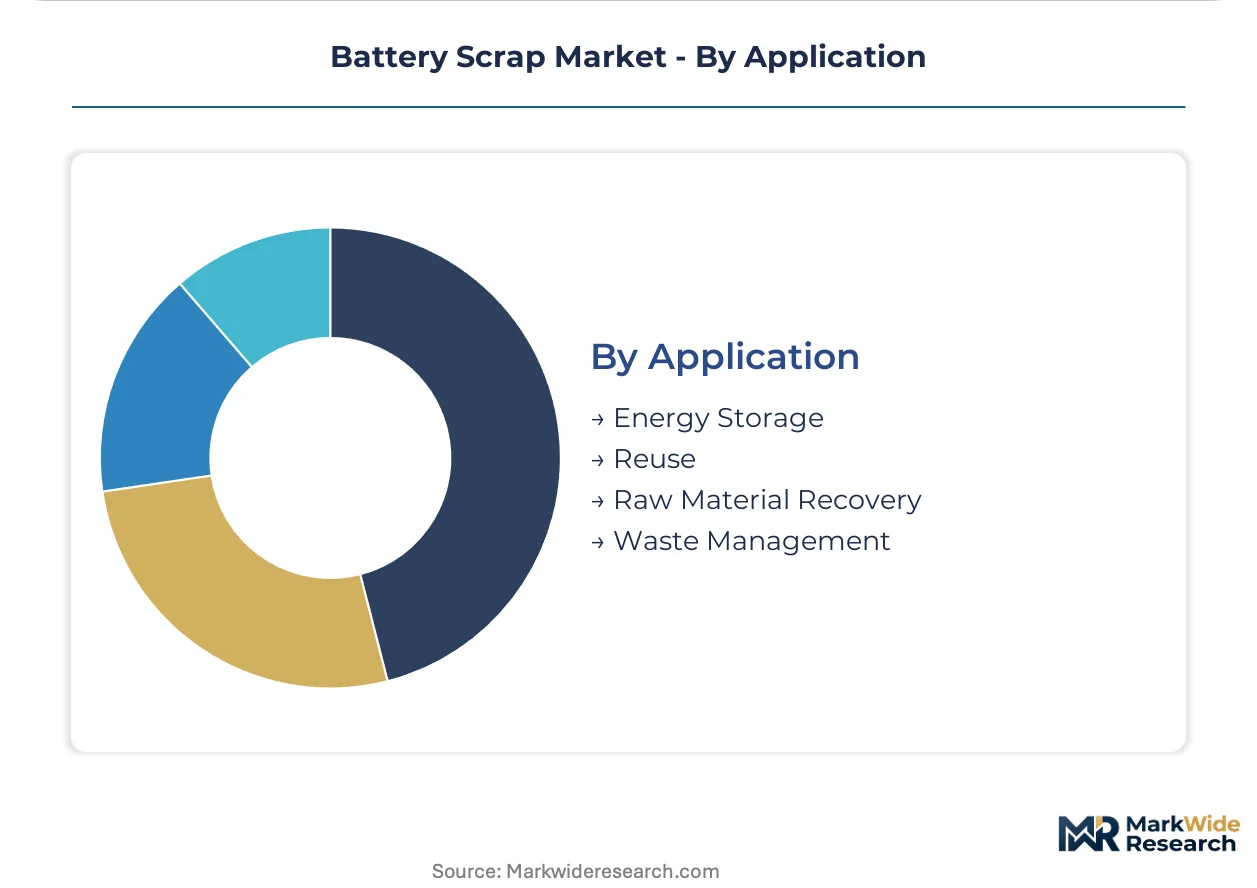
Application:
Value capture potential diverges sharply between closed-loop material return and open-loop waste disposal.
- Raw Material Recovery:Battery-grade lithium carbonate, cobalt sulfate, and nickel cathode precursor production commands premium pricing against virgin mining benchmarks. Redwood Materials' direct recycling pathways target this highest-value application.
- Energy Storage:Second-life electric vehicle pack repurposing for stationary applications extends useful service life; California and German grid operators pilot aggregation models.
- Reuse:Module-level refurbishment for less demanding automotive or industrial applications requires diagnostic infrastructure that remains underdeveloped outside China.
- Waste Management:Hazardous waste disposal compliance for non-recoverable fractions generates service fees but minimal value recovery.
Raw Material Recovery commands the steepest expansion trajectory; Waste Management handles residual volumes without growth upside.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Black mass feedstock availability clusters around automotive manufacturing corridors and battery assembly hubs in five core economies. Regulatory mandates and processing infrastructure investments are reshaping regional competitive positioning.
United States
Early electric vehicle adopter fleets in California and Texas are generating end-of-life pack volumes for hydrometallurgical refiners. EPA hazardous waste transport classifications under RCRA fragment interstate feedstock aggregation economics. Li-Cycle operates spoke-and-hub facilities across Ontario and Alabama, positioning for IRA domestic content credit capture.
China
Integrated refineries in Hunan and Jiangsu provinces process over seventy percent of global battery-grade lithium carbonate from black mass inputs. MIIT dual carbon framework mandates traceable recycled content minimums for domestic battery manufacturers. Zhejiang and Fujian provinces are expanding hydrometallurgical capacity to meet OEM qualification requirements.
Germany
Automotive OEM assembly operations in Bavaria and Baden-Württemberg drive cathode material demand with EU Battery Regulation recycled content thresholds. KBA vehicle registration data tracks end-of-life electric vehicle flows into approved dismantling networks. North Rhine-Westphalia hosts Umicore's integrated smelting complex serving European cell manufacturers.
South Korea
Cathode producers in Gyeonggi and Chungcheong provinces are pre-qualifying scrap suppliers two years ahead of mandate deadlines. MFDS chemical safety regulations extend to recycled content documentation for battery-grade outputs. Busan-Ulsan industrial corridor concentrates black mass import handling for domestic refining.
Belgium
REACH authorization requirements for cobalt compounds tighten due diligence obligations across European battery supply chains. Antwerp and Liège host mass-balance certification systems for conflict-mineral-free scrap processing. Flanders region refiners invest in IT infrastructure for EU Battery Passport chain-of-custody documentation.
Battery Scrap Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct recycling pathways and regional hub consolidation. The vendor base separates into three functional layers: integrated smelters with multi-metal recovery, mechanical shredders producing standardized black mass, and direct recycling specialists preserving cathode crystal structures. Strategic archetypes include spoke-and-hub network operators, vertically integrated OEM partners, and technology licensors. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as procurement authority shifts from spot traders to qualified supply chains.
Within the integrated smelter tier, Umicore and RSR Corporation exemplify multi-continental operational scale. Li-Cycle and Redwood Materials occupy distinct positions in the North American processing infrastructure, with the former representing spoke-and-hub mechanical pre-processing and the latter anchoring direct cathode regeneration capabilities. Retriev Technologies and Exide Technologies sit within established lead-acid recovery networks that face compression from lithium-ion chemistry transition.
| Leading Market Players |
|---|
| Gravita India |
| Li-Cycle |
| Umicore |
| RSR Corporation |
| Retriev Technologies |
| Exide Technologies |
| Call2Recycle |
| East Penn Manufacturing |
| Redwood Materials |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange cobalt price volatility cascades through black mass contracting tiers, compressing margins for mechanical shredders locked into fixed-rate purchase agreements while hydrometallurgical refiners capture spreads through battery-grade output premiums.
Pricing Analysis
After-sales technical support and chain-of-custody documentation bundle into premium black mass contracts, while unbundled spot transactions trade at discounts. Three-tier pricing structure across battery-grade certified, standard industrial, and unqualified scrap levels separates qualified EU Battery Regulation-compliant material from hazardous waste classifications. Cost compression in mechanical shredding tiers is intensifying because cobalt price swings erode forward contract profitability. Battery manufacturers with EU assembly operations exhibit lowest price sensitivity due to regulatory mandate deadlines, whereas independent collectors face acute margin pressure from transport cost fragmentation.
Supply Chain Analysis
EU Battery Passport qualification gates access to premium offtake agreements, forcing upstream collectors to invest in mass-balance certification systems before entering German or South Korean cathode producer supply chains. Feedstock concentration rests on China, Germany, and South Korea as dominant black mass generation and processing clusters. Critical dependencies include cobalt-rich lithium-ion cells from early electric vehicle fleets, manufacturing scrap from South Korean cathode plants, and hydrometallurgical reagent chemicals. Single-source vulnerability concentrates in Hunan province refining capacity. Distribution runs through spoke-and-hub networks aggregating to regional hydrometallurgical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Battery Regulation recycled content mandates are accelerating consolidation by disqualifying uncertified mechanical shredders from OEM supply chains, forcing sub-scale operators toward distressed asset sales.
For Market Incumbents: To counter cobalt price volatility eroding fixed-contract margins, integrated refiners should deepen backward integration into captive end-of-life vehicle collection networks in California and Texas, while simultaneously expanding hydrometallurgical capacity under IRA domestic content incentive frameworks to secure long-term automotive offtake agreements. For New Entrants and Emerging Players: Begin with direct recycling technology pilots targeting South Korean cathode producer partnerships, where pre-qualification timelines create white-space before mandate deadlines. The most penetrable segment lies in second-life energy storage applications for grid operators in California and Germany, leveraging diagnostic infrastructure gaps that Chinese competitors have not yet filled. For Investors and Strategic Acquirers: Distressed-cycle entries favor mechanical shredders with EPA RCRA interstate transport permits in the US Southeast, where collection infrastructure gaps persist and spoke-and-hub network assets trade below replacement cost. The long-term viability window favors processors with demonstrated battery-grade lithium carbonate output capabilities. Watch for EU Battery Passport IT system deployment delays as inflection signal for qualification timeline extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captures end-of-life electric vehicle feedstock before competitive bidding in California and Texas corridors. |
| Hydrometallurgical Capacity Expansion | Positions refiners for IRA domestic content credits and EU Battery Regulation qualified supplier status. |
| Direct Recycling Technology Deployment | Preserves cathode crystal structures for South Korean OEM partnerships seeking closed-loop supply security. |
| Mass-Balance Certification Investment | Enables market access under REACH authorization requirements for cobalt compound due diligence. |
| Reverse Logistics Partnership Formation | Secures captive manufacturing scrap streams from battery leasing operators before spot market exposure. |
Methodological Framework
Multi-period observation of black mass price indices, EU Battery Regulation implementation timelines, and hydrometallurgical capacity buildouts anchored the trend analysis, supplemented by interviews with scrap collection network operators, hydrometallurgical plant managers, cathode producer procurement leads, and automotive OEM sustainability officers. Secondary validation drew from EPA RCRA filings, MIIT dual carbon framework disclosures, EU Battery Passport pilot documentation, and London Metal Exchange cobalt price series. Bottom-up feedstock volume estimates triangulated against top-down cathode material demand projections.
Input-output matrices modeled black mass generation rates against hydrometallurgical refining capacity across the analysis window, with segmentation across lithium-ion chemistry types, processing method tiers, and end-user procurement categories. CAGRs derived from regression analysis of historical capacity utilization rates and announced facility investments. Forecast inputs included electric vehicle fleet retirement curves, EU recycled content mandate phase-in schedules, and IRA credit eligibility thresholds.
Underlying measurement precision varies by segment; hydrometallurgical capacity and automotive OEM offtake agreements carry tighter precision than emerging biotechnological processing pilot data. Forecasts reflect documented assumptions regarding regulatory timeline adherence and metal price correlation stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market