
 United States Yogurt Market | 2026-2036
United States Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
United States Yogurt Market Analytics
Dairy processing technician shortages across the Upper Midwest are unwinding production capacity expansion plans for several regional cooperatives. Chobani LLC leverages its Idaho-based manufacturing footprint to sustain national distribution density without coastal premium logistics. General Mills competes through Yoplait USA's entrenched retail shelf positioning across conventional grocery channels. Danone anchors its portfolio with strained yogurt expertise imported from European process knowledge.
United States yogurt denotes a fermented milk product cultured with Lactobacillus delbrueckii subsp. bulgaricus and Streptococcus thermophilus, achieving a titratable acidity of at least 0.9% lactic acid and often incorporating live probiotic cultures for digestive health positioning. Greek yogurt commands the highest protein-per-serving specification through straining that removes liquid whey, creating a denser texture and concentrated nutrient profile that supports premium pricing. Drinkable yogurt formats are expanding fastest among on-the-go customer segments, while organic yogurt carries elevated input costs that compress margins despite retail price premiums. Plastic cups retain dominant packaging share, though pouch formats are capturing child-oriented and fitness-oriented purchase occasions.
The FDA governs yogurt identity standards under 21 CFR 131.200, mandating minimum milkfat content and bacterial culture requirements that constrain formulation flexibility. USDA organic certification shapes ingredient sourcing and label claims, while state-level dairy pricing orders in California and Wisconsin influence raw milk cost structures. Stakeholders must monitor how FDA enforcement priorities around live-and-active culture claims intersect with evolving consumer litigation over sugar content disclosures.
Market Dynamics
Reformulation pressure from FDA added-sugar labeling mandates is compressing legacy recipes while concentrating production among facilities capable of rapid recipe engineering and clean-label certification.
Growth Catalysts
- Protein-enriched formats:Urban coastal consumers in California and New York are expanding purchases of Greek and Icelandic strained varieties, pulling volume toward premium positioning.
- 21 CFR 131.200 identity standards:Regulatory clarity on bacterial culture requirements enables consistent quality claims that support live-and-active culture marketing.
- Direct-to-home delivery channels:Specialty retail and subscription services are capturing shelf space and loyalty in metropolitan markets.
Market Restraints
- Dairy processing technician shortages:Labor scarcity across the Upper Midwest is unwinding capacity expansion plans for regional cooperatives.
- Organic input cost volatility:USDA organic certification requirements elevate ingredient sourcing costs that compress margins despite retail price premiums.
- Plastic packaging dependency:Dominant cup formats face substitution pressure from pouch alternatives without equivalent recycling infrastructure.
Strategic Opportunities
- Drinkable yogurt white space:On-the-go consumption occasions remain underpenetrated relative to spoonable formats, particularly among fitness-oriented demographics.
- State-level dairy pricing order optimization:California and Wisconsin pricing structures create arbitrage opportunities for processors with multi-state sourcing flexibility.
- Live culture litigation defense:Proactive sugar disclosure and substantiated probiotic claims create differentiation as consumer class actions intensify.
Industry Challenges
- Fermentation process control expertise:Titratable acidity management and culture viability maintenance require specialized technical talent in short supply.
- Multi-format equipment retooling:Capital intensity of lines capable of cup, pouch, and bottle output strains mid-scale processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Yogurt Market |
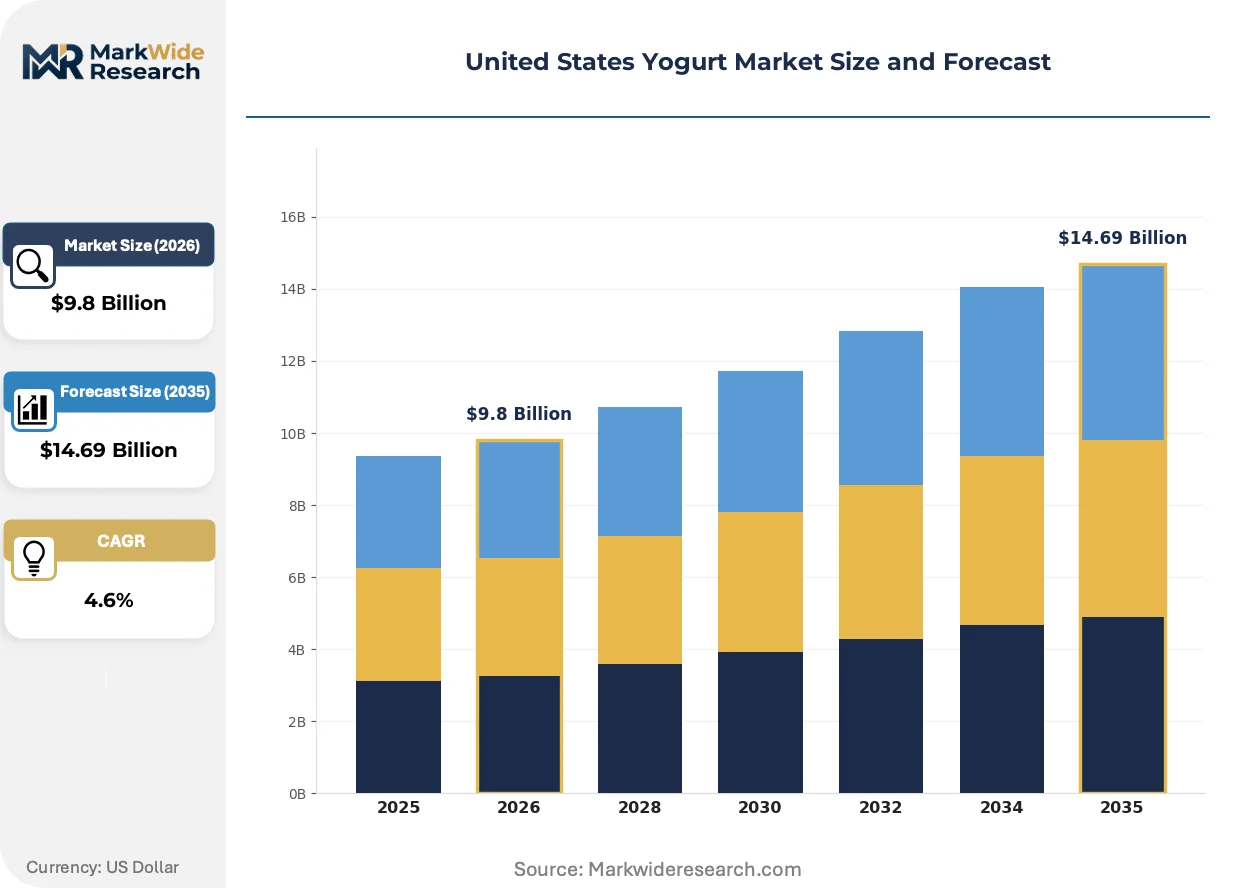
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Low-Fat Yogurt, Organic Yogurt, Drinkable Yogurt Packaging Type: Plastic Cups, Glass Jars, Pouches, Tubs Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Health-Conscious Consumers, Families, Millennials, Fitness Enthusiasts |
| Companies Covered | Chobani LLC, Danone, General Mills, Yoplait USA, FAGE International, The Dannon Company, Arla Foods amba, Lactalis, Stonyfield Farm, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Yogurt Market Evolving Landscape
Clean-label straining technologies and alternative protein fortification methods are reconfiguring competitive advantage away from conventional formulation expertise.
Aseptic cold-fill processing is displacing hot-fill sterilization in drinkable yogurt production. Beverage-oriented dairy processors are adopting these lines at accelerating pace. The shift is compressing shelf-stable flavor degradation and enabling extended refrigerated distribution without preservative additives.
FDA enforcement priorities around live-and-active culture substantiation are tightening claim documentation requirements. Manufacturers must now maintain batch-level culture viability records to defend label statements. Greek and strained categories face highest scrutiny given their premium positioning on protein and probiotic density.
Subscription-based replenishment models are capturing household pantry inventory management. Direct-to-home services in New York and California metropolitan corridors are displacing conventional grocery stock-up trips for core yogurt purchases. Fitness-oriented consumers show highest conversion to auto-delivery schedules tied to training regimens.
United States Yogurt Market Segmentation
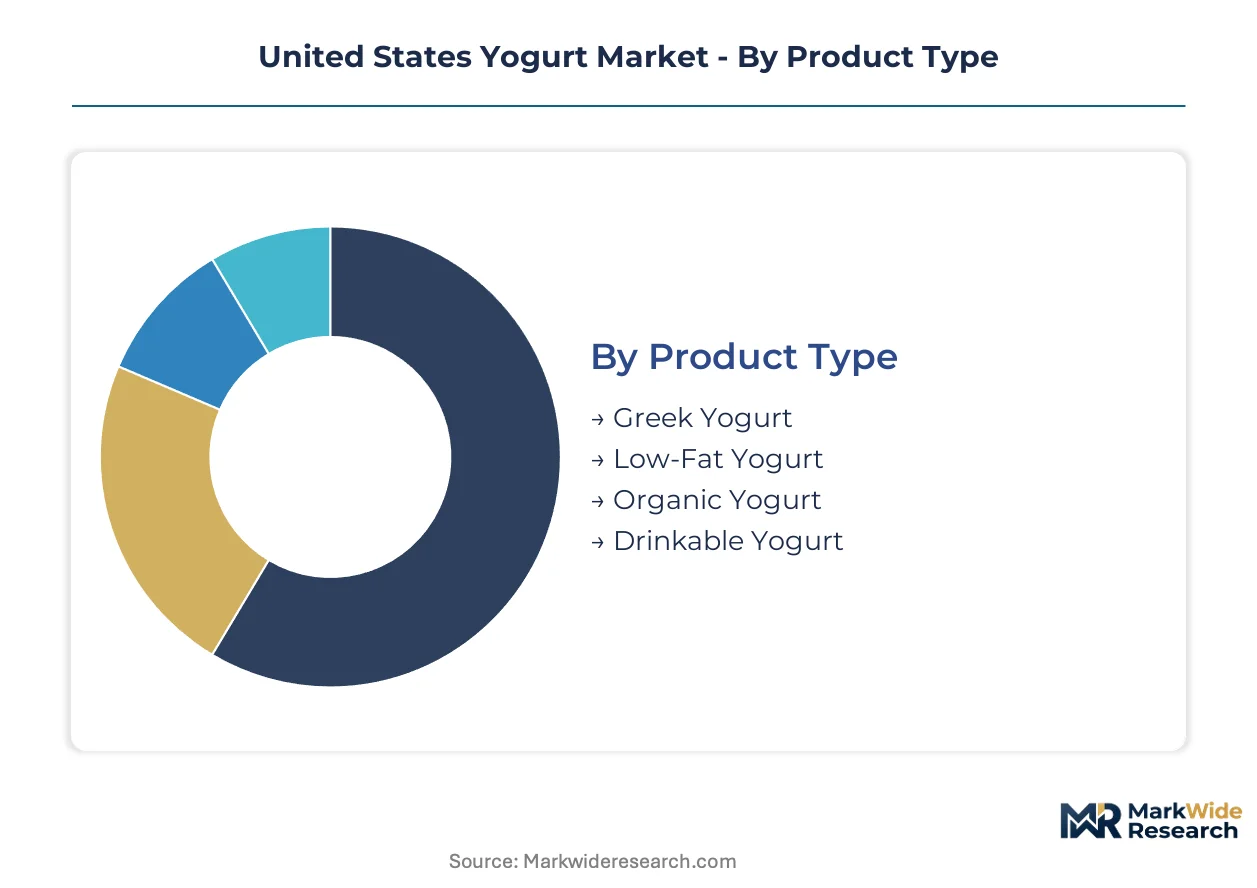
Yogurt segmentation in the United States reflects divergent supply chain configurations across format, packaging, and channel. Each category carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Domestic consumption dominates all product categories, with export volumes negligible due to refrigerated shelf-life constraints and FDA identity standard requirements.
- Greek Yogurt:Strained varieties achieve protein density through whey removal, creating a thicker texture that commands premium positioning. California and New York metropolitan markets concentrate demand for Greek formats, driven by fitness-oriented consumers seeking post-workout protein delivery.
- Drinkable Yogurt:Beverage-format fermentation requires aseptic cold-fill processing lines that extend refrigerated distribution reach without preservatives. On-the-go consumption occasions in urban corridors are expanding fastest among commuter demographics and gym-adjacent retail.
- Low-Fat Yogurt:Legacy formulations face reformulation pressure from FDA added-sugar labeling mandates.
- Organic Yogurt:USDA certification requirements elevate input costs and compress processor margins.
Greek yogurt holds the largest share; momentum sits with drinkable formats.
Packaging Type:
Packaging selection correlates with consumption occasion and retail channel density, driving capital allocation toward multi-format production lines.
- Plastic Cups:Thermoformed polystyrene and polypropylene containers retain dominant retail shelf presence through established recycling infrastructure and low unit costs. Conventional grocery channels in the Upper Midwest and Southeast rely heavily on cup formats for family-size multi-packs.
- Pouches:Flexible film packaging captures child-oriented and fitness-oriented purchase occasions through portability and portion control. Direct-to-home subscription services in California and New York metropolitan areas are adopting pouches for delivery optimization.
- Glass Jars:Premium positioning in specialty retail channels supports artisanal and small-batch production claims.
- Tubs:Bulk formats serve foodservice and institutional accounts with higher volume per transaction.
Plastic cups maintain volume leadership; pouches are climbing the fastest.
Distribution Channel:
Channel strategy determines cold-chain investment intensity and promotional spend allocation across the United States.
- Supermarkets:Conventional grocery retains the highest absolute volume through entrenched refrigerated case placement and promotional slotting fees. Chobani LLC and General Mills compete aggressively for shelf positioning in Kroger, Albertsons, and regional banner accounts.
- Online Retail:Direct-to-home delivery platforms bypass traditional distributor markups while capturing subscription-based replenishment demand. Amazon Fresh and specialized dairy subscription services are gaining household penetration in coastal metropolitan corridors.
- Convenience Stores:Grab-and-go occasions favor single-serve drinkable formats with extended shelf-life requirements.
- Specialty Stores:Natural and organic retailers command premium placement fees for certified and clean-label positioning.
Supermarkets command the largest share; steepest expansion trajectory belongs to online retail.
Customer Type:
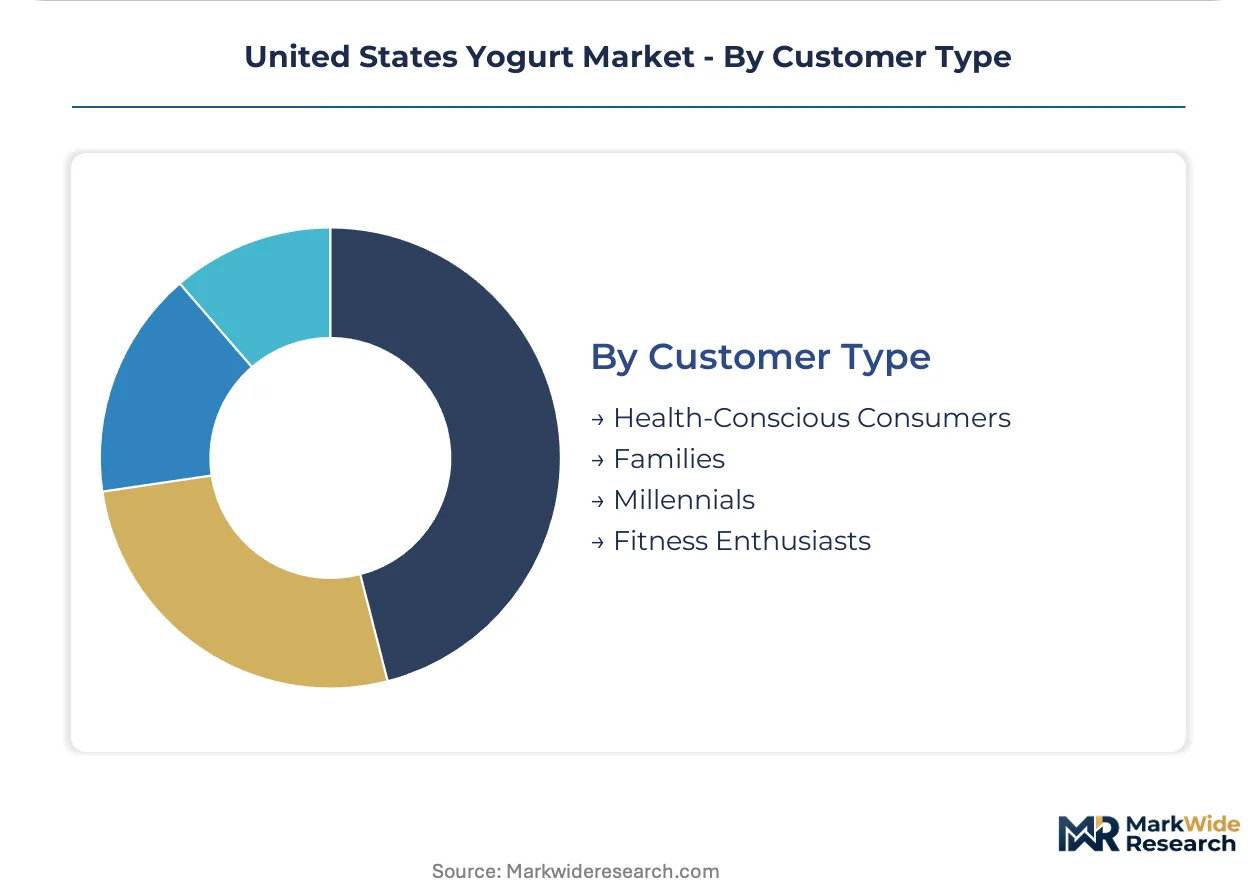
Demographic targeting shapes formulation decisions and marketing claims, with distinct protein and sugar preferences across segments.
- Health-Conscious Consumers:This segment prioritizes live-and-active culture claims and reduced sugar content, driving reformulation toward clean-label recipes. FDA enforcement priorities around probiotic substantiation directly impact purchasing confidence among this group.
- Fitness Enthusiasts:Protein-per-serving specifications dominate selection criteria, with Greek and Icelandic strained varieties preferred for post-exercise recovery. Urban gym-adjacent retail and auto-delivery subscription models show highest conversion rates.
- Millennials:Sustainability and packaging waste concerns influence brand switching behavior.
- Families:Multi-pack value pricing and child-friendly flavors drive volume in conventional grocery.
Health-conscious consumers represent the largest addressable base; fitness enthusiasts are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA identity standards under 21 CFR 131.200 anchor production quality across the United States, while state-level dairy pricing orders in California and Wisconsin reshape raw milk cost structures. Demand concentrates in coastal metropolitan corridors where direct-to-home delivery channels capture subscription loyalty.
California
Health-conscious consumers in Los Angeles and San Francisco metropolitan areas drive protein-enriched Greek yogurt purchases through specialty retail and fitness-adjacent channels. The California Department of Food and Agriculture administers state dairy pricing orders that elevate raw milk costs relative to federal order regions. Chobani LLC leverages its Idaho-based manufacturing footprint to serve California markets without coastal premium logistics.
New York
Urban professionals in New York City sustain demand for drinkable yogurt formats through commuter-oriented convenience retail and gym partnerships. New York State Department of Agriculture and Markets enforces dairy plant inspection protocols that exceed federal minimums for live culture viability documentation. Metro-area direct-to-home subscription services displace conventional grocery stock-up trips for core yogurt purchases.
Idaho
Chobani LLC's Twin Falls manufacturing complex anchors national distribution density for strained yogurt varieties. Idaho State Department of Agriculture dairy inspection programs align with FDA enforcement priorities on live-and-active culture substantiation. The Magic Valley dairy cluster supplies fluid milk inputs at pricing advantages under federal milk marketing orders.
Wisconsin
Dairy processing technician shortages unwind capacity expansion plans for regional cooperatives despite abundant raw milk supply. Wisconsin Department of Agriculture, Trade and Consumer Protection oversees dairy plant licensing that intersects with USDA organic certification requirements for ingredient traceability. The Fox Valley and Madison metropolitan areas concentrate yogurt manufacturing equipment and technical talent.
Texas
Expanding Hispanic consumer demographics drive demand for drinkable and dessert-style yogurt formats through conventional grocery and convenience channels. Texas Department of State Health Services dairy safety regulations incorporate FDA labeling requirements for added sugars disclosure. Dallas-Fort Worth and Houston metropolitan areas attract distribution center investments serving southwestern retail networks.
United States Yogurt Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States yogurt market. Large diversified food corporations dominate conventional grocery shelf positioning through entrenched retail relationships and promotional slotting fees. Three archetypes define competitive structure: national brand manufacturers with multi-format production lines, specialty strained yogurt specialists with premium positioning, and organic-certified regional processors with clean-label claims. Capacity expansion and portfolio diversification constitute the dominant competitive moves as processors retool lines for pouch and bottle formats.
Within the national brand tier, General Mills and Danone occupy positions defined by retail channel density and bacterial culture expertise. Chobani LLC exemplifies the specialty strained yogurt archetype through its Idaho-based manufacturing scale. Yoplait USA anchors conventional grocery penetration for General Mills. These three companies collectively represent the competitive tension between premium protein positioning and mass-market volume capture.
| Leading Market Players |
|---|
| Chobani LLC |
| Danone |
| General Mills |
| Yoplait USA |
| FAGE International |
| The Dannon Company |
| Arla Foods amba |
| Lactalis |
| Stonyfield Farm |
| Others |
Value Network & Pricing Analysis
Plastic-to-pouch packaging substitution across child-oriented and fitness-oriented segments is simultaneously redrawing manufacturing geography toward flexible-film capable facilities and compressing per-unit packaging economics for legacy cup-dependent processors. This shift concentrates investment in California and New York metropolitan corridors where direct-to-home delivery channels absorb the logistics premium of lighter-weight formats.
Pricing Analysis
California and New York command 15-20% retail price premiums over Upper Midwest markets due to state-level dairy pricing order differentials and cold-chain distribution intensity. Pricing stratifies across premium Greek strained varieties, standard conventional formulations, and economy private-label tiers, with protein-per-serving specifications and live culture certification as primary differentiation drivers. Cost compression in standard-tier products is intensifying as FDA added-sugar labeling mandates force reformulation investment. Families purchasing multi-packs in conventional grocery show highest price sensitivity, while fitness enthusiasts subscribing to auto-delivery platforms demonstrate lowest elasticity.
Supply Chain Analysis
Idaho, California, and Wisconsin anchor domestic yogurt manufacturing through distinct competitive advantages: Idaho's federal milk marketing order pricing, California's coastal demand proximity, and Wisconsin's technical talent concentration. Raw milk supply draws from Magic Valley dairy clusters, Central Valley cooperatives, and Fox Valley processing networks, with organic certification requirements elevating input cost volatility. Single-source vulnerability concentrates in Upper Midwest technician labor pools where dairy processing expertise scarcity threatens capacity utilization. Distribution runs through refrigerated direct-store-delivery networks serving conventional grocery, supplemented by cold-chain parcel services for subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where FDA 21 CFR 131.200 identity standards create regulatory entrenchment that elevates compliance costs for would-be challengers and protects incumbent live-and-active culture claims.
For Market Incumbents: Secure fermentation process control expertise through apprenticeship pipeline investments in Idaho and Wisconsin dairy technician programs, insulating against labor scarcity that threatens capacity expansion timelines. Deepen backward integration into Magic Valley and Central Valley raw milk supply through cooperative equity positions, defending margin position against organic input cost volatility and state pricing order arbitrage. For New Entrants and Emerging Players: Lead with drinkable yogurt white-space penetration in Texas metropolitan corridors and gym-adjacent retail networks, where Hispanic demographic expansion and on-the-go consumption occasions remain underdeveloped relative to coastal markets. Target aseptic cold-fill processing partnerships with beverage-oriented dairy processors to bypass capital-intensive multi-format line investments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional organic processors possessing USDA certification and clean-label positioning but lacking national distribution density. Long-term viability hinges on subscription channel conversion rates and live culture litigation defense capabilities. The signal to watch is FDA enforcement priority shifts around probiotic substantiation documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Line Investment | Enables extended refrigerated distribution for drinkable formats without preservative additives. |
| Direct-to-Home Channel Expansion | Captures subscription loyalty in California and New York metropolitan corridors. |
| Live Culture Litigation Defense Program | Proactive batch-level documentation protects against consumer class action exposure. |
| Multi-Format Equipment Retooling | Pouch and bottle capability addresses child-oriented and fitness-oriented purchase occasions. |
| Organic Certification Investment | USDA compliance supports premium positioning despite elevated input cost structures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing technicians, plant operations managers at regional cooperatives, category buyers at conventional grocery banners, and subscription service logistics directors. Secondary validation incorporated FDA 21 CFR 131.200 regulatory filings, USDA organic certification databases, California Department of Food and Agriculture pricing order records, and Nielsen retail audit data. Bottom-up volume triangulation across format, packaging, and channel segments was cross-checked against top-down value estimates derived from processor revenue disclosures.
Across the analysis window, the forecasting framework modeled product type segmentation including Greek, drinkable, low-fat, and organic varieties; packaging configurations spanning cups, pouches, glass, and tubs; and distribution channels covering supermarkets, online retail, convenience stores, and specialty outlets. CAGRs were derived from trend extrapolation of protein-enriched format adoption rates, reformulation timeline impacts from FDA labeling mandates, and direct-to-home channel penetration curves. Industry-specific inputs included dairy technician labor market tightness indices and state-level milk pricing order differentials.
The analysis sits within stated boundaries; outcomes outside sustained live-and-active culture claim viability, stable federal milk marketing order structures, or continued urban coastal demand concentration would require recalibration. Forecasts reflect documented assumptions regarding fermentation technology stability and cold-chain infrastructure investment continuity. Recalibration cycles align with material shifts in FDA enforcement priorities, state dairy pricing order reforms, or breakthrough alternative protein fortification methods.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Goat Milk Products Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Butter Concentrate Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
Cheese Concentrate Market
Dairy Products
Plain Yogurt Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Lactose and Derivative Market
Dairy Products
India Dairy Market
Dairy Products
Low Temperature Yogurt Market